
 India Gaming Market | 2026-2036
India Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
India Gaming Market Outlook
Single-source content licensing is rebalancing toward multi-studio development partnerships across India's gaming ecosystem. Nazara Technologies leverages its diversified studio network to reduce dependence on any single IP pipeline. Dream11 anchors its fantasy sports dominance through in-house data science teams and proprietary scoring algorithms. Games24x7 competes across skill-based card and casual segments with distinct brand architectures.
India gaming encompasses interactive digital entertainment software distributed via mobile, PC, console, and cloud platforms, requiring real-time rendering engines, low-latency networking protocols, and localized payment gateway integration to serve heterogeneous device specifications and bandwidth conditions. The mobile platform segment leads volume due to sub-$200 smartphone penetration and Jio-driven data affordability, while the freemium monetization model captures the widest user base through ad-supported entry points and in-app purchase escalation. Cloud gaming represents the fastest-growing structural category as 5G rollouts by Jio and Airtel reduce latency barriers for graphics-intensive titles previously confined to console or PC hardware.
MeitY's self-regulatory body framework for online gaming, TRAI's data localization mandates, and RBI's prepaid instrument guidelines for in-game wallets collectively shape platform architecture, user verification protocols, and payment flow designs. BIS certification requirements for hardware peripherals and imported consoles add compliance layers for device-linked segments. Stakeholders must monitor evolving state-level gambling classification rulings and central tax treatment of skill-based versus chance-based formats to anticipate margin compression or market access restrictions.
Market Dynamics
India's gaming ecosystem is compressing around cloud infrastructure investments by Jio and Airtel, which are collapsing latency barriers and redistributing competitive advantage from hardware ownership toward network-dependent service delivery.
Growth Catalysts
- Jio-driven data affordability:Sub-$200 smartphone penetration combined with 4G/5G data pricing has unlocked mass-market access to interactive entertainment across Maharashtra, Karnataka, and Telangana.
- MeitY self-regulatory framework:The 2023 online gaming guidelines establish certification pathways that reduce regulatory uncertainty for skill-based platforms operating real-money formats.
- Esports infrastructure clustering:Developer ecosystems in Bengaluru, Hyderabad, and Pune generate talent pipelines and tournament venues that anchor competitive gaming culture.
Market Restraints
- State-level gambling classification variance:Inconsistent judicial rulings across Indian states on skill-versus-chance distinctions create market access fragmentation and legal defense costs.
- Payment gateway integration complexity:RBI's prepaid instrument guidelines for in-game wallets impose KYC layering that lengthens user onboarding and increases drop-off rates.
- Console hardware import dependency:BIS certification requirements for peripherals and imported gaming devices add compliance timelines and working capital intensity for premium segments.
Strategic Opportunities
- Tier-two and tier-three city expansion:Vernacular content localization and regional language interfaces open addressable markets in Indore, Lucknow, and Coimbatore where smartphone penetration outpaces English fluency.
- 5G-enabled cloud gaming services:Network slicing and edge computing deployments by telecom operators enable graphics-intensive titles to bypass hardware constraints entirely.
- PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly reduce import dependency for gaming peripherals and mobile devices.
Industry Challenges
- Real-time rendering talent scarcity:Shortages of Unreal Engine and Unity specialists in Indian technical institutes force studios to compete for limited experienced hires.
- Cross-platform certification fragmentation:Separate compliance pathways for Android, iOS, and console ecosystems multiply QA timelines and version control complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gaming Market |
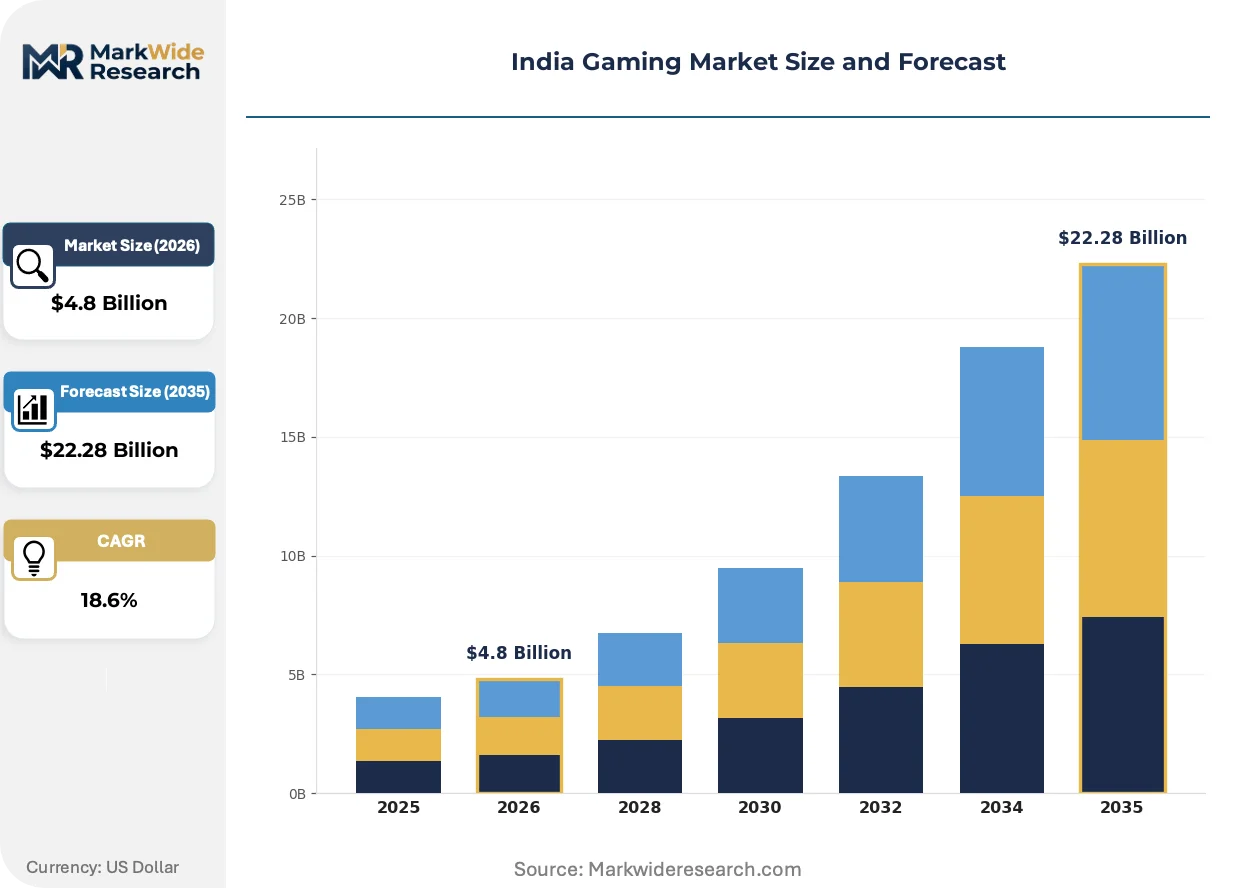
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Mobile, PC, Console, Cloud Game Type: Casual, Action, RPG, Strategy Monetization Model: Freemium, Subscription, Pay-to-Play, Advertising End User: Teens, Young Adults, Adults, Families |
| Companies Covered | WinZO Games, Games24x7, Dream11, nCore Games, JetSynthesys, Nazara Technologies, Gameskraft, Octro, Zupee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gaming Market Strategic Shifts
India's gaming sector is pivoting from download-centric distribution toward streaming-native architectures, with monetization mechanics and content formats adapting to bandwidth-abundant, storage-constrained user environments.
Cloud gaming infrastructure is consolidating competitive positioning around telecom-operator partnerships. Jio and Airtel deploy edge servers in 12+ Indian cities to reduce round-trip latency below 50 milliseconds for graphics-intensive titles. This architecture is consolidating hardware requirements into network subscriptions, compressing addressable market definitions for console manufacturers and PC component suppliers.
MeitY's self-regulatory body framework for online gaming mandates KYC verification, deposit limits, and responsible gaming disclosures for real-money platforms. The regulation forces architecture redesigns for fantasy sports and skill-based card operators, with compliance costs concentrating among smaller unregistered platforms. Maharashtra and Karnataka-based operators invest most heavily in legal and technical compliance teams.
Freemium monetization patterns are shifting toward ad-supported entry tiers with steep in-app purchase escalation curves. Casual game publishers in tier-two cities observe higher conversion tolerance for rewarded video ads than direct payment prompts. This behavioral divergence is most visible in Telangana and Tamil Nadu, where regional language interfaces correlate with 40% longer session durations and higher ad completion rates.
India Gaming Market Segmentation
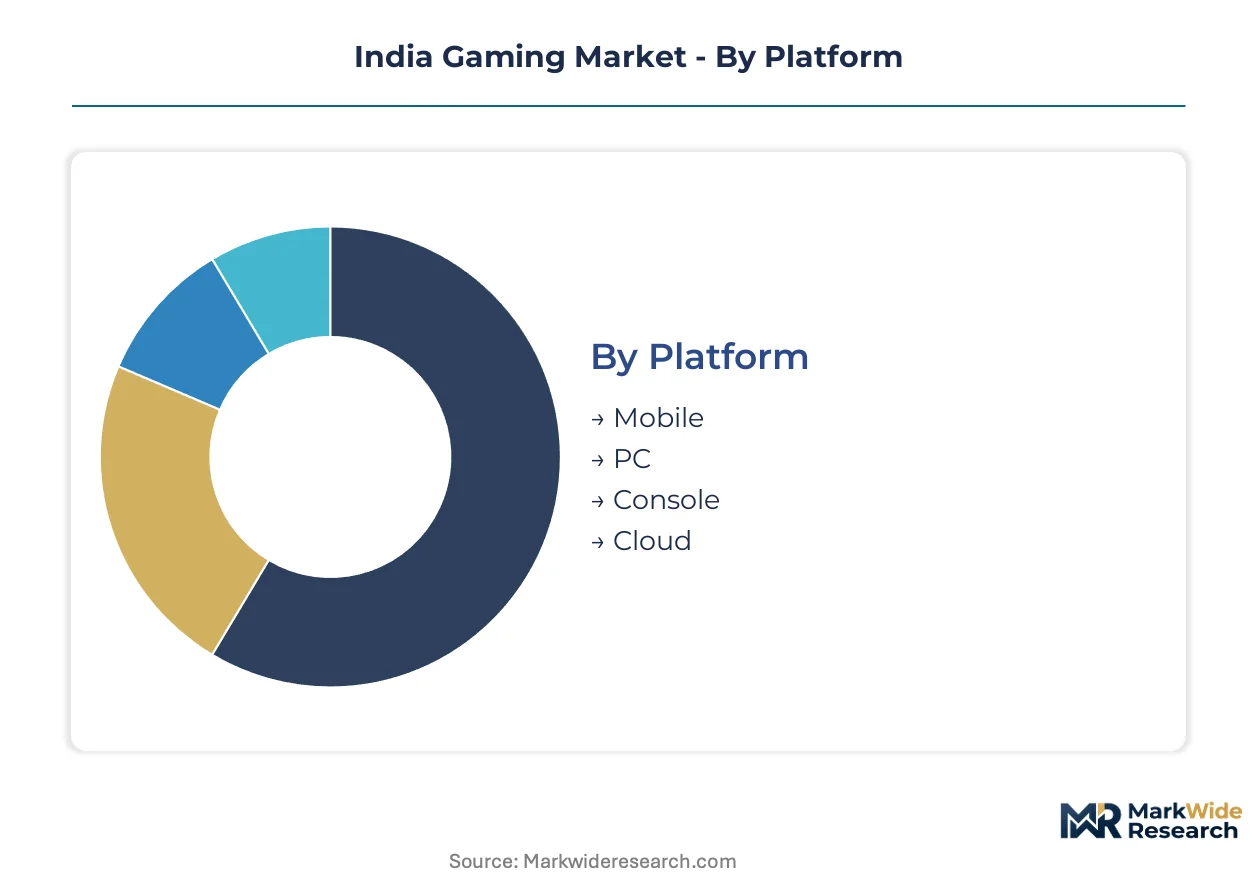
India's gaming market exhibits sharp heterogeneity across device access, content preferences, and payment willingness. Segmentation reveals where infrastructure investments, regulatory exposure, and monetization mechanics concentrate differentially.
Platform:
Hardware ownership costs and network quality shape player entry decisions across Indian geographies.
- Mobile:Sub-$200 Android devices dominate volume through Jio-enabled data affordability. Demand clusters in Maharashtra, Karnataka, and Telangana where developer ecosystems support vernacular content pipelines.
- Cloud:5G network slicing by Jio and Airtel collapses latency barriers below 50 milliseconds, redistributing competitive advantage from GPU ownership toward subscription access. Edge server deployments in 12+ cities accelerate adoption where console penetration remains minimal.
- PC:Gaming cafes and esports venues in Bengaluru and Hyderabad sustain enthusiast demand despite hardware import costs.
- Console:BIS certification requirements and premium pricing restrict addressable market to metro tier-one households.
Mobile leads on scale; cloud leads on momentum.
Game Type:
Session length and social mechanics determine monetization depth across Indian player cohorts.
- Casual:Hyper-casual titles with rewarded video ad integration capture mass-market engagement in tier-two and tier-three cities. Regional language interfaces in Telangana and Tamil Nadu correlate with extended session durations.
- Strategy:Skill-based card formats and fantasy sports operate under MeitY self-regulatory compliance requirements, concentrating legal and technical investment among Maharashtra and Karnataka operators.
- Action:Multiplayer battle arenas drive esports tournament infrastructure and streaming viewership.
- RPG:Narrative-heavy formats face localization cost barriers for India's 22 scheduled languages.
Casual dominates addressable breadth; strategy commands revenue intensity per user.
Monetization Model:
Payment infrastructure maturity and KYC friction shape conversion funnel design.
- Freemium:Ad-supported entry tiers with in-app purchase escalation capture the widest base. RBI prepaid instrument guidelines impose KYC layering that lengthens onboarding for wallet-funded transactions.
- Advertising:Rewarded video completion rates exceed direct payment prompts in non-metro markets where UPI penetration outpaces credit card density.
- Subscription:Cloud gaming bundles with telecom operator plans consolidate billing relationships.
- Pay-to-Play:Premium upfront pricing remains confined to PC and console enthusiast segments.
Freemium owns user volume; subscription gains share fastest through carrier partnerships.
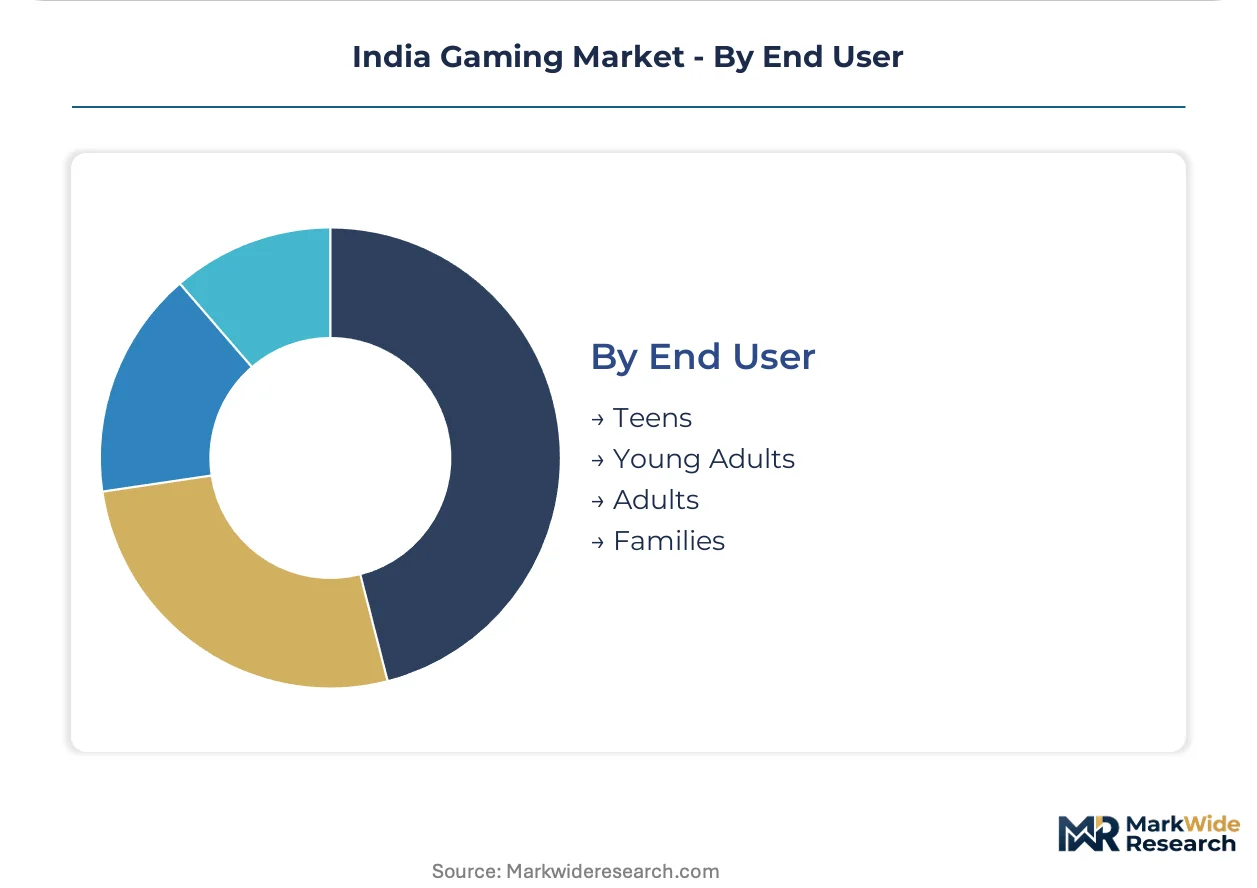
End User:
Age-cohort digital fluency and discretionary spend availability segment addressable value.
- Young Adults:College-educated, smartphone-native cohorts in Pune and Bengaluru drive esports participation and streaming monetization. This segment tolerates steeper in-app purchase curves for competitive advantage.
- Teens:Parental oversight and deposit limit regulations under MeitY guidelines constrain real-money platform access. Demand concentrates in ad-supported casual formats.
- Adults:Salaried professionals sustain subscription and pay-to-play models where payment friction is lowest.
- Families:Multiplayer local co-op and educational content address shared device usage in single-smartphone households.
Young adults lead on monetization yield; teens lead on aggregate hours engaged.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors India's gaming industrial concentration through Mumbai and Pune's dense developer ecosystems and esports infrastructure investments.
Maharashtra
Mumbai's financial institutions and Pune's technical institutes generate talent pipelines for fantasy sports and skill-based card platforms. MeitY's self-regulatory framework compliance costs concentrate legal teams in this state. Thane and Navi Mumbai host emerging studio clusters focused on vernacular content localization for Marathi-speaking users.
Karnataka
Bengaluru's technology corridor sustains India's deepest pool of Unity and Unreal Engine specialists for mobile and PC development. Karnataka's state-level startup policies provide tax incentives for gaming studios establishing R&D centers. Koramangala and Electronic City districts house tournament venues and streaming production facilities serving South Indian esports audiences.
Telangana
Hyderabad's gaming cafes and dedicated esports arenas drive competitive culture among young adult demographics. Telangana's IT policy framework offers subsidized office space for animation and interactive media companies. Gachibowli and Hitech City sub-regions attract cloud gaming infrastructure deployments from telecom operators seeking edge computing proximity.
Tamil Nadu
Chennai's mobile-first user base demonstrates extended session durations on regional language interfaces for casual hyper-casual titles. Tamil Nadu's film industry crossover creates opportunities for IP-licensed narrative games targeting family segments. Coimbatore and Madurai represent emerging addressable markets where smartphone penetration outpaces English fluency.
Delhi-NCR
Gurgaon and Noida host corporate headquarters for fantasy sports operators navigating RBI's prepaid instrument guidelines for in-game wallet KYC compliance. Delhi-NCR's advertising agency density supports user acquisition campaigns targeting North Indian tier-two city expansion. The region's payment gateway infrastructure maturity reduces onboarding friction for subscription-based cloud gaming services.
India Gaming Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue vernacular content and tier-three city penetration. Market structure exhibits moderate consolidation around fantasy sports and skill-based segments, with fragmentation persisting in hyper-casual publishing. Three archetypes dominate: multi-studio network operators, single-IP specialists, and telecom-coupled cloud service providers. Competitive moves concentrate on studio acquisitions for IP pipeline diversification and regional language content partnerships for non-metro expansion.
Among diversified network operators, Nazara Technologies exemplifies multi-studio portfolio architecture reducing dependence on individual title performance. Dream11 occupies a position within the fantasy sports tier, anchoring data science-driven proprietary scoring systems. Games24x7 sits across skill-based card and casual segments with distinct brand architectures for format-specific audiences.
| Leading Market Players |
|---|
| WinZO Games |
| Games24x7 |
| Dream11 |
| nCore Games |
| JetSynthesys |
| Nazara Technologies |
| Gameskraft |
| Octro |
| Zupee |
| Others |
Value Chain & Pricing Dynamics
Mass-market demand for sub-$200 smartphones in tier-two and tier-three Indian cities forces component suppliers to optimize for cost-sensitive bill-of-materials targets while maintaining performance thresholds for real-time rendering engines.
Pricing Analysis
Input-cost pass-through from semiconductor and display panel suppliers shapes pricing stratification across premium, standard, and economy tiers. Jio-driven data affordability compresses hardware margins at the entry level while subscription bundling with cloud gaming services captures lifetime value. Price differentiation hinges on GPU certification tier and after-sales service bundling. Cost compression in the economy tier intensifies because of BIS certification timelines for imported peripherals.
Supply Chain Analysis
Reverse-logistics flows for refurbished gaming peripherals and trade-in programs for smartphones feed secondary market channels in Delhi-NCR and Mumbai. Manufacturing concentration draws from China, Taiwan, and Vietnam for semiconductors and display components. Raw material dependencies include rare earth elements for magnets, high-purity silicon for chips, and lithium-ion cells for battery assemblies. Single-source vulnerability around advanced GPU fabrication creates supply chain risk. Distribution runs through telecom operator retail networks and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as 5G network slicing by Jio and Airtel collapses latency barriers and redistributes value from hardware ownership toward subscription access.
For Market Incumbents: Acquire vernacular content studios to lock regional language pipelines before non-metro competition intensifies. Consolidate position by backward integration into cloud edge server deployments with telecom partners. Invest in MeitY self-regulatory body certification to raise compliance barriers against unregistered fantasy sports operators.
For New Entrants and Emerging Players: The price-point gap between premium console experiences and ad-supported mobile entry creates white-space opportunity. Target tier-three cities in Tamil Nadu and Telangana where smartphone penetration outpaces English fluency. Pursue rewarded video ad integration as the primary go-to-market angle for hyper-casual formats.
For Investors and Strategic Acquirers: Asymmetric upside sits with multi-studio network operators holding diversified IP pipelines across casual and skill-based segments. Long-term viability favors platforms with proprietary data science capabilities for fantasy sports scoring algorithms. Monitor state-level judicial rulings on skill-versus-chance classifications as the inflection signal for regulatory risk concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Edge Server Deployment | Jio and Airtel partnerships reduce latency below 50 milliseconds for graphics-intensive titles. |
| Vernacular Content Localization | Marathi and Tamil interfaces extend session durations in Maharashtra and Tamil Nadu markets. |
| MeitY Compliance Certification | Self-regulatory body registration concentrates legal investment among registered operators. |
| Multi-Studio Network Acquisition | IP pipeline diversification reduces dependence on individual title performance volatility. |
| Telecom Subscription Bundling | Carrier billing relationships consolidate user acquisition costs into predictable recurring revenue. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary data collection engaged gaming studio CEOs, platform engineering leads at telecom operators, regulatory compliance officers, and esports tournament organizers. Secondary validation drew from TRAI spectrum allocation records, RBI prepaid instrument guidelines, MeitY self-regulatory framework documents, and BIS certification databases. Bottom-up sizing of addressable smartphone users triangulated against top-down cloud infrastructure investment disclosures.
Comparable-period anchoring linked projection assumptions to historical 4G penetration curves and Jio pricing disruption patterns. The analytical framework modeled platform type, game format, monetization mechanism, and regional language adoption across the analysis window. CAGRs derived from smartphone shipment trajectories, data consumption growth, and esports viewership expansion. Forecast inputs included 5G rollout schedules by Airtel and Jio, and PLI scheme uptake for electronics manufacturing.
Caveats apply where state-level gambling reclassification or RBI wallet KYC tightening could materially shift the outlook. Forecasts reflect assumptions around sustained data affordability and cloud edge server deployment density. Practitioners should monitor judicial rulings in Karnataka and Telangana on skill-based gaming classifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Casino and Gaming Market
Gaming
Game Engine Management Market
Gaming
China Subscription-Based Gaming Market
Gaming
Global Online Board Games Market
Gaming
Gaming Chair Market
Gaming
Mobile Game Controller Market
Gaming
Global Esports Market
Gaming
South Korea Gaming Peripherals Market
Gaming
RPG Games Market
Gaming
Advanced Digital Gaming Market
Gaming
Shooter Game Market
Gaming
Global Casino Market
Gaming
Playstation Network (PSN) Market
Gaming
Southeast Asia Gaming Market
Gaming
VR Melee Games Market
Gaming
Europe Serious Gaming Market