
 Africa Gaming Market | 2026-2036
Africa Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Gaming Market Analysis
Digital distribution across Africa is fragmenting as mobile network operators, app stores, and direct-to-consumer platforms compete for game discovery and payment flow control. Carry1st (Pty) Ltd. leverages its localized payment integration to anchor distribution in markets with limited credit card penetration. Maliyo Games Ltd. specializes in culturally resonant IP that competes against imported content. Leti Arts Ltd. sustains premium graphic novel and game hybrid production from its Ghana base.
Africa gaming encompasses interactive software developed for consumer entertainment across devices with specifications optimized for variable connectivity, limited storage, and prepaid billing cycles. Titles typically compress below 100 MB for feature phones and low-end smartphones, with asynchronous multiplayer functionality compensating for intermittent data access. Mobile games dominate transaction volume given Android's platform supremacy across the continent, while in-app purchases represent the fastest-expanding monetization model as telco-bundled billing matures. Browser games retain residual share in markets where device turnover lags, though margin pools concentrate where developers control both distribution and localized payment rails.
Nigeria's National Information Technology Development Agency, South Africa's Film and Publication Board, and Kenya's Communications Authority collectively shape content classification, data sovereignty, and youth protection standards that determine market access. Compliance with age-rating and data localization requirements directly influences which titles receive carrier billing integration and promotional placement. Stakeholders must monitor divergent national classification timelines and payment system interoperability as regulatory fragmentation becomes a structural cost of multi-territory expansion.
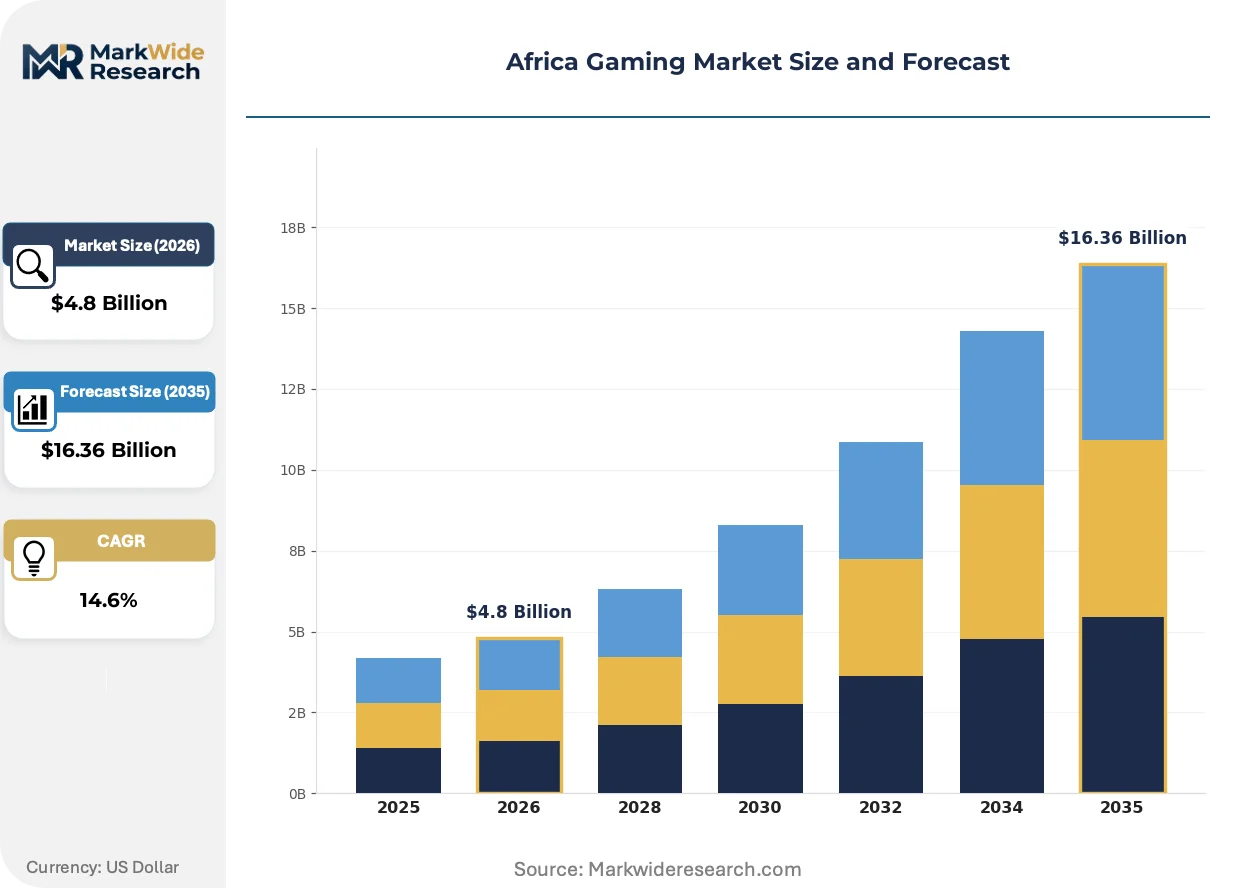
Market Dynamics
Mobile-first monetization is compressing development cycles across Africa's gaming ecosystem, forcing studios to prioritize sub-100 MB titles with telco-integrated billing over premium downloadable content.
Growth Catalysts
- Carrier billing maturation:Telco-bundled payment rails in Nigeria and Kenya bypass credit card penetration gaps, unlocking transaction volume among prepaid mobile subscribers.
- Cloud gaming infrastructure:Low-bandwidth streaming protocols are expanding addressable device bases beyond high-end smartphones into feature phone and tablet segments.
- Urban youth concentration:Lagos, Johannesburg, and Nairobi host dense clusters of platform-engaged consumers driving viral distribution mechanics.
Market Restraints
- Data cost volatility:Intermittent network reliability and fluctuating mobile data pricing compress session lengths and synchronous multiplayer feasibility.
- Regulatory fragmentation:Divergent classification timelines between South Africa's Film and Publication Board and Nigeria's National Information Technology Development Agency inflate compliance overhead.
- Device storage constraints:Low-end Android hardware with sub-16 GB capacity limits title complexity and update frequency.
Strategic Opportunities
- Francophone West Africa:Underpenetrated markets in Côte d'Ivoire and Senegal offer first-mover positioning for localized French-language content.
- Graphic novel-game hybrids:Convergence of visual narrative and interactive mechanics creates premium monetization paths distinct from pure casual gaming.
- Esports infrastructure:Dedicated tournament platforms and venue networks remain nascent outside South Africa, presenting white space for organized competitive formats.
Industry Challenges
- Localization talent scarcity:Shortage of indigenous language writers and cultural consultants delays region-specific content pipelines.
- Multi-territory compliance:Kenya's Communications Authority youth protection standards require parallel certification tracks that extend go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Gaming Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Mobile Games, PC Games, Console Games, Browser Games Monetization Model: Free-to-Play, Subscription, Pay-to-Play, In-App Purchases End User Type: Casual Gamers, Hardcore Gamers, Professional Gamers, Social Gamers Platform: Android, iOS, Windows, Web |
| Companies Covered | Nyamakop, Leti Arts Ltd., Carry1st (Pty) Ltd., Celestial Games, Gamesole Ltd., Maliyo Games Ltd., Kagiso Interactive, Kuluya, Kucheza Gaming Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Gaming Market Emerging Trajectories
Interactive entertainment across Africa is pivoting from imported IP dominance toward culturally resonant production, with distribution control shifting from global app stores to localized payment-integrated platforms.
Hyper-casual game architecture is migrating from high-fidelity 3D rendering toward lightweight 2D mechanics optimized for variable connectivity. Nigerian and Kenyan studios are adopting this compression-first approach to maintain engagement during network fluctuations. The structural consequence is margin pool redistribution toward developers who control both distribution infrastructure and telco billing relationships rather than pure content creation.
South Africa's Film and Publication Board classification requirements are tightening age-rating enforcement for carrier-bundled titles. This regulatory pressure is redirecting developer resources toward compliant content formats and documented youth protection protocols. Studios targeting multi-territory expansion must now maintain parallel classification documentation to secure promotional placement and billing integration.
Prepaid billing cycles are reshaping how gamers access premium content across Lagos and Nairobi. Subscription fatigue is pushing demand toward micro-transaction and ad-supported models that align with weekly airtime top-up patterns. This behavioral shift is most visible in Nigeria, where telco-wallet integration now outpaces direct credit card transactions for in-app purchases.
Africa Gaming Market Segmentation
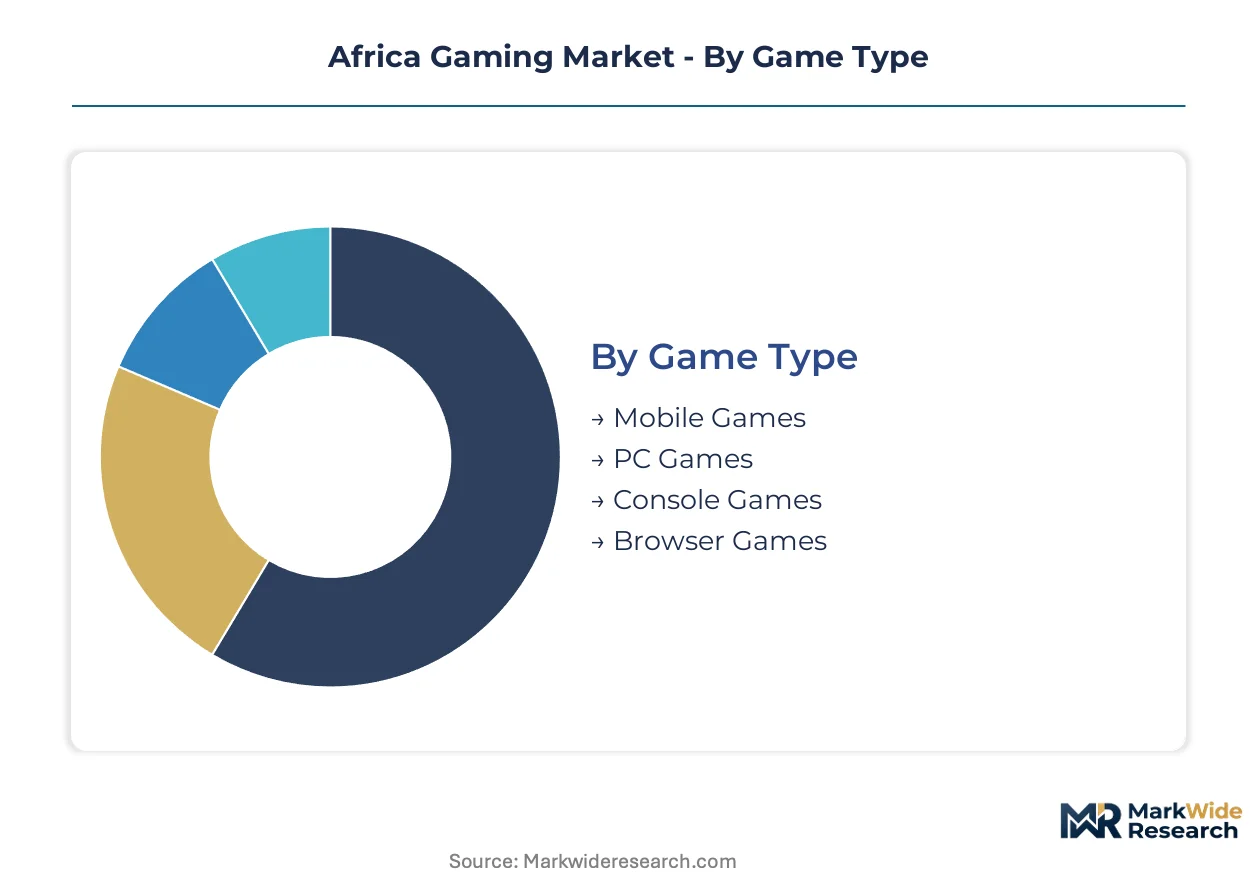
Segmentation across Africa's gaming market reveals how infrastructure constraints and payment behavior fragment commercial opportunity. Developers must align technical specifications and monetization architecture with distinct user profiles and platform dominance patterns.
Game Type:
Mature mobile formats coexist with emerging cloud-streamed alternatives as network investments reshape addressable hardware bases.
- Mobile Games:Compressed titles under 100 MB dominate transaction volume through Android's platform supremacy. Lagos and Nairobi drive platform engagement where prepaid billing cycles align with micro-transaction models.
- PC Games:Hardware cost barriers limit penetration to South African urban centers and Nigerian tech hubs. Cyber café infrastructure sustains access where personal device ownership lags.
- Console Games:Premium hardware pricing restricts adoption to Johannesburg's affluent segments. Import duties and currency volatility compress margin feasibility for physical distribution.
- Browser Games:Residual share persists in markets with slow device turnover and limited storage capacity. Lightweight 2D mechanics maintain engagement during network fluctuations.
Mobile games handle the majority of throughput; browser games are expanding most quickly as cloud infrastructure extends reach into feature phone segments.
Monetization Model:
Cost tier stratification separates mass-market accessibility from premium commitment requirements.
- Free-to-Play:Ad-supported and trial-based access captures prepaid subscriber bases across Nigeria and Kenya. Telco-wallet integration enables frictionless entry without credit card infrastructure.
- In-App Purchases:Micro-transaction architecture aligns with weekly airtime top-up patterns in urban African markets. Carrier billing maturation unlocks transaction volume among unbanked mobile subscribers.
- Subscription:Monthly commitment models face fatigue in price-sensitive segments with irregular income flows. South Africa demonstrates higher tolerance through established digital payment rails.
- Pay-to-Play:Upfront purchase requirements concentrate in premium PC and console segments with established distribution channels. Currency volatility and import costs erode margin predictability.
Free-to-play models command the largest user base; in-app purchases are gaining share fastest as billing integration matures.
End User Type:
Application intensity varies from intermittent engagement to structured competitive participation.
- Casual Gamers:Intermittent session patterns dominate Lagos and Nairobi commuter corridors. Hyper-casual 2D mechanics optimize for variable connectivity and limited attention spans.
- Hardcore Gamers:Sustained engagement demands drive premium device upgrades and data plan commitments. South African metropolitan clusters host the densest concentration of high-specification hardware.
- Professional Gamers:Tournament participation and streaming revenue remain nascent outside Johannesburg's organized competitive infrastructure. Sponsorship and prize pools lag global benchmarks.
- Social Gamers:Viral distribution mechanics leverage WhatsApp and Facebook integration for multiplayer coordination. Asynchronous functionality compensates for intermittent network reliability.
Casual gamers generate the highest transaction volume; professional gamers are climbing the fastest as esports infrastructure expands.
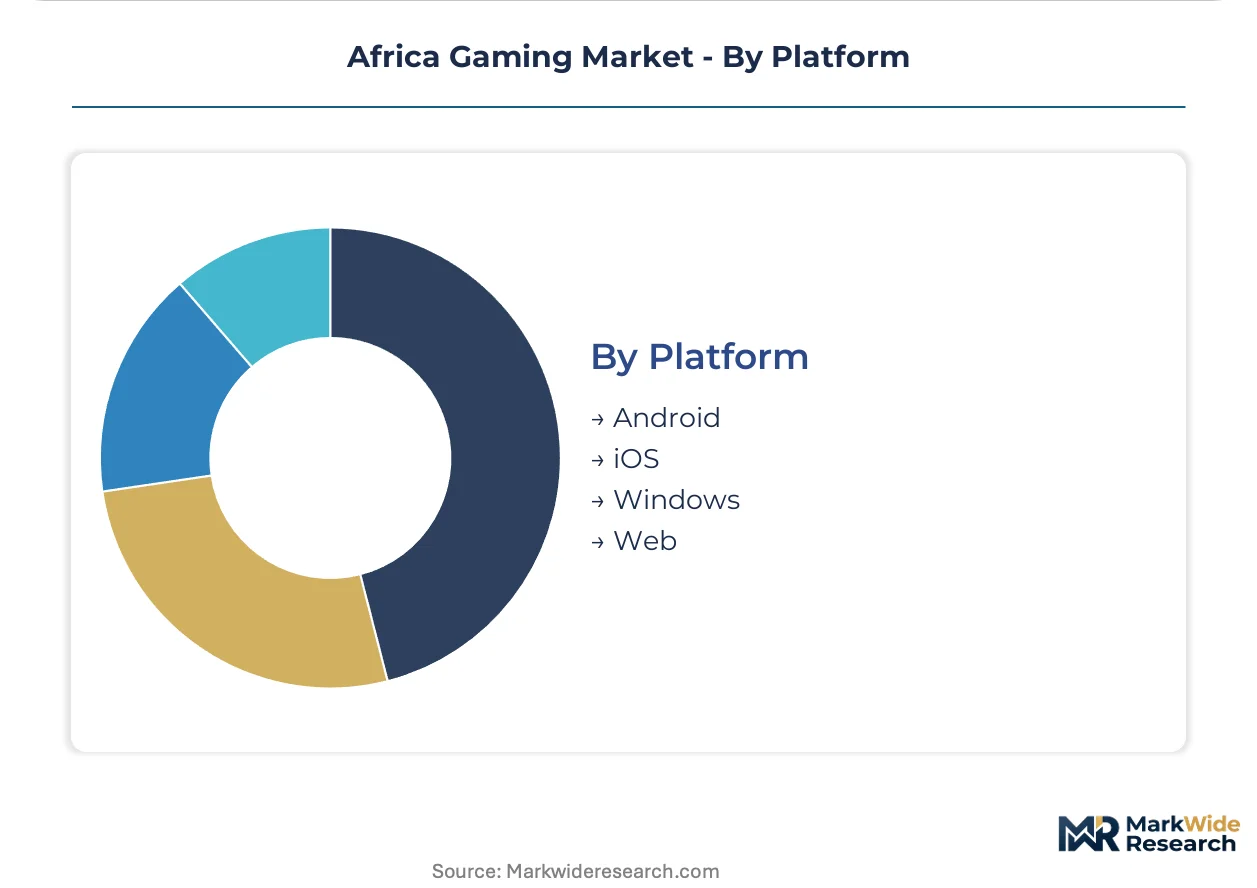
Platform:
Volume concentration reflects hardware affordability and distribution control patterns.
- Android:Open-source licensing and sub-$100 device availability anchor platform supremacy across the continent. Google's Play Store competes with localized distribution platforms for payment flow control.
- iOS:Premium hardware pricing restricts penetration to affluent urban segments in South Africa and Nigeria. Apple's closed ecosystem limits carrier billing integration flexibility.
- Windows:PC gaming concentrates in cyber café networks and institutional settings with licensed software access. Piracy and irregular update cycles complicate commercial sustainability.
- Web:Browser-based access retains relevance where app store friction and storage constraints block native installation. HTML5 optimization enables cross-device compatibility without download requirements.
Android dominates platform throughput; web platforms are gaining share fastest as cloud gaming protocols reduce hardware dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Main One subsea cable landing in Lagos anchors West Africa's data throughput capacity for interactive entertainment distribution. This infrastructure asset underwrites Nigeria's position as the continent's largest gaming addressable market by transaction volume.
Nigeria
Lagos commuter corridors and Kano youth clusters drive hyper-casual session density on sub-100 MB Android titles. The National Information Technology Development Agency enforces data localization and content classification protocols that determine carrier billing eligibility. Abuja's emerging developer studios concentrate on asynchronous multiplayer mechanics optimized for prepaid billing cycles.
South Africa
Johannesburg's affluent segments sustain premium console and PC hardware penetration unmatched elsewhere on the continent. The Film and Publication Board mandates age-rating documentation for all titles seeking telco-wallet integration, tightening youth protection enforcement. Cape Town's indie studio cluster specializes in compliant content formats that satisfy classification requirements for multi-territory export.
Kenya
Nairobi's urban youth density generates viral distribution mechanics through WhatsApp-integrated social gaming. The Communications Authority imposes parallel certification tracks for youth protection standards that extend go-to-market timelines. Mombasa's cyber café networks retain residual browser-game access where personal smartphone ownership lags.
Ghana
Accra's developer ecosystem anchors premium graphic novel-game hybrid production with Francophone West Africa export potential. The national data protection framework shapes content hosting requirements for localized distribution platforms. Kumasi's technical institutes supply animation talent that feeds into culturally resonant IP development pipelines.
Egypt
Cairo's metropolitan gaming cafés sustain hardcore engagement patterns on imported PC titles with localized Arabic interfaces. The national media regulator oversees content classification for mobile distribution through regional app store partnerships. Alexandria's university corridors incubate esports tournament infrastructure with sponsorship appeal to Gulf-based investors.
Africa Gaming Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The Africa gaming market structures around distribution control rather than pure content creation, with margin pools concentrating where developers own both localized payment rails and telco relationships. Three archetypes dominate: carrier-billing-integrated publishers, culturally resonant IP studios, and cloud-streaming infrastructure providers. Competitive moves center on strategic partnerships with mobile network operators and portfolio diversification into adjacent entertainment formats.
Within the distribution-integrated tier, Carry1st (Pty) Ltd. and Maliyo Games Ltd. exemplify divergent positioning strategies. Carry1st anchors South African operations with telco-wallet infrastructure that bypasses credit card penetration gaps. Maliyo Games occupies a position as Nigeria-based culturally resonant IP specialists competing against imported content. Leti Arts Ltd. sits within the premium hybrid production archetype from its Ghana base, sustaining graphic novel-game convergence formats distinct from pure casual gaming mechanics.
| Leading Market Players |
|---|
| Nyamakop |
| Leti Arts Ltd. |
| Carry1st (Pty) Ltd. |
| Celestial Games |
| Gamesole Ltd. |
| Maliyo Games Ltd. |
| Kagiso Interactive |
| Kuluya |
| Kucheza Gaming Ltd. |
| Others |
Supply Flow & Price Mechanics
Telco-bundled billing infrastructure fragmentation between Nigeria, Kenya, and South Africa compresses pricing tier spreads while forcing developers toward compliant, low-bandwidth content formats that reshape distribution network architecture. This regulatory chokepoint simultaneously elevates carrier-integrated publishers above pure content studios and constrains margin capture for titles lacking localized payment rails.
Pricing Analysis
Volume-discount tiering structures separate telco-integrated distribution platforms from direct-to-consumer app store channels. Premium-mid-economy pricing differentiation rests on carrier billing maturity, with Nigeria's prepaid subscriber bases commanding lower per-transaction rates than South Africa's credit-card-enabled segments. Cost compression in the economy tier intensifies because data cost volatility compresses session lengths and reduces ad-supported revenue per user. Casual gamers in Lagos and Nairobi exhibit highest price sensitivity, while Johannesburg's hardcore segments tolerate premium hardware and subscription commitments.
Supply Chain Analysis
Tariff exposure between content hosting jurisdictions and data localization requirements in Nigeria, South Africa, and Kenya elevates compliance overhead for multi-territory publishers. Raw material dependencies center on cloud infrastructure from European and Middle Eastern data centers, indigenous animation talent from Ghanaian technical institutes, and Arabic localization services from Egyptian university corridors. Single-source vulnerability concentrates in telco-wallet infrastructure controlled by dominant mobile network operators. Distribution runs through carrier-integrated platforms that bypass global app store payment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa gaming market sits in a cyclical recovery phase driven by prepaid billing cycle normalization following pandemic-era data subsidy withdrawal. Urban youth platform engagement in Lagos, Johannesburg, and Nairobi provides the demand foundation for this rebound trajectory.
For Market Incumbents: Insulate margin position by deepening backward integration into telco billing infrastructure and securing exclusive carrier partnerships in Nigeria and Kenya. Regulatory fragmentation between South Africa's Film and Publication Board and Nigeria's National Information Technology Development Agency threatens multi-territory expansion timelines; parallel classification documentation investment is the defensive priority.
For New Entrants and Emerging Players: Francophone West Africa's underpenetrated markets in Côte d'Ivoire and Senegal offer first-mover positioning with localized French-language content. Graphic novel-game hybrids and esports infrastructure remain white-space targets with premium monetization potential distinct from saturated hyper-casual segments. Direct-to-telco distribution partnerships bypass app store discovery friction.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors carrier-billing-integrated publishers with established telco relationships. Long-term viability over the next decade hinges on controlling both distribution rails and culturally resonant IP pipelines. Cloud gaming protocol maturation signals the inflection point where hardware-agnostic streaming displaces native app dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Telco Billing Integration | Carrier-wallet partnerships in Nigeria and Kenya unlock transaction volume among unbanked prepaid subscribers. |
| Localized Content Production | Culturally resonant IP from Ghanaian and Nigerian studios competes against imported titles for platform placement. |
| Cloud Gaming Infrastructure | Low-bandwidth streaming protocols extend addressable device bases into feature phone and tablet segments. |
| Multi-Territory Compliance Certification | Parallel classification documentation satisfies South Africa's Film and Publication Board and Kenya's Communications Authority requirements. |
| Esports Tournament Platform Development | Organized competitive infrastructure in Johannesburg and Cairo attracts Gulf-based sponsorship capital. |
Methodological Framework
Initial hypotheses were tested against primary input from game studio executives, mobile network operator product managers, telco billing integration specialists, and regulatory affairs leads across Nigeria, South Africa, Kenya, and Ghana, then refined against secondary validation from National Information Technology Development Agency filings, Film and Publication Board classification databases, Communications Authority certification records, and carrier billing volume disclosures. Bottom-up transaction modeling and top-down addressable market sizing were triangulated to constrain estimate variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning game type, monetization model, end user archetype, and platform ecosystem. CAGRs were derived from installed base growth curves, billing integration penetration rates, and urban youth demographic expansion patterns. Cloud infrastructure deployment timelines and data cost elasticity coefficients served as industry-specific forecast inputs.
Practitioners should monitor carrier billing regulatory revisions, data tariff volatility, and cloud gaming protocol adoption rates for early signals of trajectory deviation. Forecasts reflect assumptions about prepaid billing cycle stability and telco-wallet interoperability that could shift with sovereign data localization mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Simulation Video Game Market
Gaming
RPG Games Market
Gaming
Game Applications Market
Gaming
Gaming Hardware Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Online Casual Games Market
Gaming
Game API Market
Gaming
Australia Gaming Accessories Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Mobile Game Controller Market
Gaming
Online Casino Market
Gaming
VR Gaming Console Market
Gaming
Gaming Accessories Market
Gaming
Europe Video Game Software Market
Gaming
Mobile Shooter Market
Gaming
AAA Games Market