
 Online Strategy Games Market | 2026-2036
Online Strategy Games Market Size, Share, and Industry Trends Forecast 2026-2036
Online Strategy Games Market Analytics
Revenue-sharing partnerships between streaming platforms and developers is rewriting competitive economics in online strategy games. Tencent Holdings Ltd. leverages its super-app ecosystem to reduce user acquisition costs across mobile titles. Electronic Arts Inc. sustains franchise longevity through live-service content cadences in its strategy portfolio. Paradox Interactive AB specializes in niche grand strategy mechanics that command premium pricing from dedicated PC audiences.
Online strategy games constitute interactive entertainment software requiring real-time or turn-based tactical decision-making, typically incorporating resource management, unit command, and territorial control mechanics across networked environments. These titles serve commercial purposes spanning player engagement monetization, intellectual property extension, and platform ecosystem lock-in. Real-Time Strategy remains the dominant revenue format due to its esports broadcast compatibility and spectator-friendly pacing, while Mobile platforms exhibit the fastest expansion trajectory as 5G latency reductions enable competitive synchronous play. Free-to-Play monetization captures the largest player base volume, though In-Game Purchases generate disproportionate margin concentration from high-spending user cohorts.
The Federal Trade Commission scrutinizes loot-box mechanics and randomized reward structures under consumer protection frameworks, compelling disclosure modifications. China's National Press and Publication Administration enforces minor playtime restrictions that reshape daily active user patterns and session design requirements. South Korea's Game Rating and Administration Committee mandates probability disclosures for gacha-style monetization, establishing transparency benchmarks that propagate across regional markets. Stakeholders must monitor evolving classification standards that could reclassify certain mechanics as gambling-adjacent activities in additional jurisdictions.
Market Dynamics
Cloud gaming infrastructure is compressing hardware requirements for competitive participation while regulatory scrutiny of monetization mechanics intensifies across multiple jurisdictions simultaneously.
Growth Catalysts
- 5G Latency Reduction:Mobile network upgrades enable synchronous competitive play previously restricted to wired connections, expanding addressable audiences in Brazil and Southeast Asia.
- Esports Broadcasting Standards:Spectator-friendly pacing in Real-Time Strategy formats drives advertising inventory growth and platform licensing revenue from streaming services.
- Probability Disclosure Mandates:South Korea's Game Rating and Administration Committee transparency requirements reduce consumer friction and establish trust benchmarks that propagate to adjacent markets.
Market Restraints
- Server Infrastructure Concentration:Hyperscaler dependency for low-latency multiplayer hosting creates vendor lock-in risks and cost volatility for mid-sized publishers.
- Input Cost Volatility:Semiconductor shortages and GPU pricing fluctuations constrain cloud rendering capacity expansion and subscriber growth ceilings.
- Regulatory Classification Uncertainty:China's National Press and Publication Administration playtime restrictions for minors compress daily active user metrics and session design flexibility.
Strategic Opportunities
- Cross-Platform Progression Systems:Unified account ecosystems spanning mobile, PC, and console enable frictionless player migration and lifetime value extension across device categories.
- India's Broadband Expansion:Fiber-to-the-home rollout in tier-two cities creates first-mover advantages for publishers establishing localized server infrastructure and payment partnerships.
- AI-Generated Content Pipelines:Procedural map generation and dynamic balancing tools reduce live-service maintenance costs while accelerating content velocity for competitive metas.
Industry Challenges
- Live Operations Talent Scarcity:Data science and community management expertise for persistent game economies commands premium compensation and retention difficulty.
- Antitrust Compliance Complexity:App store fee disputes and platform exclusivity negotiations require specialized legal resources across FTC, EU Digital Markets Act, and SAMR jurisdictions.
- Legacy Code Integration:Decades-old engine architectures constrain real-time adaptation to emerging security threats and cross-play functionality demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Strategy Games Market |
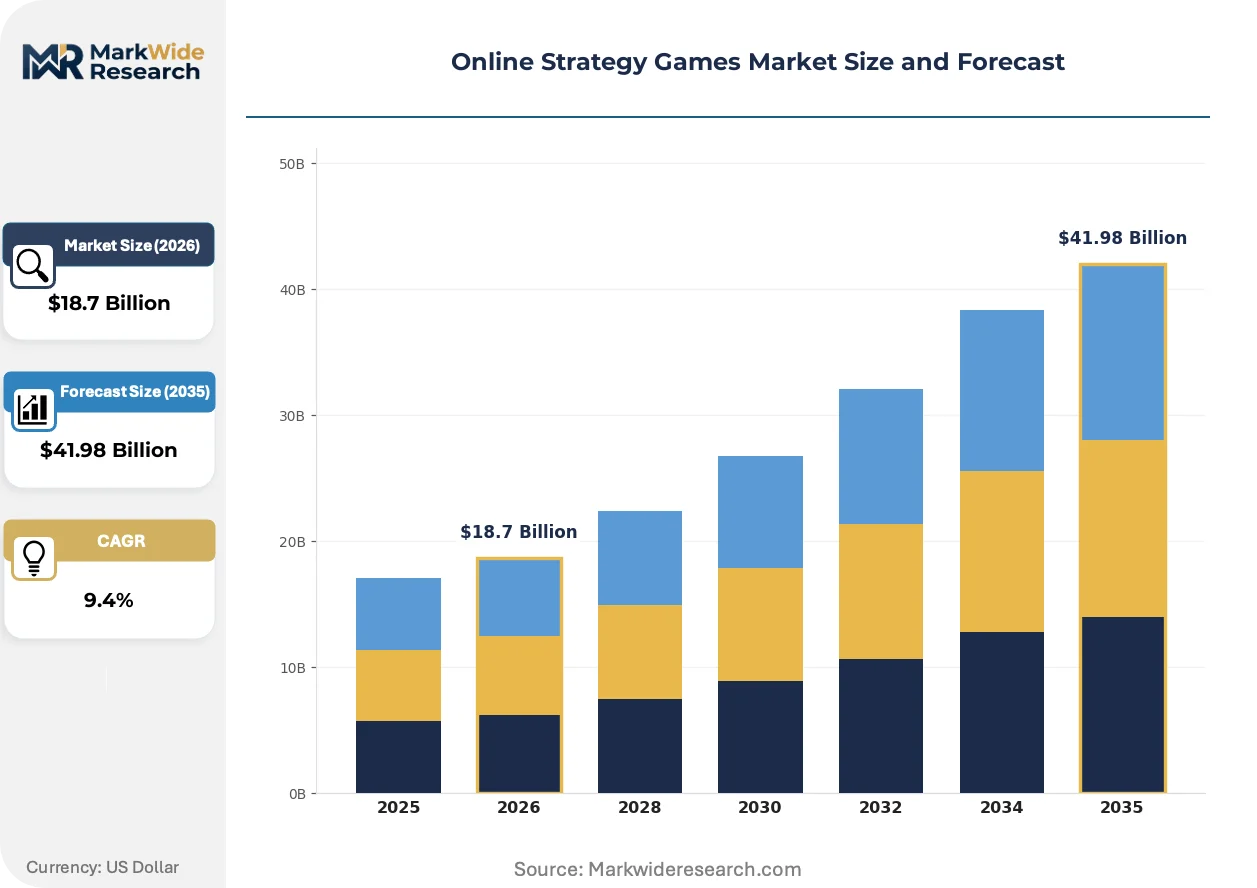
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Real-Time Strategy, Turn-Based Strategy, Tower Defense, Grand Strategy Platform: PC, Mobile, Console, Browser-Based Monetization Model: Free-to-Play, Premium, Subscription, In-Game Purchases Player Engagement: Single Player, Multiplayer, Cooperative, Competitive |
| Companies Covered | Electronic Arts Inc., Take-Two Interactive Software, Inc., Tencent Holdings Ltd., Riot Games, Paradox Interactive AB, NetEase Inc., Activision Blizzard, Inc., Supercell Oy, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Strategy Games Market Evolving Landscape
Monetization mechanics are converging with behavioral economics research while competitive integrity frameworks absorb machine learning detection systems for exploit prevention.
Edge computing architectures are migrating from centralized data center processing toward distributed node deployment. Mobile-first publishers in Indonesia and Philippines adopt mesh networking protocols to reduce last-mile latency for synchronous strategy titles. This compression of physical infrastructure distance between player and server is migrating from premium tier subscriptions toward standard accessibility packages.
The Federal Trade Commission's scrutiny of loot-box mechanics under consumer protection frameworks is compelling disclosure modifications and probability transparency. Developers must now architect reward systems assuming regulatory examination of randomized outcomes. Free-to-play titles targeting North American audiences face the steepest compliance adaptation requirements and are responding with deterministic progression alternatives.
Subscription bundling is consolidating individual title purchases into platform-native game passes that flatten revenue recognition curves. Microsoft's Game Pass and Sony's PlayStation Plus disrupt traditional unit-sales forecasting for strategy franchises. This displacement of direct purchase intent is most visible in Western European markets where digital storefront saturation has compressed discovery visibility for standalone releases.
Online Strategy Games Market Segmentation
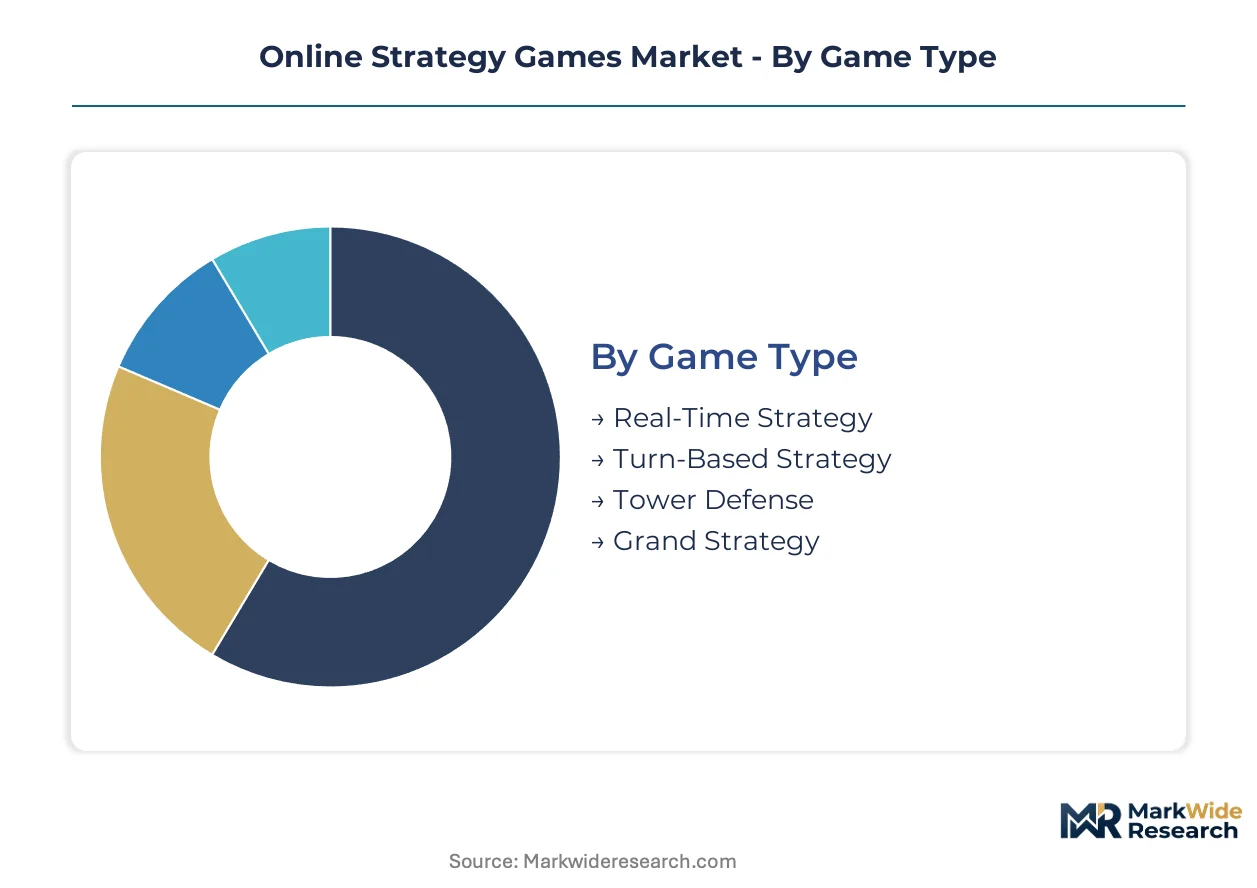
Segmentation in online strategy games determines monetization ceiling and live-service infrastructure requirements. Each dimension carries distinct after-sales-service intensity implications, from server maintenance loads to community moderation demands.
Game Type:
After-sales-service intensity varies sharply across game types, with persistent-world titles demanding continuous balancing patches and seasonal content pipelines.
- Real-Time Strategy:Synchronous tactical execution with unit micromanagement and resource allocation under time pressure. Demand concentrates in South Korea where professional gaming infrastructure sustains premium esports monetization through broadcast licensing and sponsored team ecosystems.
- Turn-Based Strategy:Asynchronous decision cycles emphasizing positional calculation and long-term planning over reflex speed. Western European markets drive adoption here, with Paradox Interactive's grand strategy adjacent titles demonstrating willingness to pay premium upfront prices for deep mechanical complexity.
- Tower Defense:Wave-based defensive positioning with upgrade progression systems. Mobile-first implementations dominate monetization through energy mechanics and cosmetic tower skins.
- Grand Strategy:Multi-domain empire management spanning diplomacy, warfare, and economic development across extended time horizons. PC-exclusive distribution maintains price integrity through Steam and direct storefront channels.
Real-Time Strategy holds the largest share; momentum sits with Turn-Based Strategy as mobile latency improvements enable competitive asynchronous play.
Platform:
Platform choice dictates input modality constraints and session length expectations that reshape core loop design.
- PC:Mouse and keyboard precision enables complex interface density and competitive ranked ladder integrity. South Korean PC bang culture sustains hourly venue fees that publishers capture through licensing arrangements.
- Mobile:Touchscreen gesture controls with simplified command inputs accommodate interrupted session patterns. Southeast Asian markets exhibit steepest expansion trajectory as 5G infrastructure penetrates Indonesia and Philippines tier-two cities.
- Console:Controller-optimized interfaces with aim-assist concessions for real-time tactics. Cross-platform parity demands constrain feature complexity to lowest-common-denominator specifications.
- Browser-Based:Instant accessibility without installation friction, historically dominant in emerging markets with storage-constrained devices. HTML5 WebGL rendering narrows visual fidelity gap with native applications.
PC commands revenue concentration among dedicated competitive players; mobile gains share fastest through emerging market broadband expansion.
Monetization Model:
Monetization architecture determines customer lifetime value curves and regulatory exposure profiles across jurisdictions.
- Free-to-Play:Zero entry barrier with revenue extraction through optional virtual goods and battle pass progression systems. China's National Press and Publication Administration minor playtime restrictions compress daily active user monetization windows.
- Premium:Upfront purchase with complete content access, sustaining price integrity through mechanical depth justification. Steam seasonal sales create predictable revenue recognition spikes.
- Subscription:Recurring access fees bundled across title libraries, flattening revenue curves. Microsoft's Game Pass integration disrupts standalone forecasting for strategy franchises.
- In-Game Purchases:À la carte virtual goods ranging from cosmetic skins to gameplay-adjacent convenience items. South Korea's Game Rating and Administration Committee probability disclosure mandates reshape gacha mechanic implementation.
Free-to-Play captures volume leadership; subscription models climb fastest as platform bundling consolidates purchasing decisions.
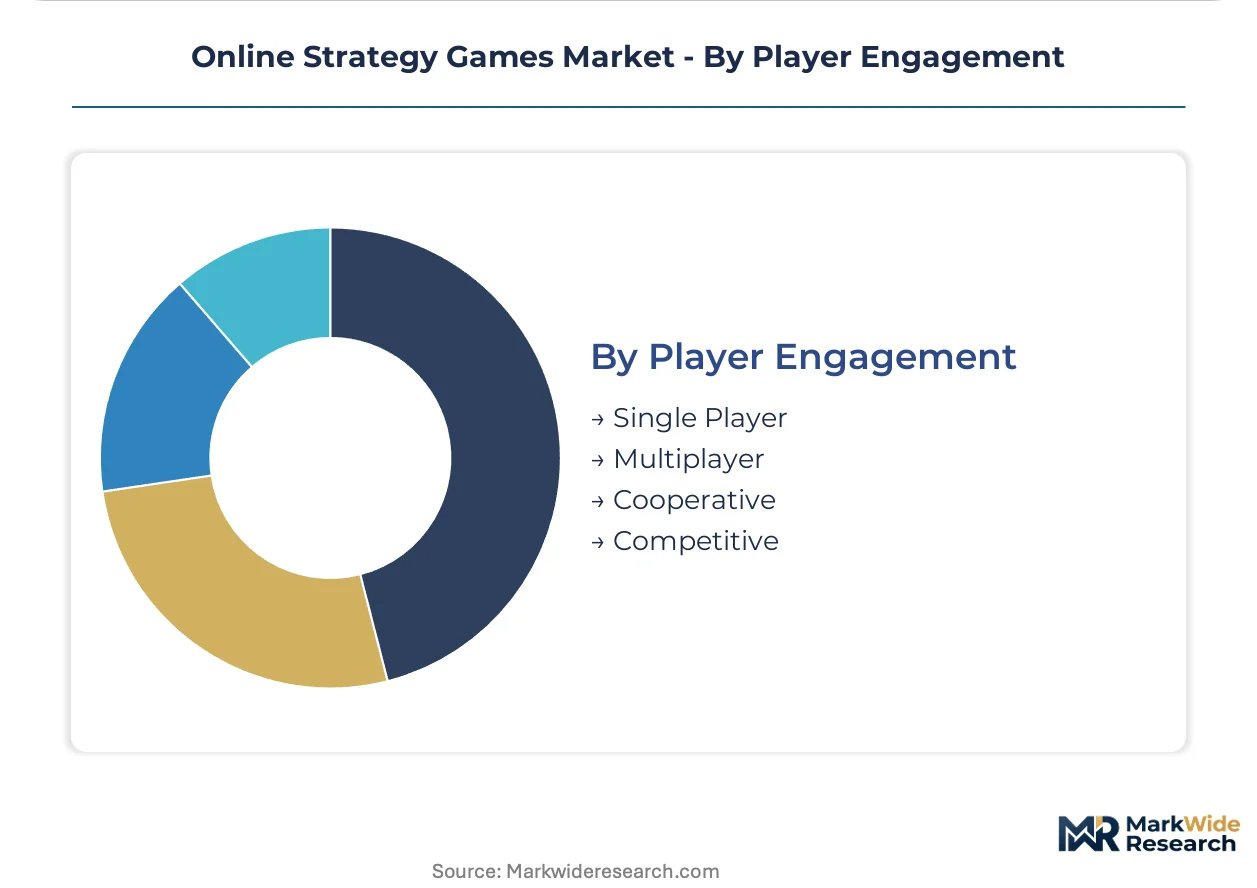
Player Engagement:
Engagement modality shapes server infrastructure topology and community management staffing ratios.
- Single Player:Narrative-driven campaigns with AI opponents and scenario challenges. Content completion curves predict churn timing for DLC release scheduling.
- Multiplayer:Matchmade competitive or cooperative sessions with stranger pairing. Latency-sensitive netcode requirements concentrate hosting spend in geographic proximity to player density.
- Cooperative:Team-versus-environment coordination against AI-controlled challenges. Session length flexibility accommodates varying group availability patterns.
- Competitive:Ranked ladder progression with skill-based matchmaking and seasonal resets. Esports broadcast compatibility demands spectator client development and anti-cheat infrastructure investment.
Competitive engagement generates highest revenue per user; cooperative modes expand most quickly as social retention mechanics prove sticky across demographic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government broadband subsidies and esports infrastructure investments are redistributing competitive participation across emerging and established gaming economies. South Korea's Game Rating and Administration Committee mandates probability disclosures that propagate transparency standards regionally. Publisher server deployment decisions now track fiber-to-the-home rollout schedules in secondary cities.
United States
FTC scrutiny of loot-box mechanics under consumer protection frameworks compels deterministic progression alternatives for North American releases. The Federal Trade Commission's disclosure requirements reshape reward system architecture before launch. Seattle and Los Angeles anchor development clusters where live-service operations talent commands premium compensation.
South Korea
Professional gaming infrastructure and PC bang venue licensing sustain premium monetization rates unmatched elsewhere. The Game Rating and Administration Committee's probability transparency mandates establish trust benchmarks that adjacent markets adopt. Seoul's esports stadium ecosystem generates broadcast licensing revenue through sponsored team franchises.
China
National Press and Publication Administration minor playtime restrictions compress daily active user windows and reshape session design. SAMR antitrust oversight constrains platform exclusivity negotiations and app store fee structures. Shenzhen and Hangzhou concentrate publisher headquarters where compliance adaptation consumes development resources.
Germany
GDPR data localization requirements increase hosting costs for persistent-world titles serving European audiences. The country's federal consumer protection frameworks examine randomized reward mechanics alongside EU-wide harmonization efforts. Berlin's indie development cluster produces premium-priced grand strategy adjacent titles for dedicated PC audiences.
Brazil
5G infrastructure penetration in São Paulo and Rio de Janeiro enables synchronous competitive play previously restricted to wired connections. National telecommunications regulator ANATEL spectrum auctions accelerate mobile network upgrades. Localized payment partnerships in Southeast Asian-style tier-two city expansions create first-mover positioning for publishers.
Online Strategy Games Market Competitive Landscape
Channel-controlling players compete with product-specialist players across platform ecosystems and monetization architectures. Market structure exhibits consolidation around super-app ecosystems and platform-native subscription bundling, with mid-sized publishers occupying niche mechanical specializations. Strategic archetypes include ecosystem-integrated conglomerates, live-service specialists, and premium-priced PC exclusivists. Dominant competitive moves encompass cross-platform progression system development and regulatory compliance infrastructure investment.
Among ecosystem-integrated conglomerates, Tencent Holdings Ltd. and Microsoft Corporation occupy positions defined by super-app distribution control and subscription bundling capacity respectively. Electronic Arts Inc. exemplifies the live-service specialist archetype through franchise longevity maintenance. Paradox Interactive AB sits within the premium-priced PC exclusivist tier, commanding dedicated audience willingness to pay upfront for mechanical depth. NetEase Inc. and Supercell Oy represent contrasting geographic anchors for mobile-first competitive strategy deployment.
| Leading Market Players |
|---|
| Electronic Arts Inc. |
| Take-Two Interactive Software, Inc. |
| Tencent Holdings Ltd. |
| Riot Games |
| Paradox Interactive AB |
| NetEase Inc. |
| Activision Blizzard, Inc. |
| Supercell Oy |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud rendering infrastructure across North American hyperscaler regions is compressing server hosting rates and forcing publishers toward multi-vendor sourcing strategies that fragment pricing power across the value chain.
Pricing Analysis
Monetization model sophistication creates the primary spread between premium live-service operators and transactional premium publishers. Free-to-play titles with battle pass systems command recurring revenue premiums over upfront purchase models, while South Korea's probability disclosure mandates add compliance cost layers that price out smaller entrants. Price erosion runs through mobile-first tiers as Southeast Asian publishers undercut Western counterparts on user acquisition costs. Indie developers exhibit highest price sensitivity, while ecosystem-integrated conglomerates absorb margin compression through cross-title subsidy mechanics.
Supply Chain Analysis
Extended payment terms from platform holders now stretch 90-120 days for independent publishers, forcing supply-chain finance facility reliance or equity dilution. Hyperscaler concentration in the United States, Ireland, and Singapore anchors cloud hosting capacity, while semiconductor fabrication for GPU acceleration draws from Taiwan and South Korea. Single-source vulnerability in Unity and Unreal engine licensing creates existential risk for mid-sized studios. Distribution runs through platform-native storefronts that extract 30% revenue shares before publisher recognition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from short-form video entertainment and social platform native games that capture fragmented attention spans previously reserved for synchronous strategy sessions.
For Market Incumbents: Pre-empt talent attrition by acquiring live-operations studios in Berlin and Stockholm where data science expertise concentrates. Defensive consolidation around cross-platform progression technology will neutralize emerging cloud-native entrants. Vertical integration into proprietary anti-cheat infrastructure reduces dependency on third-party vendors facing regulatory scrutiny.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two cities where fiber-to-the-home rollout outpaces localized server deployment by incumbents. White-space opportunity sits with asynchronous turn-based strategy for mobile, where session interruption tolerance matches commuter behavior patterns. Go-to-market through telecom bundle partnerships bypasses saturated app store discovery channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among live-service specialists with established seasonal content pipelines. Long-term viability favors publishers with proprietary engine technology and direct storefront relationships. Acquisition targets should demonstrate compliance infrastructure investment ahead of probability disclosure mandate expansion. Watch for antitrust enforcement against platform fee structures as inflection signal for margin expansion opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform Progression System Deployment | Unified account ecosystems reduce churn across mobile, PC, and console transitions for Tencent and Microsoft. |
| AI-Generated Content Pipeline Investment | Procedural map generation tools lower live-service maintenance costs for Electronic Arts and Paradox Interactive. |
| Regulatory Compliance Infrastructure Buildout | Probability disclosure systems satisfy South Korea's Game Rating and Administration Committee mandates ahead of regional propagation. |
| Localized Server Infrastructure Expansion | Edge node deployment in São Paulo and Jakarta reduces latency for competitive synchronous play in Brazil and Indonesia. |
| Esports Broadcast Capability Development | Spectator client investment unlocks advertising inventory growth through streaming platform licensing arrangements. |
Research Methodology
The analysis maps real-time strategy, turn-based strategy, tower defense, and grand strategy sub-sectors, each validated through game development executives, live-service operations directors, platform partnership managers, and esports broadcast licensing specialists. Primary interview findings triangulate against secondary sources including SEC filings, App Annie mobile revenue estimates, hyperscaler capital expenditure disclosures, and regional telecommunications regulator spectrum auction records. Bottom-up title-level revenue modeling and top-down platform ecosystem sizing converge through iterative reconciliation.
Forecast assumptions hold fixed current regulatory classification frameworks for loot-box mechanics while varying 5G penetration curves and cloud gaming subscriber conversion rates across the projection horizon. Segmentation dimensions span game type, platform, monetization model, and player engagement modality. CAGRs derive from installed base growth, average revenue per user trajectory, and content velocity assumptions. Industry-specific inputs include server hosting cost deflation curves and esports prize pool growth as proxy for competitive ecosystem health.
Sensitivities concentrate around regulatory reclassification of gacha mechanics as gambling-adjacent activities and hyperscaler pricing power shifts. Forecasts reflect documented assumptions without claiming predictive certainty. Macroeconomic contraction in emerging market broadband investment, antitrust enforcement against platform fee structures, or breakthroughs in edge computing latency reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Simulator Market
Gaming
Board Games Market
Gaming
Latin America Mobile Gaming Market
Gaming
Global Online Adventure Games Market
Gaming
China Gaming Headsets Market
Gaming
SLG Game Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Global Gaming Market
Gaming
Gaming Hardware Market
Gaming
Global Battle Royale Games Market
Gaming
Europe Serious Gaming Market
Gaming
Game Engine Management Market
Gaming
Racing Games Market
Gaming
Puzzle Video Game Market
Gaming
United States Gaming Accessories Market