
 Global Online Adventure Games Market | 2026-2036
Global Online Adventure Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Adventure Games Market Foresight
Asset-light publishing models and revenue-sharing partnerships with streaming platforms is tilting competitive dynamics toward studios that minimize upfront capital exposure. Epic Games leverages its Unreal Engine ecosystem to reduce production costs for affiliated developers. Nintendo sustains premium pricing power through proprietary hardware-software integration. Electronic Arts competes via live-service monetization architectures that extend title lifecycles beyond traditional retail windows.
Online adventure games constitute interactive narrative software delivered through networked infrastructure, combining branching story design with real-time player agency and persistent world states rendered at 60 frames per second minimum. These products serve commercial entertainment markets while functioning as engagement platforms for subscription retention and in-game economies. Role-playing and sandbox formats anchor the largest revenue pools due to recurring content monetization and user-generated expansion. Cloud gaming and cross-platform technology segments are expanding fastest as infrastructure latency drops below 20 milliseconds in major metropolitan clusters.
The EU Digital Services Act, China's MIIT content approval framework, and the US FTC's evolving stance on in-game purchase disclosures collectively elevate compliance costs for market access. GDPR-derived age-verification mandates in Europe and China's real-name registration requirements reshape onboarding flows and data architecture decisions. Stakeholders must monitor regulatory divergence between data-localization regimes and assess which compliance investments transfer across jurisdictions versus fragment operational capabilities.
Market Dynamics
Cloud gaming infrastructure is collapsing latency barriers between server farms and end-user devices, redistributing computational loads away from localized hardware and enabling subscription-based access models that bypass traditional retail distribution entirely.
Growth Catalysts
- MIIT Cloud Gaming Standards:China's framework for edge node deployment and bandwidth allocation accelerates platform licensing and reduces technical barriers for domestic publishers seeking nationwide distribution.
- Mobile-First Casual Gamers:Smartphone penetration in Southeast Asian markets creates addressable audiences that prioritize narrative accessibility over hardware investment, expanding total addressable market beyond console-dependent demographics.
- Cross-Platform Synchronization:Persistent save-state technology enables seamless session continuation across devices, increasing daily active user retention and reducing churn-driven acquisition costs for live-service titles.
Market Restraints
- Data Localization Mandates:China's cybersecurity law and Russia's sovereign internet requirements force redundant server infrastructure investments that fragment operational scale and inflate fixed costs.
- Graphics Processing Unit Supply Concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node fabrication for cloud rendering hardware, creating input cost volatility and capacity allocation risk.
- Real-Name Registration Requirements:China's MIIT verification protocols and South Korea's shutdown law impose friction-heavy onboarding flows that depress conversion rates in youth-skewing demographics.
Strategic Opportunities
- Indonesia and Vietnam:Underpenetrated Southeast Asian markets with expanding 5G coverage and rising disposable entertainment expenditure offer first-mover positioning before platform saturation.
- EU Digital Services Act:Transparency mandates for recommendation algorithms create competitive openings for studios that build direct-to-consumer distribution bypassing opaque platform curation.
- Artificial Intelligence and Procedural Generation:Converging technologies enable dynamic narrative branching and automated asset creation, compressing production timelines for mid-budget titles.
Industry Challenges
- Live-Service Engineering Talent:Scarcity of backend infrastructure specialists capable of maintaining persistent world states at 60 frames per second minimum drives compensation inflation and team instability.
- GDPR Age-Verification Architecture:European consent management platforms require costly integration with fragmented national identity systems, delaying launch windows and complicating user experience design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Adventure Games Market |
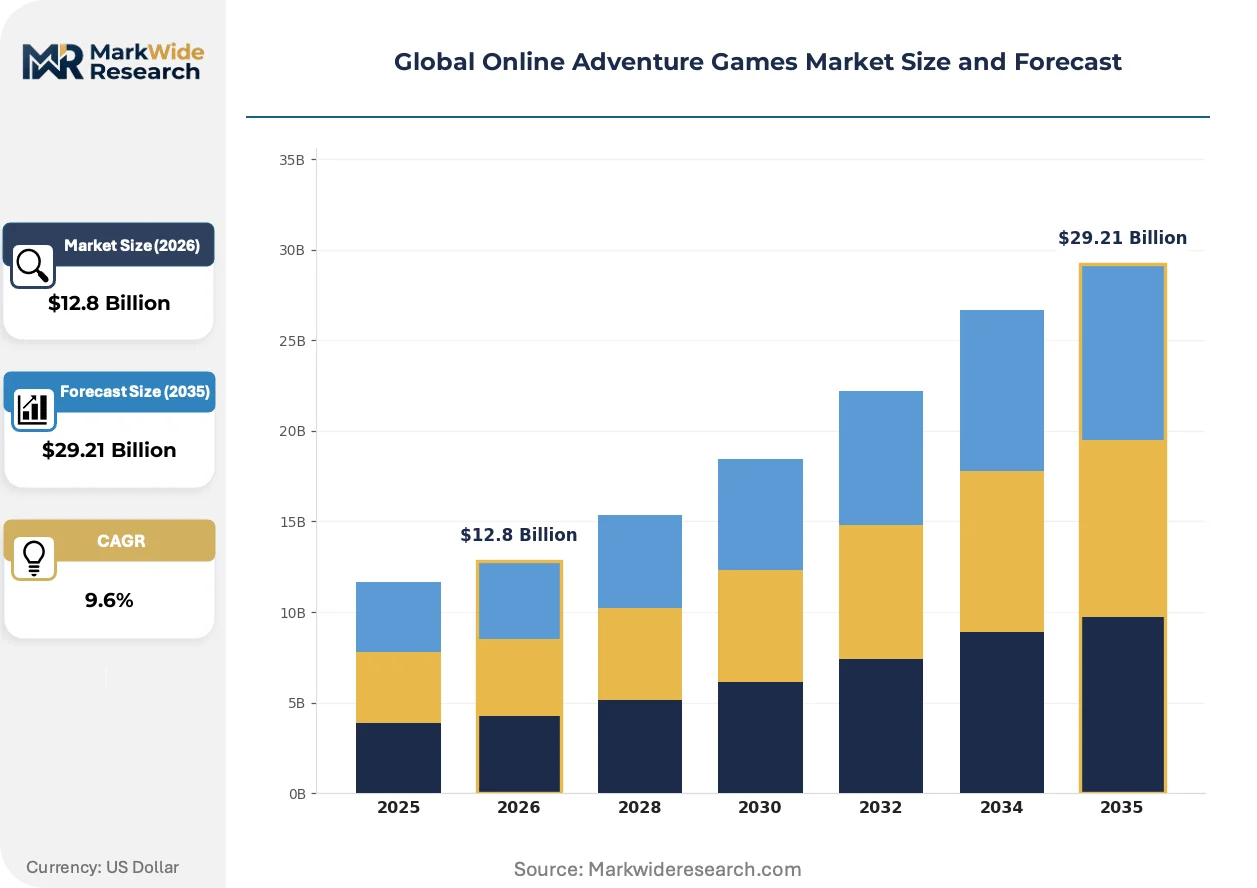
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Role-Playing, Survival, Puzzle, Platformer, Interactive Story, Sandbox Technology: Cloud Gaming, Virtual Reality, Augmented Reality, Multiplayer Online, Mobile Streaming, Cross-Platform Platform: PC, Console, Mobile, Web Browser, Dedicated Handheld, Smart TV Player Demographic: Casual Gamers, Competitive Players, Streamers, Social Gamers, eSports Participants, Content Creators |
| Companies Covered | Ubisoft, Naughty Dog, Riot Games, Take-Two Interactive, Electronic Arts, Epic Games, Rockstar Games, Nintendo, Activision Blizzard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Adventure Games Market Shifts & Advancements
Edge computing deployment and artificial intelligence integration are restructuring how adventure games are produced, distributed, and monetized across networked infrastructure.
Procedural narrative generation is collapsing the traditional scriptwriting bottleneck that constrained branching story complexity. Mid-size studios in Poland and Canada are adopting these tools to compete with AAA production values. The technology is collapsing cost differentials between linear and massively branching narrative architectures.
The EU Digital Services Act's algorithmic transparency requirements are forcing platform operators to disclose recommendation mechanics. Publishers must now optimize for direct discovery rather than opaque curation. Indie developers in France and Germany are building community-driven marketing channels that bypass platform gatekeeping.
Subscription fatigue among core gamers is fragmenting spending across multiple services rather than consolidating loyalty. This pattern is most visible in the United States and United Kingdom where average consumers maintain four to six overlapping entertainment subscriptions. Studios are responding with hybrid monetization that combines subscription access with cosmetic microtransactions.
Global Online Adventure Games Market Segmentation
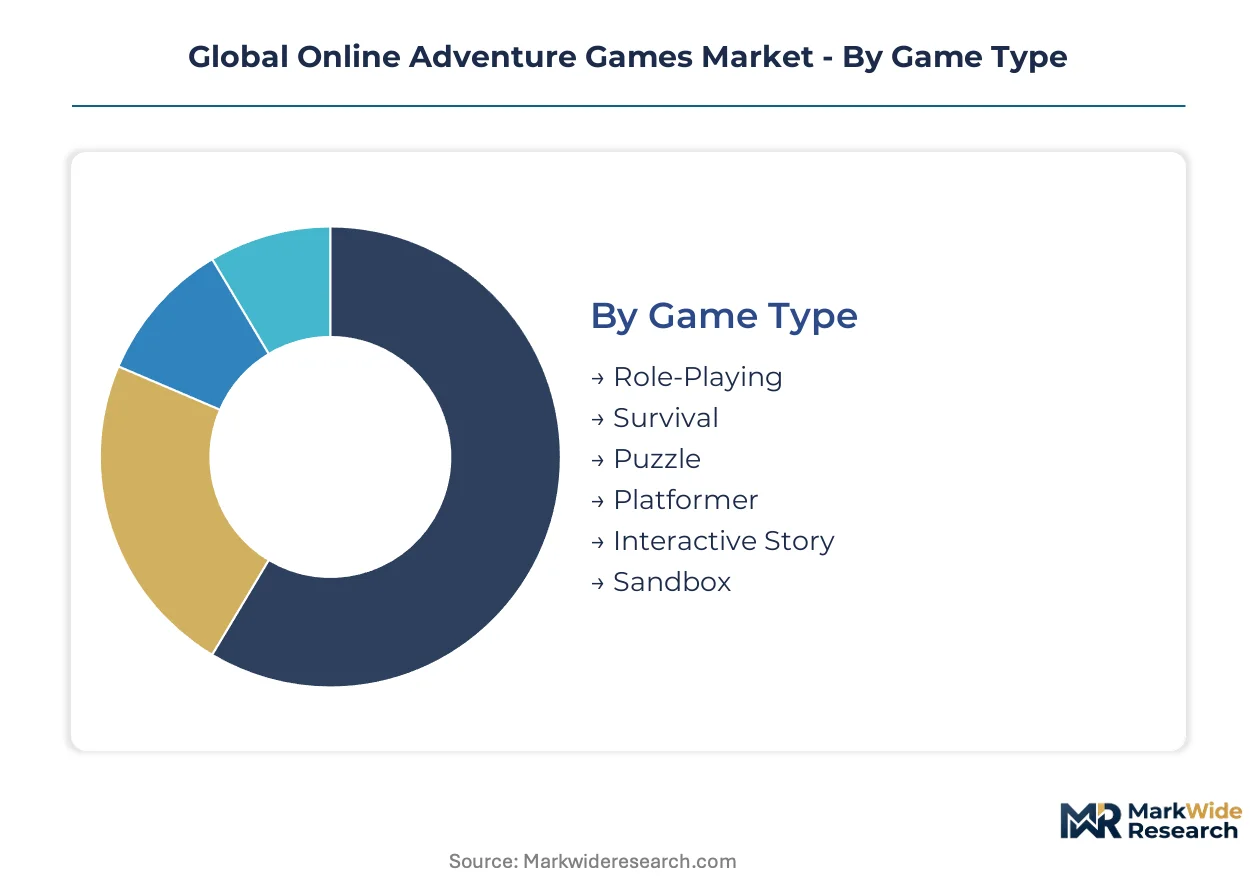
Segmentation reveals how distinct player behaviors and infrastructure requirements fragment revenue pools across the Global Online Adventure Games Market. Studios must align production budgets and monetization architectures with specific platform capabilities and demographic expectations rather than pursuing undifferentiated mass-market positioning.
Game Type:
Cost tier differentiation separates premium narrative productions from lightweight casual offerings, with production budgets ranging from indie-scale to nine-figure AAA investments.
- Role-Playing:Persistent character progression systems with branching dialogue trees and faction-based narrative consequences. Demand concentrates in China and South Korea where gacha monetization and seasonal content drops sustain multi-year engagement cycles.
- Sandbox:Open-world physics engines enabling emergent player narratives through environmental manipulation and construction mechanics. Indonesia and Vietnam drive adoption as mobile-first audiences prioritize creative expression over scripted sequences.
- Survival:Resource-scarcity mechanics combined with permadeath consequences and base-building progression loops.
- Puzzle:Spatial reasoning challenges integrated into environmental storytelling with limited action sequences.
- Platformer:Precision movement mechanics emphasizing timing-based traversal across two-dimensional or three-dimensional spaces.
- Interactive Story:Minimal gameplay systems prioritizing cinematic presentation and choice-based narrative branching.
Role-Playing commands the established base. The steepest expansion runs through Sandbox formats.
Technology:
Application architecture determines whether titles require localized hardware investment or function as thin-client streaming experiences.
- Cloud Gaming:Server-side rendering with sub-20ms latency requirements enabling smartphone access to AAA visual fidelity. China's MIIT edge node deployment standards accelerate domestic platform licensing and reduce bandwidth costs for publishers targeting tier-two cities.
- Cross-Platform:Persistent save-state synchronization across PC, console, and mobile devices with unified matchmaking pools. The EU Digital Services Act's interoperability mandates strengthen competitive positioning for studios building direct-to-consumer distribution outside platform gatekeeping.
- Virtual Reality:Six-degrees-of-freedom tracking with 90Hz minimum refresh rates and room-scale boundary systems.
- Augmented Reality:Camera-based spatial mapping overlaying digital assets onto physical environments through mobile devices.
- Multiplayer Online:Dedicated server architecture supporting 64+ concurrent players in shared persistent spaces.
- Mobile Streaming:Adaptive bitrate protocols optimized for cellular network volatility and data cap constraints.
Cross-Platform technology anchors current revenue concentration. Cloud Gaming gains share fastest as infrastructure latency thresholds cross usability thresholds in metropolitan clusters.
Platform:
Customer type and hardware ownership patterns segment addressable audiences by upfront capital commitment and session length expectations.
- Mobile:Touch-optimized control schemes with asynchronous session design accommodating sub-15-minute play windows. Southeast Asian markets led by Indonesia and Vietnam expand total addressable market as smartphone penetration outpaces console adoption.
- PC:Mouse-keyboard precision inputs with modular hardware upgrade paths and open distribution through multiple storefronts. China's real-name registration requirements and youth gaming time limits reshape onboarding architecture and retention mechanics.
- Console:Standardized hardware specifications enabling optimized visual performance with controller-centric interface design.
- Web Browser:Instant-play accessibility eliminating download friction through WebGL and WebAssembly rendering.
- Dedicated Handheld:Integrated screen-and-controller form factors emphasizing portability over raw processing power.
- Smart TV:Cloud-reliant streaming with simplified input schemes leveraging remote controls or companion smartphone apps.
PC retains the core spending base. Mobile demonstrates the steepest climb as casual demographics expand across emerging markets.
Player Demographic:
Volume concentration varies dramatically between high-frequency low-spend casual audiences and concentrated whale spending in competitive segments.
- Casual Gamers:Intermittent session patterns prioritizing narrative accessibility and low mechanical skill barriers over competitive depth. Mobile-first Southeast Asian audiences in Vietnam and the Philippines prioritize free-to-entry monetization with cosmetic microtransactions.
- Competitive Players:Skill-ranking systems with matchmaking algorithms and seasonal progression resets driving sustained engagement. South Korea's eSports infrastructure and cultural legitimization of gaming careers sustain premium spending on performance optimization.
- Streamers:Content creators prioritizing spectator-friendly mechanics and narrative moments optimized for clip generation.
- Social Gamers:Cooperative mechanics and guild systems emphasizing relationship maintenance over individual achievement.
- eSports Participants:Tournament-structured competition with standardized rule sets and spectator broadcast integration.
- Content Creators:User-generated toolsets and modding capabilities enabling derivative works and community expansion.
Casual Gamers represent the volume foundation. Competitive Players generate disproportionate per-user revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net content exports from China, the United States, and South Korea dominate cross-border digital services trade in interactive entertainment. Import demand concentrates in Southeast Asian and European markets seeking localized narrative adaptations. Regulatory divergence between data-localization regimes fragments operational scale for publishers pursuing multi-territory licensing.
China
MIIT cloud gaming standards accelerate edge node deployment across tier-two cities, reducing latency thresholds below 20 milliseconds. Real-name registration requirements and youth gaming time limits reshape onboarding architecture and compress conversion funnels. Shanghai and Beijing anchor domestic publishing headquarters while Chengdu and Hangzhou emerge as secondary development clusters for mid-budget titles.
United States
FTC scrutiny of in-game purchase disclosures elevates compliance costs for live-service monetization architectures. Subscription fatigue fragments spending across four to six overlapping entertainment services, pressuring retention metrics. Los Angeles and San Francisco Bay Area concentrate AAA development talent while Austin and Raleigh-Durham expand as secondary hubs for independent studios.
South Korea
eSports infrastructure and cultural legitimization of gaming careers sustain premium spending on performance optimization and cosmetic microtransactions. Shutdown law enforcement and real-name verification impose friction on youth-skewing demographics. Seoul anchors publisher headquarters while Busan-Ulsan corridor expands as cloud rendering infrastructure deployment zone.
Germany
GDPR-derived age-verification mandates require costly integration with fragmented national identity systems, delaying launch windows. EU Digital Services Act algorithmic transparency requirements create competitive openings for direct-to-consumer distribution bypassing platform curation. Berlin and Hamburg concentrate indie development while Munich anchors established publisher operations.
Indonesia
Smartphone penetration outpaces console adoption, expanding addressable audiences that prioritize narrative accessibility over hardware investment. Expanding 5G coverage in Jakarta and Surabaya reduces infrastructure barriers for cloud gaming access. Localized content partnerships with domestic telcos accelerate distribution reach into underpenetrated tier-two urban clusters.
Global Online Adventure Games Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated platform-holders and asset-light studios dependent on licensed engines and revenue-sharing partnerships. Consolidation pressure operates at the publishing layer while development remains fragmented across hundreds of specialized boutiques. Three archetypes dominate: engine-ecosystem orchestrators, hardware-software integrators, and live-service monetization specialists. Competitive moves concentrate on exclusive content acquisition for subscription retention and cross-platform save-state technology deployment.
Within the engine-ecosystem tier, Epic Games exemplifies supply-side leverage through Unreal Engine licensing that reduces production costs for affiliated developers. Electronic Arts occupies a position representing live-service monetization architectures that extend title lifecycles beyond traditional retail windows. Nintendo anchors the hardware-software integration archetype, sustaining premium pricing power through proprietary platform control.
| Leading Market Players |
|---|
| Ubisoft |
| Naughty Dog |
| Riot Games |
| Take-Two Interactive |
| Electronic Arts |
| Epic Games |
| Rockstar Games |
| Nintendo |
| Activision Blizzard |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud rendering infrastructure across China's tier-two cities is compressing server-hour rates and forcing publishers toward subscription bundling rather than per-title transactional models. This utilization dynamic simultaneously erodes spot pricing power for compute providers while incentivizing studios to lock in long-term capacity commitments at discounted rates.
Pricing Analysis
Industrial OEM buyers anchor hybrid monetization architectures combining subscription access with cosmetic microtransactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by content depth and early-access privileges. Cost compression in the economy tier is intensifying because Southeast Asian mobile-first audiences demand free-to-entry models. Casual gamers in Indonesia and Vietnam exhibit highest price sensitivity, while competitive players in South Korea show lowest sensitivity due to performance optimization spending.
Supply Chain Analysis
Export controls on advanced GPU fabrication equipment limit capacity expansion at Taiwan Semiconductor Manufacturing and Samsung Foundry, constraining cloud rendering hardware availability. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced node semiconductors. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized cooling substrates. Single-source vulnerability from TSMC's dominance in 5nm and below processes creates supply chain risk. Distribution runs through hyperscaler procurement contracts and direct publisher partnerships with edge node operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as subscription fatigue fragments spending across multiple services, creating niches for direct-to-consumer distribution and hybrid monetization specialists.
For Market Incumbents: Pre-empt regulatory fragmentation by building modular compliance architectures that port across China's MIIT standards, EU Digital Services Act mandates, and US FTC disclosure requirements. Secure exclusive content pipelines through revenue-sharing partnerships with mid-size studios in Poland and Canada adopting procedural generation tools. Vertical integration into edge computing infrastructure insulates against GPU supply concentration risk. For New Entrants and Emerging Players: Indonesia and Vietnam's underpenetrated mobile-first markets offer white-space positioning before platform saturation. Target sandbox format adoption where creative expression mechanics outperform scripted narrative complexity. Pursue localized content partnerships with domestic Indonesian telcos to bypass platform gatekeeping. Deploy AI-assisted procedural generation to compress production timelines for mid-budget titles competing with AAA production values. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native development pipelines as server-side rendering reduces client hardware dependencies. Long-term viability favors studios with asset-light publishing models and direct-to-consumer distribution capabilities. Acquisition targets should demonstrate cross-platform save-state technology and community-driven marketing channels. Monitor MIIT licensing velocity as inflection indicator for China market access risk.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Infrastructure Partnership | Reduces latency below 20 milliseconds in Jakarta and Ho Chi Minh City metropolitan clusters. |
| Procedural Generation Technology Adoption | Compresses scriptwriting bottlenecks for Polish and Canadian mid-size studios competing with AAA budgets. |
| Direct-to-Consumer Platform Launch | Bypasses EU Digital Services Act algorithmic transparency constraints on opaque platform curation. |
| Cross-Platform Save-State Deployment | Increases daily active user retention across PC, console, and mobile device ecosystems. |
| Localized Content Partnership | Accelerates distribution reach into underpenetrated Indonesian tier-two urban clusters through telco bundling. |
Research Methodology
Operator-level perspectives from live-service engineering directors, cloud platform procurement leads, regional publishing heads, and regulatory compliance officers anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings, MIIT licensing disclosures, EU regulatory submissions, and hyperscaler capex reports. Bottom-up title-level revenue modeling triangulated against top-down market sizing across technology, platform, and demographic segmentation dimensions.
Scenario-bracketing framed analytical outputs across the projection horizon, with CAGRs derived from trend extrapolation moderated by infrastructure deployment timelines and regulatory implementation schedules. Segmentation dimensions modeled include game type, technology architecture, platform ecosystem, and player demographic behavior patterns. Cloud gaming latency thresholds, GPU fabrication capacity allocation, and real-name registration conversion funnel impacts served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler platform operators or engine-ecosystem orchestrators would shift outcomes. Material shifts in China's MIIT content approval velocity, EU Digital Services Act enforcement intensity, or Taiwan Semiconductor Manufacturing capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Online Casino Market
Gaming
Online Strategy Games Market
Gaming
Videogames Market
Gaming
Singapore Gaming Gadgets Market
Gaming
VR Melee Games Market
Gaming
Traditional Casual Games Market
Gaming
Board Games Market
Gaming
AAA Games Market
Gaming
Lottery Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Gaming Console Market
Gaming
Global Tarot Cards Market
Gaming
FPS Game Market
Gaming
VR Gaming Console Market
Gaming
China Gaming Headsets Market