
 Global Gaming Market | 2026-2036
Global Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gaming Market Analysis
Enterprise training and education verticals is realigning how gaming technology penetrates beyond leisure consumption. Microsoft Gaming leverages its cloud infrastructure to anchor enterprise-facing simulation tools alongside consumer Xbox services. Sony Interactive Entertainment differentiates through exclusive intellectual property and hardware-software integration that sustains premium pricing power. Tencent Holdings dominates mobile distribution networks across Asia while navigating regulatory constraints in multiple jurisdictions.
Gaming encompasses interactive software and hardware systems designed for entertainment, skill development, or competitive play, typically requiring real-time rendering engines, input latency below 50 milliseconds, and networked multiplayer architecture. The primary commercial purpose spans direct consumer monetization, advertising inventory, and increasingly, workforce training simulations. Mobile games command the largest addressable user base among product type segments, though console games retain superior per-user revenue economics. Hardcore gamers generate disproportionate margin pools within customer type segments through sustained in-game purchasing behavior. Subscription services within distribution channel segments are displacing unit-sales dependency as platform holders pursue recurring revenue models.
The US FTC scrutinizes platform exclusivity arrangements and in-game monetization disclosures, while China's NMPA enforces content approval queues that directly shape release calendars for multinational publishers. The EU AI Act imposes transparency obligations on procedural content generation and adaptive difficulty systems deployed in European markets. Stakeholders must monitor evolving classification frameworks that could reclassify loot mechanics as regulated gambling instruments in additional jurisdictions.
Market Dynamics
Cloud gaming infrastructure is compressing capital requirements for market entry while fragmenting distribution control away from hardware-centric platform holders toward telecommunications and media conglomerates bundling interactive entertainment into subscription ecosystems.
Growth Catalysts
- 5G Network Rollouts:Telecommunications carriers in South Korea and Japan are bundling low-latency gaming services with mobile data plans, reducing friction for cloud-streamed titles.
- EU AI Act Transparency Mandates:Procedural content generation tools gain legitimacy through compliance frameworks that clarify liability for algorithmically generated game assets.
- Live-Service Monetization:Southeast Asian mobile-first user bases sustain recurring revenue through battle pass systems and seasonal content drops.
Market Restraints
- Input Latency Thresholds:Cloud gaming services struggle to consistently deliver sub-50 millisecond response times in regions with fiber-to-the-home penetration below 60 percent.
- GPU Supply Concentration:Advanced semiconductor fabrication for real-time ray tracing hardware depends on foundry capacity concentrated in Taiwan.
- NMPA Approval Queues:China's content review framework extends release timelines for international publishers by 6-18 months versus other jurisdictions.
Strategic Opportunities
- Enterprise Simulation Verticals:Workforce training applications in aviation and healthcare create B2B revenue streams detached from consumer entertainment cycles.
- India's Broadband Expansion:Government-funded fiber deployment in tier-2 and tier-3 cities unlocks first-time cloud gaming adoption among 400 million prospective users.
- Blockchain-Asset Convergence:Player-owned economies and cross-title item portability attract development investment from fintech-adjacent venture pools.
Industry Challenges
- Live Operations Talent Scarcity:Sustained content pipelines for service games require data analytics and community management functions where qualified personnel command premium compensation.
- Cross-Platform Certification Complexity:Multi-device releases must satisfy distinct technical requirements from Sony, Microsoft, Nintendo, Apple, and Google certification teams simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gaming Market |
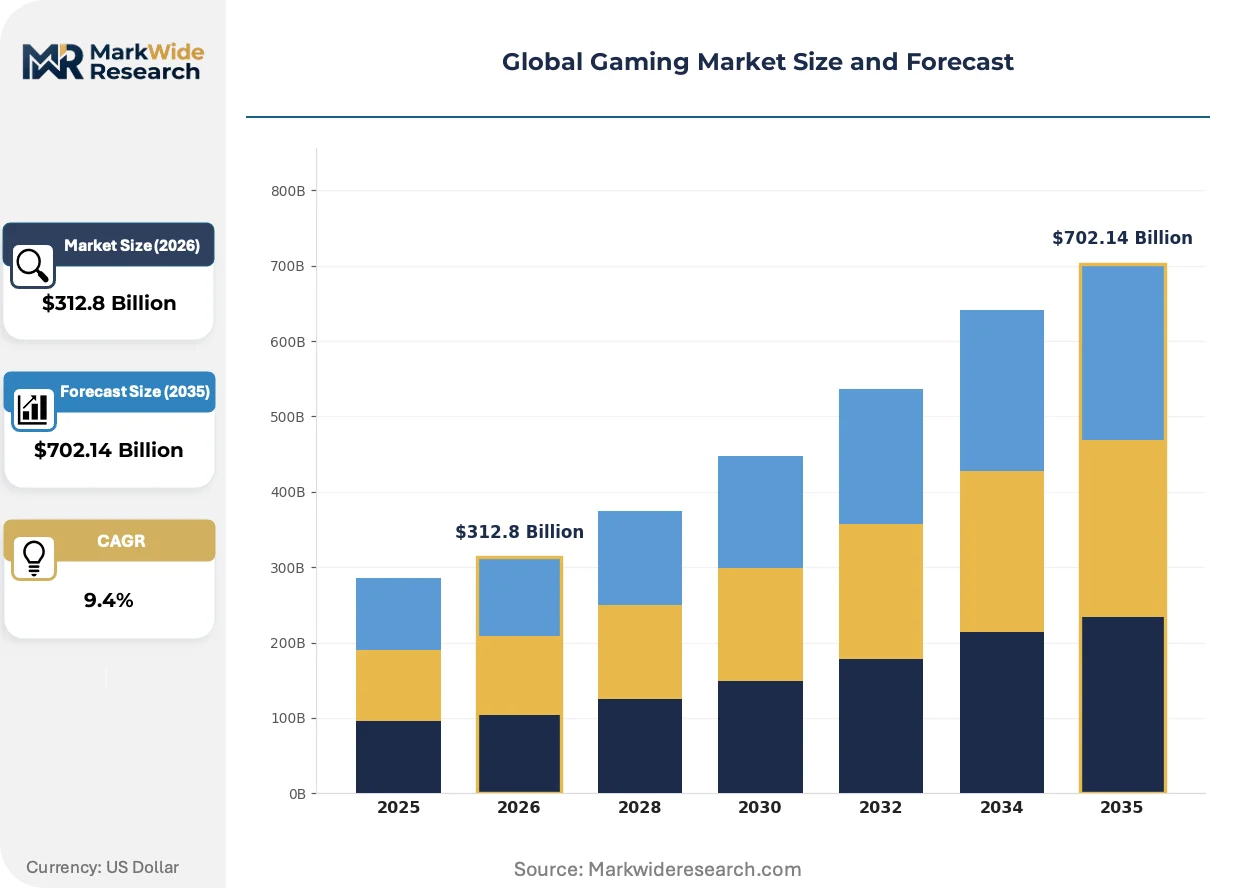
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $702.14 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Console Games, PC Games, Mobile Games, Online Games Customer Type: Casual Gamers, Hardcore Gamers, Professional Gamers, Streaming Enthusiasts Distribution Channel: Retail Stores, Online Platforms, Subscription Services, Direct Downloads Game Genre: Action, Strategy, RPG, Simulation |
| Companies Covered | Tencent Holdings, Sony Interactive Entertainment, Microsoft Gaming, NetEase Games, Nintendo, Electronic Arts, Activision Blizzard, Take-Two Interactive, Nexon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gaming Market Emerging Trajectories
Interactive entertainment technology is bifurcating between immersive hardware experiences and frictionless cloud access, with regulatory frameworks increasingly treating game mechanics as subject to consumer protection and gambling classification scrutiny.
Edge computing nodes positioned within telecommunications infrastructure are decentralizing rendering workloads away from centralized data centers. Mobile network operators in Germany and South Korea deploy graphics processing units at cell tower aggregation points, reducing round-trip latency for streaming subscribers. This architecture compresses the addressable market for dedicated gaming consoles among casual players.
China's NMPA continues tightening approval criteria for titles incorporating loot box mechanics or probabilistic item acquisition. Publishers must now disclose exact drop rates and implement spending caps for minor accounts. Multinational studios are responding by bifurcating monetization architectures, deploying direct-purchase models in regulated jurisdictions while maintaining randomized systems elsewhere.
Subscription fatigue among entertainment consumers is fragmenting purchasing behavior across multiple competing game services. Hardcore players maintain overlapping memberships to access exclusive catalogs, while casual users churn rapidly between free-to-play alternatives. This pattern concentrates lifetime value extraction on whale segments in Southeast Asian and Latin American markets where credit-based microtransaction penetration exceeds direct subscription attachment.
Global Gaming Market Segmentation
Gaming markets fragment across hardware, user behavior, and monetization pathways. Each segmentation axis reveals distinct margin structures and capital intensity requirements that shape competitive positioning.
Product Type:
Upgrade cycles and replacement dynamics vary dramatically across hardware platforms, with mobile devices refreshing every 2-3 years while console generations extend to 7-8 years.
- Console Games:Dedicated hardware-software integration demands specialized optimization for Sony PlayStation, Microsoft Xbox, and Nintendo architectures. Premium pricing power concentrates in exclusive first-party titles from Japanese and American studios, though semiconductor supply constraints periodically disrupt hardware availability.
- Mobile Games:Touch-optimized interfaces and abbreviated session design dominate Southeast Asian and Indian markets where smartphone penetration outpaces PC or console adoption. Free-to-play monetization through battle passes and gacha systems generates recurring revenue from whale segments.
- PC Games:Open hardware ecosystems permit user-modified configurations and aftermarket component upgrades. Steam and Epic Games Store distribution reduces retail dependency while enabling direct developer-publisher relationships.
- Online Games:Persistent server infrastructure supports multiplayer matchmaking and live-service content pipelines. Latency requirements below 50 milliseconds constrain viable hosting geography for competitive titles.
Mobile Games sits at the top of the volume ranking, with Online Games climbing the fastest.
Customer Type:
Spending concentration and engagement duration separate casual participants from dedicated enthusiasts who drive lifetime value extraction.
- Hardcore Gamers:Daily session lengths exceeding three hours sustain premium hardware purchases and sustained in-game transaction velocity. This segment disproportionately populates esports viewership and influencer-driven purchase decisions in South Korea and Germany.
- Professional Gamers:Tournament prize pools and streaming revenue transform gameplay into primary income generation. Training regimens and team infrastructure mirror traditional athletic preparation in markets with established esports leagues.
- Casual Gamers:Intermittent engagement patterns favor hyper-casual mobile titles with minimal learning curves. Advertising-supported monetization dominates where direct payment friction remains high.
- Streaming Enthusiasts:Content consumption without direct play creates ancillary revenue through subscription gifting and merchandise purchases. Platform algorithms in Brazil and Mexico prioritize discoverability for emerging creators.
Hardcore Gamers commands the highest per-user revenue, with Streaming Enthusiasts expanding most quickly.
Distribution Channel:
Margin capture shifts toward platform holders as digital penetration reduces physical retail intermediation.
- Subscription Services:Xbox Game Pass and PlayStation Plus bundle catalog access into predictable monthly fees. Cloud streaming components reduce hardware ownership requirements for catalog exploration.
- Online Platforms:Steam, Epic Games Store, and mobile app stores extract 15-30 percent revenue share from transactions. Discovery algorithms and seasonal sales events concentrate volume spikes.
- Direct Downloads:Publisher-operated storefronts bypass platform fees but require independent payment processing and customer support infrastructure. Fortnite and League of Legends deploy this model at scale.
- Retail Stores:Physical disc and cartridge sales persist in collector markets and regions with unreliable broadband infrastructure. Walmart and GameStop maintain dedicated gaming sections in the United States.
Online Platforms leads transaction volume, with Subscription Services gaining share fastest.
Game Genre:
Development cost structures and audience retention mechanics diverge sharply across creative categories.
- Action:High-fidelity graphics and responsive combat systems demand substantial animation and physics engineering resources. Annualized releases from Activision and EA Sports dominate Western markets.
- RPG:Narrative depth and character progression systems extend average playtime to 40-100 hours. Japanese studios in Tokyo and Osaka maintain genre leadership through decades of franchise cultivation.
- Strategy:Systems-driven gameplay prioritizes AI sophistication and multiplayer balance over visual production values. PC-centric audience in Eastern Europe and Scandinavia sustains niche profitability.
- Simulation:Authenticity requirements drive licensing partnerships with automotive, aviation, and agricultural equipment manufacturers. Farming Simulator and Microsoft Flight Simulator attract non-traditional gamer demographics.
Action holds the largest addressable audience, with Simulation climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the global gaming industry through concentrated console development expertise and decades of hardware-software integration mastery. The United States and China follow with distinct competitive advantages in cloud infrastructure and mobile distribution networks respectively. Germany, South Korea, and Brazil round out the five-country analysis with specialized strengths in simulation software, esports infrastructure, and emerging market expansion.
United States
Cloud gaming infrastructure investments and enterprise simulation demand drive domestic expansion. The FTC scrutinizes platform exclusivity arrangements and in-game monetization disclosures with renewed enforcement vigor. Seattle and Los Angeles maintain development clusters where Microsoft Gaming and multiple independent studios advance service-based monetization architectures.
China
Mobile-first user bases and super-app distribution integration sustain volume leadership across Asia. The NMPA enforces content approval queues that extend international publisher release timelines by 6-18 months versus other jurisdictions. Shenzhen and Hangzhou host development campuses where Tencent Holdings and NetEase Games refine live-service monetization systems for domestic and export markets.
Japan
Exclusive intellectual property development and hardware-software integration sustain premium pricing power in console segments. METI supports digital content export initiatives through targeted subsidy programs for localization and marketing. Tokyo and Osaka anchor development clusters where Sony Interactive Entertainment and Nintendo maintain genre leadership through decades of franchise cultivation.
Germany
Simulation genre specialization and PC-centric strategy audiences create defensible niche profitability. The EU AI Act imposes transparency obligations on procedural content generation tools deployed in European markets. Munich and Hamburg host development studios where automotive and aviation authenticity requirements drive licensing partnerships with industrial equipment manufacturers.
South Korea
Esports infrastructure investment and 5G network density enable low-latency cloud gaming service deployment. Telecommunications carriers bundle gaming subscriptions with mobile data plans under regulatory frameworks administered by the Korea Communications Commission. Seoul anchors competitive gaming clusters where professional tournament ecosystems and streaming platforms concentrate talent development and audience monetization.
Global Gaming Market Vendor Landscape
Platform exclusivity arrangements dominate the current landscape as hardware-software integration becomes the primary defensive moat. The vendor base concentrates around three strategic archetypes: cloud infrastructure operators leveraging telecommunications partnerships, exclusive content developers sustaining premium hardware attach rates, and mobile distribution platforms capturing emerging market volume. M&A activity and live-service talent acquisition represent the dominant competitive moves as studios compete for data analytics and community management capabilities.
Within the integrated platform tier, Tencent Holdings and Sony Interactive Entertainment exemplify contrasting geographic specializations—Chinese mobile distribution networks versus Japanese console hardware-software ecosystems—while Microsoft Gaming anchors the cloud-first archetype through Azure infrastructure integration. These three entities occupy positions that span consumer entertainment and emerging enterprise simulation verticals.
| Leading Market Players |
|---|
| Tencent Holdings |
| Sony Interactive Entertainment |
| Microsoft Gaming |
| NetEase Games |
| Nintendo |
| Electronic Arts |
| Activision Blizzard |
| Take-Two Interactive |
| Nexon |
| Others |
Supply Flow & Price Mechanics
Subscription fatigue among entertainment consumers is forcing publishers to bifurcate monetization architectures, compressing margins on standardized content while premium exclusive titles command hardware-attach premiums. This demand fragmentation reshapes supply chain priorities toward live-service infrastructure and cloud rendering capacity.
Pricing Analysis
Input-cost pass-through from GPU foundry capacity constraints and telecommunications bandwidth fees shapes pricing stratification across premium, standard, and economy tiers. Price differentiation rests on exclusive content access and latency-grade service levels. Pricing pressure stems from free-to-play alternatives eroding subscription attachment in Southeast Asian markets. Casual mobile segments exhibit highest price sensitivity, while hardcore console enthusiasts sustain premium hardware-software bundles.
Supply Chain Analysis
Direct-to-consumer digital storefronts handle hyperscale distribution, though physical retail persists in broadband-constrained regions. Geographic supply concentration centers on Taiwan for advanced semiconductor fabrication, South Korea for memory components, and China for assembly and mobile device manufacturing. Raw material dependencies include rare earth elements for magnetics, high-purity silicon for processors, and cobalt-lithium compounds for battery systems. Single-source vulnerability in TSMC's leading-edge foundry capacity exposes the entire ecosystem to geopolitical disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where NMPA approval timelines in China create 6-18 month release delays versus FTC-regulated US markets, rewarding publishers with parallel development pipelines and jurisdiction-specific monetization architectures.
For Market Incumbents: Anchor defensive positioning through exclusive IP cultivation and cloud infrastructure lock-in via telecommunications partnerships. Threats from emerging cloud-native entrants demand backward integration into rendering hardware supply. Priority lever: enterprise simulation verticals detach revenue from consumer entertainment cycles. For New Entrants and Emerging Players: Begin with India's tier-2 and tier-3 cities where government-funded fiber deployment unlocks first-time cloud gaming adoption among 400 million prospective users. Enterprise training simulations in aviation and healthcare offer the most penetrable white-space. Go-to-market angle: workforce certification partnerships with industrial equipment manufacturers. For Investors and Strategic Acquirers: Asymmetric upside sits with live-service talent acquisition targets possessing data analytics and community management capabilities. Long-term viability hinges on recurring revenue model durability. Acquisition target archetype: mid-cap studios with established seasonal content pipelines. Signal to watch: NMPA approval velocity as inflection indicator for China market access.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Telecommunications bundling reduces subscriber acquisition costs through mobile data plan integration. |
| Exclusive IP Development | First-party titles sustain premium hardware attach rates against platform-agnostic streaming alternatives. |
| Enterprise Simulation Expansion | Aviation and healthcare training applications unlock B2B revenue detached from consumer entertainment volatility. |
| Live-Service Talent Acquisition | Data analytics and community management capabilities command premium compensation in sustained content pipelines. |
| Regulatory Compliance Architecture | EU AI Act transparency mandates legitimize procedural content generation tools in European market deployment. |
Methodological Framework
Bottom-up gamer segmentation modeling reconciled against top-down platform holder revenue tracking forms the analytical core of this study. Primary interviews with game development executives, live-service operations directors, platform certification managers, and telecommunications partnership leads combined with secondary validation from SEC filings, NMPA approval databases, App Annie mobile revenue estimates, and hyperscaler capex disclosures. Triangulation across these sources ensures dimensional consistency.
Input-output matrix framing connects hardware shipment volumes through software attach rates to monetization event frequency across the projection horizon. Segmentation dimensions modeled include product type, customer engagement tier, distribution channel, and regional regulatory cluster. CAGRs derive from regression analysis against broadband penetration curves and GPU price-performance trajectories. Industry-specific forecast inputs incorporate 5G rollout schedules and NMPA queue processing rates.
Several conditions sit outside the modeled scope, including unannounced hardware generation transitions, regulatory reclassification of loot mechanics as gambling instruments, and geopolitical disruption of Taiwan semiconductor supply. Forecasts reflect assumptions about sustained consumer discretionary spending and cloud infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
LAMEA Gaming Posters Market
Gaming
Global NFT Gaming Market
Gaming
Gaming Simulation Market
Gaming
Lottery Market
Gaming
Videogames Market
Gaming
France Online Gambling Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Africa Gaming Market
Gaming
Puzzle Video Game Market
Gaming
Playstation Network (PSN) Market
Gaming
United States Gaming Accessories Market
Gaming
PC Games Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
FPS Game Market
Gaming
Europe Gaming Peripherals Market
Gaming
RPG Games Market