
 Photo Sharing Market | 2026-2036
Photo Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Sharing Market Outlook
Travel and hospitality marketing is realigning the revenue mix for photo sharing platforms as brands prioritize authentic visual content over traditional advertising. Meta leverages its integrated ecosystem to sustain cross-platform engagement across Instagram and WhatsApp. Pinterest anchors commerce-driven discovery by linking visual search directly to purchase pathways. Google competes through AI-powered editing and storage bundling within its cloud services.
Photo sharing encompasses digital platforms enabling users to upload, store, edit, and distribute visual content through internet-connected interfaces, typically operating on cloud-native architectures with compression algorithms reducing file sizes by 60-80% for efficient transmission. The primary commercial purpose centers on audience engagement, brand storytelling, and monetizable attention capture for advertisers and creators. Mobile Apps dominate usage volumes due to persistent smartphone penetration, while Subscription service models concentrate margin pools through recurring revenue and premium feature tiers. Social Media as a platform type captures the broadest user base, though Photographers as a user segment generate disproportionate per-user value through professional tool subscriptions.
The US Federal Trade Commission scrutinizes data harvesting practices in photo sharing, directly influencing platform consent mechanisms and targeted advertising architectures. The EU AI Act imposes transparency obligations on automated content recommendation systems, reshaping how platforms deploy algorithmic curation across European markets. India's Digital Personal Data Protection Act establishes localization requirements that affect cross-border image storage and processing workflows. Stakeholders must weigh regulatory fragmentation against the operational efficiencies of unified global platform architectures.
Market Dynamics
Generative AI image editing tools are compressing professional photography workflows into consumer-grade interfaces, forcing platforms to rebuild monetization models around automated creation rather than manual upload volumes.
Growth Catalysts
- India's Digital Personal Data Protection Act:Localization mandates are accelerating domestic cloud infrastructure buildout, reducing latency for image processing and enabling real-time feature deployment.
- Travel and hospitality marketing pivot:Brands now allocate budget toward user-generated content licensing, creating direct revenue pipelines from amateur creator bases.
- Mobile-first creator economy:Smartphone penetration in tier-2 and tier-3 Indian cities is expanding addressable user pools beyond metropolitan early adopters.
Market Restraints
- Cloud storage cost volatility:Energy price fluctuations in hyperscaler data centers directly compress platform gross margins on free-tier user bases.
- EU AI Act transparency obligations:Automated content recommendation systems now require algorithmic disclosure, increasing compliance engineering overhead.
- Generative image substitution:Synthetic media tools reduce dependency on authentic photography for commercial visual content.
Strategic Opportunities
- Underpenetrated rural India:Regional language interfaces and low-bandwidth compression protocols can unlock creator participation in non-urban districts.
- AI-powered content moderation convergence:Machine vision classifiers combined with natural language processing enable automated policy enforcement at scale.
- Commerce-linked visual search:Pinterest-style discovery-to-purchase pathways remain underdeveloped across Asian markets outside China.
Industry Challenges
- AI ethics and bias mitigation:Training data diversity gaps in facial recognition and skin-tone rendering require ongoing algorithmic audit investment.
- Legacy platform migration friction:Decades of user photo archives locked in proprietary formats complicate competitive switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Sharing Market |
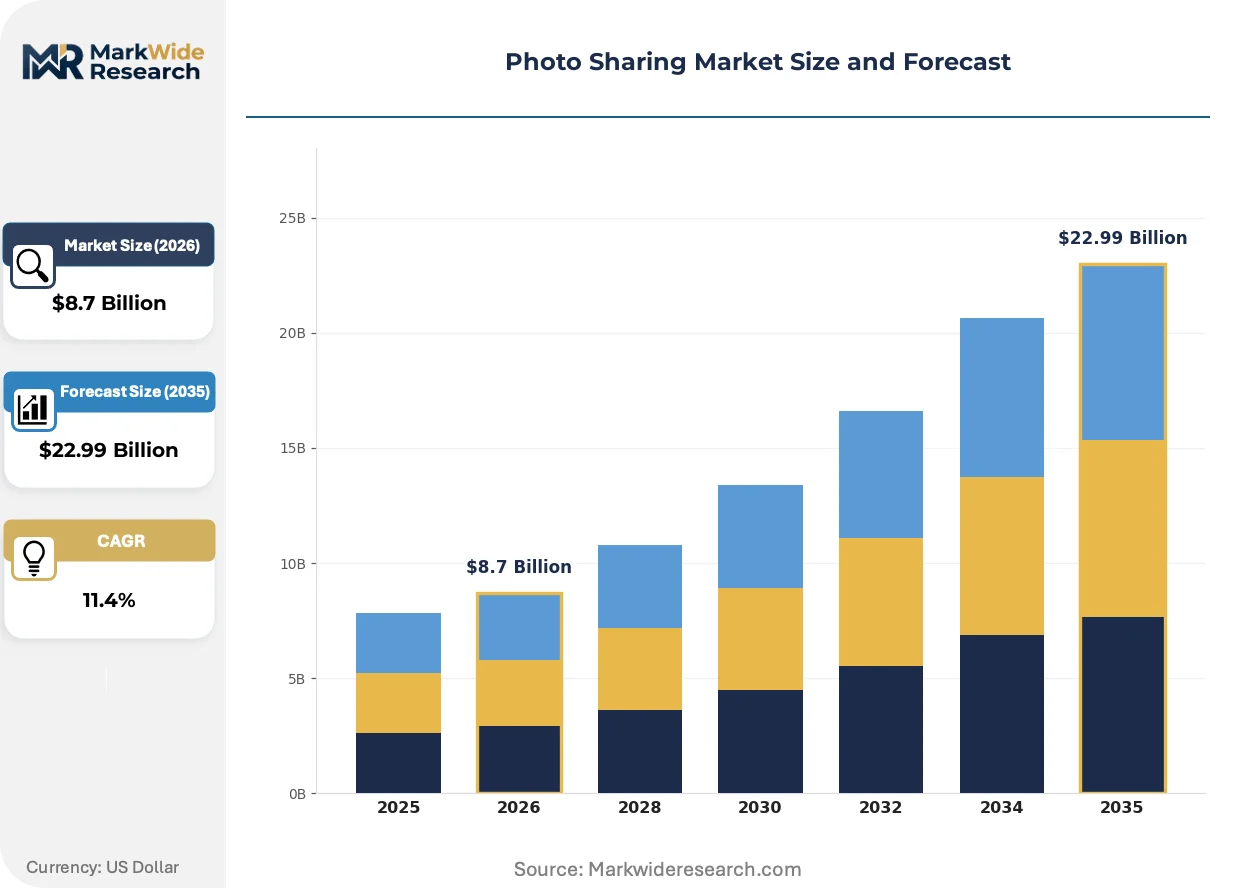
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile Apps, Web Platforms, Desktop Applications, Social Media User Type: Individual Users, Businesses, Photographers, Influencers Service Model: Freemium, Subscription, Pay-Per-Use, Advertising-Based Content Type: Images, Videos, GIFs, Animations |
| Companies Covered | Adobe, Pinterest, Meta, TikTok, Flickr, Google, Amazon, Zenfolio, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Sharing Market Strategic Shifts
Computational photography and edge-based AI processing are redistributing image enhancement workloads from centralized servers to device hardware, altering platform infrastructure economics.
Generative adversarial networks for automated background removal and style transfer are consolidating professional editing capabilities into single-tap mobile interfaces. Casual creators now produce commercial-grade visual content without desktop software expertise. This compression is collapsing the traditional segmentation between amateur and professional tool tiers.
The EU AI Act's transparency mandates for algorithmic curation are forcing platforms to expose ranking logic and provide user-facing controls over recommendation feeds. European operators must rebuild content distribution architectures around explainable automation rather than opaque engagement optimization. Travel and hospitality brands targeting EU consumers face heightened scrutiny on influencer content disclosure.
Subscription fatigue among casual users is fragmenting monetization toward microtransaction models for individual features. Platforms now unbundle premium filters, storage tiers, and analytics into à la carte purchases. India demonstrates this pattern most acutely, where price-sensitive users resist recurring commitments but demonstrate willingness to pay for discrete utility.
Photo Sharing Market Segmentation
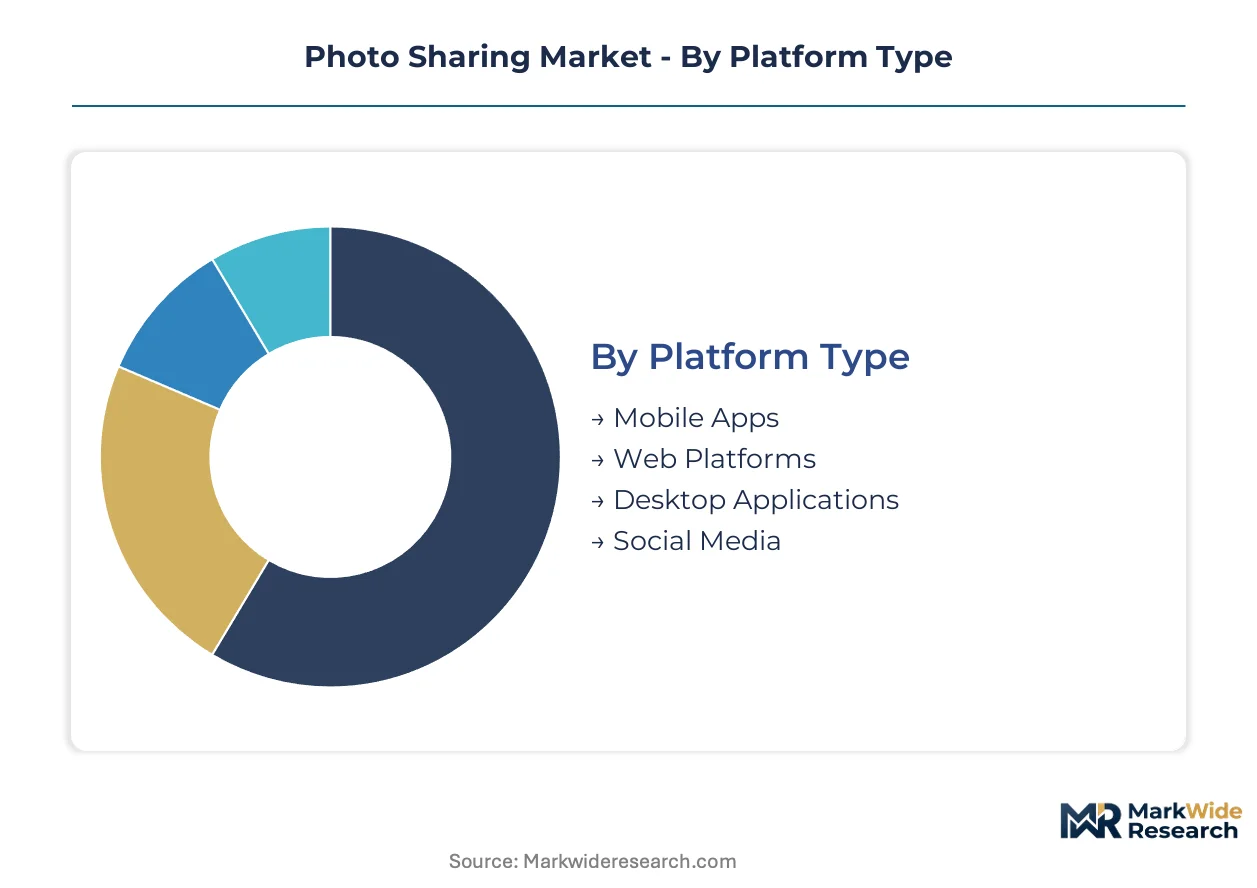
Photo sharing platforms fragment across four distinct segmentation axes that determine infrastructure requirements, monetization architecture, and user acquisition strategy. Platform type dictates technical stack and engagement patterns. User type shapes feature prioritization and pricing elasticity. Service model governs revenue predictability. Content type drives storage costs and processing workloads.
Platform Type:
Customization ranges from white-label enterprise deployments to standardized consumer interfaces, with infrastructure investment scaling inversely to standardization.
- Mobile Apps:Native iOS and Android applications leverage device GPU acceleration for real-time filtering and edge-based compression. Demand concentrates in India, where Jio's affordable data plans and Xiaomi's sub-$200 smartphone dominance have expanded addressable user bases beyond metropolitan centers. Persistent smartphone penetration in tier-2 and tier-3 cities sustains volume leadership.
- Social Media:Integrated platforms bundle photo sharing with messaging, commerce, and content discovery, capturing network effects through cross-functional engagement. Travel and hospitality brands prioritize these channels for user-generated content campaigns, redirecting marketing spend from traditional advertising toward authentic visual storytelling.
- Web Platforms:Browser-based interfaces serve professional workflows requiring desktop-grade editing tools and batch upload capabilities.
- Desktop Applications:Standalone software addresses high-resolution RAW processing and local storage preferences among professional photographers.
Leading the category by volume: Mobile Apps. Expanding most quickly: Social Media through commerce integration.
User Type:
Cost tier separation runs from free casual participants to premium professional subscribers, with per-user economics diverging by an order of magnitude.
- Photographers:Professional and semi-professional creators demand RAW format support, color grading tools, and portfolio hosting with client delivery workflows. Adobe Lightroom and Capture One integrations dominate this segment. India's wedding photography industry, concentrated in Mumbai, Delhi, and Bangalore, drives regional subscription growth for advanced editing suites.
- Businesses:Corporate accounts require brand safety controls, team collaboration features, and analytics dashboards for campaign measurement. Travel and hospitality chains in the US and EU deploy these tools for centralized content governance across property portfolios.
- Individual Users:Casual consumers prioritize simplicity, social connectivity, and free storage tiers.
- Influencers:Content creators monetizing audience attention need audience analytics, branded content disclosure tools, and direct payment integration.
Dominating by revenue per user: Photographers. Climbing the fastest: Businesses through enterprise licensing.
Service Model:
Margin structure varies from advertising-dependent volatility to subscription predictability, with hybrid models capturing intermediate risk profiles.
- Subscription:Recurring revenue models concentrate margin pools through premium feature tiers, expanded storage, and ad-free experiences. India's price-sensitive market resists monthly commitments, driving platforms toward annual discounting and family plan bundling to improve retention.
- Freemium:Tiered access converts free users through feature gates, with conversion rates determining unit economics sustainability.
- Advertising-Based:Targeted display and video advertising funds free tiers, with FTC scrutiny in the US and GDPR constraints in Europe increasing compliance overhead.
- Pay-Per-Use:Transactional pricing for discrete services—premium filters, print fulfillment, AI editing credits—addresses subscription fatigue among casual participants.
Highest revenue stability: Subscription. Gaining share fastest: Pay-Per-Use in emerging markets.
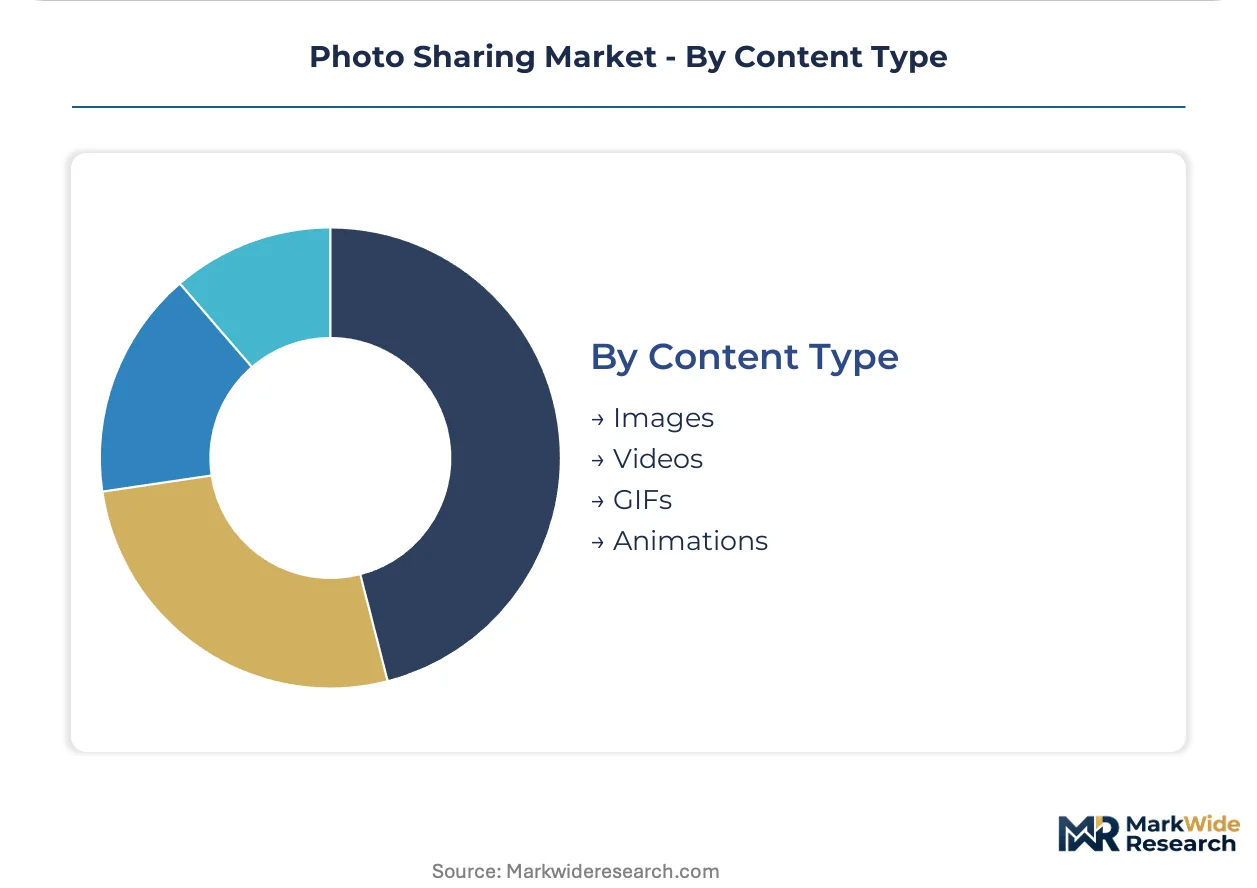
Content Type:
Processing intensity and storage economics scale from lightweight static formats to compute-heavy motion content, with infrastructure requirements diverging accordingly.
- Videos:Short-form and long-form motion content demands transcoding pipelines, adaptive bitrate delivery, and higher storage allocations. India's Reels and Shorts consumption surge strains domestic cloud infrastructure, accelerating AWS, Azure, and Google Cloud data center expansion in Mumbai and Hyderabad.
- Images:Static photographs remain the foundational format, with compression algorithms reducing file sizes by 60-80% for efficient transmission.
- GIFs:Looping silent animations serve messaging and reaction use cases with moderate processing requirements.
- Animations:Motion graphics and cinemagraphs blend static and dynamic elements, requiring specialized rendering tools.
Largest storage footprint: Videos. Steepest expansion trajectory: Animations through generative AI tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India, China, and the United States concentrate photo sharing platform infrastructure investment through data center tax incentives and cloud computing subsidies. These jurisdictions attract hyperscaler deployments that reduce latency for image processing and enable real-time feature deployment across their respective domestic markets.
United States
Enterprise licensing from travel and hospitality chains drives B2B revenue concentration, with Marriott and Hilton deploying centralized content governance tools across property portfolios. FTC scrutiny of data harvesting practices forces platforms to rebuild consent mechanisms and targeted advertising architectures. Platform engineering clusters in Seattle and Menlo Park anchor AI-powered content moderation development for global deployment.
India
Jio's affordable data plans and Xiaomi's sub-$200 smartphone dominance expand addressable user bases beyond metropolitan centers into tier-2 and tier-3 cities. The Digital Personal Data Protection Act establishes localization requirements that accelerate domestic cloud infrastructure buildout by AWS, Azure, and Google Cloud in Mumbai and Hyderabad. Wedding photography industries in Delhi, Mumbai, and Bangalore drive regional subscription growth for advanced editing suites.
China
Short-form video consumption strains domestic cloud infrastructure, accelerating proprietary data center expansion by ByteDance and Tencent. MIIT regulations on algorithmic recommendation transparency reshape content distribution architectures. Creator economy clusters in Hangzhou and Shenzhen anchor live-stream commerce integration with visual content platforms.
Germany
EU AI Act transparency obligations force platforms serving European users to expose ranking logic and provide user-facing controls over recommendation feeds. GDPR constraints increase compliance engineering overhead for automated content curation systems. Berlin and Munich host engineering centers rebuilding content distribution around explainable automation rather than opaque engagement optimization.
Japan
Aging demographics and high smartphone penetration sustain premium subscription tolerance distinct from price-sensitive emerging markets. METI guidelines on AI ethics influence platform investment in facial recognition training data diversity. Tokyo and Osaka concentrate mobile-first creator tool development for domestic and export markets.
Photo Sharing Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated social platforms capturing network effects while standalone editing tools concentrate professional revenue. The vendor base organizes around three tiers: hyperscale ecosystem operators with cross-platform integration, commerce-linked visual discovery specialists, and professional workflow tool providers. Consolidation pressure intensifies as generative AI capabilities compress the traditional segmentation between amateur and professional feature tiers. Dominant competitive moves include strategic partnerships between platforms and travel brands for user-generated content licensing, plus geographic expansion through regional language interface localization.
Within the hyperscale ecosystem tier, Meta and Google exemplify platform operators leveraging integrated messaging and cloud infrastructure to sustain cross-platform engagement. Adobe occupies a position representing professional workflow consolidation, anchoring the premium editing tool segment through subscription-based creative suites. Pinterest exemplifies the commerce-linked discovery archetype, sitting within the visual search-to-purchase pathway specialization that remains underdeveloped across Asian markets outside China.
| Leading Market Players |
|---|
| Adobe |
| Meta |
| TikTok |
| Flickr |
| Amazon |
| Zenfolio |
| Apple |
| Others |
Value Chain & Pricing Dynamics
Travel and hospitality procurement teams now demand real-time content licensing with compressed negotiation cycles, forcing platforms to pre-negotiate bulk creator agreements and compress margin structures to secure preferred supplier status.
Pricing Analysis
Short lead-time premiums dominate enterprise licensing as Marriott and Hilton procurement teams pay 15-40% markups for same-day content clearance versus standard 30-day terms. Three-tier pricing structure across premium, standard, and economy levels separates white-glove managed services from self-serve API access and bulk archival tiers. Price differentiation hinges on exclusivity windows and geographic usage rights, with global campaign licenses commanding multiples of single-market rates. Pricing pressure stems from generative AI tools reducing dependency on authentic photography, compressing what brands will pay for licensed UGC. Individual users in India demonstrate highest price sensitivity, resisting recurring subscriptions while professional photographers in Japan tolerate premium tiers for RAW workflow integration.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, India, and Germany, with AWS, Azure, and Google Cloud anchoring global processing capacity. GPU clusters for AI moderation and generative tools draw from Taiwanese semiconductor foundries and South Korean memory fabricators, creating dependencies on East Asian component flows. Supply chain risk centers on energy price volatility in European data centers, where renewable transition costs transmit directly to storage pricing. Distribution runs through direct API integrations for enterprise clients, while mobile app stores capture consumer gateway control with 15-30% platform fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photo sharing market has become a vertical-integration race as platforms pursue backward integration into creator tooling and forward integration into commerce fulfillment to capture margin pools currently leaking to adjacent specialists.
For Market Incumbents: Deploy proprietary AI editing suites to lock professional photographers into captive workflows, reducing churn to standalone tools like Adobe Lightroom. Consolidate position by acquiring regional language interface specialists in tier-2 Indian cities before local competitors establish creator network effects. Generative AI substitution threatens licensed UGC revenue; platforms must embed automated creation tools to retain brand spend that would otherwise migrate to synthetic media providers. For New Entrants and Emerging Players: Launch via white-label enterprise deployments targeting mid-market hotel chains underserved by Meta and Google's self-serve advertising complexity. Underpenetrated rural India offers the most penetrable geography, where Jio's data penetration has created device-ready users lacking regional language platform options. Commerce-linked visual search in Southeast Asian markets outside China remains undeveloped, enabling Pinterest-style discovery-to-purchase pathways without incumbent saturation. For Investors and Strategic Acquirers: The window for entry favors professional workflow tool specialists with established photographer subscriber bases and RAW processing IP. Long-term viability hinges on platforms controlling the full creation-to-monetization stack rather than modular point solutions. Watch generative AI disclosure mandates in EU jurisdictions as an inflection indicator; compliance engineering overhead will favor well-capitalized incumbents and strain venture-backed challengers.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Content Moderation Scale-Up | Machine vision classifiers from Google and Meta enable automated policy enforcement reducing human review costs. |
| Regional Language Interface Expansion | Tamil, Telugu, and Marathi localization unlocks creator participation in India's tier-2 and tier-3 cities beyond metropolitan English-dominant users. |
| Commerce Integration Partnership | Pinterest-style visual search-to-purchase pathways capture affiliate revenue streams currently lost to external e-commerce platforms. |
| Creator Tool Acquisition | RAW processing and color grading IP from standalone editing specialists consolidates professional workflow control within integrated platforms. |
| Domestic Cloud Infrastructure Buildout | AWS, Azure, and Google Cloud data centers in Mumbai and Hyderabad reduce latency for India's surging Reels and Shorts consumption. |
Study Parameters
Document review covered SEC filings from hyperscaler cloud providers, App Annie mobile engagement metrics, and EU AI Act regulatory disclosures, complemented by interviews with platform product managers, travel brand marketing directors, and wedding photography studio owners in Delhi and Mumbai. Secondary validation drew from FTC consent order documentation, TRAI data localization guidance, and hyperscaler capex announcements. Bottom-up triangulation across creator economy transaction flows and top-down reconciliation against advertising spend migration patterns anchored market sizing.
Cross-referencing historical revenue per user trajectories against expert panel inputs on generative AI adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, user archetype, service model, and content format intensity. CAGRs were derived from S-curve penetration modeling for AI tooling and elasticity-adjusted pricing responses in price-sensitive emerging markets. Cloud infrastructure capacity expansion timelines and regulatory compliance cost buildups served as industry-specific forecast inputs.
Generative AI capability leaps, EU algorithmic transparency enforcement delays, and India's rural data tariff adjustments are the dominant revision risks that could compress or extend projected growth trajectories. Forecasts embed assumptions on creator participation rates and brand UGC licensing willingness that warrant sensitivity testing. A small set of named triggers—specifically EU AI Act implementation timing and Jio's pricing posture—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market