
 Gaming Controller Market | 2026-2036
Gaming Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Controller Market Analysis
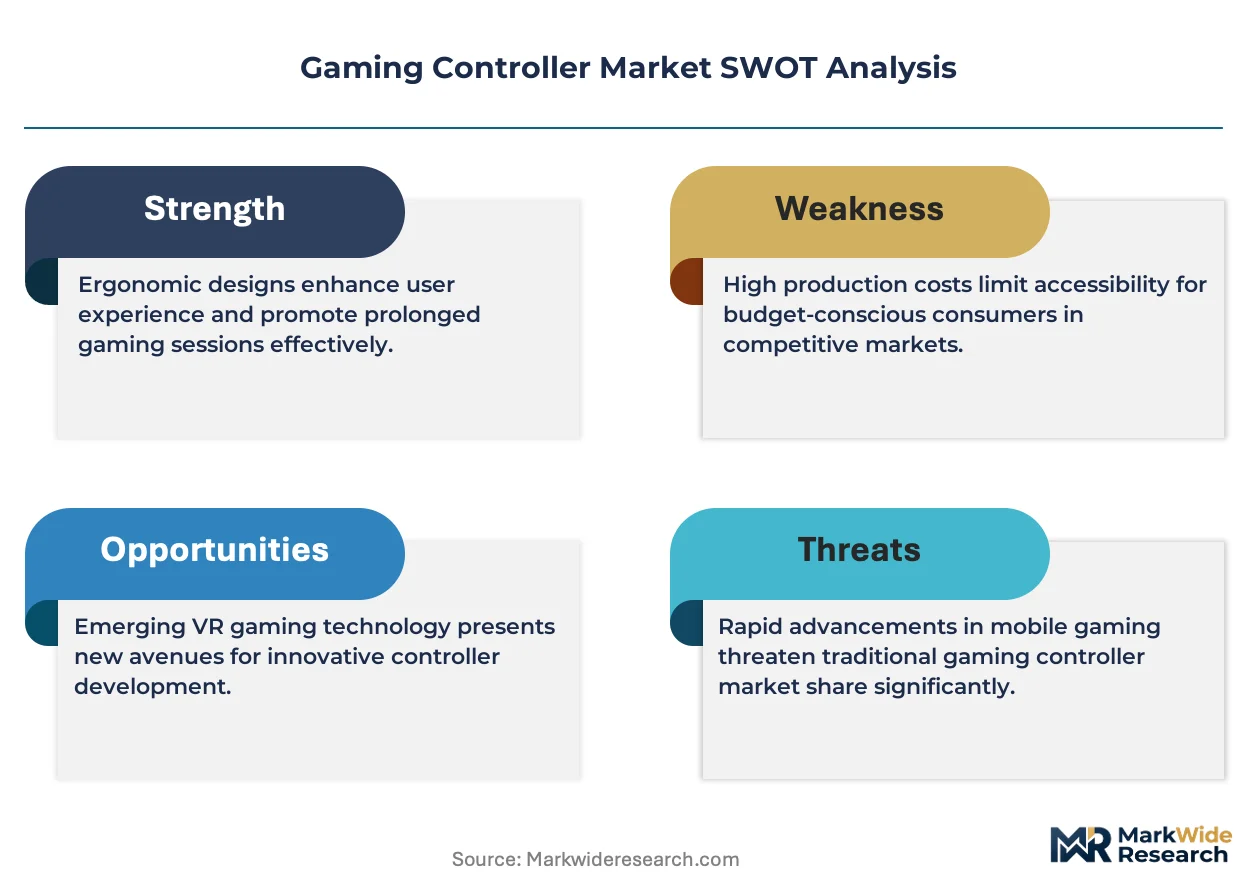
Aftermarket customization revenue is reshaping margin distribution across the gaming controller value chain. SCUF Gaming dominates the high-performance customization segment with patented paddle systems and configurable trigger stops. Razer leverages its Synapse software ecosystem to sustain recurring engagement beyond hardware sales. Microsoft anchors the mainstream wireless segment through deep platform integration with Xbox and Windows.
A gaming controller is a human interface device comprising analog sticks, pressure-sensitive triggers, gyroscopic sensors, and haptic actuators, engineered to translate physical inputs into digital commands for interactive software. Wireless controllers now lead unit economics as Bluetooth Low Energy and proprietary 2.4 GHz protocols eliminate latency gaps previously favoring wired alternatives. The adaptive controller segment shows the fastest structural expansion, driven by inclusive design mandates and hardware accessibility standards. Haptic feedback features command premium positioning as Sony's DualSense and comparable architectures demonstrate tangible gameplay differentiation.
The Federal Communications Commission governs radio frequency emissions for wireless controllers sold in the United States, while the EU REACH regulation restricts hazardous substances in plastics and solder compositions. The EU Ecodesign for Sustainable Products Regulation will soon mandate repairability documentation and spare parts availability, forcing redesigns of sealed-unit architectures. Stakeholders must monitor how right-to-repair legislation propagates across additional jurisdictions and whether haptic patent thickets consolidate around a few technology licensors.

Market Dynamics
Cloud gaming infrastructure is compressing hardware refresh cycles as professional esports leagues mandate sub-10ms latency standards, forcing controller manufacturers to prioritize radio frequency optimization over mechanical durability in design trade-offs.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates modular architectures and spare parts availability, accelerating repairable controller platform development ahead of compliance deadlines.
- Bluetooth Low Energy 5.3:Eliminates perceptible latency differentials versus wired connections, enabling wireless-first engineering decisions across mid-tier and premium product lines.
- Professional esports league standardization:Tournament-grade certification requirements create pull-through demand for identical consumer hardware, collapsing the gap between enthusiast and mass-market specifications.
Market Restraints
- Advanced haptic actuator supply concentration:Precision linear resonant actuators and voice coil motors depend on Korean and Japanese component specialists, exposing procurement to single-source fragility.
- Right-to-repair documentation burdens:Jurisdictions including France and US states mandate disassembly guides and parts availability, increasing compliance overhead for sealed-unit legacy designs.
- Smartphone touch interface substitution:Cloud gaming services on mobile devices reduce dedicated controller attachment rates among casual users, compressing addressable volume in entry segments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives attract controller assembly and component sourcing, creating cost-competitive export capacity for Asia-Pacific and Middle East markets.
- Adaptive controller accessibility mandates:WCAG 2.1 and national disability standards in Germany, Japan, and Australia require programmable input alternatives, expanding addressable user base beyond traditional gaming demographics.
- Direct-to-consumer subscription bundling:Hardware-as-a-service models paired with game library access reshape customer lifetime value calculations and reduce retail channel dependency.
Industry Challenges
- RF certification timeline compression:FCC and CE marking processes for proprietary 2.4 GHz protocols extend 14-22 weeks, delaying product launches behind software platform release schedules.
- Haptic feedback patent thickets:Sony, Immersion Corporation, and Texas Instruments hold overlapping intellectual property in force-feedback systems, complicating clean-sheet design for new entrants.
- Legacy platform backward compatibility:Maintaining firmware support for three console generations fragments engineering resources and complicates unified software stack development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Controller Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Controllers, Wireless Controllers, Adaptive Controllers, Mobile Controllers Platform: PC, PlayStation, Xbox, Nintendo End User: Casual Gamers, Professional Gamers, Streaming Enthusiasts, Game Developers Features: Multi-Device Compatibility, Haptic Feedback, Customizable Buttons, Ergonomic Design |
| Companies Covered | 8BitDo, Gulikit, GameSir, Turtle Beach, Astro Gaming, Razer, Flydigi, Microsoft, SCUF Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Controller Market Emerging Trajectories
Haptic fidelity is becoming the primary hardware differentiator as visual output standardizes across cloud streaming services, shifting competitive investment from display-adjacent features to tactile feedback engineering.
Programmable haptic actuators is digitizing the physical feedback layer of gaming interfaces. Sony's DualSense architecture demonstrates that variable resistance triggers and localized vibration patterns enable gameplay mechanics impossible with legacy rumble motors. First-party studios and AAA publishers are adopting these APIs within 18-24 month development cycles, compressing the window for third-party controller parity.
EU REACH substance restrictions are forcing solder and plastic reformulation across controller supply chains. The regulation's cadmium and phthalate limitations require validated alternative chemistries in circuit board assembly and shell molding, increasing material qualification costs. Manufacturers serving European distribution channels are consolidating supplier audits to preempt enforcement actions by ECHA.
Subscription bundling is displacing standalone hardware purchases in cloud gaming customer acquisition. Microsoft and NVIDIA prioritize controller-inclusive monthly plans over retail box sales, compressing unit margin realization into recurring revenue streams. This pattern concentrates in the United States and United Kingdom markets where game service penetration exceeds 40 percent of broadband households.
Gaming Controller Market Segmentation
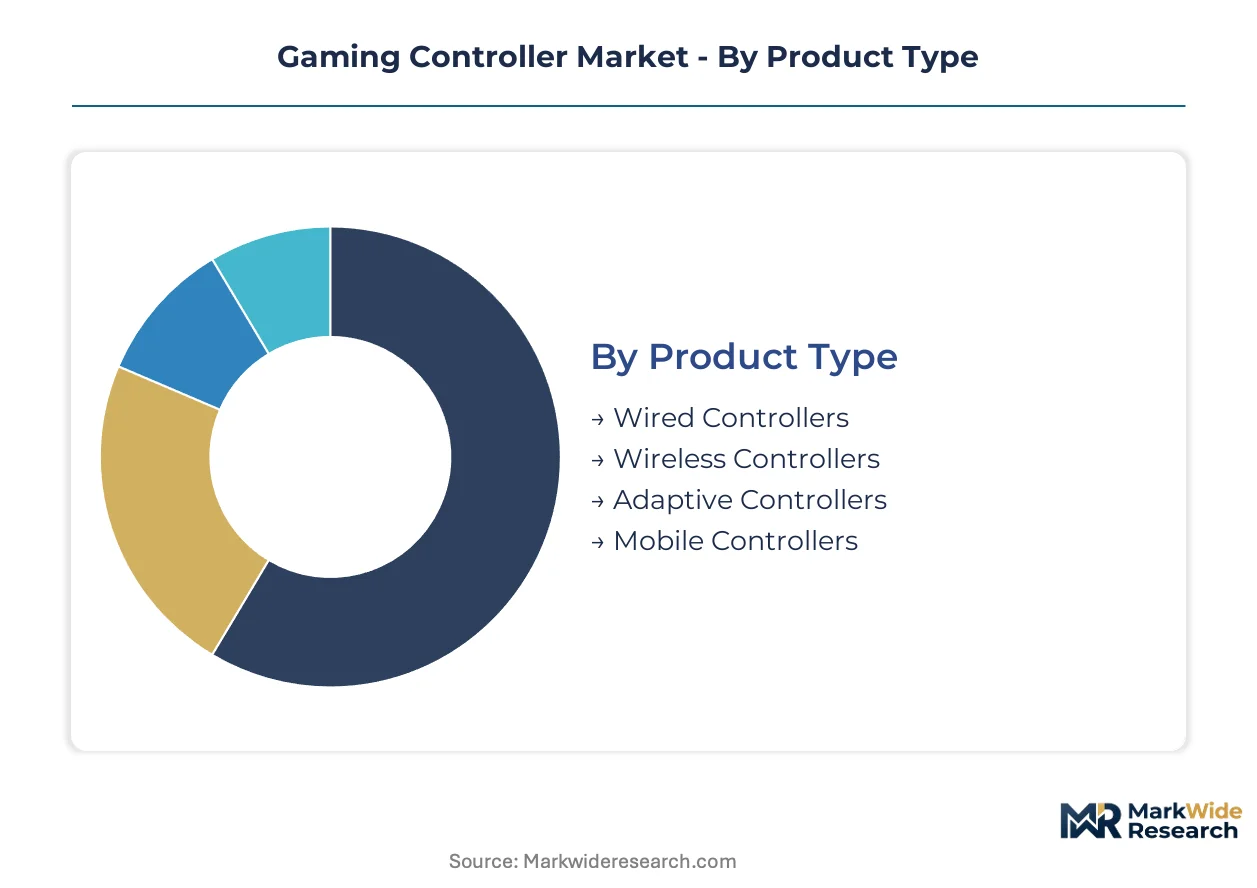
Controller segmentation reveals how hardware specialization fragments across platform ecosystems and user intensity levels. Manufacturers must balance universal compatibility against proprietary optimization to capture value across these divides.
Product Type:
Mature wireless architectures now dominate unit economics while emerging adaptive designs reshape accessibility mandates.
- Wired Controllers:USB-C and proprietary connector variants deliver sub-1ms input latency for tournament-grade certification. Demand concentrates in South Korea's PC bang culture and Brazilian LAN gaming centers where infrastructure cost sensitivity overrides wireless convenience premiums.
- Wireless Controllers:Bluetooth Low Energy 5.3 and proprietary 2.4 GHz protocols eliminate perceptible latency gaps versus wired alternatives. United States households with multiple console generations drive replacement cycles as cross-platform pairing becomes standard.
- Adaptive Controllers:Modular button arrays and switch interfaces serve motor-impaired users under WCAG 2.1 and German disability access mandates.
- Mobile Controllers:Collapsible clamp designs and cloud gaming-optimized latency profiles target smartphone-native users in India and Southeast Asia.
Wireless controllers retain volume leadership; adaptive controllers hold the steepest expansion curve.
Platform:
Application intensity varies dramatically across console loyalty versus open PC ecosystems.
- PC:Steam Input API compatibility and anti-cheat driver certification requirements fragment firmware development. Germany's competitive Counter-Strike community sustains premium peripheral spending for precision mouse-to-controller hybrid setups.
- PlayStation:DualSense haptic API integration creates first-party hardware lock-in for Sony-published titles. Japanese development studios prioritize adaptive trigger mechanics in exclusive franchises.
- Xbox:Windows-native driver stacks and Game Pass bundling concentrate demand in United States and United Kingdom subscription households.
- Nintendo:Motion control patents and Joy-Con form factor constraints limit third-party mechanical parity. Family-oriented demographics in France and Canada sustain colorful variant purchases.
PC platforms retain volume leadership; PlayStation holds the steepest expansion curve.
End User:
Customer type segmentation tracks engagement hours and hardware refresh frequency.
- Casual Gamers:Bundled controller satisfaction and smartphone touch substitution compress dedicated purchase intent. French and Italian households prioritize single-device versatility over specialized peripherals.
- Professional Gamers:Sub-10ms latency certification and paddle customization define procurement standards. Saudi Arabia's esports league investments and United States collegiate programs drive tournament-grade volume.
- Streaming Enthusiasts:Aesthetic customization and audience-visible RGB integration prioritize content creator appeal. United Kingdom Twitch and YouTube Gaming demographics sustain SCUF and Razer premium positioning.
- Game Developers:Debug controller variants with telemetry output and rapid firmware flashing support iterative input design. Japanese and Polish studio clusters maintain direct manufacturer relationships for prototype evaluation.
Casual gamers retain volume leadership; professional gamers hold the steepest expansion curve.
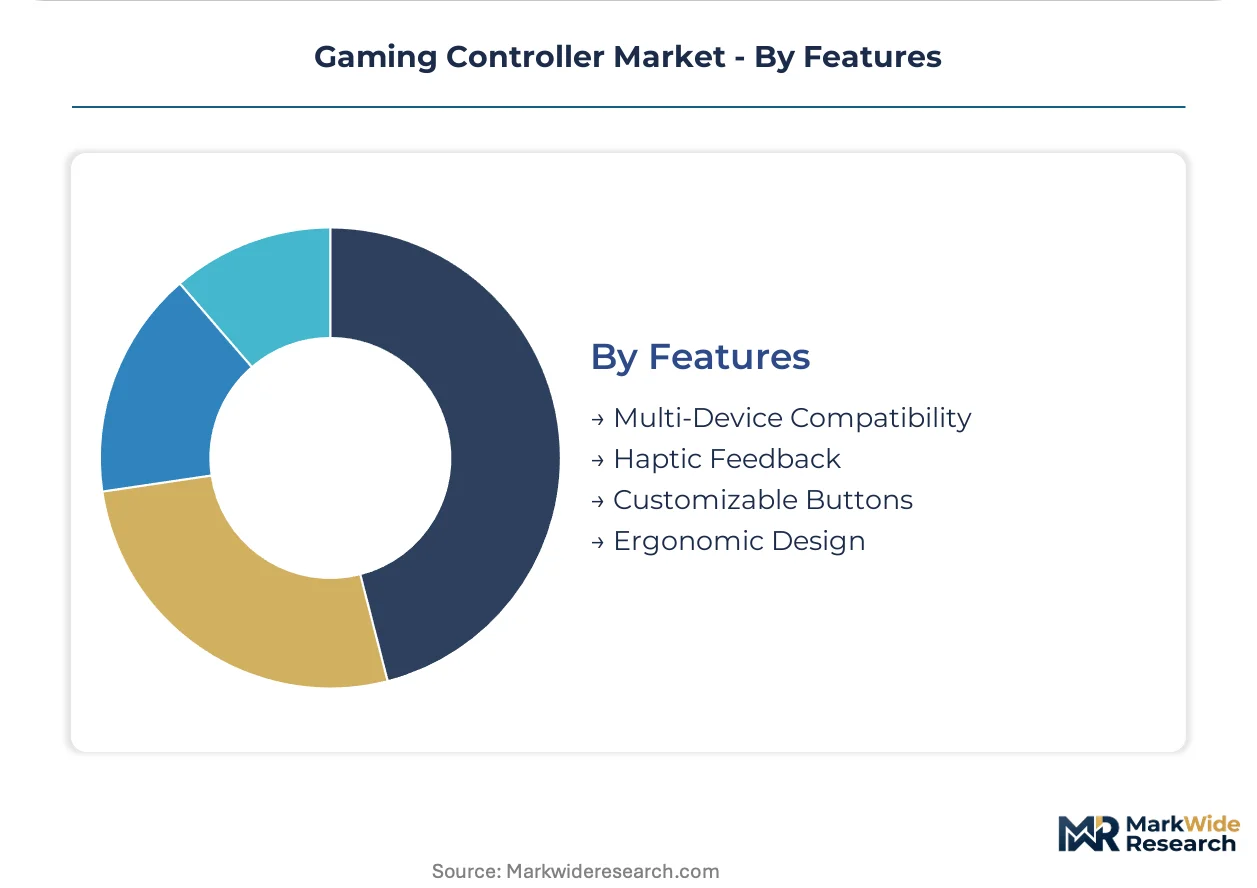
Features:
Feature bundling now determines margin tiering more than raw mechanical quality.
- Multi-Device Compatibility:Platform-agnostic pairing protocols and profile switching reduce clutter for multi-console households. Australian and Canadian consumers with split platform loyalty pay premiums for unified peripherals.
- Haptic Feedback:Variable resistance triggers and localized vibration patterns enable gameplay mechanics impossible with legacy rumble. Sony's DualSense patent licensing constrains third-party parity timelines.
- Customizable Buttons:Rear paddle configurations and trigger stop adjustments serve competitive shooter demographics. German and Dutch FPS communities drive aftermarket modification service revenue.
- Ergonomic Design:Anthropometric data from East Asian hand size distributions increasingly shapes shell molding for global products.
Multi-device compatibility retains volume leadership; haptic feedback holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States households absorb premium wireless peripherals with minimal resistance, while Indian and Southeast Asian buyers prioritize collapsible mobile controllers under $30. German and Japanese markets sit in the middle, demanding tournament-grade certification without flagship pricing.
United States
Console penetration exceeds 50 percent of broadband households, sustaining replacement cycles for multi-generational platform families. FCC radio frequency certification governs all 2.4 GHz and Bluetooth Low Energy device launches, extending lead times 14-22 weeks. Austin and Seattle host firmware development clusters for Game Pass-integrated controller ecosystems.
Germany
Competitive Counter-Strike communities drive precision peripheral spending for hybrid mouse-to-controller setups. REACH substance restrictions and impending Ecodesign repairability mandates force solder and plastic reformulation across supply chains. Berlin-Brandenburg concentrates accessibility engineering for WCAG 2.1-compliant adaptive controller variants.
Japan
DualSense haptic API integration creates hardware lock-in for Sony-published exclusive franchises. METI accessibility standards and national disability mandates expand programmable input alternatives beyond traditional gaming demographics. Tokyo and Osaka studio clusters maintain direct manufacturer relationships for debug controller prototypes with telemetry output.
India
Smartphone-native cloud gaming users in Mumbai and Bangalore favor collapsible clamp designs optimized for sub-100ms latency on 4G networks. PLI scheme production-linked incentives attract controller assembly and component sourcing for Asia-Pacific export capacity. BIS certification requirements for wireless devices extend domestic market entry timelines.
South Korea
PC bang culture sustains wired controller demand where infrastructure cost sensitivity overrides wireless convenience premiums. Precision linear resonant actuator supply concentrates among Korean component specialists, exposing procurement to single-source fragility. Seoul's esports league investments mandate sub-10ms latency standards that compress hardware refresh cycles.
Gaming Controller Market Vendor Landscape
Platform-integrated giants and modular customization specialists split the market into distinct value capture zones. First-party hardware manufacturers leverage proprietary API lock-in and subscription bundling to secure recurring engagement. Third-party peripheral makers compete on haptic differentiation, ergonomic specialization, and aftermarket modification services. Dominant competitive moves include M&A for haptic patent portfolios and strategic partnerships with cloud gaming infrastructure providers.
Within the customization-specialist tier, SCUF Gaming and 8BitDo exemplify divergent positioning strategies. SCUF anchors the high-performance aftermarket with patented paddle configurations and configurable trigger stops. 8BitDo occupies a position bridging retro form factor nostalgia with modern wireless protocol compatibility. Microsoft sits within the platform-integrated archetype, leveraging deep Xbox and Windows driver stack integration to sustain mainstream wireless segment leadership.
| Leading Market Players |
|---|
| 8BitDo |
| Gulikit |
| GameSir |
| Turtle Beach |
| Astro Gaming |
| Razer |
| Flydigi |
| Microsoft |
| SCUF Gaming |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Southeast Asian electronics assembly is compressing component pricing while simultaneously eroding supplier leverage, forcing controller manufacturers to absorb margin pressure or accelerate design differentiation to escape commodity tiers.
Pricing Analysis
Aftermarket customization revenue, spanning paddle configurations and trigger modifications, drives lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by haptic fidelity certification and tournament-grade latency validation. Pricing pressure stems from smartphone touch substitution in casual segments, compressing entry-tier viability. Professional gamers demonstrate lowest price sensitivity, absorbing premiums for sub-10ms certification and SCUF paddle systems.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Pegatron, and Jabil holding dominant controller assembly capacity across their Shenzhen and Vietnam facilities. Precision linear resonant actuators draw from Korean and Japanese component specialists, while Bluetooth Low Energy chipsets hinge on Taiwanese semiconductor foundries. Single-source vulnerability in haptic actuator supply exposes procurement to disruption. Distribution runs through Amazon and Best Buy retail channels, with direct-to-consumer subscription bundling displacing traditional wholesale in United States and United Kingdom markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gaming controller market is entering a cyclical recovery phase as cloud gaming infrastructure investments compress hardware refresh cycles and professional esports standardization mandates accelerate replacement demand.
For Market Incumbents: Pre-empt patent thickets consolidation by securing haptic feedback licensing from Immersion Corporation or Texas Instruments before exclusivity windows close. Accelerate modular platform architectures to satisfy EU Ecodesign repairability mandates ahead of compliance deadlines, converting regulatory burden into first-mover advantage against sealed-unit legacy competitors.
For New Entrants and Emerging Players: Build out adaptive controller accessibility capabilities to capture WCAG 2.1-mandated procurement in Germany, Japan, and Australia, where programmatic input alternatives remain undersupplied. Target India's PLI scheme production-linked incentives for cost-competitive export capacity serving Asia-Pacific and Middle East mobile controller demand.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated manufacturers with Game Pass-style subscription bundling, reshaping customer lifetime value calculations away from transactional hardware margins. Long-term viability favors acquisition targets with captive haptic actuator supply relationships or proprietary paddle system patents. Monitor FCC and CE marking timeline compression as inflection signal for launch velocity differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Patent Portfolio Acquisition | Secures licensing freedom for DualSense-comparable force-feedback architectures against Sony and Immersion Corporation thickets. |
| Modular Platform Architecture Development | Anticipates EU Ecodesign spare parts mandates while enabling repairable controller premium positioning. |
| Cloud Gaming Infrastructure Partnership | Integrates latency-optimized controllers with NVIDIA GeForce Now and Xbox Cloud Gaming service bundles. |
| Adaptive Controller Accessibility Expansion | Captures WCAG 2.1-mandated procurement in German and Japanese disability access markets. |
| Direct-to-Consumer Subscription Bundling | Converts transactional hardware margins into recurring revenue streams through Game Pass-integrated controller ecosystems. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with controller hardware engineering directors, esports league procurement officers, FCC certification consultants, and cloud gaming platform product managers; and secondary validation against FCC equipment authorization databases, EU ECHA REACH substance restriction filings, SEC 10-K disclosures from Microsoft and Razer, and customs trade records for Bluetooth module imports. Bottom-up unit shipment modeling triangulated against top-down consumer spending surveys across the analysis window.
Forecast inputs considered wireless protocol adoption curves, professional esports league standardization timelines, and regulatory compliance phase-ins across segmentation dimensions including product type, platform ecosystem, end-user intensity, and feature bundling. CAGRs were derived from fitted growth curves anchored to historical replacement cycle data and projected cloud gaming penetration rates. Haptic API adoption velocity and right-to-repair legislation propagation served as industry-specific forecast modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated giants or haptic patent consolidators would shift outcomes beyond modeled ranges. Quarterly review of FCC certification backlog durations and EU Ecodesign implementing act releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Board Games Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Racing Games Market
Gaming
Gaming Chair Market
Gaming
Gaming As a Service Market
Gaming
United Kingdom Online Gambling Market
Gaming
Arcade Cabinet Market
Gaming
Global Tarot Cards Market
Gaming
Europe Video Game Software Market
Gaming
GCC Gaming Headsets Market
Gaming
Online Casino Market
Gaming
Metaverse in Gaming Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Gaming Software Market
Gaming
China in-Game Advertising Market
Gaming
Game Engine Management Market