
 China Casino Tourism Market | 2026-2036
China Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
China Casino Tourism Market Outlook
Integrated resort distribution channels are rewriting how casino tourism reaches Chinese consumers. Wynn Macau Ltd leverages its premium hotel inventory to capture high-spending visitors. Sands China Ltd anchors its competitive position through massive convention and exhibition capacity. Galaxy Entertainment Group Ltd differentiates via family-oriented non-gaming attractions that extend visitor dwell time.
China casino tourism encompasses travel for legalized gambling and associated hospitality services within approved jurisdictions, primarily Macau as a special administrative region operating under distinct gaming concession frameworks separate from mainland China's gambling prohibitions. The sector generates revenue through table game commissions, slot machine yields, and bundled resort amenities serving both leisure and business travelers. VIP gamblers represent the highest-yield customer segment, though domestic tourists now form the fastest-growing visitor category as mainland travel restrictions ease and middle-class discretionary spending rises. Table games command the largest share of gaming revenue, while slot machines attract casual players seeking lower-stakes entertainment.
SAMR oversees mainland advertising and consumer protection standards affecting cross-border casino marketing, while Macau's Gaming Inspection and Coordination Bureau regulates concessionaire operations, licensing terms, and anti-money-laundering protocols. China's central bank monitors payment flows through UnionPay and digital yuan channels, constraining capital movement to gaming venues. Stakeholders must track Hainan's regulatory pilot programs and any gaming liberalization signals that could reshape China's casino tourism geography.
Market Dynamics
Integrated resort operators are pivoting toward non-gaming revenue streams as China's central bank tightens capital flow monitoring through UnionPay and digital yuan channels, compressing traditional VIP gaming yields while elevating hospitality and entertainment monetization.
Growth Catalysts
- Hainan Free-Trade Port Framework:Pilot policies loosening cross-border travel constraints are redirecting mainland leisure demand toward approved gaming jurisdictions, expanding the addressable visitor base.
- Domestic Middle-Class Expansion:Rising discretionary spending among tier-one and tier-two city households is fueling demand for premium hospitality experiences bundled with entertainment offerings.
- Convention Infrastructure:Massive exhibition capacity anchors business traveler segments, extending average dwell time and per-visitor spend beyond pure gaming activity.
Market Restraints
- Capital Movement Constraints:SAMR oversight of mainland advertising and China's central bank monitoring of payment flows create friction in cross-border casino marketing and fund transfers.
- Geographic Supply Concentration:Cotai Strip infrastructure in Macau dominates premium capacity, limiting operator diversification options and creating vulnerability to localized demand shocks.
- Technical Surveillance Limitations:Anti-money-laundering protocol complexity slows customer onboarding and increases compliance operational overhead for concessionaires.
Strategic Opportunities
- Greater Bay Area Integration:Infrastructure connectivity between Guangdong, Hong Kong, and Macau is compressing travel friction and expanding same-day and overnight visitor catchment zones.
- Family-Oriented Attraction Development:Theme parks, retail, and entertainment complexes capture spending from non-gaming visitors, diversifying revenue per available room.
- Digital Yuan Settlement Pilots:Regulatory experimentation with central bank digital currency channels offers potential for traceable, compliant payment flows that satisfy both operators and financial regulators.
Industry Challenges
- Concession Renewal Timeline Compression:Licensing framework uncertainty surrounding Macau gaming concession terms creates strategic planning paralysis and capex deployment hesitation among operators.
- Specialized Compliance Talent Scarcity: Expertise in anti-money-laundering protocols, cross-border financial surveillance, and dual-jurisdiction regulatory navigation commands premium compensation and retention difficulty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Casino Tourism Market |
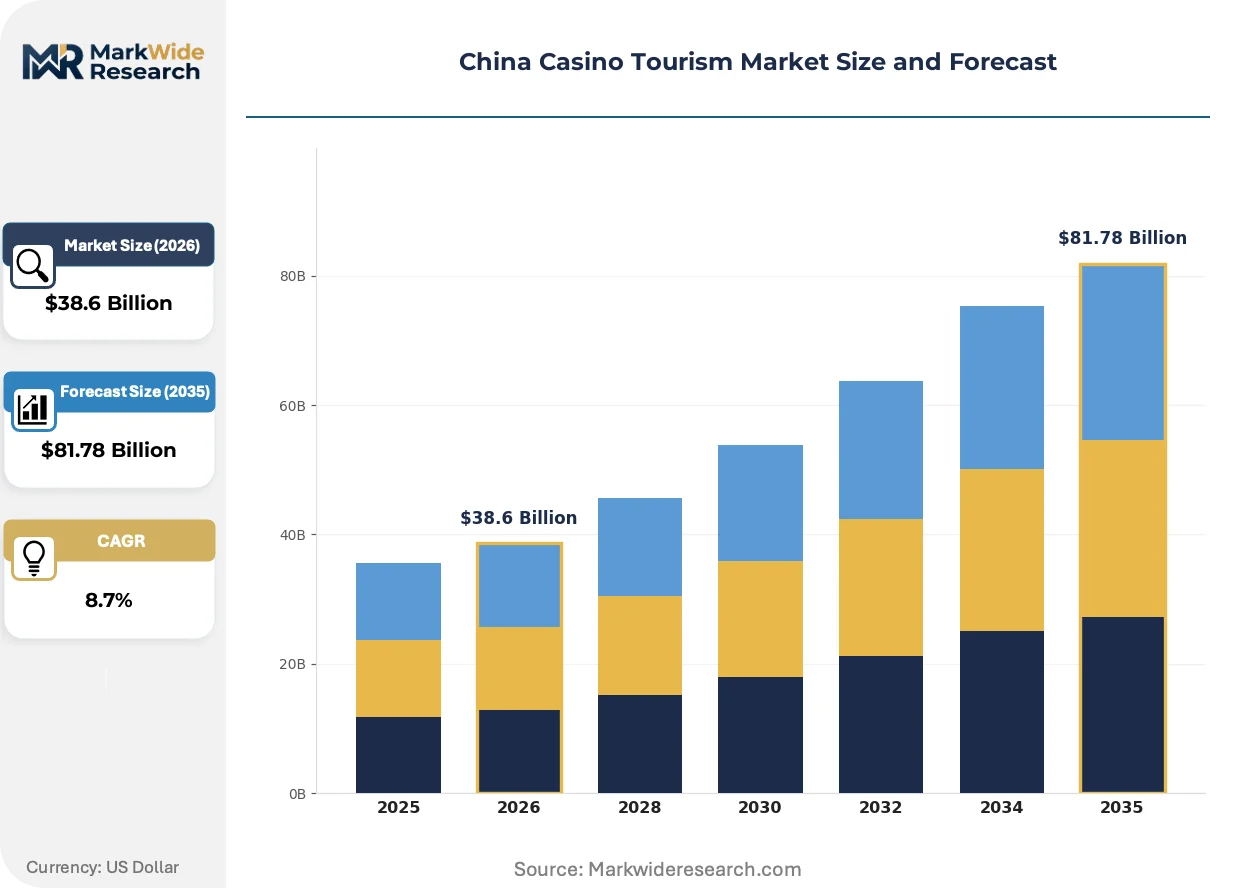
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Domestic Tourists, International Visitors, VIP Gamblers, Casual Players Gaming Type: Slot Machines, Table Games, Poker Rooms, Sports Betting Service Type: Hotel Packages, Dining Experiences, Entertainment Shows, Spa Services Payment Method: Cash, Credit Card, E-Wallets, Casino Chips |
| Companies Covered | Wynn Macau Ltd, SJM Holdings Ltd, Galaxy Entertainment Group Ltd, Melco International Development Ltd, Studio City International Holdings Ltd, Sands China Ltd, Melco Resorts & Entertainment Ltd, MGM Resorts International, MGM China Holdings Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Casino Tourism Market Strategic Shifts
Technology integration and regulatory adaptation are converging to reshape how casino tourism operators capture and retain Chinese visitors, with digital infrastructure and policy experimentation driving competitive differentiation.
Facial recognition and behavioral analytics systems are rendering obsolete traditional player tracking and loyalty program architectures. Integrated resort operators deploy computer vision across gaming floors and hospitality touchpoints to personalize service delivery in real time. VIP hosts and mass-market floor staff now rely on algorithmic prompts rather than manual observation to anticipate guest preferences.
Macau's Gaming Inspection and Coordination Bureau is tightening concessionaire accountability through enhanced reporting mandates on source-of-funds verification. Operators must now demonstrate granular documentation of high-value player capital origins, elevating compliance infrastructure to board-level strategic priority. Premium gaming segments face the steepest operational adjustment costs as regulatory scrutiny intensifies.
Visitor booking patterns are fragmenting across direct-to-consumer digital channels, compressing traditional travel agency intermediation. Younger mainland tourists research and reserve integrated resort packages through short-video platforms and super-app ecosystems rather than established tour operators. This shift is most pronounced in Guangdong province, where digital-native consumers bypass legacy distribution relationships entirely.
China Casino Tourism Market Segmentation
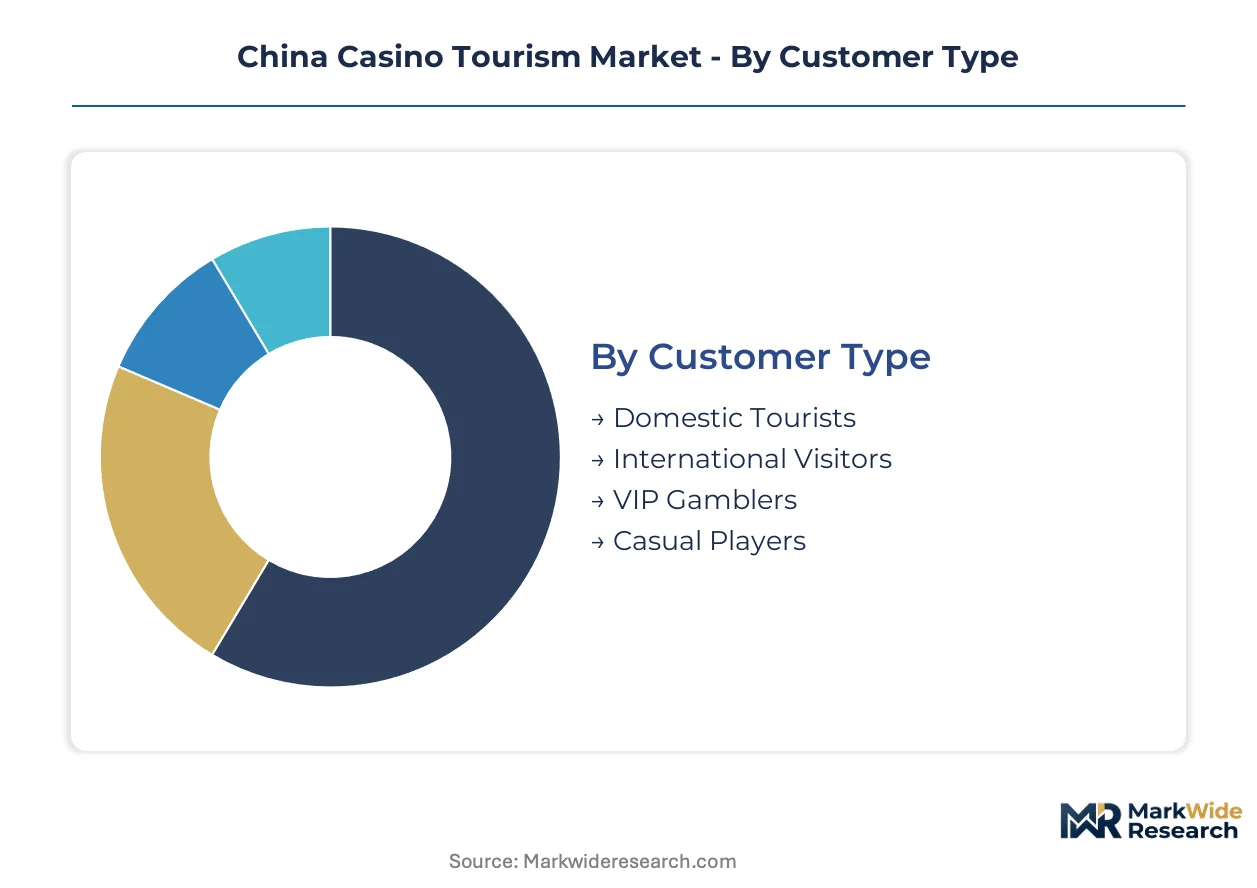
Casino tourism operators in China segment visitors to optimize yield management and tailor hospitality programming. Distinct customer profiles, gaming preferences, and service expectations require differentiated operational approaches across Macau's integrated resorts.
Customer Type:
Visitor economics and spending patterns vary sharply across traveler categories, with concessionaire revenue models calibrated to distinct behavioral profiles.
- Domestic Tourists:Mainland travelers from Guangdong, Fujian, and Hunan provinces constitute the volume base, with middle-class households from Shenzhen and Guangzhou driving weekend visitation. These visitors concentrate spending on bundled hotel-entertainment packages rather than pure gaming activity, responding to Hainan free-trade port marketing that redirects leisure demand toward Macau.
- VIP Gamblers:High-net-worth individuals command premium table minimums and private salon access, though UnionPay transaction monitoring and source-of-funds verification have compressed this segment's historical yield dominance. Concessionaires now deploy facial recognition systems to sustain personalized service delivery amid tightened compliance protocols.
- International Visitors:Southeast Asian and Northeast Asian travelers leverage visa facilitation agreements, with Korean and Japanese tourists showing preference for Cotai Strip properties with direct ferry connectivity.
- Casual Players:Lower-stakes participants seek entertainment value through slot machines and electronic gaming terminals, generating stable floor traffic during off-peak periods.
VIP Gamblers command the established base. The steepest expansion runs through Domestic Tourists.
Gaming Type:
Gaming floor configuration reflects revenue yield hierarchy and regulatory compliance burden across distinct product categories.
- Table Games:Baccarat dominates Macau's gaming revenue architecture, with VIP and mass-market pits configured to separate player tiers. Anti-money-laundering documentation requirements from the Gaming Inspection and Coordination Bureau have lengthened onboarding procedures for high-limit participants.
- Slot Machines:Electronic gaming terminals attract casual players and family-group visitors, with themed machines and progressive jackpots extending dwell time among non-core gamblers. Cotai Strip operators position slot zones adjacent to retail and dining precincts to capture incidental play.
- Poker Rooms:Tournament and cash game formats serve expatriate communities and skilled player segments, operating under distinct regulatory supervision with lower revenue contribution than house-banked alternatives.
- Sports Betting:Wagering on football and basketball competitions operates through licensed intermediaries, with mobile platform integration constrained by mainland China's gambling prohibitions and cross-border marketing restrictions under SAMR oversight.
Table Games command the established base. The steepest expansion runs through Slot Machines.
Service Type:
Ancillary revenue streams now determine integrated resort profitability as gaming yields face regulatory compression.
- Hotel Packages:Premium suite inventory at Wynn Macau and Galaxy Entertainment properties anchors per-visitor spend, with tiered loyalty programs incentivizing extended stays. Weekend occupancy rates in Cotai Strip towers reflect pricing power during peak mainland travel periods.
- Entertainment Shows:Resident productions and visiting performer engagements differentiate properties competing for Guangdong province's discretionary leisure budget. Family-oriented spectacles extend visitor dwell time beyond gaming floors.
- Dining Experiences:Celebrity chef restaurants and regional Chinese cuisine outlets capture spending from food-focused travelers, with Michelin-recognized venues serving as destination anchors independent of gaming activity.
- Spa Services:Wellness and recovery amenities serve VIP segments and convention delegates, generating recurring revenue from multi-day visitors.
Hotel Packages command the established base. The steepest expansion runs through Entertainment Shows.
Payment Method:
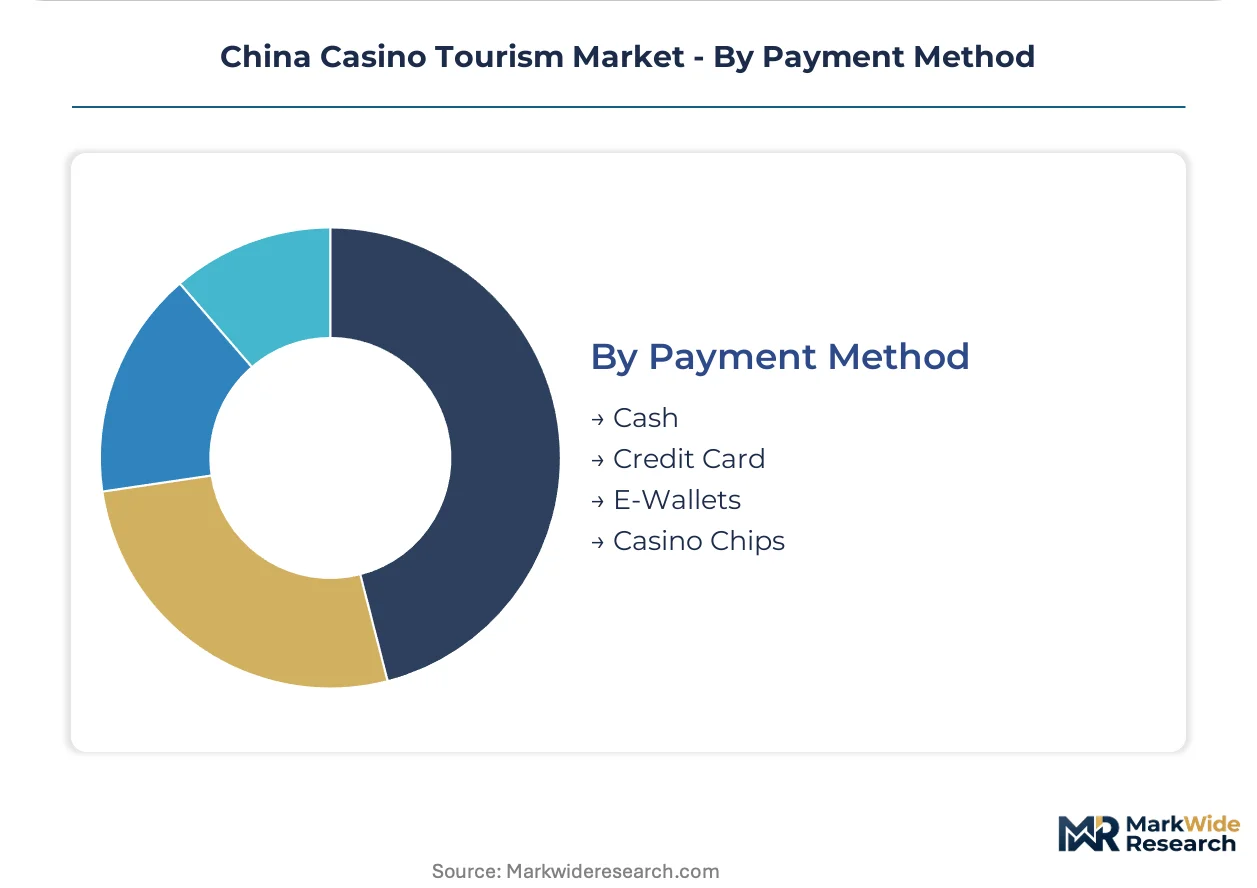
Transaction infrastructure shapes customer acquisition and regulatory risk exposure across Macau's concessionaire ecosystem.
- Casino Chips:Physical tokens remain the dominant gaming floor medium, with redemption protocols subject to Gaming Inspection and Coordination Bureau surveillance mandates and cross-border currency declaration requirements.
- E-Wallets:Alipay and WeChat Pay integration at retail and hospitality touchpoints serves mainland visitors accustomed to cashless transactions, though gaming floor usage remains restricted by China's central bank capital flow monitoring.
- Cash:Physical currency handling persists for unbanked visitors and privacy-seeking segments, with large transactions triggering enhanced due diligence under anti-money-laundering frameworks.
- Credit Card:UnionPay and international card networks facilitate hotel and retail spending, with gaming advances prohibited under mainland regulatory constraints.
Casino Chips command the established base. The steepest expansion runs through E-Wallets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Macau's Gaming Inspection and Coordination Bureau anchors the regulatory framework governing casino tourism across the Greater Bay Area, with SAMR oversight extending to mainland marketing channels and cross-border promotional activities.
Macau Special Administrative Region
Cotai Strip integrated resorts draw weekend visitation from Guangdong province's middle-class households seeking bundled entertainment packages. The Gaming Inspection and Coordination Bureau enforces enhanced source-of-funds verification for VIP segments, lengthening onboarding procedures while tightening compliance accountability. Galaxy Entertainment Group Ltd and Wynn Macau Ltd anchor premium capacity in Taipa, with convention infrastructure extending business traveler dwell time.
Guangdong Province
Shenzhen and Guangzhou metropolitan areas generate the fastest-growing domestic tourist segment for Macau-bound casino tourism. Hainan free-trade port pilot policies redirect leisure demand through streamlined cross-border travel frameworks. Zhuhai's Gongbei port and Hong Kong-Zhuhai-Macau Bridge compression reduce friction for same-day and overnight visitors.
Hainan Province
Sanya and Haikou are piloting duty-free retail expansion and entertainment tourism under the State Council's free-trade port framework. SAMR monitors advertising standards affecting cross-border casino marketing to mainland visitors. The island's regulatory experimentation signals potential gaming liberalization that could reshape China's casino tourism geography.
Hong Kong Special Administrative Region
Ferry terminals and airport connectivity anchor international visitor throughput to Macau's gaming jurisdictions. The city's financial infrastructure facilitates UnionPay and digital yuan payment channel monitoring by China's central bank. Tsim Sha Tsui and Central districts concentrate travel agency intermediation for integrated resort packages.
Fujian Province
Xiamen and Fuzhou households contribute to weekend visitation patterns alongside Guangdong source markets. Provincial tourism promotion policies align with national frameworks easing cross-border leisure travel constraints. Quanzhou's cultural tourism infrastructure complements casino tourism demand through multi-destination itinerary packaging.
China Casino Tourism Market Competitive Environment
Integrated resort operators and concessionaire holding companies split the market between hospitality-anchored diversified revenue models and gaming-centric yield optimization. The vendor base concentrates around six licensed concessionaires operating under Macau's renewed gaming framework. Three strategic archetypes dominate: premium hospitality flagships, mass-market entertainment complexes, and hybrid convention-gaming destinations. Competitive moves center on non-gaming attraction development and loyalty program digitization rather than capacity expansion.
Among concessionaire holding companies, Wynn Macau Ltd and Galaxy Entertainment Group Ltd exemplify the premium hospitality archetype through Cotai Strip positioning. Sands China Ltd anchors the mass-market entertainment complex model with substantial convention infrastructure. MGM China Holdings Ltd occupies a hybrid position bridging premium gaming and entertainment destination development.
| Leading Market Players |
|---|
| Wynn Macau Ltd |
| SJM Holdings Ltd |
| Galaxy Entertainment Group Ltd |
| Melco International Development Ltd |
| Studio City International Holdings Ltd |
| Sands China Ltd |
| Melco Resorts & Entertainment Ltd |
| MGM Resorts International |
| MGM China Holdings Ltd |
| Others |
Value Chain & Pricing Dynamics
The Hong Kong-Zhuhai-Macau Bridge freight corridor compresses logistics costs for Cotai Strip integrated resorts while amplifying pricing power concentration among six licensed concessionaires. Supply-side infrastructure scarcity in premium hospitality feeds downstream price differentiation between mass-market entertainment packages and VIP-configured experiences.
Pricing Analysis
The customization-premium spread separates standard hotel-entertainment bundles from configured-to-order VIP salon experiences with private gaming pits and dedicated host services. Three-tier pricing structure across premium, standard, and economy levels reflects brand positioning, loyalty tier status, and bundled amenity depth. Cost compression in mass-market segments is intensifying because digital-native tourists from Guangdong province comparison-shop through short-video platforms. Domestic middle-class households exhibit highest price sensitivity, while high-net-worth VIP gamblers demonstrate lowest elasticity due to privacy and service customization requirements.
Supply Chain Analysis
Upstream feedstock for integrated resort development draws from construction materials suppliers in mainland China, hospitality equipment manufacturers in Italy and Germany, and gaming technology providers in the United States and Japan. Critical dependencies include premium suite furnishings, casino surveillance systems, and entertainment production hardware. Single-source vulnerability concentrates in facial recognition and behavioral analytics software from approved vendors under Gaming Inspection and Coordination Bureau compliance mandates. Distribution runs through concessionaire procurement divisions with direct vendor relationships, bypassing traditional hospitality supply intermediaries for core gaming and surveillance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in cross-jurisdiction compliance expertise—spanning SAMR advertising oversight, Macau's source-of-funds verification protocols, and central bank payment flow monitoring—constrains operator expansion and elevates strategic talent acquisition to board-level priority.
For Market Incumbents: Build regulatory compliance depth as a defensible moat through in-house development of anti-money-laundering documentation systems and Gaming Inspection and Coordination Bureau relationship infrastructure. Invest in loyalty program digitization to counter travel agency disintermediation by short-video platform booking channels. Prioritize backward integration into entertainment production capabilities to reduce reliance on third-party resident show operators. For New Entrants and Emerging Players: Establish a beachhead in family-oriented non-gaming attractions where Galaxy Entertainment Group Ltd has demonstrated yield expansion through theme park and retail complex development. Target Hainan free-trade port pilot zones for hospitality service contracts ahead of potential gaming liberalization signals. Deploy direct-to-consumer digital marketing through WeChat Pay and Alipay ecosystems to bypass established tour operator intermediation. For Investors and Strategic Acquirers: Mid-scale integrated resort operators with underutilized convention infrastructure represent compelling acquisition targets for yield optimization through business traveler segment development. Long-term viability hinges on regulatory relationship durability across concession renewal timelines and Hainan policy evolution. Monitor digital yuan settlement pilot expansion as an inflection indicator for compliant payment flow architecture investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Gaming Attraction Development | Family-oriented theme parks and retail complexes extend visitor dwell time beyond gaming floors at Cotai Strip properties. |
| Digital Loyalty Platform Integration | Algorithmic personalization through facial recognition systems replaces manual player tracking at Wynn Macau and Sands China Ltd. |
| Convention Infrastructure Expansion | Massive exhibition capacity anchors business traveler segments with higher per-visitor spend than pure gaming visitors. |
| Compliance Technology Investment | Source-of-funds verification systems satisfy Gaming Inspection and Coordination Bureau mandates while reducing onboarding friction. |
| Direct-to-Consumer Channel Buildout | Short-video platform booking integration captures Guangdong province tourists bypassing legacy travel agency distribution. |
Study Parameters
The analysis maps integrated resort revenue streams, gaming concession frameworks, and cross-border tourism policy clusters, each validated through casino operations executives, hospitality procurement directors, and regulatory compliance officers. Primary interviews with SAMR policy specialists and Macau Gaming Inspection and Coordination Bureau consultants combined with secondary validation from State Council tourism promotion filings, central bank payment flow disclosures, and Greater Bay Area infrastructure development records. Bottom-up visitor segmentation triangulated against top-down concessionaire revenue reporting produces integrated market estimates.
Assumption sets held Hainan free-trade port policy evolution and digital yuan pilot expansion as variable inputs while fixing mainland gambling prohibition frameworks and Macau concession licensing architecture as boundary conditions. Segmentation dimensions modeled include customer type, gaming product category, service bundling configuration, and payment method across the projection horizon. CAGRs derive from visitor volume elasticity to cross-border travel facilitation, per-visitor spend progression by loyalty tier, and non-gaming revenue yield expansion. Forecast inputs incorporate convention infrastructure capacity utilization and short-video platform booking channel penetration.
Stress conditions across UnionPay transaction monitoring intensity, VIP segment regulatory scrutiny, and Hainan gaming liberalization timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about domestic middle-class discretionary spending trajectory and infrastructure connectivity completion schedules. Cross-checking against China Tourism Academy visitor sentiment indices and Macau Statistics and Census Service arrival data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
FPS Game Market
Gaming
Mobile Game Controller Market
Gaming
VR Gaming Controller Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Shooter Game Market
Gaming
PC Games Market
Gaming
Online Casual Games Market
Gaming
Lottery Market
Gaming
Gaming Accessories Market
Gaming
China Gaming Headsets Market
Gaming
Gaming Software Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Serious Games Market
Gaming
Video Game Software Market
Gaming
Africa Gaming Market