
 Cloud Gaming Market | 2026-2036
Cloud Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Gaming Market Analysis
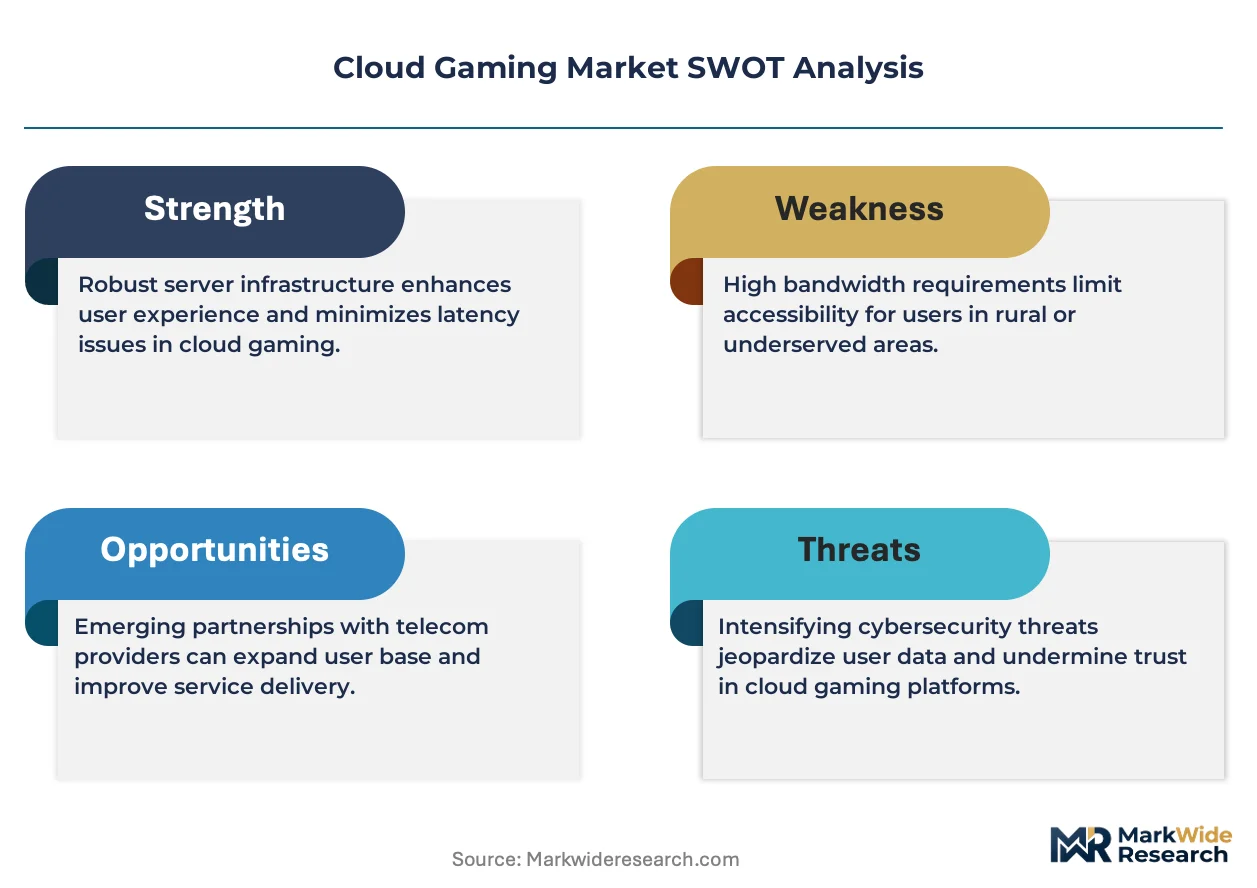
Subscription-based access to GPU-rendered game streams is pivoting how publishers monetize interactive entertainment. Microsoft Corporation leverages its Azure data center footprint to reduce latency for Xbox Cloud Gaming users across North American and European nodes. NVIDIA Corporation anchors its competitive position through GeForce NOW's integration with existing PC game libraries, sustaining developer relationships without exclusive content requirements.
Cloud gaming delivers interactive software execution via remote server-side rendering, with video frames compressed through H.265 or AV1 codecs and streamed to client devices at 60-120 frames per second depending on network conditions. Subscription-based services currently dominate revenue as consumers prefer predictable monthly costs over hardware ownership. Mobile platforms represent the fastest-expanding addressable base, though smart TV integration is emerging as a margin-rich channel for family-oriented casual gamer segments.
FCC net neutrality rulings in the United States shape how internet service providers can prioritize gaming traffic, while GDPR and the EU AI Act constrain biometric data collection from player behavior analytics in Europe. China's MIIT enforces domestic cloud infrastructure requirements that limit foreign platform operators' direct market access. Stakeholders must monitor evolving data localization mandates and spectrum allocation policies that determine edge computing deployment economics.
Market Dynamics
Edge computing infrastructure deployment by mobile network operators is compressing latency thresholds for interactive streaming, while GDPR and the EU AI Act impose new data sovereignty constraints on platform architecture decisions.
Growth Catalysts
- 5G Edge Computing:Mobile network operators in South Korea and Japan are deploying multi-access edge computing nodes to reduce round-trip latency for real-time gameplay rendering.
- FCC Net Neutrality Framework:Traffic prioritization rulings in the United States enable internet service providers to guarantee quality-of-service tiers for interactive streaming applications.
- Fiber Broadband Penetration:Government-backed infrastructure investments in South Korea create dense addressable markets for premium subscription tiers requiring sub-20ms latency.
Market Restraints
- Data Center Energy Costs:GPU-intensive server farms face electricity price volatility that compresses margins for infrastructure operators in European markets.
- Codec Licensing Complexity:H.265 and AV1 patent pools create royalty stacking that elevates per-stream costs for independent platform operators.
- MIIT Localization Mandates:China's Ministry of Industry and Information Technology requires domestic cloud infrastructure, blocking direct foreign platform access without local joint ventures.
Strategic Opportunities
- Smart TV Integration:Family-oriented casual segments on Samsung and LG television platforms represent underexploited distribution channels with higher average revenue per user.
- Cross-Platform Library Access:Integration with existing PC and console game libraries eliminates content acquisition costs while accelerating subscriber acquisition velocity.
- GDPR-Compliant Analytics:Privacy-preserving player behavior modeling creates differentiation for European operators facing biometric data restrictions under the EU AI Act.
Industry Challenges
- Codec Optimization Talent:Shortage of engineers specializing in real-time video compression and adaptive bitrate algorithms limits streaming quality at scale.
- Legacy Console Certification:First-party platform holders impose technical compliance timelines that delay cloud versions of licensed titles by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Gaming Market |
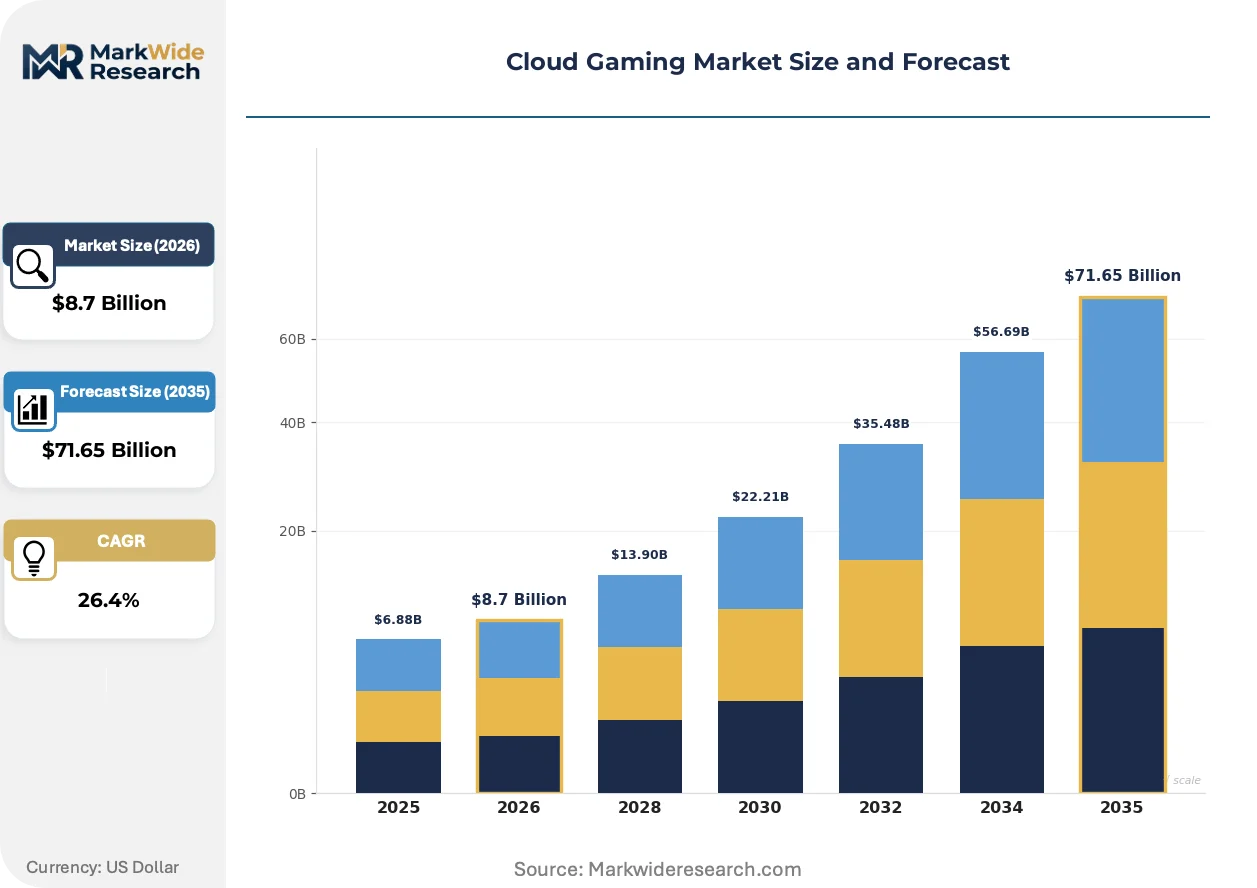
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, One-Time Purchase, Free-to-Play, Advertising-Based Platform: PC, Console, Mobile, Smart TVs Technology: Virtual Reality, Augmented Reality, Streaming, Downloadable Content Customer Type: Casual Gamers, Hardcore Gamers, Families, Professional Players |
| Companies Covered | Microsoft Corporation, NVIDIA Corporation, Sony Group Corporation, Amazon Web Services, Inc., Tencent Holdings Limited, Google LLC, Intel Corporation, Electronic Arts, Inc., Ubitus K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Gaming Market Emerging Trajectories
Interactive entertainment delivery is fragmenting across device categories while compression protocols and regulatory frameworks force architectural reinvention.
AV1 royalty-free video encoding is overtaking H.265 across major platform operators due to reduced licensing friction and superior compression efficiency at low bitrates. Smart TV manufacturers and mobile chipset vendors are embedding hardware decode support at accelerating pace. This codec transition is overtaking incumbent streaming infrastructure investments and compressing cost structures for high-frame-rate gameplay delivery.
The EU AI Act's biometric data restrictions are constraining player emotion recognition and behavioral prediction systems deployed in European markets. Platform operators must reengineer analytics pipelines to exclude facial and physiological data collection. Cloud gaming services targeting Germany and France are responding by pivoting toward aggregate session metrics rather than individual player profiling.
Subscription fatigue among entertainment consumers is fragmenting commitment patterns across multiple concurrent services. Casual gamers in South Korea and Japan are adopting shorter-term passes and event-based access models alongside traditional monthly subscriptions. This behavioral rotation is most visible in mobile-first markets where platform operators now bundle cloud access with telecommunications tariffs.
Cloud Gaming Market Segmentation
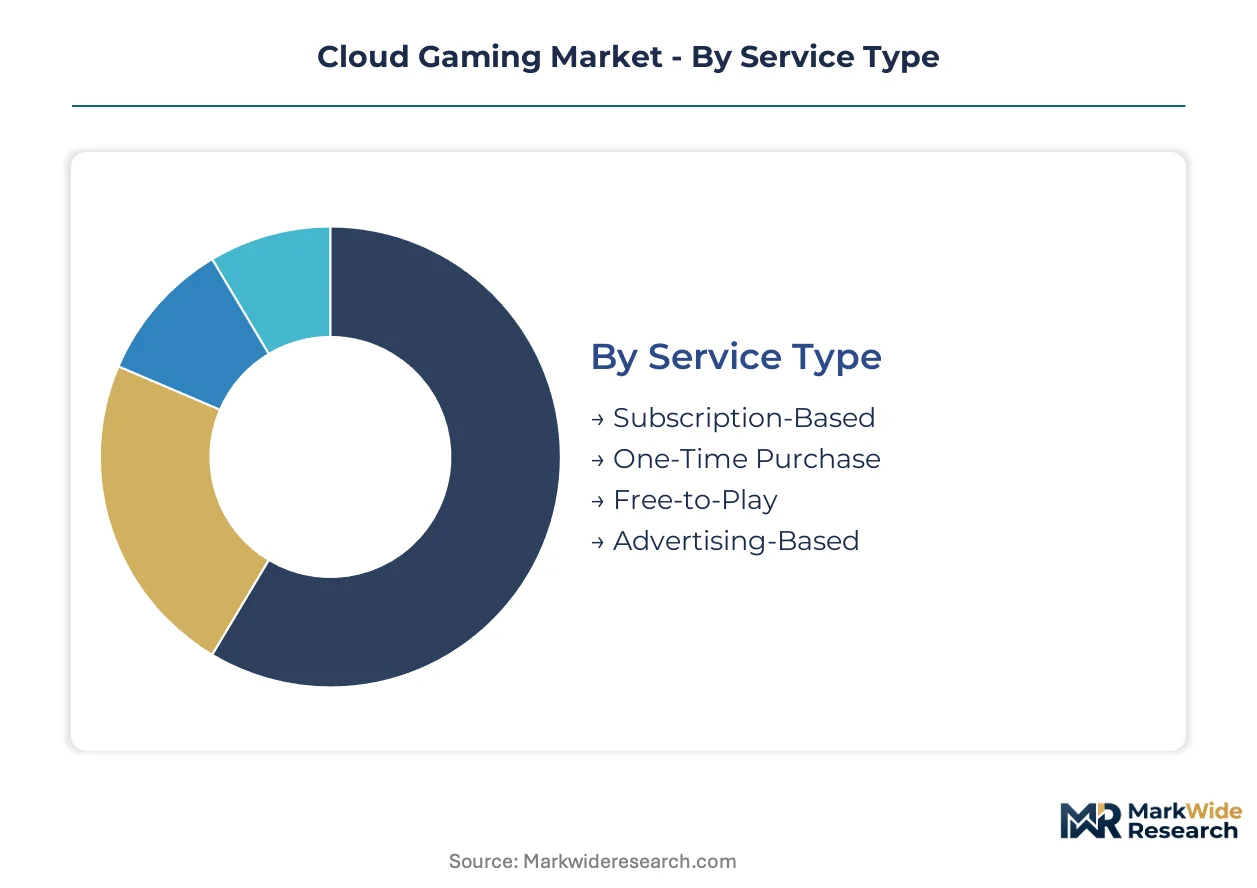
Cloud gaming monetization and delivery architectures fragment sharply across service models and device categories. Platform operators configure infrastructure investments and content licensing strategies differently for each segment combination.
Service Type:
GDPR and the EU AI Act impose distinct consent and data minimization burdens on subscription services versus ad-supported models, with biometric analytics restrictions hitting advertising-based streams hardest.
- Subscription-Based:Recurring monthly or annual fees grant unlimited access to curated game libraries hosted on GPU server clusters. South Korean operators bundle these tariffs with 5G mobile plans, driving penetration in fiber-dense metropolitan markets.
- One-Time Purchase:Individual title licensing without recurring commitment, typically for premium AAA releases where players retain perpetual streaming rights. Demand concentrates among hardcore segments seeking specific franchise releases without hardware investment.
- Free-to-Play:Zero-entry-cost access generating revenue through in-game microtransactions and cosmetic item sales. China's MIIT localization mandates force foreign operators into domestic joint venture structures to deploy this model legally.
- Advertising-Based:Interstitial or display ad insertion subsidizing gameplay access for price-sensitive casual users. GDPR consent frameworks and biometric data restrictions under the EU AI Act complicate behavioral targeting and ad personalization in European deployments.
Leading the category by volume: Subscription-Based. Growing fastest: Free-to-Play.
Platform:
Latency tolerance and codec efficiency requirements vary dramatically across device categories, dictating edge computing node placement and adaptive bitrate algorithm design.
- PC:Browser-based or native application streaming to Windows, macOS, and Linux systems with keyboard-mouse or controller input. Hardcore gamers in Germany and France drive demand for 120fps streams with sub-20ms latency on fiber connections.
- Console:Cloud versions of titles running on Xbox PlayStation or Nintendo hardware, often as companion services to physical disc libraries. Legacy certification timelines from first-party platform holders delay cloud releases by 6-18 months.
- Mobile:iOS and Android streaming via touch controls or Bluetooth peripherals, representing the fastest-expanding addressable base. 5G multi-access edge computing deployments in Japan and South Korea enable premium subscription uptake on smartphones.
- Smart TVs:Embedded applications on Samsung, LG, and Sony television platforms targeting family-oriented casual segments. Higher average revenue per user emerges from shared household sessions and reduced price sensitivity versus mobile users.
Dominant by installed base: Mobile. Steepest expansion trajectory: Smart TVs.
Technology:
Rendering pipeline architecture diverges between server-side execution and client-side augmentation, with regulatory frameworks constraining biometric data collection in immersive formats.
- Virtual Reality:Cloud-rendered stereoscopic video streams delivered to standalone headsets, requiring ultra-low latency to prevent motion sickness. GDPR and EU AI Act biometric restrictions limit facial tracking and physiological response analytics in European deployments.
- Augmented Reality:Overlay graphics composited onto real-world camera feeds, demanding precise spatial mapping and low-latency pose estimation. Use cases remain nascent outside enterprise training and location-based entertainment.
- Streaming:Dominant delivery mechanism compressing server-rendered frames through H.265 or AV1 codecs for real-time network transmission. AV1 hardware decode support is accelerating across mobile chipsets and smart TV silicon.
- Downloadable Content:Hybrid models caching executable assets locally while streaming dynamic elements, reducing bandwidth dependency for narrative-driven single-player experiences.
Core volume driver: Streaming. Emerging fastest: Virtual Reality.
Customer Type:
Session duration, content preferences, and price sensitivity cluster distinctly across gamer psychographics, shaping platform marketing spend and content acquisition priorities.
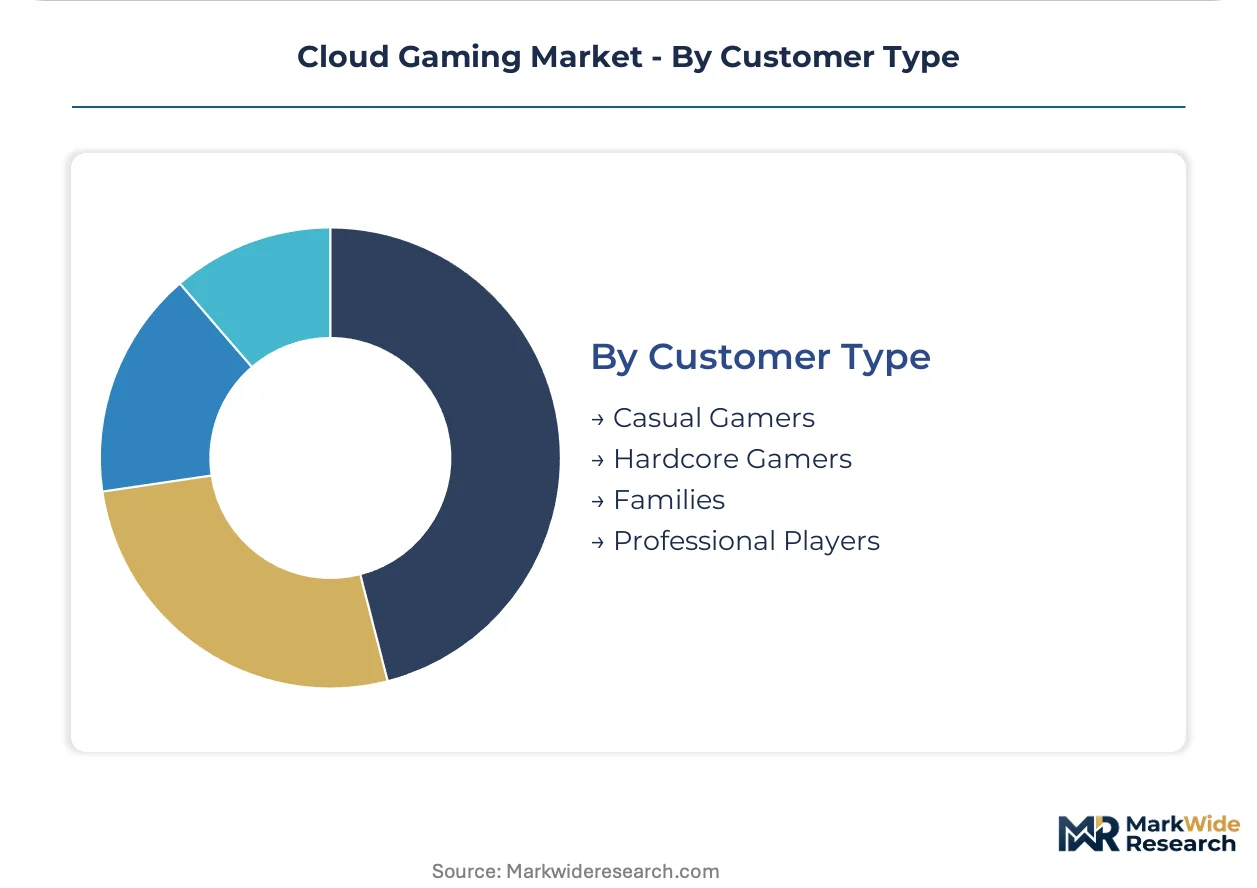
- Casual Gamers:Short-session mobile players prioritizing puzzle, simulation, and hyper-casual titles with minimal learning curves. South Korean telecommunications bundles capture this segment through zero-rating and tariff integration.
- Hardcore Gamers:Extended-session enthusiasts demanding competitive multiplayer, AAA narrative content, and esports-grade latency performance. Fiber broadband penetration in Japanese urban centers supports premium tier subscription density.
- Families:Multi-user households seeking parental controls, content filtering, and shared library access across age-appropriate titles. Smart TV integration targets this segment with living-room convenience and simplified controller schemes.
- Professional Players:Esports competitors and content creators requiring broadcast-quality streams, tournament-grade latency, and spectator mode functionality. Regulatory constraints on biometric data collection limit performance analytics deployment in EU markets.
Largest addressable base: Casual Gamers. Gaining share fastest: Families.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors cloud gaming infrastructure investment through government-backed 5G edge computing corridors. The city hosts dense fiber broadband penetration that enables sub-20ms latency thresholds for premium subscription services.
United States
FCC net neutrality rulings shape traffic prioritization frameworks for internet service providers delivering interactive streams. Data center operators in Northern Virginia and Dallas-Fort Worth concentrate GPU server deployments to serve East and Central time zones. Microsoft Corporation leverages Azure nodes across these clusters to reduce latency for Xbox Cloud Gaming subscribers.
South Korea
Government infrastructure programs drive fiber broadband penetration rates exceeding 95 percent in metropolitan corridors. Korea Communications Commission spectrum allocations support multi-access edge computing deployments by mobile network operators. Seoul and Busan host the densest concentrations of 5G base stations enabling real-time gameplay rendering on smartphones.
Japan
METI digital infrastructure initiatives accelerate edge computing node placement in Tokyo and Osaka metropolitan zones. Ministry of Internal Affairs and Communications 5G spectrum licenses enable low-latency streaming partnerships between telecommunications carriers and platform operators. Chubu region manufacturing clusters supply specialized cooling systems for GPU-intensive server farms.
Germany
GDPR and the EU AI Act impose biometric data restrictions on player behavior analytics deployed by platform operators. Frankfurt and Munich data center hubs concentrate cloud gaming infrastructure serving Central European latency requirements. BNetzA telecommunications regulations govern quality-of-service guarantees for interactive streaming applications.
China
MIIT domestic cloud infrastructure mandates require foreign platform operators to establish local joint ventures for market access. Shanghai and Shenzhen technology zones host domestic hyperscaler data centers rendering games for local distribution. SAMR antitrust oversight shapes partnership structures between international publishers and domestic telecommunications carriers.
Cloud Gaming Market Vendor Landscape
Capital-heavy infrastructure operators compete with asset-light platform designers for subscriber acquisition and content licensing leverage. The market structures around three tiers: hyperscale cloud providers owning data center footprints, semiconductor vendors controlling GPU supply chains, and pure-play streaming services aggregating third-party libraries. Strategic archetypes include vertical integrators combining silicon and infrastructure, platform-agnostic aggregators licensing existing game libraries, and telecommunications bundlers integrating cloud access with mobile tariffs. Dominant competitive moves encompass edge computing capacity expansion in metropolitan corridors and cross-platform library partnerships eliminating exclusive content requirements.
Within the hyperscale infrastructure tier, Microsoft Corporation and Amazon Web Services occupy positions defined by global data center node density. NVIDIA Corporation exemplifies the silicon-to-platform archetype through GeForce NOW's library integration model. Tencent Holdings Limited anchors the telecommunications bundling strategy through domestic market scale and carrier partnership structures in China.
| Leading Market Players |
|---|
| Microsoft Corporation |
| NVIDIA Corporation |
| Sony Group Corporation |
| Amazon Web Services, Inc. |
| Tencent Holdings Limited |
| Google LLC |
| Intel Corporation |
| Electronic Arts, Inc. |
| Ubitus K.K. |
| Others |
Supply Flow & Price Mechanics
Subscription fatigue among casual gamers is forcing platform operators toward shorter-term pass models and telecommunications bundle partnerships, compressing recurring revenue predictability and pressuring infrastructure providers to optimize GPU server utilization rates.
Pricing Analysis
Margin tightening in premium subscription tiers reflects escalating electricity costs for GPU-intensive server farms in European markets. Three-tier pricing structure across premium, standard, and economy levels dominates service configurations, with differentiation driven by resolution caps and session duration limits. Casual mobile gamers in South Korea exhibit highest price sensitivity, while family-oriented smart TV subscribers demonstrate lowest sensitivity due to shared household cost amortization.
Supply Chain Analysis
China's MIIT domestic cloud infrastructure mandates are reshaping sourcing patterns for foreign platform operators seeking market access. GPU supply concentrates in Taiwan, South Korea, and the United States, with server assembly drawing from specialized cooling system manufacturers in Japan's Chubu region. Single-source vulnerability in advanced semiconductor lithography equipment creates structural risk. Distribution runs through hyperscale data center operators and telecommunications carrier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming infrastructure is transitioning from H.265 codec dominance toward AV1 royalty-free encoding, displacing legacy licensing structures and compressing per-stream delivery costs.
For Market Incumbents: Anchor competitive position through multi-access edge computing capacity expansion in fiber-dense metropolitan corridors. Defend against emerging platform-agnostic aggregators by deepening exclusive content partnerships with AAA publishers. Prioritize certification investment for smart TV silicon integration to capture family-oriented casual segments. For New Entrants and Emerging Players: AV1-native streaming infrastructure offers a technology-first wedge into price-sensitive casual gamer segments underserved by incumbent codec transition timelines. Target South Korean and Japanese telecommunications bundle channels as the most penetrable distribution pathway. Pursue white-label platform licensing to regional carriers lacking in-house cloud gaming engineering capabilities. For Investors and Strategic Acquirers: The window for entry favors asset-light platform designers with proprietary adaptive bitrate algorithms over capital-heavy data center operators. Long-term viability hinges on cross-platform library integration capabilities rather than exclusive content ownership. Watch for AV1 hardware decode penetration rates in mid-range mobile chipsets as the critical inflection signal for infrastructure cost structure compression.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Expansion | Multi-access edge computing deployment in Seoul and Tokyo reduces latency below 20ms thresholds. |
| Cross-Platform Library Integration | Existing PC and console game library access eliminates content acquisition costs for subscriber acquisition. |
| Smart TV Application Certification | Samsung and LG embedded application partnerships unlock family-oriented casual gamer segments. |
| Telecommunications Bundle Partnership | South Korean 5G tariff integration drives premium subscription density in fiber-dense markets. |
| AV1 Codec Transition | Royalty-free encoding reduces per-stream licensing friction versus H.265 patent pool obligations. |
Methodological Framework
Multi-period observation of GPU server deployment capex, codec adoption curves, and 5G spectrum allocation patterns anchored the trend analysis, supplemented by interviews with platform engineering executives, telecommunications carrier partnership leads, cloud infrastructure procurement officers, and regulatory affairs specialists at major operators. Secondary validation drew from hyperscaler capital expenditure disclosures, FCC spectrum auction records, MIIT infrastructure filings, and EMA regulatory guidance documents. Bottom-up subscriber modeling and top-down market sizing triangulated volume estimates.
Input-output matrices mapped service type, platform category, and customer psychographic dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against infrastructure capacity buildout timelines. Forecast inputs incorporated edge computing node density trajectories, fiber broadband penetration curves, and GDPR compliance cost assumptions.
Several conditions sit outside the modeled scope, including unannounced semiconductor export restrictions, abrupt spectrum policy reversals, and breakthrough client-side rendering technologies. Forecasts reflect documented assumptions about codec transition timelines and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Game Controller Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
North America Gaming Market
Gaming
H5 Games Market
Gaming
Game API Market
Gaming
Social Gaming Market
Gaming
Gaming Peripheral Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
3D Gaming Technology Market
Gaming
Flat Gaming Monitors Market
Gaming
Serious Games Market
Gaming
Southeast Asia Gaming Market
Gaming
Germany Gaming Headset Market
Gaming
AAA Games Market
Gaming
India Gaming Market
Gaming
Console Games Market