
 Global Trading Card Games Market | 2026-2036
Global Trading Card Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trading Card Games Market Outlook
Mass-market retail partnerships and direct-to-collector online drops are reshaping how trading card games reach buyers. The Pokémon Company leverages its vertically integrated animation-studio-publisher-retail structure to sustain dominant brand recognition across generations. Konami Holdings Corporation anchors its Yu-Gi-Oh! franchise through rigorous organized play infrastructure and tournament licensing. Bandai differentiates via cross-media IP exploitation, binding card releases to anime broadcast schedules and toy lines.
Trading card games are competitive tabletop or digital products comprising randomized or fixed assortments of illustrated cards with defined gameplay mechanics, printed on cardstock typically measuring 63 by 88 millimeters and governed by formal rule sets for head-to-head or multiplayer contest. Their primary commercial purpose is to generate recurring revenue through expandable card pools, organized competitive play, and secondary-market collectibility. Standard cards and booster packs command the highest volume throughput, while collector cards capture concentrated margin pools from graded-specimen resale. Digital and hybrid formats are expanding fastest as publishers integrate blockchain-adjacent ownership verification and mobile companion apps, though physical retains the core profit engine.
FDA guidelines on youth-targeted advertising influence how publishers label randomized pack contents in the United States, while EU consumer protection frameworks under the European Commission constrain loot-box-style digital mechanics that parallel physical booster randomization. Japan's Consumer Affairs Agency monitors gacha-derived monetization structures that increasingly blur into digital card game economies. Stakeholders must track evolving gambling-classification precedents across Germany's KBA-influenced youth protection standards and emerging state-level legislation in the United States, as regulatory reclassification would force fundamental restructuring of both physical pack randomization and digital card acquisition mechanics.
Market Dynamics
Organized play infrastructure and authenticated resale channels are concentrating competitive advantage among publishers with vertically integrated tournament ecosystems, while EU packaging waste directives force rapid material transitions across card stock supply chains.
Growth Catalysts
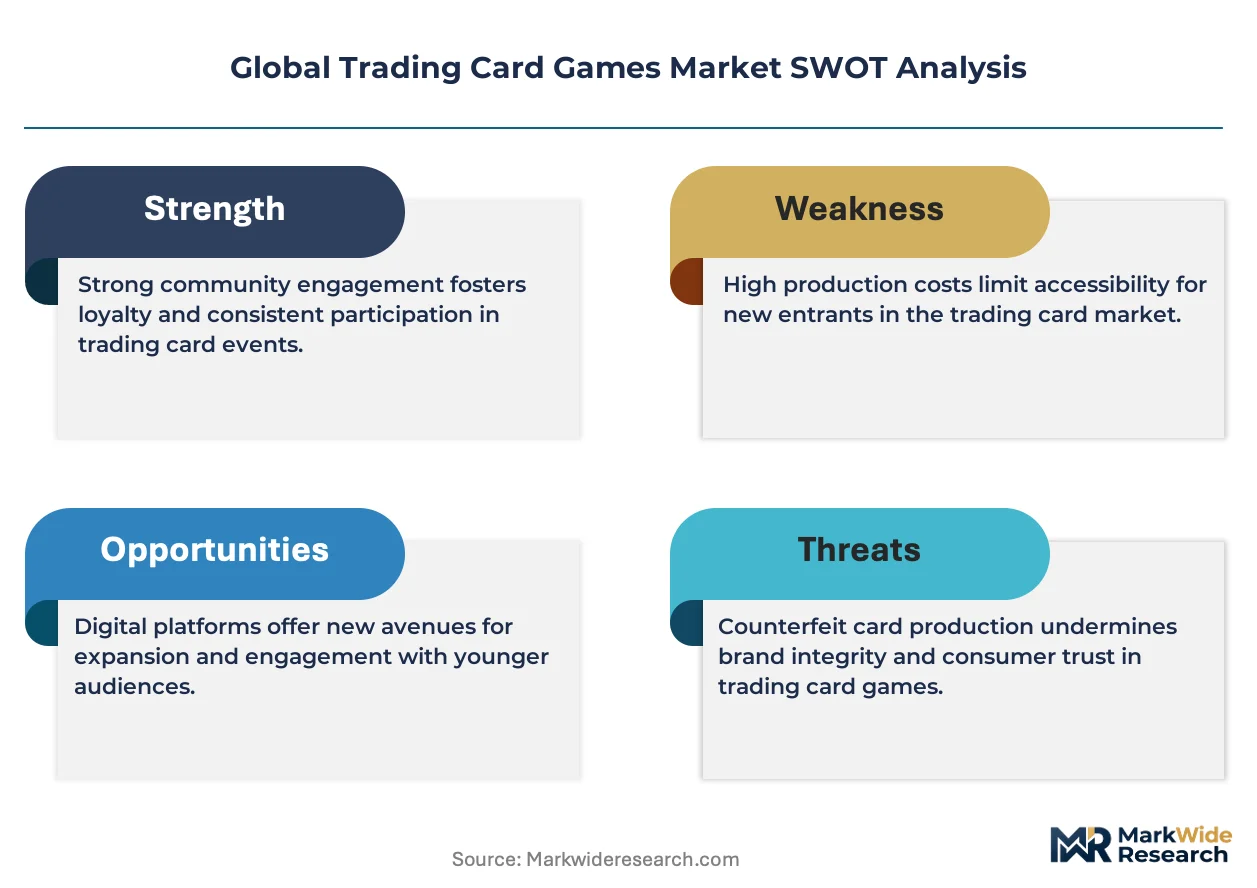
- EU Green Deal packaging directives:Regulatory pressure toward recyclable card stock and reduced plastic wrap is accelerating sustainable material R&D investment across European manufacturing facilities.
- Esports venue integration:Hobby shops and dedicated tournament halls in Japan, the United States, and South Korea are expanding organized play capacity to capture recurring event revenue.
- Blockchain-adjacent ownership verification:Digital companion apps with provable scarcity mechanics are bridging physical collector markets to mobile-native buyer cohorts.
Market Restraints
- Pulp and specialty paper cost volatility:Fluctuating input prices for coated card stock compress margin predictability for high-volume standard product lines.
- Gambling-classification precedent risk:Germany's KBA-influenced youth protection standards and emerging US state legislation threaten booster pack randomization mechanics with forced restructuring.
- Secondary market authentication bottlenecks:Concentrated grading service capacity in the United States creates supply constraints for collector-grade product liquidity.
Strategic Opportunities
- India's underpenetrated organized play infrastructure:Nascent hobby shop networks and limited tournament circuits present first-mover expansion potential for established publishers.
- Cross-media IP synchronization:Binding card release schedules to anime broadcast calendars and toy line launches creates multi-touch revenue capture from single content investments.
- Direct-to-collector online drops:Bypassing traditional retail allocation constraints allows margin retention and scarcity-controlled release cadence.
Industry Challenges
- Regulatory compliance timeline compression:Japan's Consumer Affairs Agency monitoring of gacha-derived monetization requires rapid adaptation of digital card economy structures to avoid reclassification.
- Legacy organized play infrastructure integration:Tournament licensing systems and judge certification programs face friction when merging with emerging digital hybrid formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trading Card Games Market |
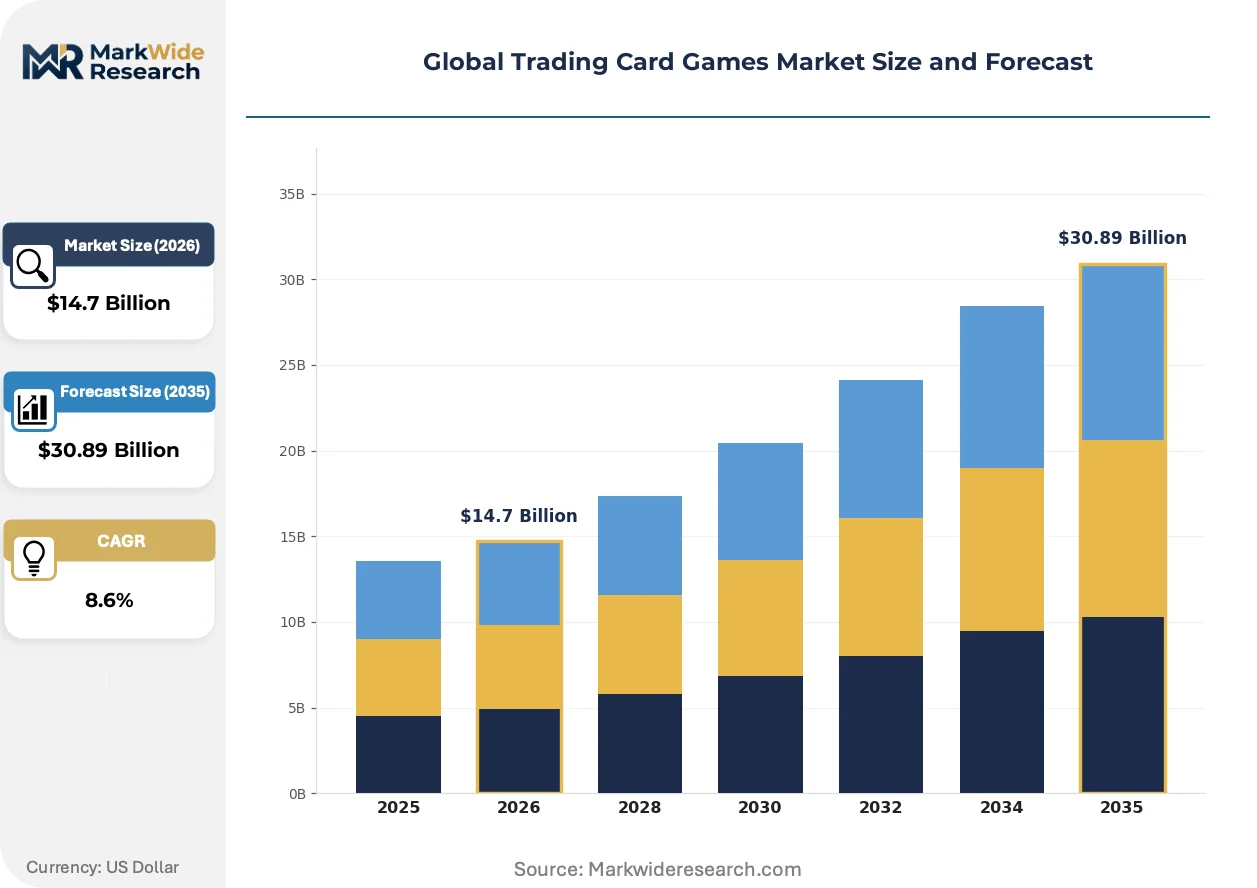
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cards, Collector Cards, Booster Packs, Starter Decks Game Format: Physical, Digital, Hybrid, Online Player Demographics: Children, Teens, Adults, Families Distribution Channel: Retail Stores, Online Platforms, Events, Tournaments |
| Companies Covered | The Pokémon Company, Konami Holdings Corporation, Hasbro, Bandai, Bushiroad, Upper Deck Company, Blizzard Entertainment, Riot Games, CyberAgent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trading Card Games Market Strategic Shifts
Physical-digital convergence and regulatory material mandates are actively restructuring how trading card games are produced, authenticated, and monetized across publisher ecosystems.
Near-field communication (NFC) chip embedding in premium card stock is hybridizing physical collectibility with digital wallet verification. High-end collectors and speculators in Japan and the United States are adopting NFC-enabled cards at accelerating velocity. This technology is hybridizing authentication workflows, compressing reliance on third-party grading services while enabling real-time ownership transfer tracking.
The EU Green Deal's packaging waste directives are mandating recyclable card stock and elimination of non-recyclable plastic wrap across member state distribution. Manufacturers serving European markets are reformulating coating chemistries and sourcing FSC-certified pulp to maintain shelf access. Collector-grade products with premium foil treatments face the steepest compliance redesign timelines and cost absorption challenges.
Buyer procurement is fragmenting across direct-to-consumer drops, subscription-based allocation programs, and traditional hobby shop channels simultaneously. Dedicated collectors are bypassing mass retail to secure guaranteed allocation through publisher-managed portals, while casual buyers remain concentrated in big-box retail. This channel disintermediation is most visible in the United States and United Kingdom, where authenticated resale platforms are capturing price discovery functions previously held by brick-and-mortar arbitrage.
Global Trading Card Games Market Segmentation
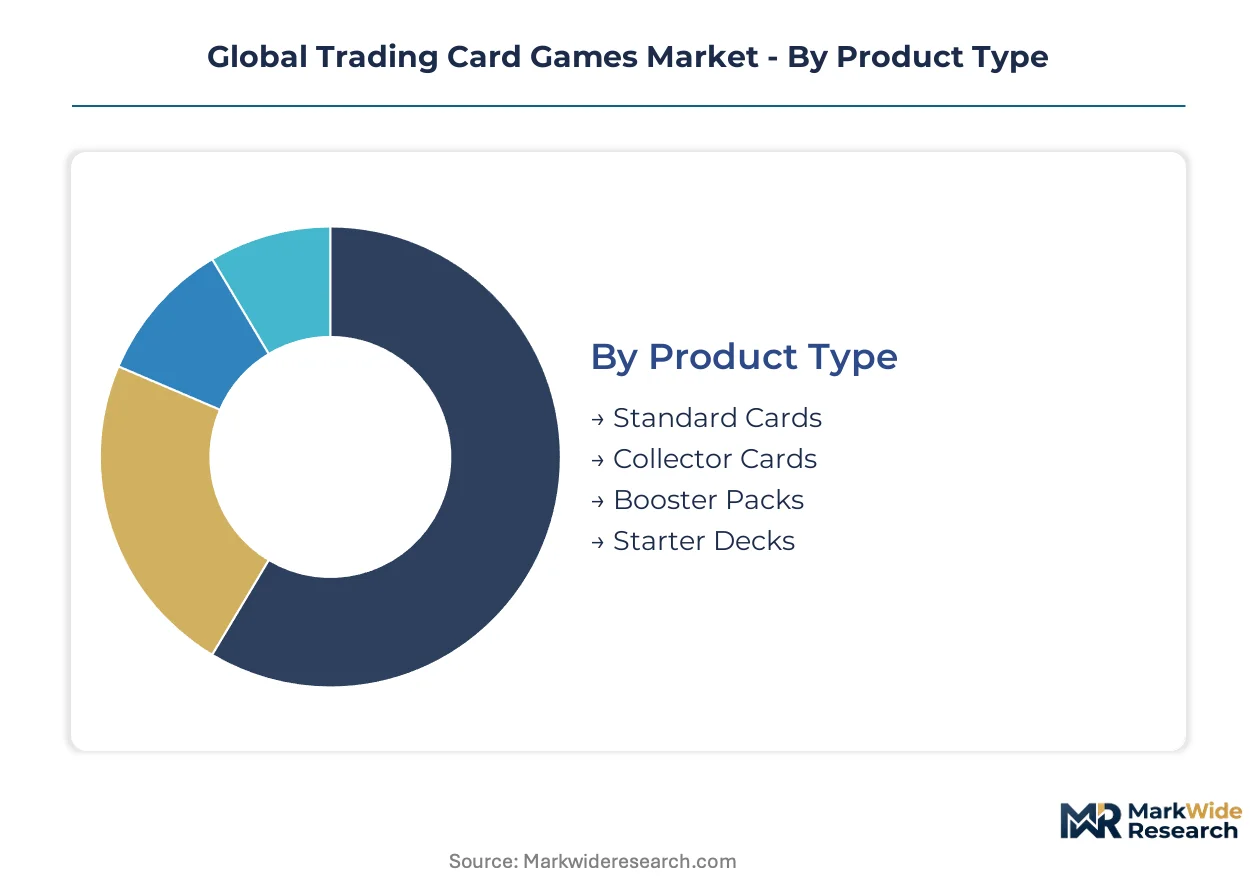
Trading card games fragment across product tiers, play modalities, and buyer cohorts with distinct margin profiles and aftermarket service requirements. Each segment demands tailored inventory strategies, authentication workflows, and organized play investment to capture full lifetime value.
Product Type:
After-sales intensity varies sharply across product tiers, with collector cards requiring grading partnerships and authentication infrastructure while standard products flow through high-velocity retail replenishment cycles.
- Standard Cards:High-volume cardstock products printed on 63 by 88 millimeter coated stock with standardized gameplay text and illustrations. Mass-market demand concentrates in the United States and Japan through hobby shop networks and big-box retail partnerships, driven by tournament participation requirements and deck-building refresh cycles.
- Collector Cards:Premium specimens featuring alternate art treatments, serialized numbering, and specialty foiling processes that command aftermarket grading and authentication services. Speculator demand clusters in the United States, Japan, and the United Kingdom through authenticated resale platforms, constrained by concentrated grading service capacity creating liquidity bottlenecks.
- Booster Packs:Randomized assortments of cards in sealed packaging, the core recurring revenue engine for publishers.
- Starter Decks:Fixed-content entry products designed for new player acquisition with predetermined card selections.
Standard cards hold the largest share; momentum sits with collector cards.
Game Format:
Cost tier stratification separates physical production from digital infrastructure investments, with hybrid formats demanding dual supply chain capabilities and integrated authentication technology.
- Physical:Printed cardstock products governed by formal rule sets for tabletop play, retaining the core profit engine across publisher portfolios.
- Digital:Software-native card collections with randomized acquisition mechanics, expanding most quickly as publishers integrate blockchain-adjacent ownership verification and mobile companion apps.
- Hybrid:NFC-enabled card stock embedding near-field communication chips for digital wallet verification, compressing reliance on third-party grading services while enabling real-time ownership transfer tracking in Japan and the United States.
- Online:Browser and client-based platforms with server-hosted collections and automated matchmaking infrastructure.
Physical formats dominate current revenue; hybrid architectures are gaining share fastest.
Player Demographics:
Application context varies by life stage, with competitive tournament circuits serving adult collectors while family-oriented products emphasize accessibility and simplified rule sets.
- Children:Entry-level buyers aged 6-12 years, typically introduced through franchise-animated content tie-ins and simplified starter products.
- Teens:Competitive tournament participants driving organized play infrastructure investment, with deck optimization and metagame analysis behaviors.
- Adults:Speculator-collector cohorts aged 25-40 years commanding authenticated resale channel development and premium product allocation strategies in the United States and Japan.
- Families:Multi-generational purchase units emphasizing casual play formats and cross-media franchise recognition.
Adult collectors generate the highest per-capita spend; teen tournament participation drives the steepest volume expansion.
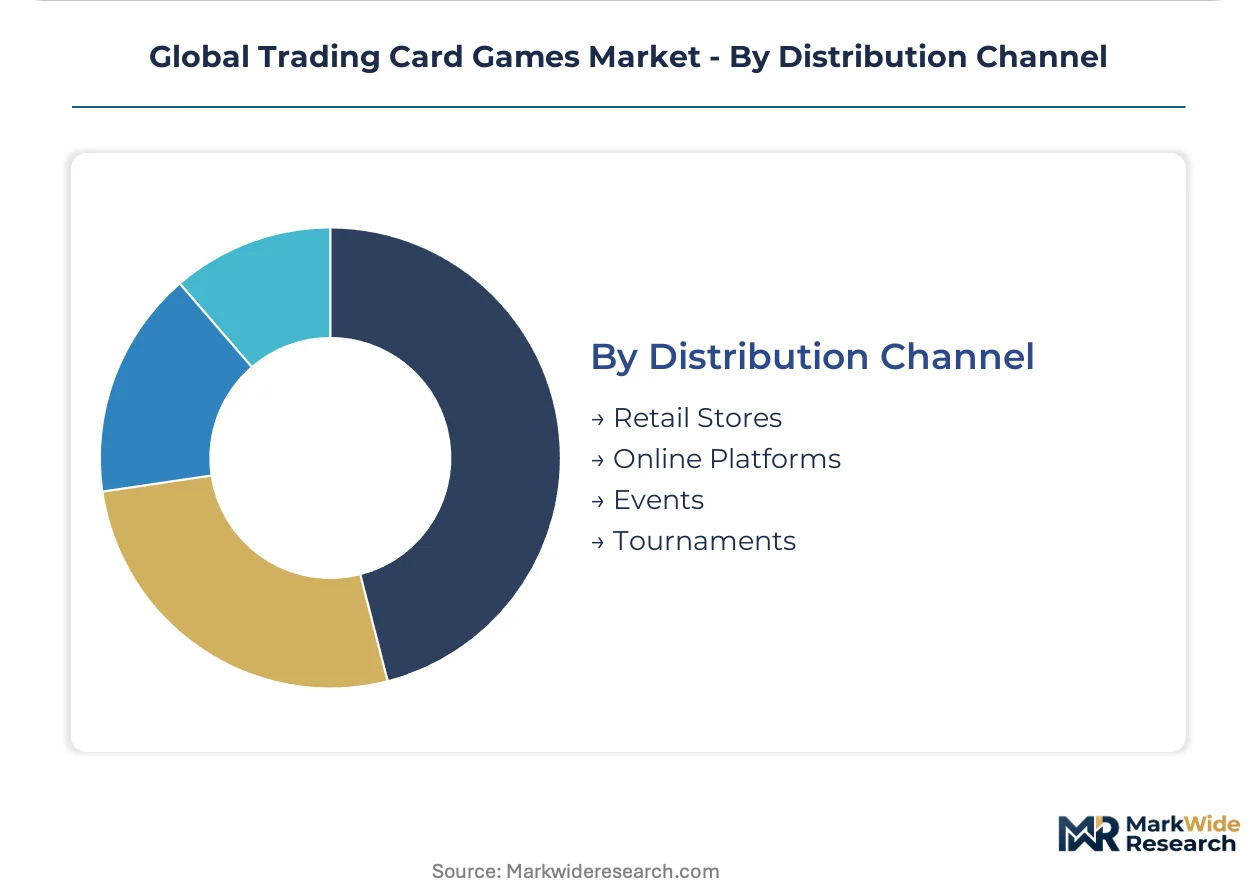
Distribution Channel:
Customer type fragmentation separates dedicated collectors pursuing guaranteed allocation through direct channels from casual buyers remaining in mass retail environments.
- Retail Stores:Hobby shops and big-box outlets providing tactile product discovery and immediate inventory fulfillment, facing margin compression from direct-to-consumer disintermediation.
- Online Platforms:Publisher-managed portals and authenticated resale marketplaces capturing price discovery functions previously held by brick-and-mortar arbitrage, most visible in the United States and United Kingdom.
- Events:Convention and product launch activations with limited-edition drops and experiential engagement.
- Tournaments:Organized play circuits with licensed venues generating recurring event revenue and player retention through competitive ranking systems.
Retail stores maintain the broadest reach; online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese collector markets while European manufacturers absorb compliance-driven cost premiums. The United States generates the steepest authenticated resale velocity through concentrated grading infrastructure. Cross-border arbitrage channels between these three markets sustain regional price differentiation.
United States
Adult collector cohorts aged 25-40 years drive authenticated resale channel development through platforms capturing price discovery functions. The FTC monitors youth-targeted advertising disclosures for randomized pack contents under consumer protection frameworks. Grading service capacity concentrates in Arizona and Texas, creating liquidity bottlenecks for premium specimens.
Japan
Vertically integrated animation-studio-publisher-retail structures sustain dominant brand recognition across generational buyer cohorts. METI standards govern product safety labeling while the Consumer Affairs Agency monitors gacha-derived monetization structures in digital card economies. Tokyo and Osaka anchor tournament circuit density with dedicated hobby shop networks.
Germany
KBA-influenced youth protection standards threaten booster pack randomization mechanics with potential gambling reclassification. EU Green Deal packaging directives mandate recyclable card stock transitions across manufacturing facilities serving European distribution. Frankfurt and Munich host organized play venue expansion amid regulatory compliance timeline compression.
United Kingdom
Direct-to-collector online drops bypass traditional retail allocation constraints with accelerating adoption among dedicated buyers. GDPR compliance requirements shape data collection practices for publisher-managed portals and mobile companion applications. London concentrates authenticated resale platform headquarters with cross-border EU arbitrage functionality.
South Korea
Esports venue integration expands organized play capacity to capture recurring event revenue from competitive tournament participants. MFDS guidelines influence product safety standards for youth-targeted card products with specialized coating chemistries. Seoul anchors dedicated tournament hall infrastructure with licensed venue networks.
Global Trading Card Games Market Competitive Environment
Vertically integrated IP holders and specialized tournament infrastructure providers split the market between franchise-driven volume and organized play ecosystem control. Publisher concentration remains high at the top tier, with mid-scale regional competitors occupying niche IP exploitation positions. Two archetypes dominate: cross-media conglomerates with captive animation and toy production, and dedicated game-system specialists with rigorous judge certification programs. Competitive moves center on direct-to-consumer channel construction and NFC-enabled hybrid product development.
Within the cross-media conglomerate tier, The Pokémon Company and Bandai exemplify vertically integrated structures binding card releases to broadcast schedules and toy line launches. Konami Holdings Corporation occupies a distinct position as a tournament infrastructure specialist with licensed venue networks and judge certification programs. These three entities collectively represent the strategic archetypes shaping competitive dynamics: IP-integrated content studios, organized play ecosystem operators, and hybrid-format technology adopters.
| Leading Market Players |
|---|
| The Pokémon Company |
| Konami Holdings Corporation |
| Hasbro |
| Bandai |
| Bushiroad |
| Upper Deck Company |
| Blizzard Entertainment |
| Riot Games |
| CyberAgent |
| Others |
Value Chain & Pricing Dynamics
Tokyo and Osaka's vertically integrated animation-studio-publisher-retail clusters concentrate premium collector-grade pricing power through controlled scarcity releases and authenticated resale channel partnerships. This geographic concentration of IP-controlled supply directly shapes downstream margin capture across Japanese, United States, and United Kingdom markets.
Pricing Analysis
The customization-premium spread separates authenticated collector specimens from mass-market standard products by a factor driven by grading certification tier and serialized scarcity mechanics. Three-tier pricing structure across premium, standard, and economy levels stratifies buyer cohorts, with adult collectors aged 25-40 years showing lowest price sensitivity for NFC-enabled hybrid formats. Cost compression in standard card stock intensifies because pulp and specialty paper input volatility compresses margin predictability for high-volume product lines. Teen tournament participants represent the most price-sensitive segment, prioritizing deck-building efficiency over premium treatments.
Supply Chain Analysis
Contract-manufacturing concentration rests with Japanese specialty printers and South Korean coating facilities serving FSC-certified pulp requirements under EU Green Deal mandates. China, Japan, and Belgium anchor coated card stock production with dependency on Brazilian eucalyptus pulp, German specialty chemical coatings, and Taiwanese NFC chip components. Single-source vulnerability concentrates in United States-based grading services creating authentication bottlenecks for collector liquidity. Distribution runs through hobby shop networks in Japan and the United States, with direct-to-collector publisher portals capturing margin retention in the United Kingdom and United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trading card games market sits in early-cycle expansion as organized play infrastructure investment accelerates tournament participation rates and authenticated resale platforms mature collector-grade liquidity mechanisms.
For Market Incumbents: Build tournament ecosystem moats through accelerated judge certification program scaling and licensed venue network density in underpenetrated metropolitan clusters. Defend against digital-native entrants by deepening backward integration into NFC-enabled card stock production and securing exclusive animation-studio partnerships for cross-media IP synchronization. Priority lever rests on direct-to-collector portal construction bypassing retail allocation constraints.
For New Entrants and Emerging Players: Build out white-space presence in India's nascent hobby shop networks and limited tournament circuits where first-mover organized play infrastructure investment faces minimal incumbent saturation. Target family-oriented casual play segments with simplified rule-set products binding card releases to educational toy line launches. Go-to-market angle emphasizes subscription-based allocation programs guaranteeing product access for dedicated collectors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid-format specialists with NFC chip integration capabilities and blockchain-adjacent ownership verification infrastructure. Long-term viability across the projection horizon hinges on regulatory compliance adaptability as gambling-classification precedents threaten booster pack randomization mechanics. Acquisition target archetype comprises regional tournament infrastructure operators with licensed venue networks. Signal to watch is Consumer Affairs Agency enforcement action on gacha-derived monetization structures forcing digital card economy restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| NFC-Enabled Hybrid Product Launch | Bridges physical collector markets to mobile-native buyers through digital wallet verification. |
| Direct-to-Collector Portal Expansion | Bypasses retail allocation constraints enabling scarcity-controlled release cadence and margin retention. |
| Organized Play Infrastructure Buildout | Captures recurring event revenue through licensed venue networks and competitive ranking systems. |
| Sustainable Material Transition | Ensures EU Green Deal compliance through FSC-certified pulp and recyclable coating chemistry reformulation. |
| Cross-Media IP Synchronization | Binds card release schedules to anime broadcast calendars creating multi-touch revenue capture. |
Study Parameters
The analysis maps physical card stock manufacturing, digital platform economics, and hybrid authentication technology segments, each validated through primary interviews with tournament organizers, hobby shop proprietors, card grading service operators, and publisher licensing executives. Secondary validation draws from customs trade data for pulp and specialty paper flows, SEC filings of publicly traded entertainment conglomerates, Consumer Affairs Agency enforcement notices, and EU packaging waste directive implementation records. Bottom-up volume modeling triangulates against top-down publisher revenue attribution across product tiers.
Assumption sets held fixed regulatory classification of booster pack randomization and EU Green Deal compliance timelines while varying pulp input cost trajectories and digital adoption curves across the projection horizon. Segmentation dimensions modeled include product type tier, game format architecture, player demographic cohort, and distribution channel structure. CAGRs derive from regression analysis against historical tournament participation growth and authenticated resale platform transaction velocity, with NFC chip cost decline curves and organized play venue expansion rates as industry-specific forecast inputs.
Stress conditions across pulp price volatility bands, gambling reclassification scenarios, and grading service capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sustained organized play investment and collector-grade aftermarket liquidity. Quarterly review of Consumer Affairs Agency enforcement patterns, KBA youth protection standard revisions, and United States state-level loot box legislation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Gaming Market
Gaming
3D Gaming Technology Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Mobile MOBA Games Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Chinese Gaming Industry Market
Gaming
United Kingdom Online Gambling Market
Gaming
Slot Machine Market
Gaming
India Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Africa Gaming Market
Gaming
LAMEA Gaming Posters Market
Gaming
Gaming Peripheral Market
Gaming
Console Games Market
Gaming
China in-Game Advertising Market