
 MMORPG Gaming Market | 2026-2036
MMORPG Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
MMORPG Gaming Market Foresight
Digital distribution platforms is reshaping how MMORPG titles reach audiences, bypassing traditional retail gatekeepers and enabling direct-to-consumer monetization cycles. Tencent leverages its WeGame ecosystem and mobile publishing dominance to control access across Asian markets. Activision Blizzard anchors its position through Battle.net infrastructure and sustained investment in live-service operations for flagship franchises. NetEase competes through proprietary engine development and co-publishing partnerships with Western studios seeking China market entry.
Massively multiplayer online role-playing games constitute persistent virtual environments supporting thousands of concurrent users through client-server architectures with tick rates typically ranging from 20 to 64 Hz depending on combat system demands. These platforms serve commercial purposes spanning entertainment consumption, virtual goods marketplaces, and social community formation with multi-year player retention as a core performance metric. Free-to-Play monetization models now dominate revenue generation across the sector, though subscription offerings retain superior lifetime value metrics among hardcore player cohorts. Mobile platforms represent the fastest-expanding addressable base, while PC installations sustain the deepest monetization per user through higher-value in-game purchase behavior.
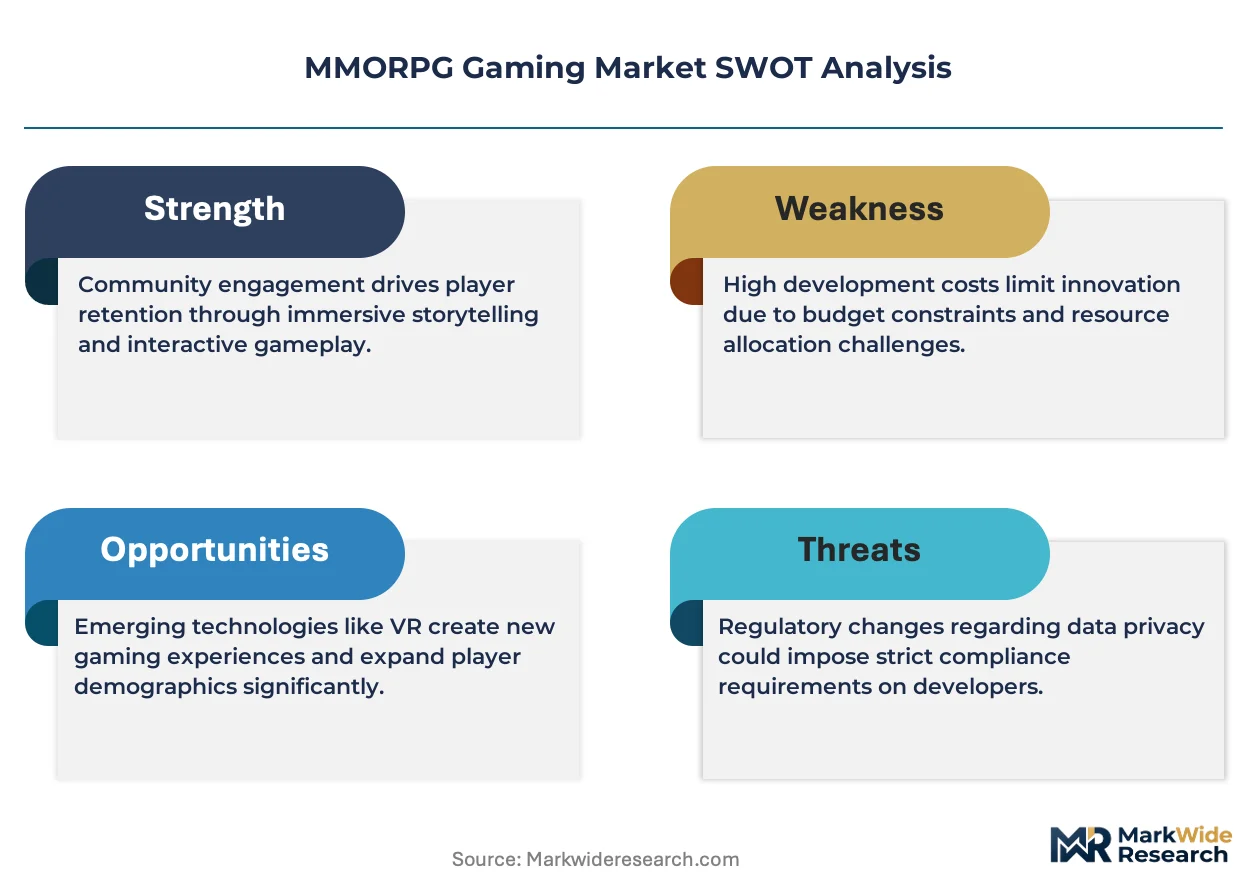
The Federal Trade Commission scrutinizes loot box mechanics and dark pattern design under evolving consumer protection frameworks, directly influencing monetization architecture decisions. China's National Press and Publication Administration imposes content approval requirements and playtime restrictions for minors, constraining release velocity and youth targeting strategies for titles seeking mainland distribution. South Korea's Game Rating and Administration Committee mandates probability disclosure for randomized item mechanics, setting compliance benchmarks that multinational publishers must integrate across regional builds. Stakeholders must monitor how divergent regulatory philosophies across these jurisdictions fragment development pipelines and force modular content architecture decisions.
Market Dynamics
Cloud gaming infrastructure is compressing server architecture costs while fragmenting platform control, forcing publishers to rebuild monetization systems around latency-tolerant synchronous multiplayer and asynchronous social loops rather than traditional real-time combat dominance.
Growth Catalysts
- Cross-Platform Interoperability:Unified account systems and shared progression mechanics eliminate platform silos, expanding addressable player bases across console, PC, and mobile endpoints without duplicate content production.
- China's NPPA Content Pipeline:Accelerated approval timelines for domestically developed titles under streamlined review categories enable faster monetization cycles for publishers with mainland distribution licenses.
- South Korean Esports Infrastructure:Dedicated stadium networks and broadcast licensing ecosystems transform flagship MMORPGs into spectator sport properties, extending revenue streams beyond direct player spending.
Market Restraints
- Input Cost Volatility:GPU and specialized server hardware pricing fluctuations squeeze cloud infrastructure margins for publishers operating proprietary data center networks.
- Regulatory Fragmentation:Divergent loot box disclosure mandates across South Korea's GRAC, China's NPPA, and the US FTC force modular build architectures that inflate development overhead.
- Technical Limitation:Tick rate synchronization constraints between mobile and PC clients cap competitive parity, limiting cross-platform PvP viability in latency-sensitive combat systems.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Vietnam, Indonesia, and Philippines present concentrated young adult demographics with rising disposable income and limited domestic competition from established regional publishers.
- Regulatory Tailwind:South Korea's probability disclosure mandates, while compliance-intensive, create first-mover transparency advantages for publishers integrating visible drop-rate architecture ahead of broader FTC adoption.
- Technology Convergence:AI-driven procedural content generation and neural network-based localization are compressing asset production timelines for multi-language regional launches.
Industry Challenges
- Live-Service Talent Scarcity:Experienced game economy designers capable of balancing free-to-play progression curves with whale monetization targets command premium compensation, constraining team scaling.
- Compliance Timeline Compression: Simultaneous submission requirements across China's NPPA, South Korea's GRAC, and Japan's CERO extend pre-launch certification windows, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MMORPG Gaming Market |
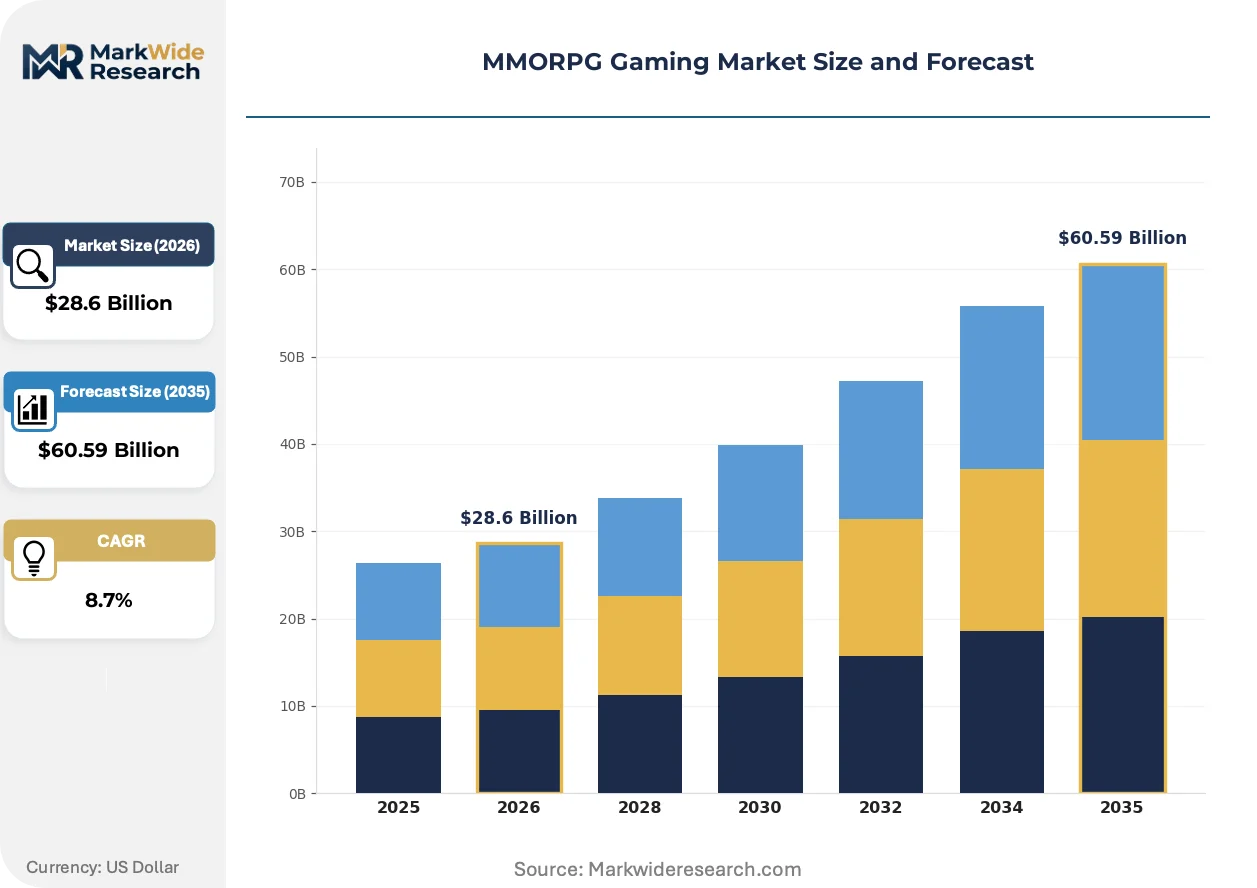
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
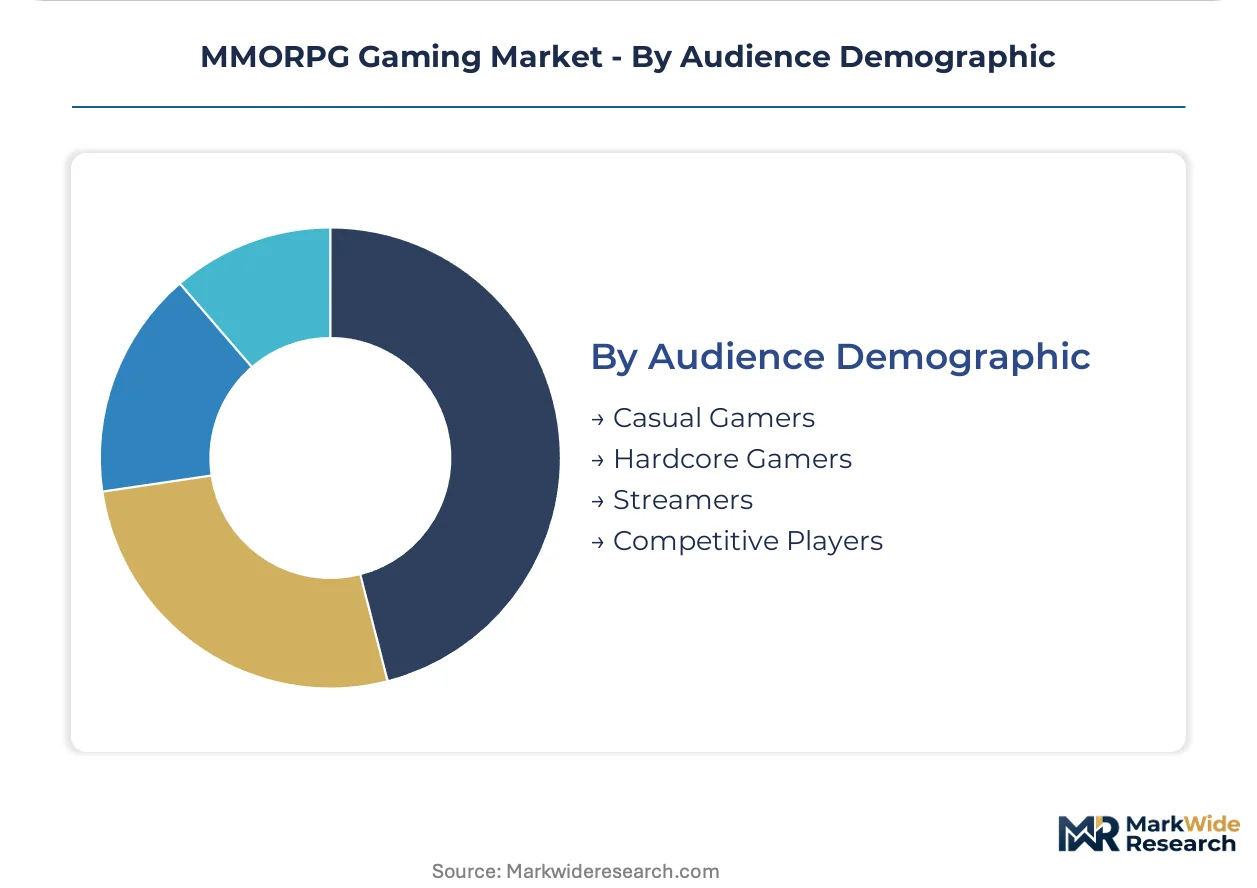
| Segmentation | Game Type: Sandbox, Theme Park, Hybrid, Action MMORPG Platform: PC, Console, Mobile, Web Monetization Model: Free-to-Play, Subscription, Buy-to-Play, In-Game Purchases Audience Demographic: Casual Gamers, Hardcore Gamers, Streamers, Competitive Players |
| Companies Covered | Activision Blizzard, Electronic Arts, Tencent, Pearl Abyss, Ubisoft Entertainment, NetEase, Nexon, Blizzard Entertainment, NCSOFT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MMORPG Gaming Market Shifts & Advancements
Monetization architecture is pivoting from randomized reward mechanics toward transparent progression systems, while backend infrastructure migrates toward edge-computing deployments that reduce latency for distributed player bases.
Procedural content generation is hybridizing traditional hand-crafted quest design with algorithmic world-building tools. Mid-tier studios in Poland and Sweden are adopting hybrid pipelines to accelerate live-service content cadences without proportional headcount expansion. This compression enables quarterly expansion releases that previously required eighteen-month development cycles, reshaping player retention expectations.
South Korea's GRAC probability disclosure mandates are forcing architectural transparency into randomized item mechanics. Publishers must now expose backend drop-rate tables and implement visible pity-counter systems that guarantee rewards after specified expenditure thresholds. Mobile-first titles targeting the Korean market are most affected, with several Western publishers delaying regional launches to reengineer monetization layers.
Subscription-adjacent battle pass systems are displacing pure loot box revenue in premium player cohorts. Hardcore segments across North American and European markets demonstrate higher lifetime value under predictable seasonal content models than under variable reward structures. This behavioral pivot is most visible in PC-installed titles with established multi-year player communities, where trust erosion from opaque mechanics has accelerated churn.
MMORPG Gaming Market Segmentation
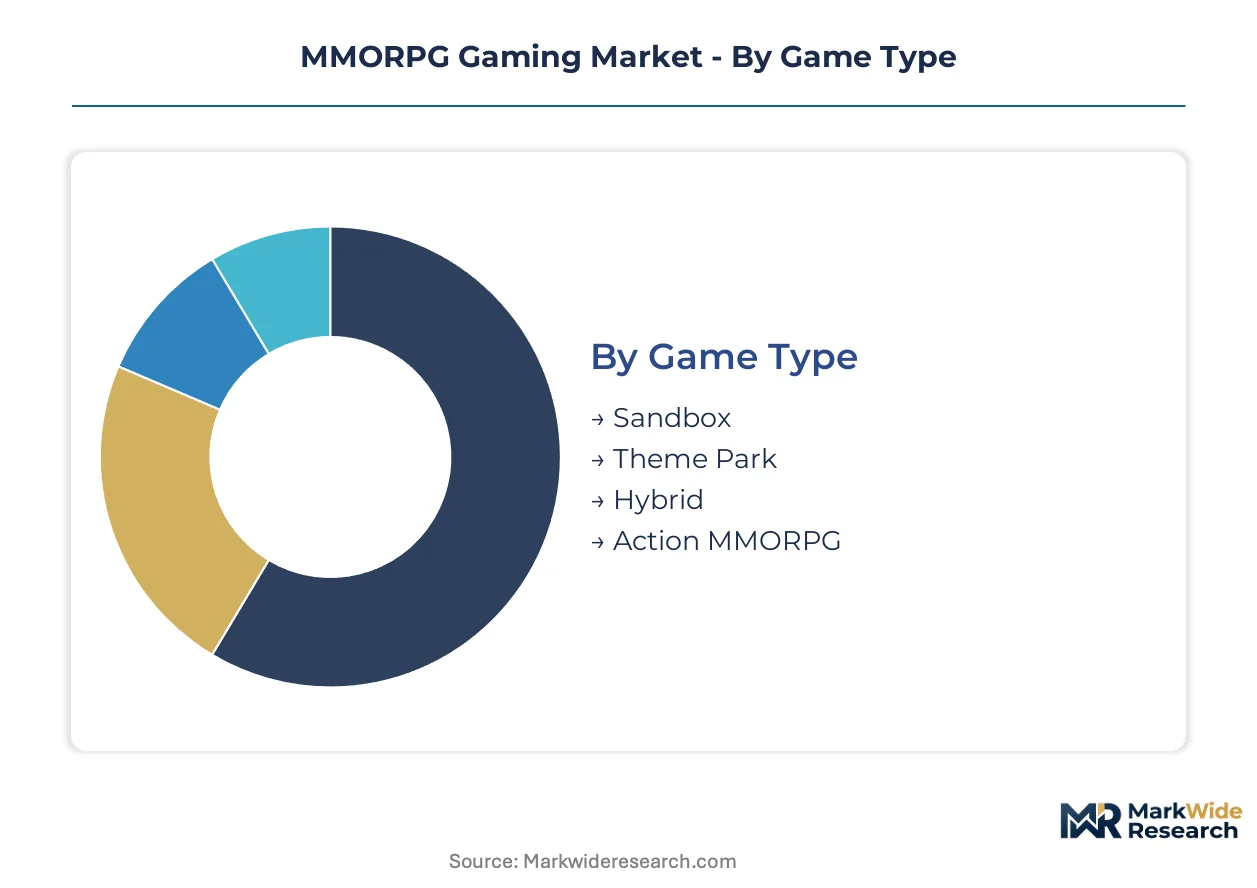
MMORPG market segmentation reveals divergent infrastructure requirements and monetization architectures across player engagement profiles. Distinct technical specifications for tick rates, server density, and content update cadences shape how publishers allocate development resources across segment boundaries.
Game Type:
After-sales service intensity varies dramatically across design philosophies, with persistent-world maintenance demands scaling directly with player agency and emergent system complexity.
- Theme Park:Guided narrative structures with curated quest chains and zone-based progression require intensive scripted content pipelines. South Korean publishers concentrate development here, driven by esports broadcast compatibility and predictable spectator engagement loops that sustain stadium licensing revenue.
- Sandbox:Player-driven economies and territory control systems demand continuous live-service intervention to combat exploitation and maintain economic equilibrium. Chinese studios prioritize this architecture for its superior long-term retention metrics and whale monetization potential through player-versus-player dominance hierarchies.
- Hybrid:Blends structured narrative beats with open-world exploration, splitting infrastructure costs between authored content and procedural systems.
- Action MMORPG:High tick-rate combat systems prioritize responsive netcode over persistence depth, attracting competitive player migration from adjacent fighting game genres.
By volume, Theme Park titles lead. By growth pace, Sandbox is ahead.
Platform:
Cost tier stratification separates premium PC installations from mass-market mobile endpoints, with console occupying an intermediate position on both hardware investment and monetization depth.
- Mobile:Touch-optimized control schemes and asynchronous social loops dominate architecture decisions. Southeast Asian markets drive demand concentration here, with Vietnam and Indonesia presenting young adult demographics where disposable income growth outpaces PC hardware penetration.
- PC:Keyboard-mouse precision enables complex ability rotations and high-skill-ceiling PvP systems. North American and European hardcore cohorts sustain the deepest per-user monetization through high-value cosmetic and convenience purchases.
- Console:Controller-native combat design and achievement integration attract session-based players seeking structured progression without persistent time investment.
- Web:Browser-based delivery minimizes download friction for trial conversion, though technical limitations constrain synchronous multiplayer fidelity.
Mobile claims the largest addressable base. PC retains the steepest expansion trajectory in revenue per user.
Monetization Model:
Application context determines model viability, with competitive integrity requirements in esports-tilted titles constraining pay-to-win mechanics that subsidize casual-oriented productions.
- Free-to-Play:Zero-entry-cost acquisition with whale-subsidized progression dominates Asian market penetration. China's NPPA playtime restrictions for minors force publishers toward cosmetic-only revenue in youth-targeted builds.
- Subscription:Predictable recurring revenue sustains premium server infrastructure and GM-staffed live events. Japanese players demonstrate highest conversion tolerance for this model among mature MMORPG markets.
- Buy-to-Play:Upfront purchase with expansion DLC cycles aligns with Western player expectations of content ownership and limited microtransaction intrusion.
- In-Game Purchases:A la carte item sales persist as supplementary revenue across all models, with South Korea's GRAC probability disclosure mandates reshaping randomized mechanic transparency.
Free-to-Play commands the broadest installed base. Subscription models are climbing the fastest in lifetime value metrics among hardcore retention cohorts.
Audience Demographic:
Customer type differentiation shapes content cadence and community management staffing, with streaming-visible titles requiring dedicated influencer liaison functions absent from private-server niches.
- Hardcore Gamers:Multi-hour daily sessions and guild leadership responsibilities demand the deepest systems complexity and highest-difficulty raid content. South Korean PC bang culture concentrates this demographic geographically.
- Casual Gamers:Fragmented play sessions and solo-preference questing drive mobile platform dominance and autoplay mechanic integration. Philippine and Indonesian markets show strongest growth in this segment.
- Competitive Players:Ranked ladder systems and tournament infrastructure requirements mirror esports title specifications, with dedicated spectator mode development consuming disproportionate engineering resources.
- Streamers:Content creator toolkits and drop-campaign integration transform titles into marketing channels, with visibility algorithms favoring high-production-value visual presentation.
Casual Gamers lead by volume. Competitive Players are gaining share fastest through esports broadcast licensing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea's esports-licensing ecosystem while Vietnam's emerging mobile-first markets trade at steep discount-to-value entry points. This asymmetry shapes how publishers allocate server infrastructure investment and monetization architecture across Asian expansion priorities.
South Korea
Seoul's PC bang culture and dedicated esports stadium networks sustain the deepest per-user monetization through broadcast licensing and spectator revenue streams. The Game Rating and Administration Committee mandates probability disclosure for randomized item mechanics, forcing transparent drop-rate architecture into all regional builds. Busan-Ulsan corridor hosts concentrated development studios specializing in high-tick-rate competitive MMORPG systems.
China
Domestic publishers leverage accelerated National Press and Publication Administration approval timelines for locally developed titles under streamlined review categories. Playtime restrictions for minors constrain youth-targeted monetization, pushing revenue toward cosmetic-only mechanics in compliant builds. Yangtze River Delta development clusters in Shanghai and Hangzhou dominate proprietary engine investment and co-publishing partnership negotiations.
Japan
Subscription model tolerance exceeds all mature Asian markets, with hardcore retention cohorts sustaining predictable recurring revenue streams. Consumer Affairs Agency scrutiny of gacha mechanics influences regional monetization transparency standards. Tokyo-based publishers anchor premium server infrastructure investments for GM-staffed live events and seasonal content cadences.
United States
North American hardcore PC segments generate highest-value cosmetic and convenience purchases through keyboard-mouse precision combat systems. Federal Trade Commission scrutiny of loot box mechanics and dark pattern design constrains randomized reward architecture decisions. Austin and Los Angeles development clusters concentrate live-service talent acquisition for economy balancing and whale monetization optimization.
Vietnam
Rising disposable income among young adult demographics outpaces PC hardware penetration, creating mobile-first addressable bases with limited domestic publisher competition. Regulatory frameworks remain less prescriptive on probability disclosure than South Korean or Chinese counterparts. Ho Chi Minh City development studios specialize in asynchronous social loops and autoplay mechanic integration for fragmented session patterns.
MMORPG Gaming Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on engine technology and regional distribution infrastructure. Market structure consolidates around three to five dominant publishers with integrated publishing ecosystems, while mid-tier studios fragment across specialized genre niches and geographic licensing partnerships. Strategic archetypes separate ecosystem gatekeepers with proprietary storefronts, engine-technology licensors, and regional co-publishing specialists. Dominant competitive moves include co-publishing partnerships for China market entry and proprietary cloud infrastructure investment for latency reduction.
Among Asia-Pacific platform integrators, Tencent and NetEase occupy positions spanning mobile publishing dominance and proprietary engine development. Activision Blizzard anchors Western competitive positioning through integrated storefront infrastructure and sustained live-service operations. These three exemplify how ecosystem control over distribution and account systems creates defensive moats against modular build competitors.
| Leading Market Players |
|---|
| Activision Blizzard |
| Electronic Arts |
| Tencent |
| Pearl Abyss |
| Ubisoft Entertainment |
| NetEase |
| Nexon |
| Blizzard Entertainment |
| NCSOFT |
| Others |
Supply & Pricing Matrix
GPU foundry concentration in Taiwan and South Korea feeds directly into cloud infrastructure margin pools for publishers operating proprietary data center networks, with pricing power accumulating downstream at platform integrators rather than component suppliers.
Pricing Analysis
Configured-to-order server deployments command 40-60% premiums over standard colocation pricing in esports-tilted markets where low-latency edge nodes are non-negotiable. Three-tier pricing structure across premium, standard, and economy levels separates dedicated bare-metal instances from shared virtualized environments and spot-market overflow capacity. Cost compression in economy-tier cloud hosting is intensifying because hyperscaler competition and idle capacity auctions. Casual mobile-first publishers exhibit highest price sensitivity, while South Korean esports broadcasters demonstrate lowest sensitivity due to spectator revenue offsetting infrastructure costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for server hardware procurement, with component sourcing increasingly bifurcated across domestic assembly requirements. Taiwan, South Korea, and China anchor GPU and specialized AI accelerator manufacturing, while Malaysia and Vietnam host final assembly for networking equipment. Raw material dependencies center on high-bandwidth memory modules, advanced packaging substrates, and rare-earth magnet components for cooling systems. Single-source vulnerability in TSMC's leading-edge node production creates concentration risk for tick-rate-sensitive competitive titles. Distribution runs through direct OEM relationships for hyperscale publishers and tier-one systems integrators for mid-tier studios lacking procurement scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming infrastructure and AI-driven procedural content generation are compressing development timelines and fragmenting platform control, creating high-growth disruption as regulatory probability disclosure mandates simultaneously reshape monetization architecture.
For Market Incumbents: Harden live-service operations through proprietary edge-computing deployments that reduce latency for distributed player bases, insulating core competitive titles from hyperscaler dependency. Consolidate position by acquiring specialized game economy design talent pools in Austin and Los Angeles to address live-service talent scarcity. Vertical integration into cloud infrastructure ownership offsets GPU pricing volatility squeezing operating margins.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's mobile-first market where rising disposable income among young adult demographics outpaces domestic publisher competition. Target Indonesia and Philippines for similar white-space expansion with asynchronous social loop architectures optimized for fragmented session patterns. Pursue co-publishing partnerships with established China market licensees rather than direct NPPA submission to bypass compliance timeline compression.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier studios in Poland and Sweden that have adopted hybrid procedural-handcrafted pipelines but lack capital for live-service scaling. Long-term viability favors publishers with integrated account systems and cross-platform progression infrastructure over modular build competitors. Watch South Korea's GRAC probability disclosure mandates as signal for broader FTC adoption trajectory affecting monetization transparency investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cloud Infrastructure Investment | Reduces latency for distributed player bases and insulates margins from hyperscaler pricing volatility. |
| Cross-Platform Account System Integration | Eliminates platform silos and expands addressable bases across console, PC, and mobile endpoints. |
| AI-Driven Procedural Content Generation | Compresses asset production timelines for quarterly expansion releases without proportional headcount expansion. |
| Transparent Drop-Rate Architecture Deployment | Creates first-mover compliance advantages ahead of broader FTC probability disclosure adoption. |
| Live-Service Talent Acquisition | Addresses economy designer scarcity constraining team scaling for free-to-play progression balancing. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filing analysis anchors the qualitative findings across the MMORPG value chain. Conversations with live-service operations directors, game economy designers, cloud infrastructure procurement leads, and regional publishing partners informed demand-side dynamics. Secondary sources include NPPA content approval databases, GRAC probability disclosure filings, SEC 10-K live-service revenue disclosures, and hyperscaler capex reports. Bottom-up triangulation across platform-specific monetization metrics and top-down validation against aggregate publisher revenue disclosures ensured consistency.
Calibration against historical release velocity and regulatory approval timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include game type, platform, monetization model, and audience demographic, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from installed base expansion rates and per-user monetization trajectory analysis. Forecast inputs incorporated cloud infrastructure cost curves and probability disclosure compliance overhead estimates.
Sensitivities concentrate around NPPA approval timeline volatility, GPU pricing fluctuations affecting cloud margins, and FTC regulatory adoption pace for probability disclosure mandates. Forecasts reflect documented assumptions regarding cross-platform interoperability standardization and AI content generation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game Engine Management Market
Gaming
Slot Machine Market
Gaming
Videogames Market
Gaming
Global Tarot Cards Market
Gaming
Gaming Gadgets Market
Gaming
H5 Games Market
Gaming
Arcade Cabinet Market
Gaming
Global Gaming Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
SLG Game Market
Gaming
Global Online Board Games Market
Gaming
3D Gaming Technology Market
Gaming
Global Battle Royale Games Market
Gaming
Germany Gaming Headset Market
Gaming
Australia Gaming Accessories Market
Gaming
Arcade Games Market