
 Smart Power Market | 2026-2036
Smart Power Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Power Market Outlook
Data center power architecture is recalibrating as hyperscale facilities shift from conventional UPS topologies to intelligent rack-level distribution with embedded telemetry. Infineon Technologies AG leverages its silicon carbide portfolio to dominate high-efficiency server power supplies across European and Asian installations. Texas Instruments Incorporated anchors the signal-chain and sensing layer that enables real-time thermal and electrical monitoring at the board level.
Smart power encompasses semiconductor-based systems that condition, convert, monitor, and distribute electrical energy with embedded control intelligence, typically operating at switching frequencies above 100 kHz and efficiencies exceeding 94 percent in gallium nitride implementations. The primary industrial purpose centers on minimizing energy loss while enabling bidirectional power flow and grid-responsive load shaping. Energy Storage Solutions within the technology dimension commands the deepest margin pools as utility-scale battery deployments require sophisticated power conversion and battery management integration. Residential Sector applications in the application dimension represent the fastest-expanding addressable base, driven by rooftop solar pairing with home energy management systems.
The US Federal Energy Regulatory Commission shapes interstate grid interconnection standards that dictate inverter functionality requirements for distributed resources, while the EU F-Gas Regulation and CE marking framework constrain coolant and insulation choices in power-dense European equipment. China's GB standards and MIIT directives mandate domestic compatibility protocols that influence product architecture for any manufacturer accessing state procurement channels. Stakeholders must monitor how divergent efficiency certification regimes across these jurisdictions fragment test-and-validate budgets and determine which product variants achieve commercial scale.
Market Dynamics
The shift from silicon to wide-bandgap semiconductors is compressing switching losses while forcing wholesale redesigns of thermal management architectures across power conversion equipment.
Growth Catalysts
- US Inflation Reduction Act:Domestic manufacturing incentives for grid-modernization hardware are accelerating localized production of intelligent inverters and battery management systems.
- Data center workload density:Hyperscale operators are mandating rack-level telemetry integration, pulling demand for embedded power monitoring ICs and digital control loops.
- Silicon carbide substrate supply:Vertical integration by substrate manufacturers into epitaxy and device fabrication is expanding available wafer capacity for high-efficiency power modules.
Market Restraints
- Gallium nitride wafer cost volatility:Limited six-inch substrate supply concentrates among two merchant foundries, exposing module pricing to raw material swings.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon coolants is constraining thermal design options for power-dense European equipment, extending qualification timelines.
- Copper and rare earth magnet dependence:Winding and magnetic component costs track commodity indexes, compressing margin on mid-power inverter platforms.
Strategic Opportunities
- India rooftop solar pairing:PLI scheme subsidies for domestic module manufacturing are creating pull-through demand for grid-tied inverters with export-limiting functionality.
- Vehicle-to-grid convergence:Bidirectional onboard chargers merging automotive power electronics with residential energy management represent unclaimed white space.
- Second-life battery integration:Decommissioned EV packs repurposed for stationary storage require novel power conversion architectures and control firmware.
Industry Challenges
- Wide-bandgap power electronics talent scarcity:Device physics expertise for SiC and GaN gate drive design concentrates among semiconductor specialists, constraining OEM hiring pipelines.
- Multi-jurisdictional certification burden:Divergent efficiency test protocols across US DOE, EU Ecodesign, and China GB standards fragment validation budgets and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Power Market |
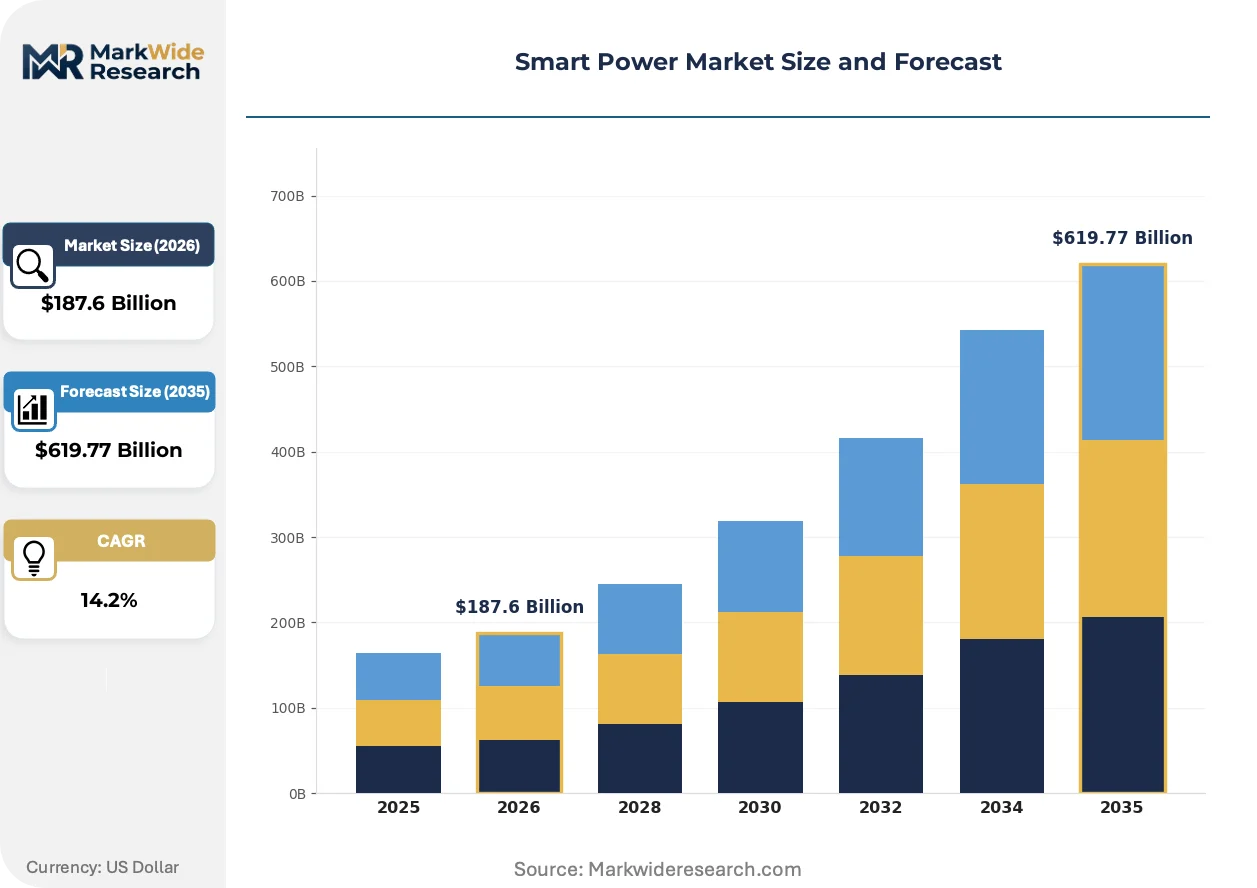
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Grid, Energy Storage Solutions, Demand Response, Distributed Generation Application: Residential Sector, Industrial Automation, Commercial Buildings, Renewable Integration End User: Utilities, Energy Providers, Government Agencies, Commercial Users Service Type: Consulting, Installation, Maintenance, Managed Services |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies AG, STMicroelectronics N.V., ON Semiconductor Corporation, Qualcomm Incorporated, Tesla, Apple, Navitas Semiconductor, GaN Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Power Market Strategic Shifts
Power semiconductor architectures are converging with system-level intelligence, embedding predictive algorithms directly into conversion stages rather than treating control as a separate domain.
Gallium nitride high-electron-mobility transistors are electrifying server power supply designs by collapsing switching transition losses that previously dominated thermal budgets. Hyperscale data center operators are now specifying GaN-based 48V-to-load converters as default for new rack deployments. This compression of magnetics volume and cooling overhead is enabling 50 percent power density gains without liquid cooling infrastructure.
The EU F-Gas Regulation is forcing refrigerant transitions in power-dense cooling systems, prohibiting hydrofluorocarbon-based thermal management in new European installations above specified charge thresholds. Equipment manufacturers are responding with air-cooled architectures and dielectric fluid immersion for high-voltage inverters. Grid-tied solar and storage installations in Germany and the Netherlands face the most immediate redesign pressure.
Buyer consolidation among utility-scale project developers is compressing supplier qualification cycles and unbundling hardware from long-term service agreements. Developers now procure inverters and battery management systems through separate RFPs rather than turnkey EPC contracts. This pattern is most pronounced in Texas and California, where independent power merchants dominate renewable asset ownership.
Smart Power Market Segmentation
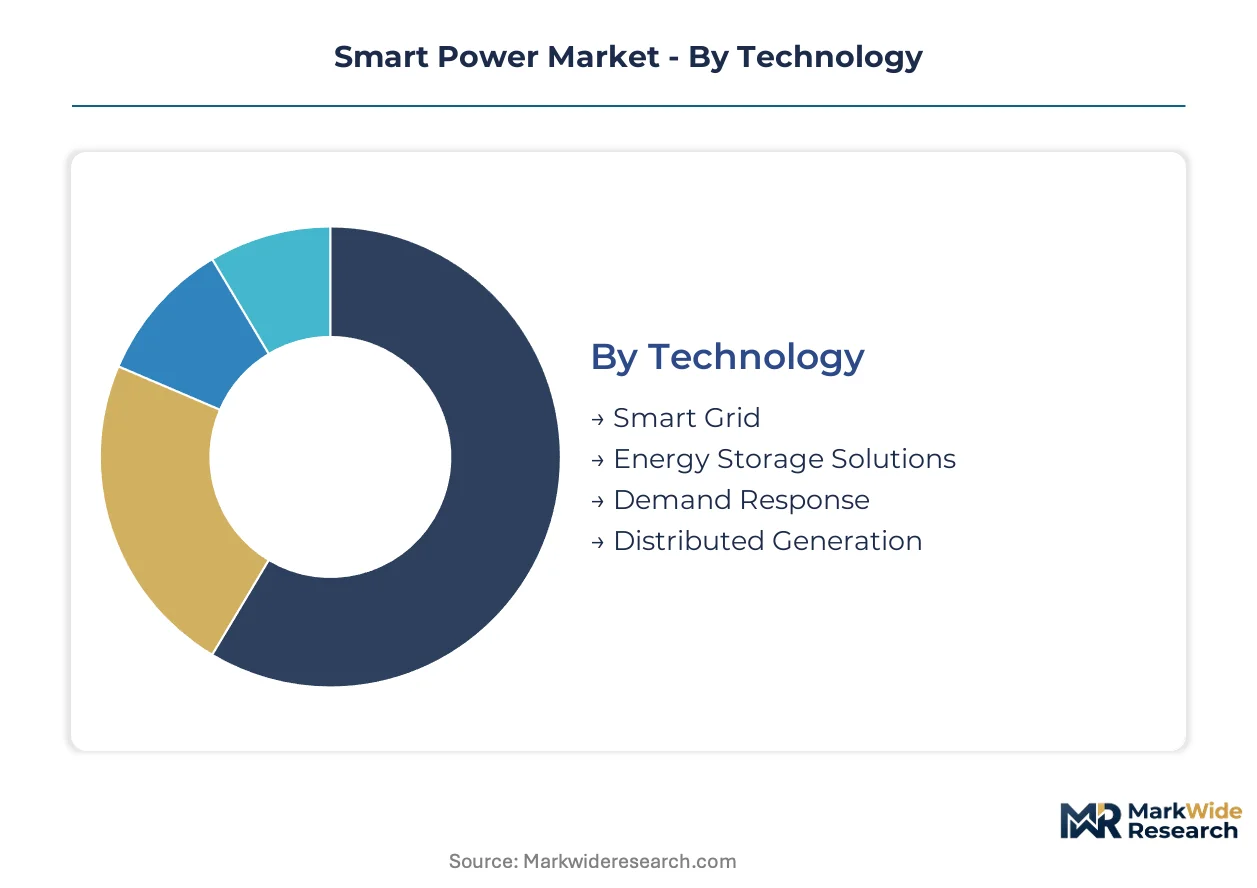
Smart power market segmentation reveals distinct certification and interoperability requirements across each dimension. Technology choices dictate semiconductor efficiency thresholds while application segments determine grid-code compliance burdens and end-user procurement patterns.
Technology:
Each technology segment carries specific efficiency certification mandates from US DOE, EU Ecodesign, and China GB standards that fragment validation budgets across product variants.
- Smart Grid:Advanced metering infrastructure and distribution automation systems integrating SCADA with two-way communication protocols. Demand concentrates in China where state-backed ultra-high-voltage transmission deployment outpaces other national markets, driven by MIIT-mandated domestic compatibility protocols.
- Energy Storage Solutions:Utility-scale battery systems combining power conversion with battery management integration at switching frequencies above 100 kHz. Demand concentrates among Texas and California independent power merchants unbundling hardware from long-term service agreements, constrained by FERC interstate interconnection standards.
- Demand Response:Load-shaping systems enabling bidirectional power flow between grid operators and flexible consumers.
- Distributed Generation:Rooftop solar and microturbine interfaces requiring localized inverter functionality per jurisdiction-specific standards.
Leading the category by volume: Energy Storage Solutions. Growing fastest: Distributed Generation.
Application:
Application segments stratify by customer procurement scale and service agreement complexity, from residential single-unit sales to industrial multi-year performance contracts.
- Residential Sector:Home energy management systems paired with rooftop solar and behind-the-meter storage. Demand concentrates in India where PLI scheme subsidies for domestic module manufacturing create pull-through for grid-tied inverters with export-limiting functionality.
- Commercial Buildings:Intelligent HVAC and lighting integration with sub-metering analytics for multi-tenant facilities. Demand concentrates in Germany and the Netherlands where EU F-Gas Regulation prohibitions on hydrofluorocarbon coolants force immediate redesign of power-dense thermal management.
- Industrial Automation:Process control systems with embedded power quality monitoring for manufacturing lines.
- Renewable Integration:Grid-tied solar, wind, and hybrid storage interfaces for utility-scale asset developers.
Dominant by revenue: Commercial Buildings. Climbing the fastest: Residential Sector.
End User:
End user categories diverge sharply in technical specification authority and vendor qualification cycles.
- Utilities:Investor-owned and municipal grid operators procuring transmission and distribution infrastructure with 20-year asset horizons. Demand concentrates in China state procurement channels where GB standards and MIIT directives mandate domestic compatibility protocols influencing product architecture.
- Energy Providers:Independent power merchants and retail electricity suppliers optimizing generation portfolios against wholesale price volatility. Demand concentrates in Texas and California where buyer consolidation compresses supplier qualification cycles and separates inverter procurement from EPC contracts.
- Government Agencies:Federal and state entities deploying public infrastructure under procurement preference rules.
- Commercial Users:Large industrial and institutional consumers with on-site generation and peak-shaving objectives.
Highest procurement authority: Utilities. Expanding most quickly: Energy Providers.
Service Type:
Service segments align with asset lifecycle phases and recurring revenue potential for system integrators.
- Consulting:Front-end engineering and grid interconnection feasibility studies navigating multi-jurisdictional certification requirements. Demand concentrates among European project developers facing EU Ecodesign efficiency test protocols divergent from US DOE methods.
- Managed Services:Long-term asset performance contracts with guaranteed availability and predictive maintenance algorithms. Demand concentrates in US utility-scale deployments where Inflation Reduction Act domestic manufacturing incentives accelerate localized production of intelligent inverters requiring ongoing firmware optimization.
- Installation:Turnkey deployment of hardware with commissioning and initial warranty support.
- Maintenance:Reactive and preventive service contracts for established infrastructure.
Largest revenue pool: Managed Services. Steepest expansion trajectory: Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for electronics manufacturing concentrate smart power component assembly, while China's Yangtze River Delta anchors wafer fabrication for wide-bandgap semiconductors.
United States
Data center operators in Northern Virginia and Dallas-Fort Worth mandate rack-level power telemetry for new hyperscale builds. FERC interstate interconnection standards dictate inverter functionality requirements for distributed solar and storage assets. Texas independent power merchants unbundle inverter procurement from EPC contracts, compressing supplier qualification cycles.
China
State-backed ultra-high-voltage transmission deployment outpaces other national markets for grid-modernization hardware. MIIT directives and GB standards mandate domestic compatibility protocols influencing product architecture for state procurement channels. The Yangtze River Delta cluster around Shanghai concentrates silicon carbide epitaxy and device fabrication capacity.
Germany
Commercial building operators face immediate redesign pressure for power-dense thermal management systems. EU F-Gas Regulation prohibitions on hydrofluorocarbon coolants constrain equipment choices above specified charge thresholds. Industrial automation corridors in Bavaria and Baden-Württemberg drive demand for embedded power quality monitoring in manufacturing lines.
India
PLI scheme subsidies for domestic solar module manufacturing create pull-through demand for grid-tied inverters with export-limiting functionality. CEA technical standards govern grid interconnection for distributed generation assets. Manufacturing clusters in Gujarat and Tamil Nadu concentrate assembly operations for residential energy management systems.
Japan
Automotive OEMs advance bidirectional onboard charger integration for vehicle-to-grid applications. METI efficiency standards shape power semiconductor specifications for industrial equipment. The Nagoya industrial corridor anchors development of predictive algorithms embedded directly into power conversion stages.
Smart Power Market Competitive Environment
Top-tier vendors anchor high-efficiency semiconductor supply, while mid-tier specialists occupy system integration and application-specific module niches. The structure stratifies across three tiers: integrated device manufacturers with captive substrate supply, fabless power semiconductor designers, and system-level integrators bundling hardware with firmware. Strategic moves concentrate on backward integration into epitaxy capacity and geographic expansion through joint ventures in India and Southeast Asia.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics N.V. represent the dominant archetype of vertically structured suppliers controlling silicon carbide substrate through device fabrication. Texas Instruments Incorporated anchors the signal-chain and sensing layer segment, exemplifying the diversified semiconductor portfolio approach. Navitas Semiconductor occupies a position within the fabless gallium nitride specialist tier, reflecting the emerging competitive vector of pure-play wide-bandgap device design.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| ON Semiconductor Corporation |
| Qualcomm Incorporated |
| Tesla |
| Apple |
| Navitas Semiconductor |
| GaN Systems |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate manufacturing expansion simultaneously compresses wafer costs and concentrates supply among vertically integrated device manufacturers. This dual effect reshapes procurement economics for power module assemblers while amplifying pricing power for substrate-captive suppliers.
Pricing Analysis
Short lead-time premiums dominate spot procurement for gallium nitride wafers, with six-inch substrate scarcity forcing module makers to pay 15-30 percent markups for expedited delivery. Contract-based long-term offtake agreements anchor the dominant pricing structure, separating premium tiers (FERC-certified grid-tied inverters with embedded telemetry) from standard offerings (industrial drives without grid-code compliance) and economy variants (consumer-grade power supplies). Price differentiation hinges on certification grade (UL 1741-SA vs basic CE marking) and volume scale, with hyperscale data center operators extracting steepest discounts. Pricing pressure stems from copper and rare earth magnet commodity index volatility, compressing margins on mid-power inverter platforms. Residential rooftop solar buyers exhibit highest price sensitivity, while utility-scale developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics flows for decommissioned EV battery packs are creating secondary material channels that compete with virgin silicon carbide and gallium nitride substrate supply. Manufacturing concentration centers on China's Yangtze River Delta for epitaxy and device fabrication, Germany's Bavaria corridor for industrial automation power modules, and Texas for data center power distribution hardware. Raw material dependencies include six-inch SiC substrates, copper windings, and neodymium-dysprosium rare earth magnets. Single-source vulnerability concentrates in merchant GaN foundry capacity, where two suppliers control global six-inch wafer output. Distribution runs through direct OEM partnerships for utility-scale deployments and authorized distributor networks for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart power market has become a vertical-integration race, with substrate-to-system control over silicon carbide supply emerging as the decisive competitive lever.
For Market Incumbents: Hedge gallium nitride supply exposure through multi-foundry qualification while locking long-term SiC substrate offtake with Yangtze River Delta manufacturers. Consolidate position in FERC-compliant grid-tied inverter segments where certification barriers deter modular competitors, and expand captive epitaxy capacity to defend margin against substrate price volatility. For New Entrants and Emerging Players: Bidirectional onboard charger firmware for vehicle-to-grid applications offers the most penetrable white space, with automotive OEMs seeking power electronics partners outside incumbent semiconductor hierarchies. Target India's PLI-subsidized solar manufacturing clusters with export-limiting inverter designs tailored to CEA technical standards. Pursue direct utility partnerships in Texas and California where unbundled procurement favors specialized hardware vendors over turnkey EPCs. For Investors and Strategic Acquirers: Re-rating potential sits with fabless GaN specialists given hyperscale data center procurement shifts toward 48V-to-load converters. Over a multi-year horizon, acquisition value concentrates in firms combining wide-bandgap device design with embedded predictive control firmware. Monitor F-Gas Regulation implementation timelines in Germany and the Netherlands as early signals of thermal management redesign cycles that will reshape equipment supplier competitive positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive wafer production insulates Infineon and STMicroelectronics from merchant foundry pricing volatility. |
| GaN-Based 48V Server Power Supply Launch | Hyperscale operators in Northern Virginia and Dallas-Fort Worth now specify GaN as default for new rack builds. |
| India Joint Venture for Inverter Assembly | PLI scheme subsidies in Gujarat and Tamil Nadu create localized manufacturing cost advantages for grid-tied products. |
| Vehicle-to-Grid Firmware Platform Integration | Automotive OEMs in Japan's Nagoya corridor seek power electronics partners for bidirectional charger development. |
| Second-Life Battery Power Conversion Architecture | Decommissioned EV packs require novel control firmware that merges automotive and stationary storage design expertise. |
Study Parameters
Independent corroboration across primary interviews with power semiconductor device physicists, data center infrastructure procurement directors, and utility-scale project developers, combined with secondary validation of FERC filings, EIA generation capacity data, and IEA grid modernization reports, underwrites the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing from customs trade records and SEC semiconductor segment disclosures.
Comparable-period anchoring to historical wide-bandgap adoption curves and silicon-to-SiC transition timelines structures the forecast framework across the analysis window. Segmentation dimensions include technology tier (Si IGBT vs SiC MOSFET vs GaN HEMT), application scale (residential single-unit vs utility multi-MW), and regional regulatory cluster (FERC-interconnection vs EU Ecodesign vs China GB standards). CAGRs derive from installed base replacement cycles and emerging application penetration curves, with inputs from hyperscaler capex disclosure trends and state-level renewable portfolio standard trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gallium nitride substrate supply disruption or accelerated EU F-Gas Regulation phase-down schedules. Practitioners should monitor six-inch SiC wafer capacity expansion announcements and India PLI scheme disbursement rates for early signals of supply-cost inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
United States Power Market
Power
Global Hydraulic Turbine Market
Power
Electric Arc Furnaces Market
Power
Power Rental Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Brunei Power Market
Power
Substation Automation System Market
Power
Russian Federation Power Market
Power
Mexico Power EPC Market
Power
Power Shelf Market
Power
Australia Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Steam Turbine MRO Market
Power
Qatar Power Market
Power
Germany Solar Inverter Market
Power
Kuwait Power Market