
 Russian Federation Power Market | 2026-2036
Russian Federation Power Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Power Market Analytics
Wholesale electricity capacity markets is fragmenting as independent generators challenge legacy state-owned structures. RusHydro PJSC leverages its vast Siberian hydropower cascade to dominate renewable-class output. Gazprom PJSC anchors thermal generation through its integrated gas-to-power value chain. Inter RAO UES PJSC competes in cross-border electricity trade with Baltic and Central Asian neighbors.
The Russian Federation Power encompasses electricity production, transmission, and distribution infrastructure operating across voltage classes from 0.4 kV distribution to 750 kV ultra-high-voltage trunk lines, with thermal plants burning natural gas, coal, and fuel oil to produce steam-driven turbine rotation. Its primary purpose is converting primary energy into grid-synchronous alternating current for industrial machinery, residential heating, and commercial operations. Thermal generation occupies the largest installed capacity share, while hydropower sustains the highest capacity utilization rates due to minimal fuel cost exposure. Solar and wind segments lead incremental capacity additions, though from a low base, as developers navigate locational marginal pricing in Russia's European territory.
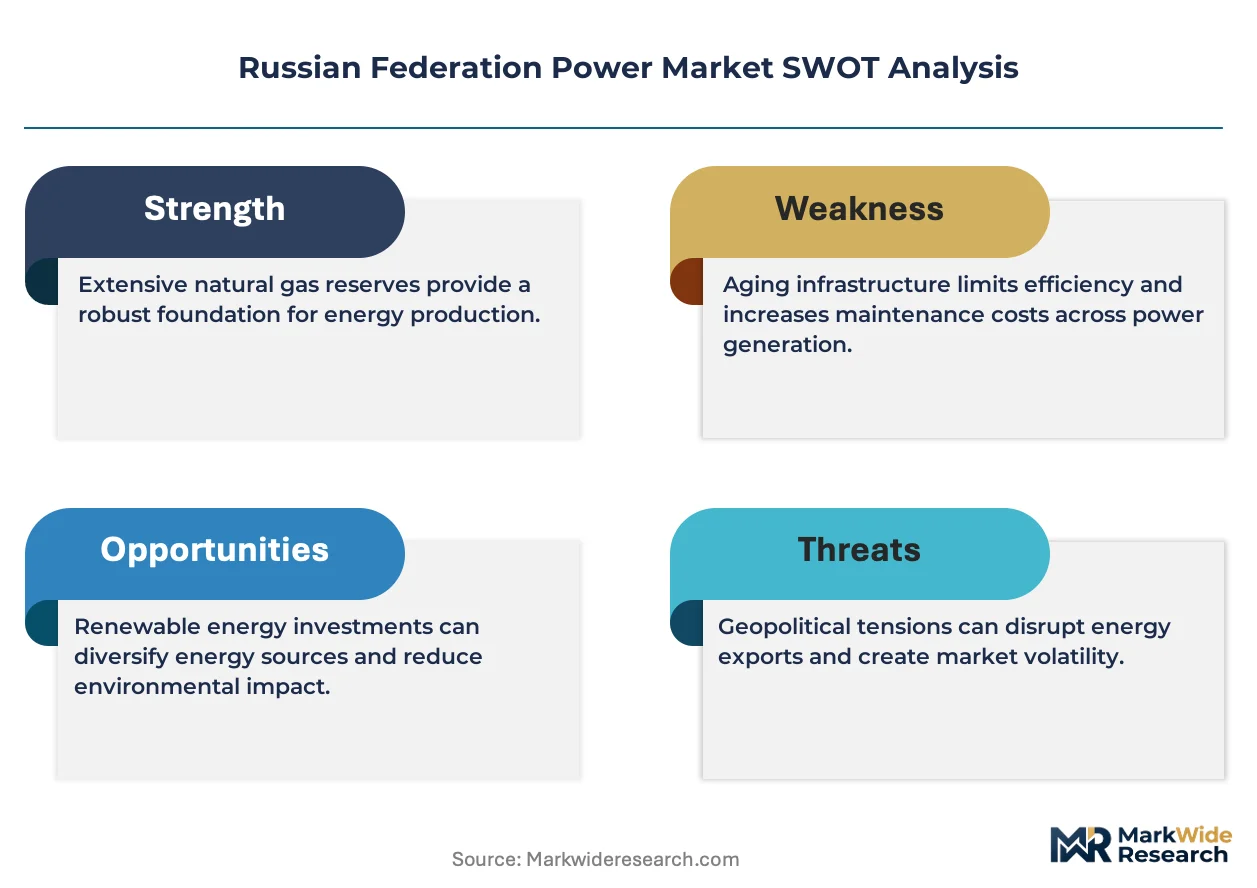
Russia's Federal Antimonopoly Service and the Ministry of Energy administer capacity supply agreements and tariff regulation that determine generator revenue stability and investor payback periods. Technical standards from the Federal Grid Company mandate frequency stability and reactive power compensation, filtering which plant designs secure grid connection permits. Stakeholders must monitor how carbon border adjustment mechanisms in neighboring European markets reshape the competitiveness of Russian electricity-intensive exports.
Market Dynamics
Siberian metallurgical clusters and Moscow's high-voltage ring drive electricity demand patterns that reshape generation dispatch priorities across voltage classes.
Growth Catalysts
- Industrial Electrification:Steel and aluminum smelters in Krasnoyarsk and Bratsk expand arc furnace capacity, pulling baseload power from hydropower cascades.
- Grid Modernization Mandates:Federal Grid Company's technical standards for frequency stability force transmission upgrades that unlock stranded generation assets.
- Cross-Border Trade Liberalization:Inter RAO UES PJSC secures export slots to Kazakhstan and Baltic states, monetizing European Russia's thermal surplus.
Market Restraints
- Gas Price Volatility:Gazprom PJSC's domestic tariff linkage to oil-indexed export contracts creates margin compression for combined-cycle operators.
- Equipment Import Dependency:Gas turbine and generator set supply concentrates among German and Japanese OEMs, exposing project timelines to currency and sanctions friction.
- Grid Connection Queues:Unified National Electric Grid's permitting backlog for reactive power compensation studies delays renewable project commissioning.
Strategic Opportunities
- Far East Isolation:Kamchatka and Sakhalin remain electrically islanded from the national grid, creating captive market structures for small modular reactor developers.
- Carbon Border Adjustment Arbitrage:EU CBAM implementation incentivizes low-carbon power sourcing for aluminum and fertilizer exporters in Volga industrial corridors.
- Distributed Solar+Storage:Declining lithium-ion battery costs converge with net metering reforms to unlock commercial rooftop installations in Krasnodar Krai.
Industry Challenges
- Specialized Turbine Maintenance:Aero-derivative and heavy-frame gas turbine overhaul expertise concentrates among aging field engineers, constraining fleet availability.
- Legacy SCADA Integration:Soviet-era control systems in Ural and Volga thermal plants resist interoperability with modern digital substation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Power Market |
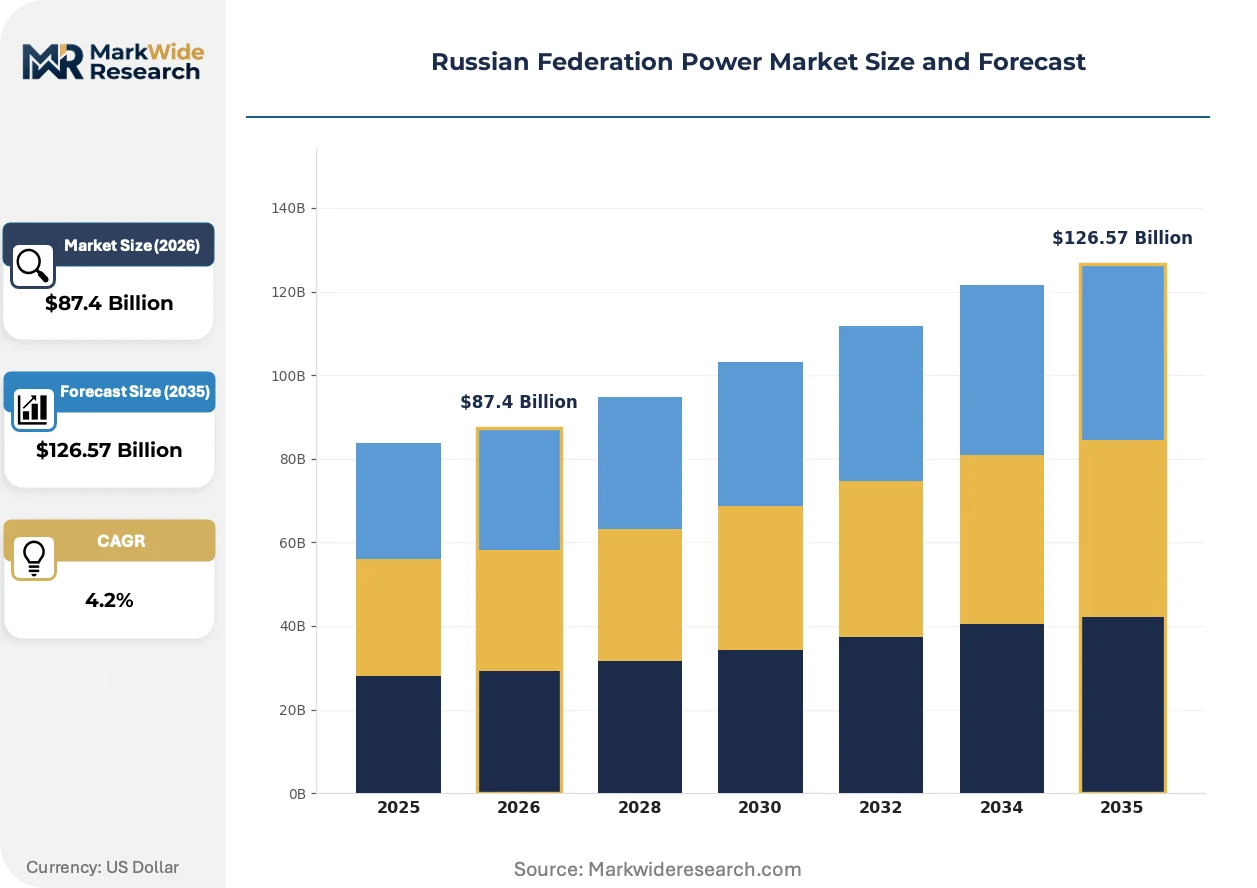
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $126.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Generation Type: Thermal, Hydropower, Wind, Solar Technology: Gas Turbine, Hydroelectric, Biomass, Geothermal End User: Residential, Commercial, Industrial, Agricultural Utility Model: State-Owned, Private, Independent, Hybrid |
| Companies Covered | RusHydro PJSC, Rosatom Corp, Gazprom PJSC, Rosseti PJSC, Inter RAO UES PJSC, Gazprom Energoholding, Unipro PJSC, T Plus Group, Power Machines, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Power Market Evolving Landscape
Digital substation architectures and synchronous condenser retrofits are compressing traditional protection relay markets while opening new service revenue streams for grid operators.
Gas-insulated switchgear (GIS) at 220-500 kV is rendering obsolete air-insulated substations in dense urban corridors. Moscow's high-voltage ring operators deploy GIS to shrink footprint within existing substation fences. This technology is rendering obsolete land-intensive AIS designs that dominated Soviet-era construction.
Russia's Ministry of Energy capacity supply agreement reforms now index payments to actual availability rather than declared capacity, forcing thermal generators to invest in cold-weather start reliability. Siberian plant operators face the steepest compliance curves due to extreme ambient temperature ranges. Hydropower generators gain relative advantage from this shift.
Large industrial offtakers in Chelyabinsk and Nizhny Novgorod now contract directly with independent generators under bilateral power purchase agreements, bypassing wholesale market intermediation. This disintermediation compresses trading margins for incumbent supply companies. The trend concentrates in regions with surplus generation and creditworthy anchor loads.
Russian Federation Power Market Segmentation
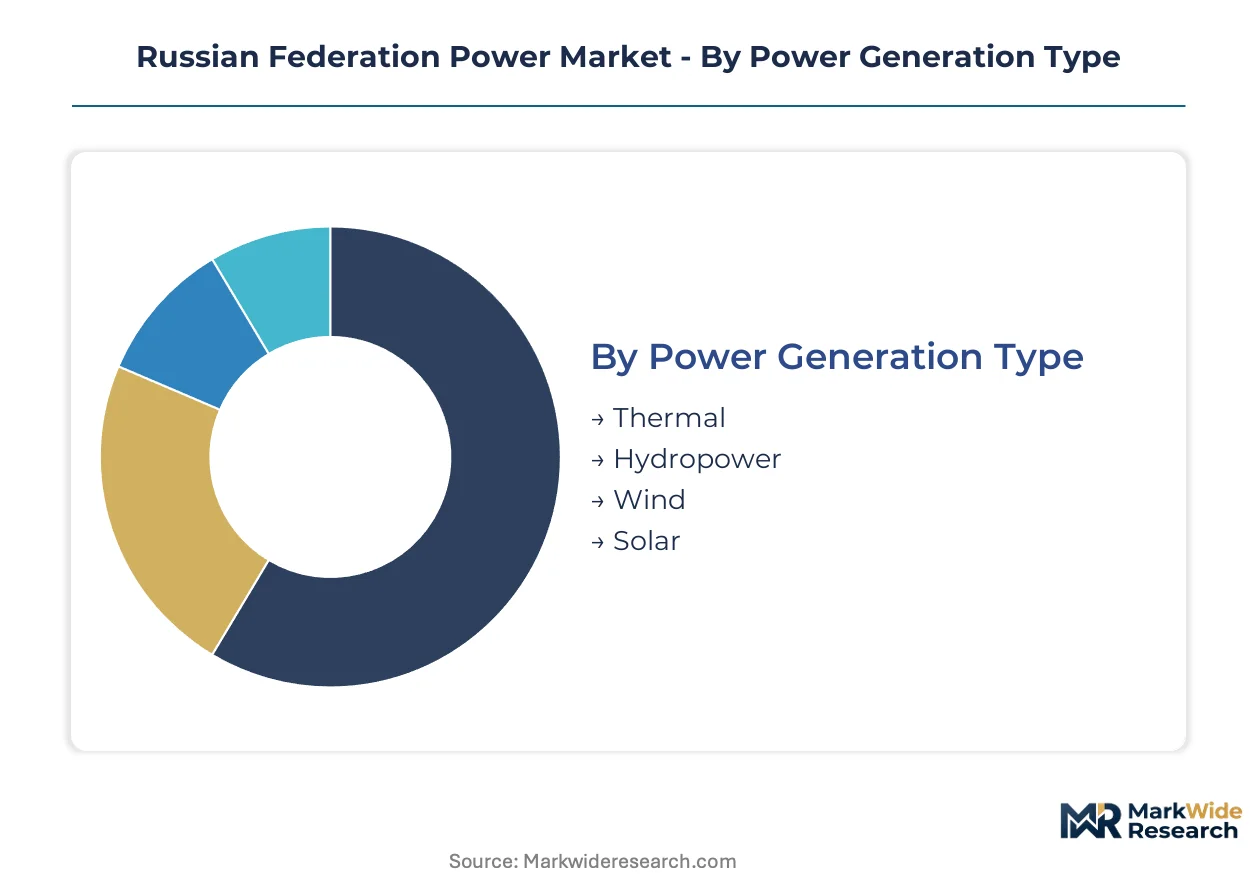
Russian power market segmentation reveals divergent investment horizons across generation technologies and ownership structures. Each category carries distinct regulatory exposure and capital recovery profiles that shape stakeholder entry strategies.
Power Generation Type:
Mature baseload technologies dominate installed capacity while emerging renewables capture policy-driven expansion mandates.
- Thermal:Natural gas, coal, and fuel oil plants provide steam-driven turbine rotation for grid-synchronous alternating current. Demand concentrates around Moscow's high-voltage ring and Volga industrial corridors where metallurgical clusters require baseload reliability. Gazprom PJSC anchors this segment through integrated gas-to-power value chains.
- Hydropower:Siberian cascade reservoirs deliver the highest capacity utilization rates due to minimal fuel cost exposure. RusHydro PJSC leverages vast Siberian hydropower assets to dominate renewable-class output. Krasnoyarsk and Bratsk aluminum smelters pull baseload power from these cascades.
- Wind:Developers navigate locational marginal pricing in Russia's European territory. Federal Grid Company permitting backlog for reactive power compensation studies delays project commissioning.
- Solar:Declining lithium-ion battery costs converge with net metering reforms to unlock commercial rooftop installations in Krasnodar Krai.
Thermal handles the majority of throughput; solar is expanding most quickly on share.
Technology:
Cost tier stratification separates established turbine architectures from niche renewable conversions.
- Gas Turbine:Aero-derivative and heavy-frame designs face specialized maintenance constraints as overhaul expertise concentrates among aging field engineers. Combined-cycle operators suffer margin compression from Gazprom PJSC's oil-indexed domestic tariffs.
- Hydroelectric:Siberian plant operators gain relative advantage from Ministry of Energy reforms indexing payments to actual availability rather than declared capacity. Extreme ambient temperature ranges force thermal competitors into steeper compliance curves.
- Biomass:Agricultural residue conversion remains marginal within Russia's primary energy mix.
- Geothermal:Kamchatka Peninsula hosts isolated development potential outside unified national grid synchronization.
Gas turbine technology commands the largest capital deployment; hydroelectric offers the steadiest regulatory preference.
End User:
Customer type determines voltage class access and contract structure flexibility.
- Industrial:Steel and aluminum smelters in Krasnoyarsk and Bratsk expand arc furnace capacity. Large offtakers in Chelyabinsk and Nizhny Novgorod now contract directly with independent generators under bilateral power purchase agreements.
- Residential:Moscow's high-voltage ring operators deploy gas-insulated switchgear to shrink footprint within existing substation fences.
- Commercial:Distributed solar-plus-storage configurations target creditworthy anchor loads in surplus generation regions.
- Agricultural:Irrigation pumping loads concentrate in Volga basin corridors with seasonal demand spikes.
Industrial offtakers generate the highest revenue per megawatt-hour; commercial segments are climbing the fastest on distributed generation adoption.
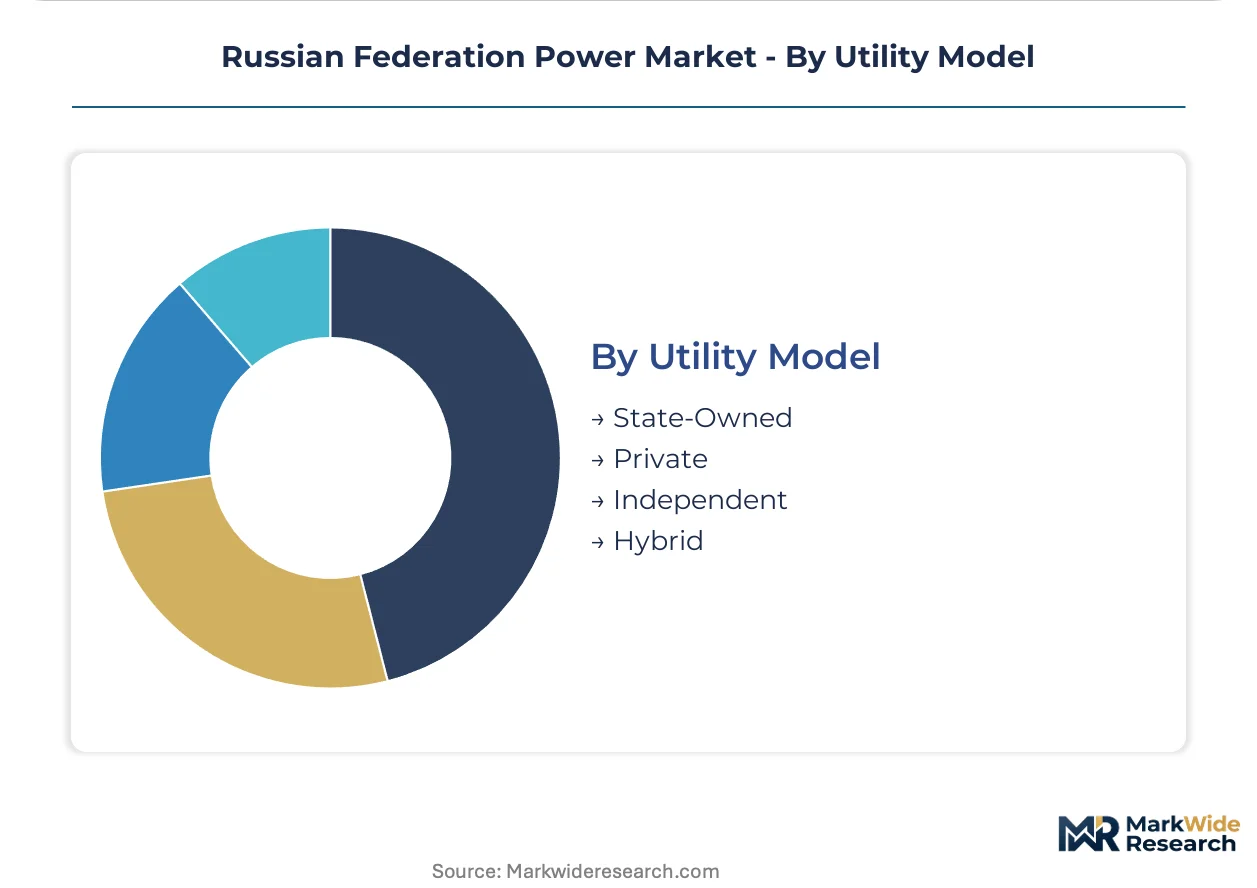
Utility Model:
Ownership concentration shapes access to state-backed capacity supply agreements and cross-border export licenses.
- State-Owned:Federal Grid Company mandates frequency stability and reactive power compensation standards that filter plant designs securing grid connection permits. Unified National Electric Grid's technical requirements determine generator revenue stability.
- Independent:Developers challenge legacy structures in wholesale electricity capacity markets. Direct contracting with industrial offtakers compresses trading margins for incumbent supply companies.
- Private:Merchant generators face exposure to oil-indexed gas tariff volatility without regulated cost pass-through mechanisms.
- Hybrid:Mixed ownership structures attempt to balance state-backed offtake security with operational efficiency incentives.
State-owned entities control transmission infrastructure access; independent generators are gaining share fastest through bilateral contract disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Unified National Electric Grid anchors Russia's power geography, stretching 2.3 million kilometers across eleven time zones and binding European demand centers to Siberian generation assets through 750 kV trunk lines.
Central Federal District
Moscow's high-voltage ring concentrates 18% of national electricity consumption across financial services and data center loads. The Ministry of Energy's capacity supply agreement reforms index payments to actual availability, forcing thermal generators into cold-weather reliability investments. Grid operators deploy gas-insulated switchgear within existing substation fences to shrink footprint in dense urban corridors.
Siberian Federal District
Krasnoyarsk and Bratsk aluminum smelters pull baseload power from RusHydro's Yenisei cascade, sustaining the highest capacity utilization rates nationwide. Federal Grid Company mandates frequency stability standards that filter which plant designs secure connection permits. Extreme ambient temperature ranges force thermal competitors into steeper compliance curves than hydropower assets.
Volga Federal District
Chelyabinsk and Nizhny Novgorod metallurgical clusters now contract directly with independent generators under bilateral power purchase agreements. The Federal Antimonopoly Service administers tariff regulation that determines generator revenue stability and investor payback periods. Large industrial offtakers bypass wholesale market intermediation, compressing trading margins for incumbent supply companies.
Far Eastern Federal District
Kamchatka and Sakhalin remain electrically islanded from the national grid, creating captive market structures for distributed generation developers. The Ministry of Energy's technical standards for reactive power compensation delay renewable project commissioning through permitting backlogs. Small modular reactor developers target these isolated load centers where transmission interconnection proves economically prohibitive.
Southern Federal District
Krasnodar Krai commercial rooftops unlock distributed solar-plus-storage installations as net metering reforms converge with declining lithium-ion battery costs. Federal Grid Company's grid connection queues for compensation studies strand merchant renewable projects in development pipelines. Agricultural irrigation loads concentrate in Volga basin corridors with seasonal demand spikes that reshape local dispatch priorities.
Russian Federation Power Market Competitive Landscape
On the supply side, the industry is consolidating around state-backed generation and transmission holding structures while independent developers carve bilateral contract niches. Gazprom PJSC and RusHydro PJSC anchor thermal and hydropower output respectively, their integrated value chains insulating against fuel price volatility. Three archetypes dominate: vertically integrated gas-to-power majors, cascade-holding renewable generators, and cross-border trading specialists. Competitive moves concentrate on securing capacity supply agreement offtake and obtaining export licenses to Kazakhstan and Baltic neighbors.
Within the state-owned generation tier, RusHydro PJSC exemplifies renewable-class dominance through Siberian cascade control, while Gazprom PJSC anchors thermal baseload through integrated fuel access. Inter RAO UES PJSC occupies a distinct position as the primary cross-border electricity trader, monetizing European Russia's thermal surplus through Baltic and Central Asian export slots. These three structures represent the fundamental competitive positions available to market participants: captive fuel integration, locational renewable advantage, or geographic arbitrage across asynchronous grids.
| Leading Market Players |
|---|
| RusHydro PJSC |
| Rosatom Corp |
| Gazprom PJSC |
| Rosseti PJSC |
| Inter RAO UES PJSC |
| Gazprom Energoholding |
| Unipro PJSC |
| T Plus Group |
| Power Machines |
| Others |
Value Network & Pricing Analysis
German and Japanese gas turbine OEM concentration upstream feeds directly into margin compression for Russian combined-cycle operators downstream, as equipment import dependency forces project sponsors to absorb currency and sanctions friction through extended depreciation schedules.
Pricing Analysis
Volume-discount tiering structures dominate capacity supply agreements, with the Ministry of Energy indexing payments to actual availability rather than declared capacity. Price differentiation rests on cold-weather start reliability certification and bilateral PPA anchoring with creditworthy metallurgical offtakers. Pricing pressure stems from oil-indexed domestic gas tariffs that compress thermal generator margins. Industrial offtakers in Chelyabinsk and Nizhny Novgorod exhibit lowest price sensitivity due to direct contracting leverage, while merchant renewable developers face acute sensitivity to locational marginal pricing volatility.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs now stretch to 24-36 months for heavy-frame gas turbine and generator set deliveries, reflecting supply-chain finance facilities absorbing sanctions-related counterparty risk. Manufacturing concentrates in Germany, Japan, and domestic Russian assembly facilities for lower-specification components. Critical dependencies include aero-derivative turbine blades, generator excitation systems, and 500 kV GIS switchgear. Single-source vulnerability runs through Siemens Energy and Mitsubishi Heavy Industries for advanced-class turbines. Distribution runs through Federal Grid Company-mandated technical qualification gates that filter equipment eligibility for grid connection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Russian Federation Power Market operates as a defensive-moat structure where regulatory entrenchment through capacity supply agreement administration creates switching costs that lock in generator revenue stability across decade-long payback periods.
For Market Incumbents: Harden cold-weather start reliability through synchronous condenser retrofits in Siberian thermal plants, insulating against Ministry of Energy availability-indexed payment reforms. Deepen backward integration into gas field development through Gazprom PJSC's integrated value chain, neutralizing oil-indexed tariff volatility that threatens combined-cycle margins. Consolidate bilateral PPA origination capacity in Volga industrial corridors before independent generators capture anchor load relationships.
For New Entrants and Emerging Players: Build out distributed solar-plus-storage configurations in Krasnodar Krai commercial rooftops, exploiting net metering reforms and declining lithium-ion battery costs that bypass Federal Grid Company connection queues. Target Kamchatka and Sakhalin islanded load centers where transmission interconnection economics fail, positioning small modular reactor or captive geothermal development as alternatives to diesel-fired generation. Lead with direct industrial offtake contracting rather than wholesale market intermediation.
For Investors and Strategic Acquirers: Capital is best deployed toward cascade-holding hydropower generators with locational renewable advantage and cross-border trading specialists monetizing European Russia thermal surplus through Baltic export slots. Long-term viability favors assets with captive fuel integration or geographic arbitrage positioning rather than merchant exposure. Watch Federal Antimonopoly Service tariff rebalancing signals as the inflection indicator for generator revenue stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Supply Agreement Optimization | Availability-indexed payment reforms force thermal generators into cold-weather reliability investments. |
| Cross-Border Export License Securement | Inter RAO UES PJSC monetizes European Russia thermal surplus through Kazakhstan and Baltic slots. |
| Digital Substation Architecture Deployment | Federal Grid Company mandates compress legacy protection relay markets while opening service revenue. |
| Gas-Insulated Switchgear Retrofit | Moscow high-voltage ring operators shrink footprint within existing fences, displacing Soviet-era AIS. |
| Bilateral PPA Direct Contracting | Chelyabinsk and Nizhny Novgorod metallurgical clusters bypass wholesale intermediation, compressing incumbent margins. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA data, IEA reports, FERC-equivalent filings, and project development databases. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided structured input across generation, transmission, and distribution segments. Bottom-up capacity and dispatch modeling triangulates against top-down regulatory flow analysis from the Ministry of Energy and Federal Antimonopoly Service.
Forecast inputs include fuel source segmentation, generation capacity tiering, project scale thresholds, regulatory framework evolution, and regional grid type classification across the analysis window. CAGRs derive from capacity addition pipelines, retirement schedules, and demand elasticity modeling for metallurgical and data center loads. Industrial electrification trajectories in Krasnoyarsk and Moscow's high-voltage ring anchor volume projections.
Stress conditions across sanctions friction, currency volatility, and equipment import disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding capacity supply agreement continuity and cross-border trade liberalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Norway Power Market
Power
Steam Turbine MRO Market
Power
Europe Power Purchase Agreement Market
Power
North America Power Market
Power
Wireless Power Receiver Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
HVDC Capacitor Market
Power
Angola Power EPC Market
Power
Saudi Arabia Power Market
Power
High Voltage DC Power System Market
Power
Canada Power Market
Power
LNG Power Barge Market
Power
Colombia Power Market
Power
Middle-East and Africa Power Market
Power
Wind Alarm Controller Market