
 Kuwait Power Market | 2026-2036
Kuwait Power Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Power Market Foresight
The premium utility-scale segment and commodity distributed generation tier is restructuring around divergent capital intensity and grid integration standards. ACWA Power International leverages its independent power project expertise to anchor large-scale renewable developments. Kharafi National S.A.E. competes across EPC and O&M services, sustaining diversified exposure to both conventional and emerging power infrastructure. Al-Ahleia Switchgear Co. K.S.C.C specializes in medium-voltage electrical equipment, occupying a defensible niche in domestic substation modernization.
Kuwait power encompasses electricity generation, transmission, and distribution infrastructure operating at 50 Hz with nominal voltages spanning 132 kV transmission down to 240 V residential delivery, primarily serving desalination, petrochemical, and urban cooling loads. Natural gas and solar photovoltaics dominate new capacity additions, with gas turbines retaining baseload reliability margins while utility-scale solar captures policy-backed procurement. Distributed generation remains nascent, constrained by regulatory ambiguity around wheeling tariffs and net metering frameworks that delay commercial and industrial self-supply adoption.
The Ministry of Electricity and Water enforces technical standards aligned with Gulf Cooperation Council grid codes, while the Environment Public Authority mandates emissions compliance for thermal plants under Kuwait's clean air regulations. The Public Authority for Industry oversees equipment certification through conformity assessment procedures that shape import access for switchgear and generation technology. Stakeholders must monitor how renewable purchase obligation implementation and independent water and power producer framework revisions alter project economics and procurement timelines.
Market Dynamics
Kuwait's power sector is reconfiguring around the Ministry of Electricity and Water's renewable procurement mandates, which force conventional gas turbine operators to absorb grid balancing costs while utility-scale solar captures priority dispatch rights under Vision 2035 targets.
Growth Catalysts
- Kuwait Vision 2035:The national development framework mandates 15% renewable electricity by 2035, directing capital toward Al-Jahra and Al-Ahmadi solar zones and creating guaranteed offtake pools for independent power producers.
- Seawater desalination expansion:Rising potable water demand from urban cooling loads and industrial users drives co-located power-desalination investments, favoring high-efficiency combined-cycle gas turbines with thermal desalination integration.
- Grid code harmonization:Gulf Cooperation Council technical standards for frequency regulation and voltage ride-through enable cross-border electricity trade and attract regional EPC contractors with transferable project execution capabilities.
Market Restraints
- Natural gas supply concentration:Kuwait relies on domestic gas fields and LNG imports for 85% of generation feedstock, exposing dispatch economics to global LNG price volatility and term contract renegotiation cycles.
- Land availability constraints:Utility-scale solar deployment competes with oil field infrastructure, military zones, and urban expansion for flat desert terrain, concentrating viable sites in designated renewable energy zones with transmission access limitations.
- Net metering ambiguity:The absence of finalized wheeling tariffs and distributed generation frameworks under Environment Public Authority guidelines blocks commercial and industrial self-supply adoption despite technical feasibility.
Strategic Opportunities
- Al-Jahra governorate cluster development:Sparsely populated western territory with high solar irradiance and existing 132 kV transmission corridors offers consolidated land parcels for gigawatt-scale photovoltaic parks with minimal resettlement friction.
- Battery energy storage convergence:Lithium-ion systems paired with solar plants can capture time-of-use arbitrage and provide synthetic inertia, addressing grid stability concerns that currently favor gas turbine retention.
- Independent water and power producer framework:Pending regulatory revisions to the IWPP model may permit foreign equity participation above current thresholds, unlocking project finance structures unavailable to state-owned developers.
Industry Challenges
- Grid integration engineering:High renewable penetration requires dynamic stability studies and synchronous condenser deployment that exceed local transmission operator experience, forcing reliance on international consultancy contracts.
- Equipment certification timelines:Public Authority for Industry conformity assessment procedures for medium-voltage switchgear and inverters extend procurement lead times, compressing construction windows before summer demand peaks.
- Thermal plant workforce transition:Gas turbine O&M specialists face skill obsolescence as solar and storage assets displace operating hours, creating retraining burdens for utilities with limited renewable asset management experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Power Market |
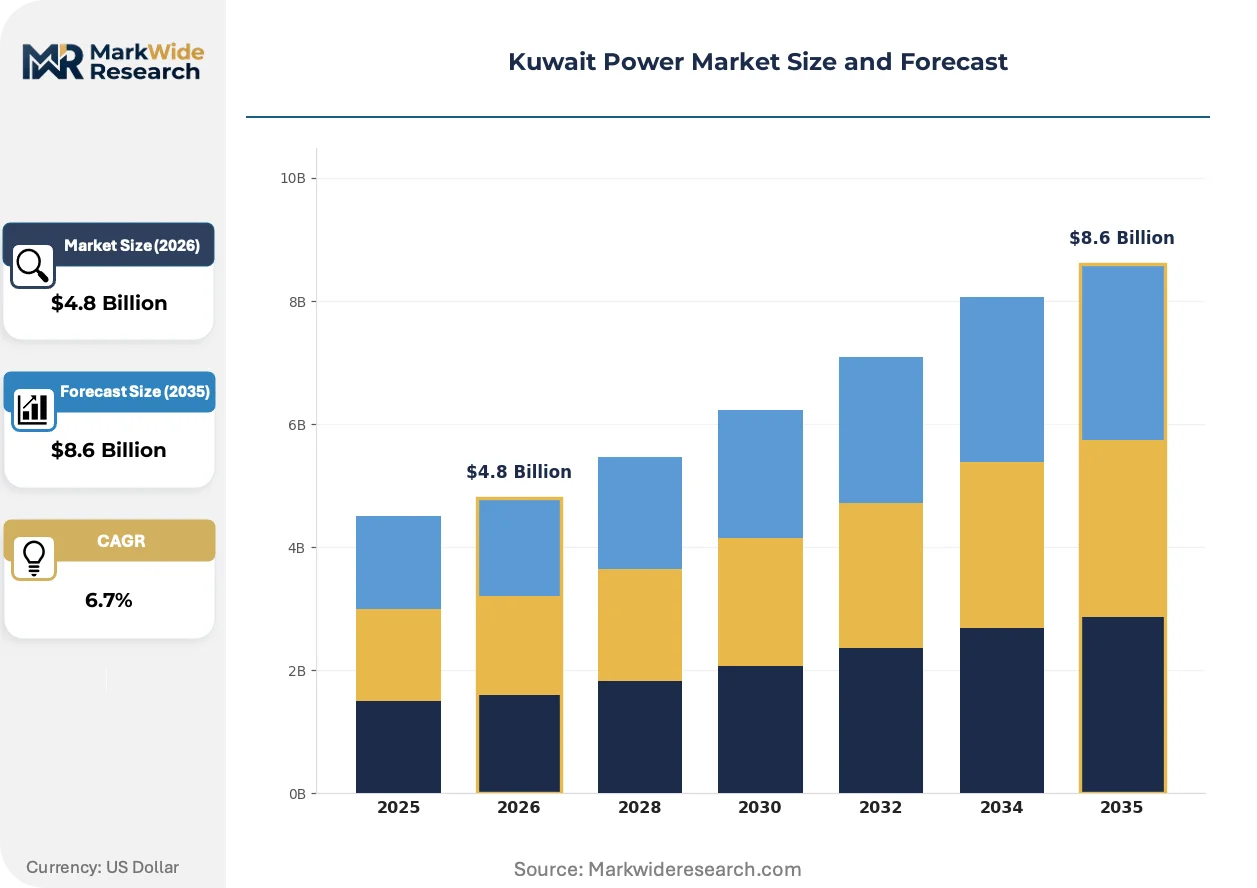
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Natural Gas, Oil, Coal Installation: Onshore, Offshore, Utility-Scale, Distributed Generation Technology: Wind Turbines, Solar Photovoltaics, Gas Turbines, Hydropower End User: Residential, Commercial, Industrial, Utilities |
| Companies Covered | Al-Ahleia Switchgear Co. K.S.C.C, ACWA Power International, Kuwait Petroleum Corporation, L&T-Sargent & Lundy Limited, Kharafi National S.A.E., General Electric Company, ABB Ltd, Kuwait National Petroleum Company, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Power Market Shifts & Advancements
Technology substitution and procurement model evolution are compressing conventional asset lifecycles while regulatory clarity around private participation reshapes project ownership structures across Kuwait's generation stack.
Single-axis tracking photovoltaic systems is overtaking fixed-tilt installations in utility-scale tenders. The technology increases capacity factors by 20-25% in Kuwait's high-direct-normal-irradiance conditions. Developers including ACWA Power International specify tracking hardware to minimize levelized cost and maximize bid competitiveness under long-term power purchase agreements.
Environment Public Authority emissions compliance mandates for thermal plants are tightening particulate and NOx limits under Kuwait's clean air regulations. Retrofit obligations are forcing aging gas turbine operators to evaluate selective catalytic reduction systems or early retirement. The Al-Ahmadi refinery power complex faces the steepest compliance costs given its 1980s-vintage steam turbine base.
Long-term service agreements are fragmenting into component-level contracts and predictive analytics subscriptions. Petrochemical buyers with captive power plants now unbundle turbine maintenance from OEMs, engaging third-party O&M specialists like Kharafi National S.A.E. for hot gas path inspections while retaining software diagnostics in-house. This pattern concentrates in the Shuaiba industrial corridor where multiple operators create competitive aftermarket pools.
Kuwait Power Market Segmentation
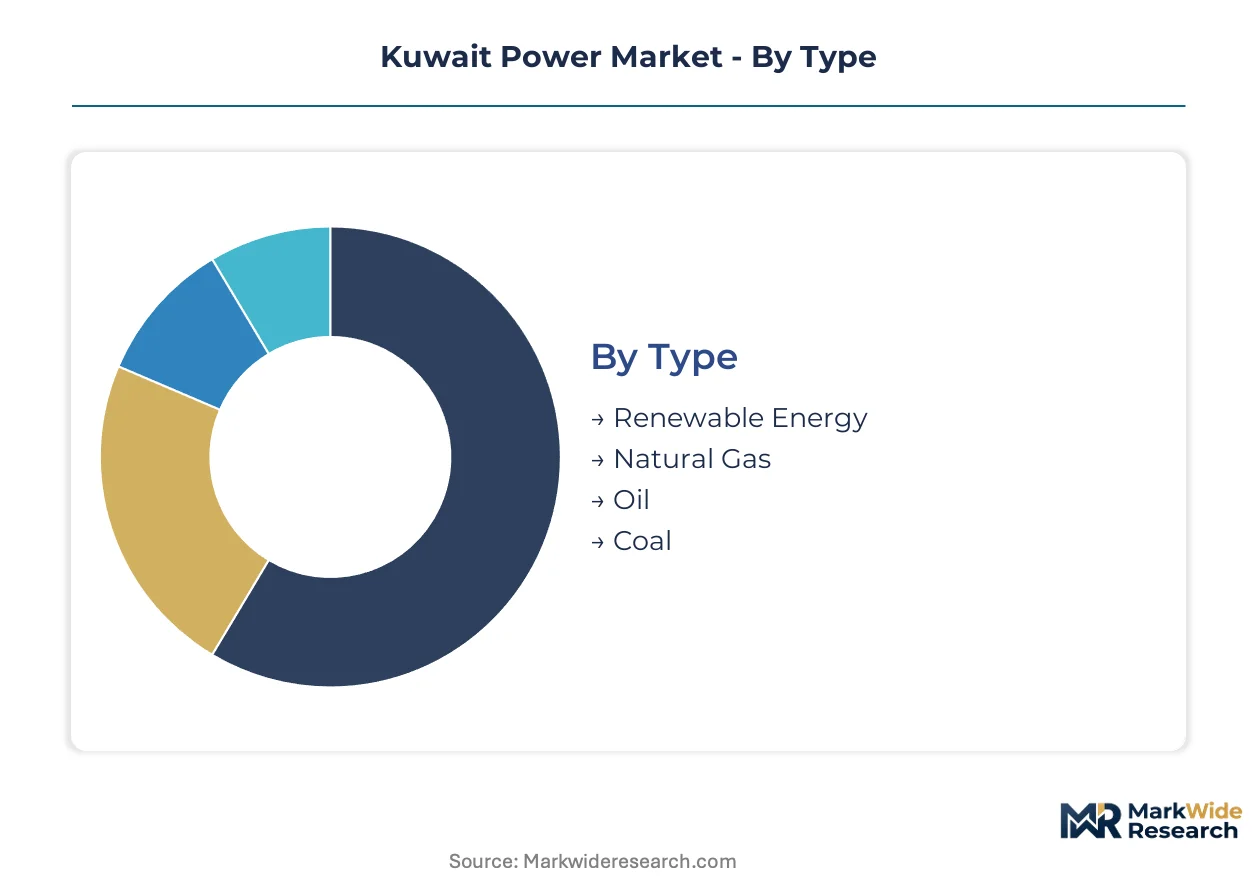
Kuwait's power market segmentation reflects divergent certification pathways and capital intensity across generation technologies. Each dimension carries distinct regulatory burdens from the Environment Public Authority and Public Authority for Industry that reshape procurement economics.
Type:
Public Authority for Industry conformity assessment procedures vary sharply by fuel source, with thermal plants facing emissions equipment certification that renewable projects bypass entirely.
- Renewable Energy:Solar photovoltaic arrays dominate new capacity, requiring only electrical equipment certification for inverters and switchgear rather than combustion-related approvals. Al-Jahra governorate hosts the largest project pipeline under Ministry of Electricity and Water procurement mandates.
- Natural Gas:Combined-cycle and simple-cycle gas turbines supply baseload reliability, subject to Environment Public Authority NOx and particulate limits that mandate selective catalytic reduction retrofits on vintage units. Feedstock supply contracts through Kuwait National Petroleum Company anchor project finance structures.
- Oil:Heavy fuel oil and crude-burning steam plants operate at Al-Ahmadi refinery complexes, facing the steepest emissions compliance costs under clean air regulations. These assets serve dual power-desalination loads with limited expansion potential.
- Coal:No operational coal capacity exists in Kuwait, with import infrastructure bans and environmental restrictions blocking development despite regional interest elsewhere in the Gulf.
Natural Gas sits at the top of the volume ranking, with Renewable Energy climbing the fastest.
Installation:
Capital deployment scale determines grid connection standards, with utility-scale projects triggering full Gulf Cooperation Council grid code compliance while smaller assets face simplified interconnection reviews.
- Onshore:All terrestrial generation assets fall under this classification, encompassing the entirety of Kuwait's operational fleet given the country's land-based geography. Transmission infrastructure at 132 kV and 275 kV serves these installations.
- Offshore:No offshore wind or marine energy projects are technically viable in Kuwait's shallow Gulf waters, leaving this segment dormant despite regional interest elsewhere.
- Utility-Scale:Projects exceeding 50 MW capacity trigger independent power producer framework negotiations and long-term power purchase agreements with the Ministry of Electricity and Water. ACWA Power International anchors development through competitive tenders.
- Distributed Generation:Commercial and industrial self-supply remains constrained by unresolved wheeling tariff frameworks under Environment Public Authority guidelines, blocking rooftop solar adoption despite technical feasibility.
Utility-Scale captures the dominant share of investment flows, with Distributed Generation expanding most quickly once regulatory clarity emerges.
Technology:
Equipment certification timelines from the Public Authority for Industry stretch longest for imported gas turbines, while solar hardware benefits from streamlined conformity assessment procedures.
- Wind Turbines:Kuwait's low average wind speeds and extreme summer temperatures render utility-scale wind economically unviable, with no operational capacity and minimal development interest.
- Solar Photovoltaics:Single-axis tracking systems capture priority dispatch rights under Vision 2035 targets, with capacity factors 20-25% above fixed-tilt alternatives in high-direct-normal-irradiance conditions across Al-Jahra and Al-Ahmadi zones.
- Gas Turbines:Heavy-duty and aeroderivative units provide frequency regulation and spinning reserves, with long-term service agreements fragmenting into component-level contracts as petrochemical buyers unbundle maintenance from OEMs.
- Hydropower:No riverine or pumped-storage hydro resources exist in Kuwait's arid terrain, eliminating this technology from the generation mix entirely.
Gas Turbines retain the largest installed base, with Solar Photovoltaics gaining share fastest through ministry-backed procurement.
End User:
Tariff structures and reliability requirements segment demand, with industrial buyers securing interruptible rates while residential consumers receive subsidized baseline allocations.
- Residential:Urban cooling loads drive summer peak demand, with 240 V single-phase delivery and consumption subsidies that suppress price signals for efficiency investment. The Public Authority for Housing Welfare influences electrification rates in new developments.
- Commercial:Retail and office segments face tariff rebalancing pressures as the Ministry of Electricity and Water targets cost-reflective pricing, accelerating interest in behind-the-meter solar once net metering frameworks finalize.
- Industrial:Petrochemical complexes at Shuaiba and Al-Zour operate captive power plants with dual fuel flexibility, engaging third-party O&M specialists for hot gas path inspections while retaining control system diagnostics in-house.
- Utilities:The Ministry of Electricity and Water remains the dominant offtaker, procuring capacity through competitive tenders and direct state investment while managing transmission assets at 132 kV and 275 kV voltage levels.
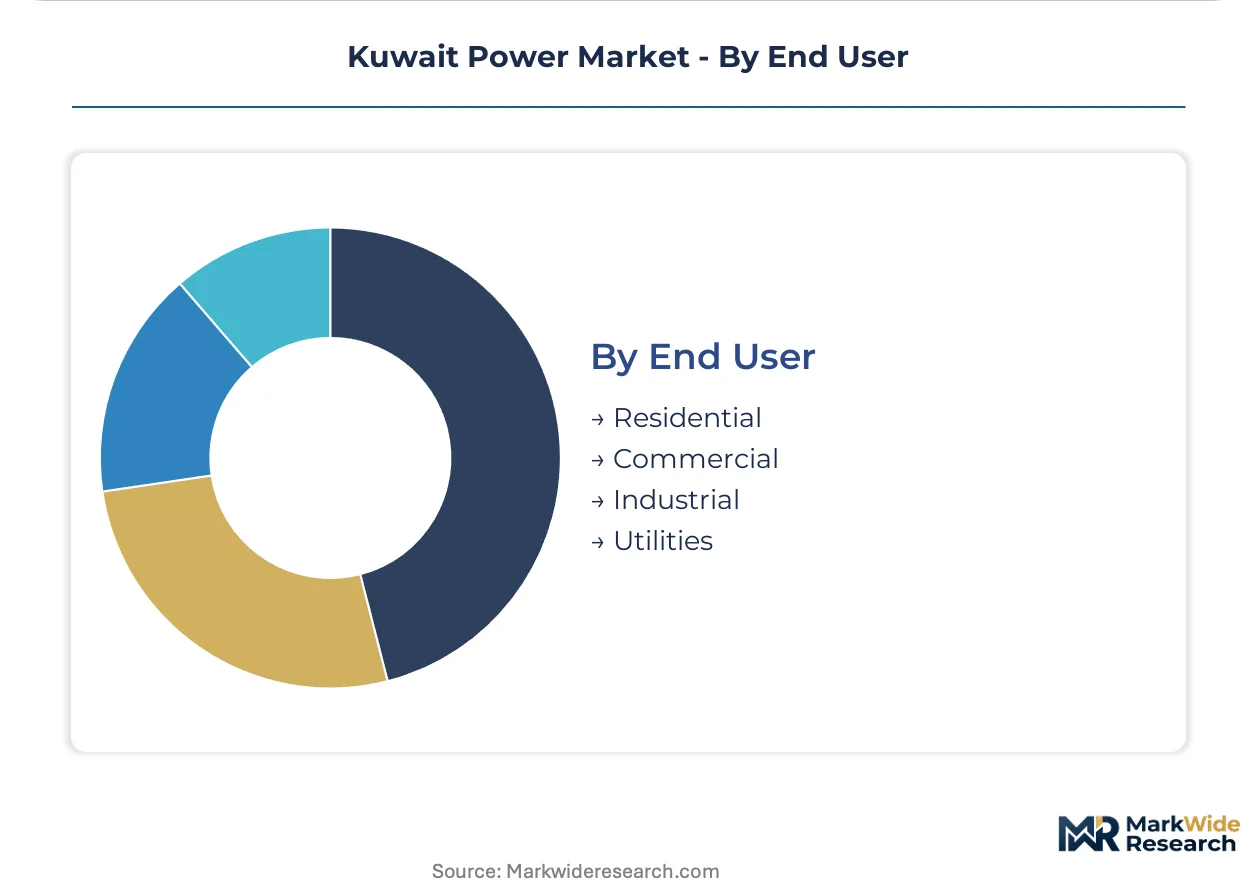
Utilities command the highest absolute consumption, with Industrial users showing the steepest efficiency-driven demand response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Al-Ahmadi and Al-Jahra governorates anchor Kuwait's power infrastructure deployment. Transmission specialists and solar EPC contractors cluster around Ministry of Electricity and Water procurement zones. Domestic workforce development programs target grid integration competencies to reduce reliance on international consultancy contracts.
Al-Ahmadi Governorate
Petrochemical complexes and refinery power demand drive baseload generation requirements. The Environment Public Authority enforces emissions compliance mandates for thermal plants under Kuwait's clean air regulations. The Shuaiba industrial corridor hosts multiple captive power operators engaging third-party O&M specialists for hot gas path inspections.
Al-Jahra Governorate
High solar irradiance and sparsely populated western territory enable gigawatt-scale photovoltaic development. Ministry of Electricity and Water procurement mandates direct capital toward designated renewable energy zones with existing 132 kV transmission corridors. Flat desert terrain offers consolidated land parcels for utility-scale solar parks with minimal resettlement friction.
Hawalli Governorate
Urban cooling loads and residential consumption peaks strain distribution infrastructure during summer months. The Public Authority for Housing Welfare influences electrification rates in new residential developments. Dense urban corridors require medium-voltage substation modernization to accommodate rising per-capita electricity intensity.
Capital Governorate
Commercial and financial services demand creates concentrated load centers with tariff rebalancing pressures. The Ministry of Electricity and Water manages transmission assets at 132 kV and 275 kV voltage levels from central operations. Grid control centers coordinate frequency regulation across the Kuwaiti network using gas turbine spinning reserves.
Mubarak Al-Kabeer Governorate
Desalination co-location opportunities attract combined-cycle gas turbine investments with thermal distillation integration. Kuwait National Petroleum Company feedstock supply contracts anchor project finance structures for power-water integrated facilities. Coastal positioning enables seawater intake infrastructure for dual-purpose thermal plants.
Kuwait Power Market Competitive Landscape
Capital-heavy asset developers compete with asset-light engineering contractors across Kuwait's bifurcated procurement landscape. The vendor base stratifies between integrated power project sponsors and specialized equipment suppliers. Three archetypes dominate: Gulf-based independent power producers with regional execution capabilities, European and Asian OEMs with long-term service agreement portfolios, and domestic switchgear specialists with Public Authority for Industry certification advantages. Competitive positioning hinges on ministry tender participation and conformity assessment timeline management.
Among independent power project developers, ACWA Power International anchors large-scale renewable developments through competitive procurement. Kharafi National S.A.E. exemplifies diversified EPC and O&M service providers sustaining exposure across conventional and emerging infrastructure. Al-Ahleia Switchgear Co. K.S.C.C occupies a defensible niche in domestic substation modernization, representing medium-voltage electrical equipment specialists with established certification pathways.
| Leading Market Players |
|---|
| Al-Ahleia Switchgear Co. K.S.C.C |
| ACWA Power International |
| Kuwait Petroleum Corporation |
| L&T-Sargent & Lundy Limited |
| Kharafi National S.A.E. |
| General Electric Company |
| ABB Ltd |
| Kuwait National Petroleum Company |
| Siemens AG |
| Others |
Supply & Pricing Matrix
LNG feedstock costs cascade through Kuwait's generation stack, with term contract renegotiation cycles at Kuwait National Petroleum Company compressing margins for gas turbine operators while solar EPC contractors capture fixed-price procurement advantages under Ministry of Electricity and Water tenders.
Pricing Analysis
The bundled-vs-unbundled service split separates OEM long-term service agreements from component-level third-party maintenance contracts. Pricing stratifies across premium, standard, and economy tiers based on equipment certification grade from the Public Authority for Industry and volume scale of generation assets. Cost compression in the distributed generation tier is intensifying because regulatory ambiguity around wheeling tariffs blocks commercial adoption despite technical feasibility. Industrial captive power operators at Shuaiba exhibit lowest price sensitivity due to dual fuel flexibility, while commercial buyers face highest sensitivity under tariff rebalancing pressures.
Supply Chain Analysis
Freight costs for heavy gas turbine components from Germany, Japan, and the United States anchor landed equipment pricing for combined-cycle projects. Solar photovoltaic hardware draws from China, South Korea, and Vietnam, with inverter and tracking system dependencies creating single-source vulnerability for single-axis tracking deployments. Distribution runs through Ministry of Electricity and Water procurement channels for utility-scale assets, while industrial buyers source directly through EPC contractors for captive installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's power market represents a late-cycle quality story as grid integration standards tighten and buyers prioritize Gulf Cooperation Council-certified equipment over uncertified alternatives.
For Market Incumbents: Anchor market position through selective backward integration into battery energy storage manufacturing and predictive analytics capabilities. Gas turbine operators must absorb grid balancing cost shifts as solar captures priority dispatch rights. Certification investment with the Public Authority for Industry defends substation equipment margins against Asian import competition.
For New Entrants and Emerging Players: Enter via the Al-Jahra governorate solar cluster where land availability and transmission access create consolidated development opportunities. The distributed generation segment offers most penetrable white space once Environment Public Authority finalizes net metering frameworks. Target industrial captive power buyers in the Shuaiba corridor with unbundled O&M service offerings.
For Investors and Strategic Acquirers: Consolidation pressure builds where equipment certification timelines stretch procurement lead times and compress construction windows. Long-term viability over the medium-term projection horizon favors developers with established Ministry of Electricity and Water tender relationships. Acquisition targets should demonstrate Public Authority for Industry conformity assessment capabilities. Monitor independent water and power producer framework revisions as inflection signal for foreign equity participation thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Al-Jahra solar zones absorb capital directed by Vision 2035 procurement mandates. |
| Power Purchase Agreement | Long-term offtake contracts with Ministry of Electricity and Water anchor project finance. |
| Technology Licensing | Single-axis tracking hardware licenses maximize capacity factors in high-irradiance conditions. |
| Backward Integration into Storage | Lithium-ion system integration addresses grid stability concerns favoring gas turbine retention. |
| Green Certification Program | Environment Public Authority emissions compliance creates retrofit obligations for thermal assets. |
Research Methodology
Multiple input streams — utility planning officer interviews, EPC contractor project databases, regulatory filing reviews — were reconciled to construct market size estimates. Primary discussions with IPP developers, grid operators, and fuel supply specialists were cross-checked against secondary sources including IEA country reports, FERC-style regulatory disclosures, and project development tracking databases. Bottom-up capacity addition tallies and top-down electricity demand forecasts were triangulated to resolve segmentation splits.
Historical deployment patterns were cross-referenced against panel input from procurement officers and transmission specialists to model capacity expansion across the projection horizon. Segmentation dimensions included fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from regression analysis of capacity commissioning timelines and policy implementation schedules. Forecast inputs incorporated Environment Public Authority emissions compliance timelines and Ministry of Electricity and Water tender release cadence.
The model holds under stable regulatory implementation; deviation in net metering finalization or IWPP foreign equity threshold adjustments would shift distributed generation and utility-scale investment proportions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Equatorial Guinea Power Market
Power
Germany Solar Inverter Market
Power
Flue Gas Desulfurization Unit Market
Power
Qatar Power Market
Power
Distribution Feeder Protection System Market
Power
Critical Power Market
Power
Asia-Pacific Package Substation Market
Power
Modular PSA Nitrogen Generator Market
Power
Single-Phase Microinverter Market
Power
Norway Power Market
Power
Water Turbine Market
Power
Global Advanced Marine Power Supply Market
Power
Rotating Phase Converter Market
Power
Middle-East and Africa Power Rental Market
Power
Asia-Pacific Power Market
Power
Asia-Pacific Power Purchase Agreement Market