
 United States Power Market | 2026-2036
United States Power Market Size, Share, and Industry Trends Forecast 2026-2036
United States Power Market Analytics
Data center electrification is recalibrating utility load forecasts across the United States, with hyperscale computing clusters now commanding multi-gigawatt procurement commitments. Duke Energy leverages its regulated utility footprint in the Carolinas to anchor long-term power purchase agreements with technology tenants. NextEra Energy sustains its renewable development pipeline through vertically integrated construction and operational platforms. Constellation Energy specializes in nuclear fleet uprates and clean hydrogen co-production to differentiate its baseload offering.
United States Power encompasses the generation, transmission, and distribution of electrical energy across alternating current networks operating at 60 Hz with standard voltages ranging from 120V residential service to 765kV extra-high-voltage transmission lines. The system delivers primary commercial purpose through reliable electrification of industrial machinery, building systems, transportation infrastructure, and digital networks. Renewable generation segments now lead capacity additions, with utility-scale solar and wind capturing dominant shares of new interconnection approvals. Distributed generation segments represent the fastest-growing structural category as behind-the-meter solar paired with battery storage reshapes residential and commercial demand patterns. Nuclear and hydropower segments occupy mature margin pools characterized by high capital intensity, extended asset lives, and regulated cost recovery mechanisms that insulate returns from wholesale price volatility.
FERC Order 2023 interconnection reforms and EPA greenhouse gas standards for existing power plants are reshaping investment timelines and technology selection criteria for utilities and independent developers. The Inflation Reduction Act production tax credits and investment tax credits, administered through IRS guidance and Treasury regulations, direct capital toward qualifying clean energy technologies while imposing domestic content requirements that reconfigure supply chain sourcing. State-level renewable portfolio standards in California, New York, and Illinois layer additional compliance obligations that fragment procurement strategies. Stakeholders must monitor interconnection queue reform implementation and evolving EPA compliance pathways to align capital deployment with regulatory certainty.
Market Dynamics
Data center electrification is compressing utility planning horizons across the United States, forcing grid operators to reconcile gigawatt-scale load commitments with decade-long interconnection timelines. ERCOT queue volumes in Texas now exceed 80 gigawatts of new demand requests, fundamentally restructuring how utilities procure capacity.
Growth Catalysts
- Inflation Reduction Act tax credits:Production tax credits and investment tax credits administered by Treasury redirect developer capital toward utility-scale solar and offshore wind installations with domestic content requirements.
- Hyperscale data center procurement:Technology tenants now execute multi-gigawatt power purchase agreements that anchor long-term revenue visibility for regulated utilities and independent generators.
- FERC Order 2023 interconnection reforms:Cluster study processes and ready-build criteria accelerate queue processing timelines for renewable and storage projects in congested transmission regions.
Market Restraints
- Transformer supply concentration:Domestic manufacturing capacity for extra-high-voltage transformers remains concentrated among three specialized producers, extending procurement lead times to 24-36 months.
- Interconnection cost allocation disputes:FERC Order 2023's cluster study cost-sharing mechanisms create regulatory friction between incumbent utilities and merchant developers over network upgrade liabilities.
- Natural gas price volatility:Henry Hub price swings transmit directly into marginal electricity costs across gas-dependent balancing authorities, compressing merchant generator margins.
Strategic Opportunities
- Offshore wind lease areas:Bureau of Ocean Energy Management lease auctions along the Atlantic Coast open development corridors with capacity factors exceeding 45 percent for coastal load centers.
- Nuclear fleet uprates and hydrogen co-production:Existing pressurized water reactor licenses support thermal output increases and electrolyzer coupling for industrial hydrogen offtake.
- Behind-the-meter storage aggregation:Virtual power plant platforms aggregate residential battery systems into dispatchable capacity resources for wholesale market participation.
Industry Challenges
- Transmission siting and permitting timelines:National Environmental Policy Act review processes and state-level certificate of public convenience requirements extend high-voltage line development to 8-12 years.
- Grid-forming inverter integration:Converter-interfaced renewable and storage resources require advanced controls to maintain frequency stability as synchronous machine inertia declines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Power Market |
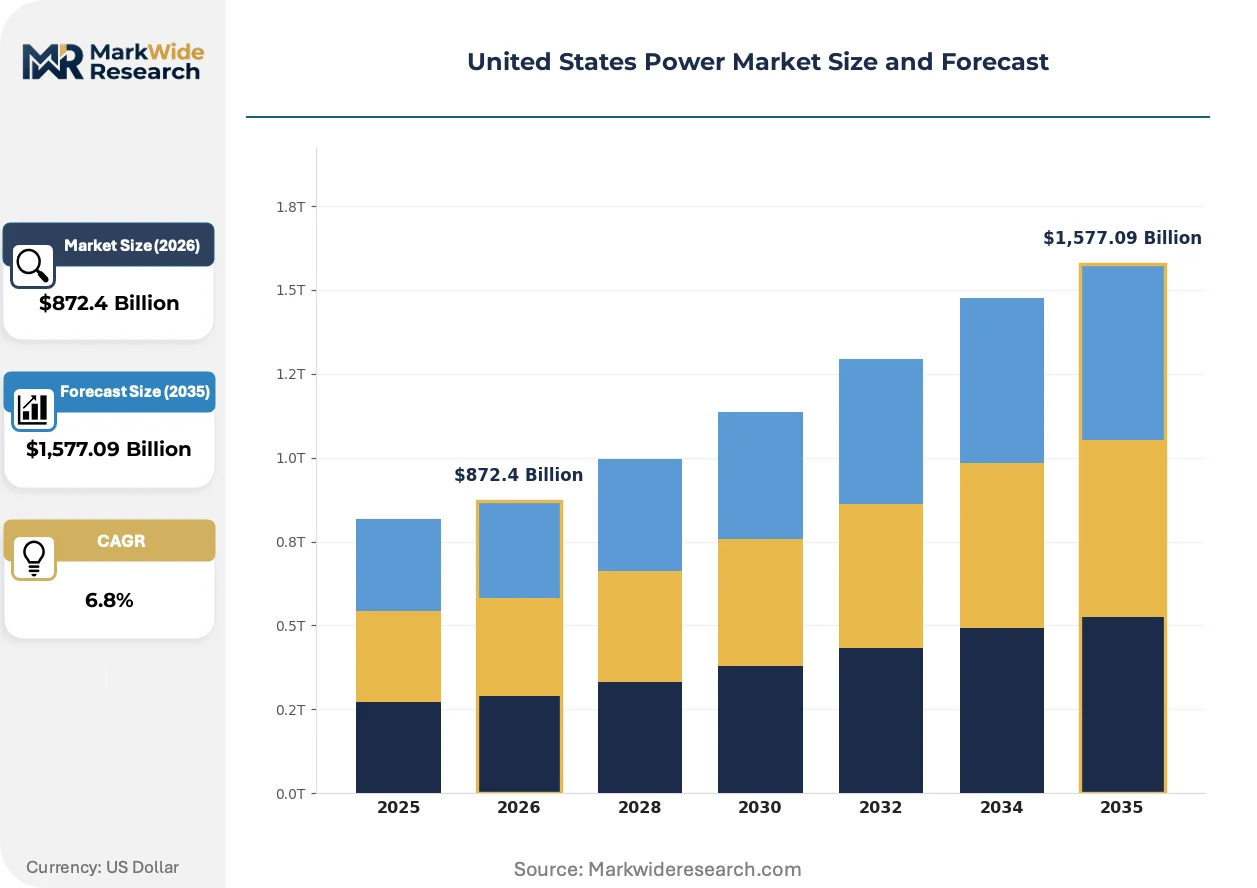
| Market Size in 2026 | $872.4 Billion |
| Market Size in 2035 | $1,577.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-renewable, Nuclear, Distributed Generation Application: Residential, Commercial, Industrial, Utility Technology: Solar, Wind, Hydropower, Biomass End User: Households, Corporations, Government Agencies, Educational Institutions |
| Companies Covered | GE Vernova, NextEra Energy, Southern Company, Constellation Energy, Duke Energy, American Electric Power, PG&E Corporation, Vistra Corp, Exelon Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Power Market Evolving Landscape
Battery energy storage systems are bridging the dispatchability gap between variable renewable output and firm capacity requirements, reshaping how utilities and grid operators manage intra-day price volatility and resource adequacy.
Grid-scale lithium-ion battery installations paired with solar photovoltaic arrays are integrating four-hour duration storage into resource stacks that compete directly with peaking combustion turbines. Merchant developers in Texas and California now procure battery systems as standard equipment, not supplemental technology. This integration is compressing the merchant peaker market and forcing gas turbine OEMs to reposition toward longer-duration flexible capacity.
EPA greenhouse gas standards for existing power plants impose emissions rate limits that accelerate coal retirement timelines while creating compliance pathways through co-firing, carbon capture retrofits, or clean energy replacement. The rule's best system of emission reduction framework triggers state implementation plan revisions. Coal-dependent utilities in the Midwest and Southeast face compressed capital allocation decisions between retrofit investments and accelerated renewable procurement.
Corporate offtakers now execute virtual power purchase agreements that separate contractual renewable energy credits from physical delivery, enabling data center operators to claim carbon-free electricity without locational matching. This financial contracting model displaces traditional utility green tariff programs. The shift is most visible in Northern Virginia and Dallas-Fort Worth, where hyperscale tenants dominate interconnection queue positions without requiring dedicated transmission infrastructure.
United States Power Market Segmentation
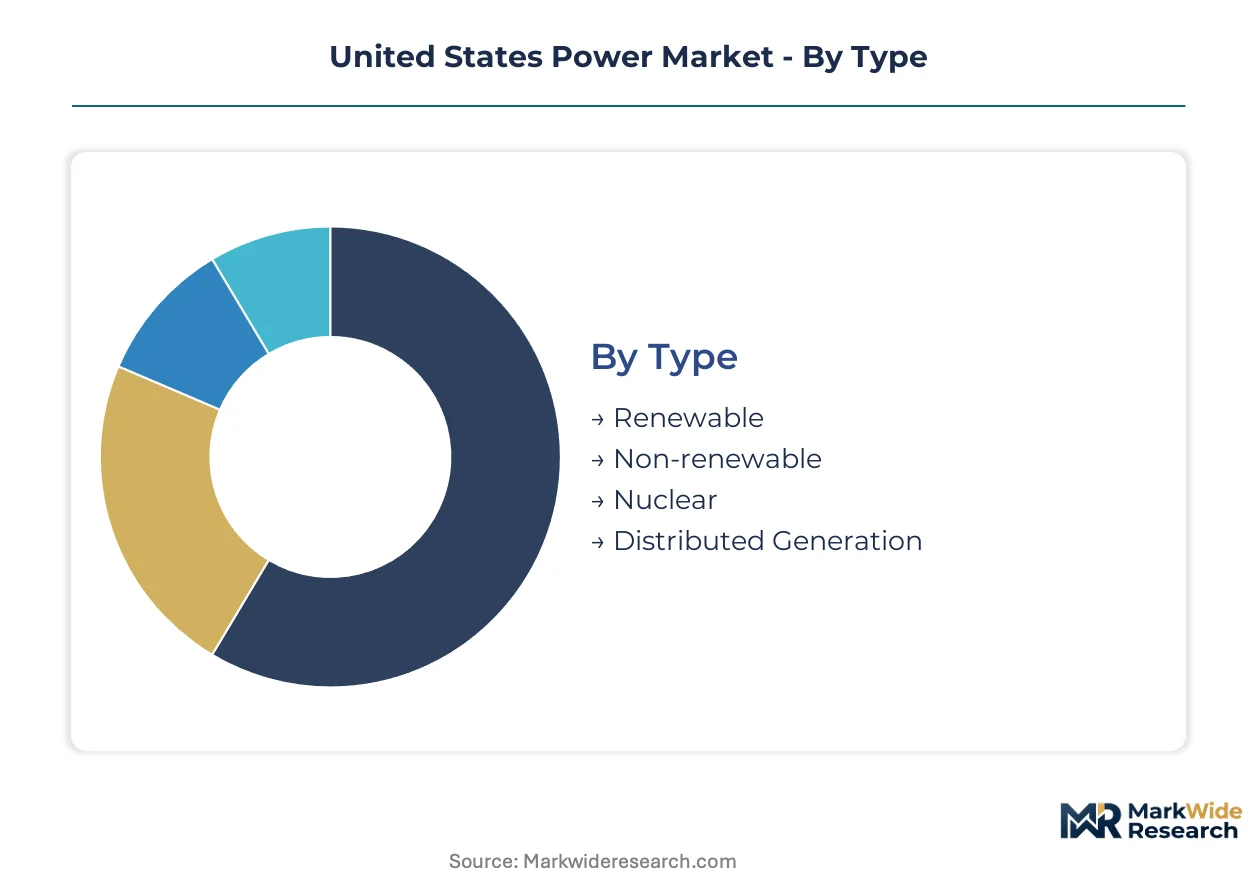
Power market segmentation reveals how capital allocation diverges across generation technologies, customer load profiles, and grid integration architectures. Each dimension carries distinct regulatory exposure, asset lifecycles, and procurement contracting norms that reshape competitive positioning for developers and utilities.
Type:
Supply concentration in generation equipment manufacturing varies sharply across these categories, with turbine and panel sourcing geography determining project viability timelines.
- Renewable:Utility-scale solar and wind installations dominate interconnection queue volumes, with photovoltaic module supply chains concentrated in Southeast Asian manufacturing hubs subject to U.S. tariff and domestic content rule exposure. ERCOT and CAISO balancing authorities absorb the majority of new renewable capacity seeking grid access.
- Non-renewable:Combined-cycle natural gas plants provide dispatchable capacity for residual load balancing, though Henry Hub price volatility compresses merchant developer returns and shifts utility procurement toward long-term tolling agreements with pipeline-integrated sponsors.
- Nuclear:Pressurized water reactor fleets operate under NRC license renewals extending to sixty-year asset lives, with uprate investments and hydrogen co-production pilot programs creating new revenue streams for existing baseload infrastructure.
- Distributed Generation:Behind-the-meter solar paired with lithium-ion battery storage reshapes distribution utility load profiles, with virtual power plant aggregations enabling residential assets to participate in wholesale capacity markets.
Today's leader: Non-renewable baseload. Tomorrow's challenger: Distributed generation aggregation platforms.
Application:
Customer scale determines tariff structures, reliability requirements, and behind-the-meter investment economics across the United States.
- Residential:Single-family and multifamily dwellings account for distributed solar adoption driven by net metering policies and time-of-use rate differentials, with battery attachment rates climbing fastest in California and Hawaii markets with high retail electricity rates.
- Commercial:Office buildings, retail centers, and warehouses execute on-site generation and demand response contracts to manage peak demand charges, with C&I solar procurement accelerating in states with avoided-cost ratemaking.
- Industrial:Manufacturing facilities and data centers command multi-megawatt direct access arrangements and behind-the-fence generation, with hyperscale computing loads in Northern Virginia and Dallas-Fort Worth recalibrating utility resource planning horizons.
- Utility:Investor-owned utilities, public power authorities, and electric cooperatives procure centralized generation through integrated resource plans subject to state public utility commission review, with renewable portfolio standards driving technology mix decisions.
Industrial load growth is expanding most quickly, though residential storage aggregation is gaining share fastest in regulated markets with advanced metering infrastructure.
Technology:
Equipment cost curves and resource availability constrain deployment potential for each conversion pathway.
- Solar:Crystalline silicon photovoltaic modules with single-axis tracking capture dominant shares of new capacity additions, with utility-scale projects achieving lowest levelized costs in Southwestern states with high irradiance and flat terrain.
- Wind:Onshore turbines exceeding three megawatts in nameplate capacity achieve capacity factors above forty percent in Great Plains wind corridors, while offshore lease areas along the Atlantic Coast require specialized installation vessels and transmission interconnection.
- Hydropower:Run-of-river and pumped-storage facilities provide firm capacity and ancillary services, though environmental permitting under the Federal Power Act constrains new dam construction and favors retrofit investments at existing sites.
- Biomass:Agricultural residue and dedicated energy crop combustion supplies baseload generation in rural regions with established feedstock supply chains, with anaerobic digesters capturing methane from livestock operations for distributed power production.
Solar technology commands current deployment volumes. Offshore wind represents the steepest expansion trajectory pending transmission infrastructure completion.
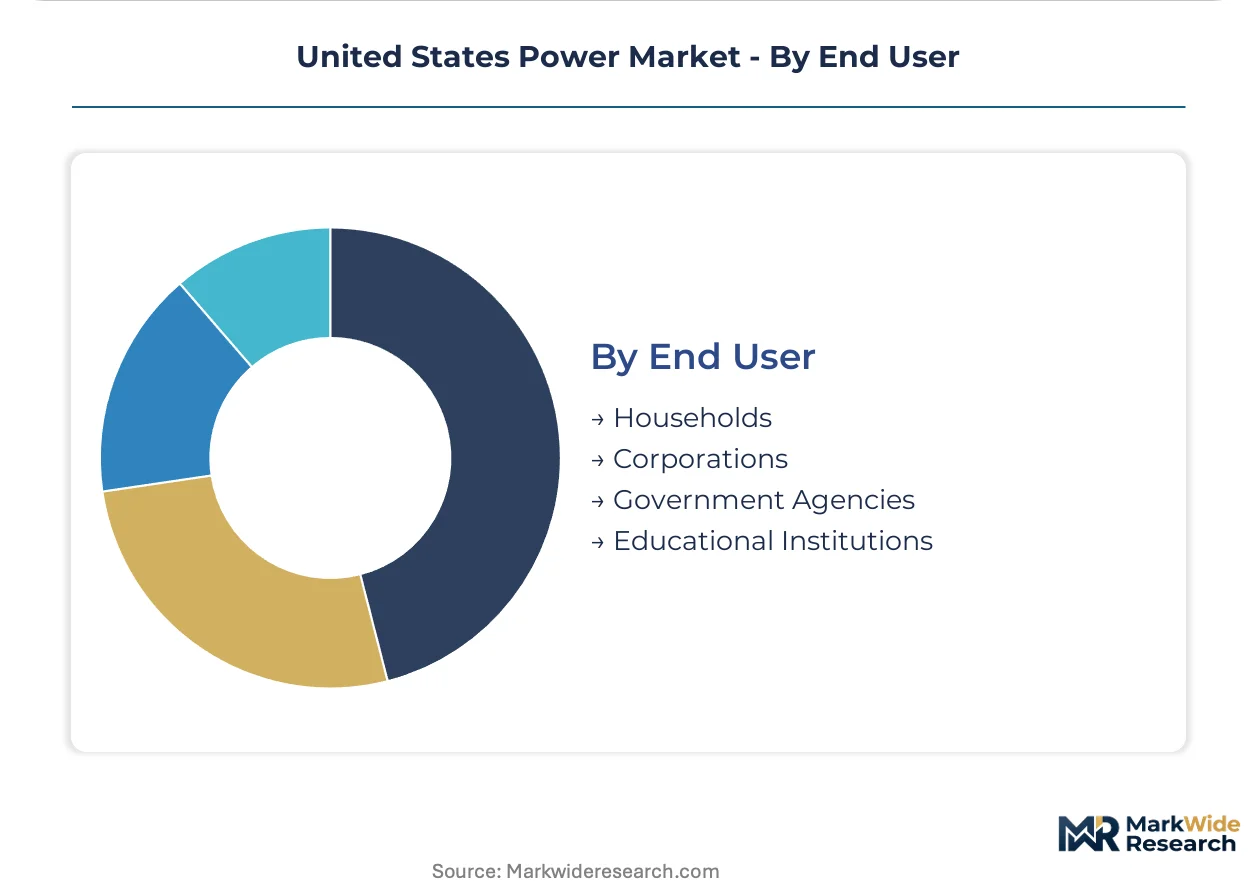
End User:
Procurement sophistication and creditworthiness vary across customer categories, shaping offtake contract structures and developer financing terms.
- Households:Residential ratepayers participate through utility green tariff programs and rooftop solar leases, with low-to-moderate income access programs expanding in states with equity-focused clean energy mandates.
- Corporations:Fortune 500 technology and retail tenants execute virtual power purchase agreements for renewable energy credit claims, with data center operators in Northern Virginia and Phoenix driving gigawatt-scale procurement commitments.
- Government Agencies:Federal facilities pursue energy savings performance contracts and renewable energy certificates to meet Executive Order carbon neutrality targets, with Defense Department installations prioritizing resilience through microgrid investments.
- Educational Institutions:Universities and K-12 districts deploy on-site solar and geothermal systems through tax-exempt municipal bond financing, with campus sustainability commitments accelerating behind-the-meter adoption.
Corporate offtakers anchor today's utility-scale renewable financeability. Government procurement holds tomorrow's challenger position through federal clean electricity purchasing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between state-level renewable mandates and wholesale market structures is redirecting power generation investment toward jurisdictions with accelerated permitting timelines and streamlined interconnection processes.
Texas
ERCOT interconnection queues now exceed 80 gigawatts of new demand requests, driven by hyperscale data center commitments in Dallas-Fort Worth and Houston. The state's merchant market structure and absence of capacity markets attract capital-intensive renewable and storage developers seeking price exposure. West Texas solar installations and South Texas coastal wind clusters anchor the nation's fastest-growing generation pipeline.
California
CPUC resource adequacy mandates and SB 100 carbon-free electricity targets compress procurement timelines for utility-scale solar-plus-storage. The CAISO duck curve has intensified as behind-the-meter solar penetration exceeds 15 percent of peak load. Northern Virginia data center operators now execute virtual power purchase agreements that separate renewable energy credits from physical delivery obligations.
Carolinas
Duke Energy's regulated utility footprint anchors long-term power purchase agreements with technology tenants seeking carbon-free electricity claims. North Carolina's renewable portfolio standard and South Carolina's Act 236 distributed generation incentives create complementary procurement pathways. Charlotte and Research Triangle Park data center clusters command multi-gigawatt load commitments.
New York
CLCPA mandates for 70 percent renewable electricity by 2030 accelerate offshore wind lease development along the Atlantic Coast. NYSERDA clean energy standard compliance obligations fragment utility procurement strategies between upstate wind and downstate transmission-constrained load centers. New York City peaker plant replacement programs drive battery storage siting in environmental justice communities.
Illinois
CEJA renewable energy credit pricing mechanisms and nuclear fleet preservation subsidies insulate Exelon's Illinois reactor assets from merchant market volatility. Chicago-area data center load growth recalibrates Commonwealth Edison distribution infrastructure planning horizons. The state's interconnection queue reforms align with FERC Order 2023 cluster study implementation timelines.
United States Power Market Competitive Landscape
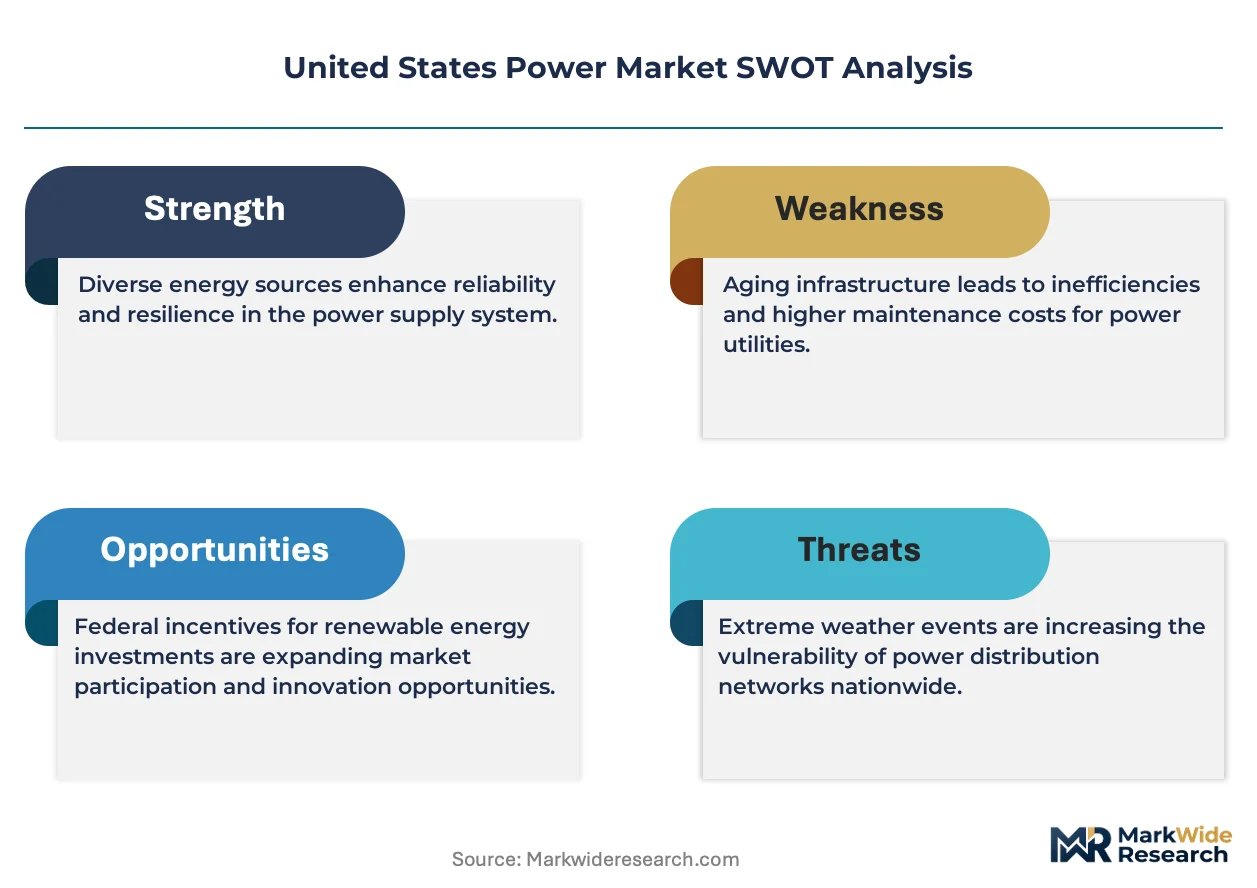
Capacity expansion through utility-scale renewable and storage project development dominates the current landscape, with developers racing to capture Inflation Reduction Act tax credits before domestic content requirements intensify. The vendor base stratifies across three tiers: vertically integrated utilities with regulated rate base advantages, independent power producers with merchant market exposure, and specialized renewable developers with construction and operational platforms. Strategic archetypes include transmission-anchored utilities, tax equity monetization specialists, and behind-the-meter aggregation platforms. Competitive moves center on interconnection queue positioning and long-term offtake contracting with creditworthy technology tenants.
Among integrated utility holding companies, NextEra Energy and Duke Energy exemplify the regulated-utility-plus-renewable-development archetype, while Constellation Energy occupies a position as the nuclear fleet uprate and clean hydrogen co-production specialist. These three entities anchor distinct strategic vectors within the competitive set, representing the premium-tier regulated utility, the scale-driven renewable developer, and the baseload differentiation specialist respectively.
| Leading Market Players |
|---|
| GE Vernova |
| NextEra Energy |
| Southern Company |
| Constellation Energy |
| Duke Energy |
| American Electric Power |
| PG&E Corporation |
| Vistra Corp |
| Exelon Corporation |
| Others |
Value Network & Pricing Analysis
Hyperscale data center operators anchor long-term power purchase agreements that compress merchant generator margins while elevating regulated utility rate base premiums. This buyer concentration forces developers to compete on contract duration and creditworthiness rather than spot market exposure.
Pricing Analysis
Long-term offtake contracting dominates developer revenue models, with price differentiation resting on interconnection queue position and renewable energy credit bundling. FERC Order 2023 cluster study cost allocation creates tiered exposure between ready-build and speculative projects. Pricing pressure stems from transformer supply bottlenecks extending procurement timelines. Industrial offtakers exhibit lowest price sensitivity due to carbon neutrality commitments, while merchant developers face acute margin compression from natural gas price volatility.
Supply Chain Analysis
Transformer refurbishment and remanufacturing flows are expanding as domestic extra-high-voltage manufacturing capacity concentrates among three specialized producers. Crystalline silicon photovoltaic modules draw from Southeast Asian assembly hubs subject to IRA domestic content rules. Rare earth permanent magnets for wind turbines hinge on Chinese processing concentration. Tariff exposure on imported battery cells creates single-source vulnerability for utility-scale storage projects. Distribution runs through EPC contractors with vertically integrated construction platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Power Market functions as a stable compounder underpinned by data center load growth that recalibrates utility resource planning across every major balancing authority.
For Market Incumbents: Lock in interconnection queue positions before FERC Order 2023 cluster study reforms accelerate competitive entry. Secure long-term power purchase agreements with hyperscale technology tenants to defend against merchant renewable developers. Deepen backward integration into battery storage system assembly to capture IRA domestic content credits and insulate against cell supply concentration. For New Entrants and Emerging Players: Virtual power purchase agreement platforms offer the lowest customer acquisition cost route into corporate renewable procurement. Target behind-the-meter residential storage aggregation in California and Hawaii where retail rate structures maximize arbitrage value. Pursue distributed generation partnerships with commercial real estate owners seeking peak demand charge reduction. For Investors and Strategic Acquirers: Regulated utilities with data center load exposure are the most active acquirer in this space, consolidating renewable development platforms to secure pipeline access. Nuclear fleet uprate specialists and offshore wind lease holders represent acquisition targets with contracted revenue visibility. Monitor ERCOT interconnection queue withdrawal rates as an inflection indicator for developer capital discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Interconnection Queue Positioning | ERCOT cluster study reforms reward developers with ready-build transmission access over speculative entrants. |
| Power Purchase Agreement Execution | Multi-gigawatt contracts with Northern Virginia data center operators anchor project financeability for utility-scale solar. |
| Domestic Content Compliance | IRA tax credit eligibility hinges on North American assembly of battery cells and photovoltaic modules. |
| Nuclear Fleet Uprate Investment | NRC license amendments enable thermal output increases that extend pressurized water reactor revenue streams. |
| Virtual Power Plant Aggregation | Residential battery dispatch platforms participate in CAISO wholesale markets as distributed energy resources. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining utility planning officer discussions, IPP project developer assessments, EPC contractor input, and grid operator perspectives with EIA generation data, FERC interconnection filings, IEA power system reports, and project development database validation. Bottom-up capacity addition modeling triangulated against top-down demand forecast reconciliation.
Historical capacity deployment patterns anchored projections across the analysis window, with segmentation modeling spanning fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derived from least-squares fitting of annual installation trajectories incorporated IRA tax credit phase-down schedules and EPA compliance pathway assumptions.
Interconnection queue reform implementation delays, transformer supply chain disruptions, and data center load commitment reversals are the dominant revision risks. Forecasts embed assumptions about FERC Order 2023 cluster study adoption timelines and IRA domestic content rule stringency. Practitioners should monitor ERCOT queue withdrawal rates and BOEM lease auction participation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Telecom Power Rental Market
Power
Wind Alarm Controller Market
Power
Gabon Power Market
Power
Asia-Pacific Power Market
Power
Electric Power Sports Market
Power
Global UPS Market
Power
North America Microturbine Market
Power
China Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Spain Power Market
Power
Modular PSA Nitrogen Generator Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
India Power Market
Power
Solar Plants Controllers Market
Power
Smart PV Inverters Market