
 Europe Microturbine Market | 2026-2036
Europe Microturbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microturbine Market Insights
Italy is reconfiguring its distributed generation supply base through investments in high-efficiency microturbine assembly. Ansaldo Energia leverages its gas turbine heritage to anchor utility-scale microturbine deployments across Southern Europe. Centrax Gas Turbines specializes in packaged power solutions that sustain industrial captive power demand in the United Kingdom. Aurelia Turbines Oy differentiates through oil-free bearing technology that competes on maintenance intervals in Nordic commercial installations.
A microturbine is a compact combustion turbine typically rated below 500 kW, employing a single-stage radial compressor and turbine mounted on a shared shaft with a permanent magnet generator operating at rotational speeds exceeding 50,000 RPM. The device converts gaseous or liquid fuel into electrical and thermal output for on-site industrial and commercial energy service. Natural gas configurations dominate installed capacity due to existing pipeline infrastructure and lower capital cost per kilowatt, while hydrogen-ready designs represent the fastest-growing product category as European gas networks plan blending mandates. Combined heat and power applications capture the largest margin pool by utilizing exhaust thermal energy for process steam or district heating, whereas backup power segments face price pressure from competing battery storage technologies.
EMA efficiency standards and the EU Green Deal carbon pricing framework are tightening operational emissions limits for distributed generation assets below 1 MW. F-Gas Regulation restrictions on fluorinated refrigerants affect thermal recovery system designs in CHP-integrated microturbines. CE marking and MDR-aligned pressure equipment directives govern market access for manufacturers exporting across the European Economic Area. Stakeholders must monitor hydrogen infrastructure build-out timelines and national renewable gas certification schemes to align product roadmaps with evolving fuel supply chains.
Market Dynamics
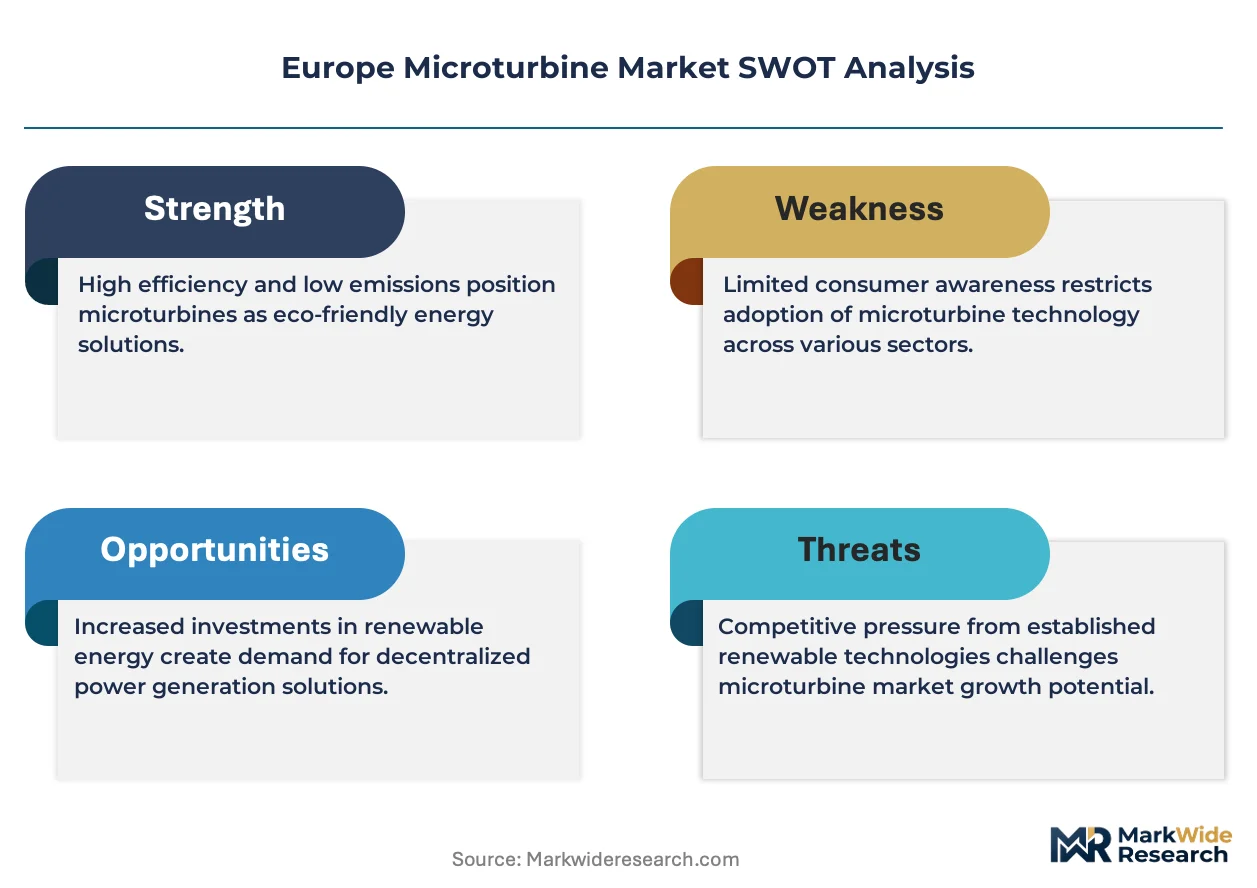
The EU Green Deal carbon pricing framework is forcing distributed generation asset operators below 1 MW to reconfigure thermal recovery systems and fuel sourcing strategies across industrial and commercial installations.
Growth Catalysts
- CHP Deployment Mandates:Industrial combined heat and power installations across Germany and Italy are expanding procurement of gas-fueled microturbine units to capture exhaust thermal energy for process steam applications.
- F-Gas Regulation Compliance:Restrictions on fluorinated refrigerants are accelerating redesign of thermal recovery systems in CHP-integrated microturbines to maintain operational permits.
- Grid Modernization Programs:Decentralized energy infrastructure prioritization in the Netherlands is channeling public investment toward on-site generation assets.
Market Restraints
- Input Cost Volatility:Natural gas price fluctuations compress project economics for pipeline-dependent configurations that dominate current installed capacity.
- Battery Storage Substitution:Lithium-ion backup power systems are capturing price-sensitive segments below 200 kW through declining cell costs and shorter deployment timelines.
- Supply Concentration Risk:Permanent magnet generator components concentrate among East Asian rare earth processors, exposing European assemblers to export control vulnerabilities.
Strategic Opportunities
- Hydrogen Infrastructure Build-Out:National renewable gas certification schemes in Germany and the Netherlands are creating certified demand for hydrogen-ready microturbine designs.
- Nordic Commercial Segment:Oil-free bearing technology is penetrating district heating networks in Finland and Sweden where maintenance interval requirements exceed Southern European norms.
- EMA Efficiency Standards:Tightening operational emissions limits for sub-1 MW assets are disqualifying legacy reciprocating engines from industrial captive power tenders.
Industry Challenges
- CE Marking Timeline Compression:MDR-aligned pressure equipment directives are extending certification cycles for manufacturers exporting across the European Economic Area.
- High-RPM Bearing Specialist Scarcity:Rotational speeds exceeding 50,000 RPM require precision manufacturing capabilities concentrated among a limited supplier base.
- Legacy Control System Integration:Existing SCADA architectures in industrial facilities demand custom protocol bridges for microturbine dispatch optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microturbine Market |
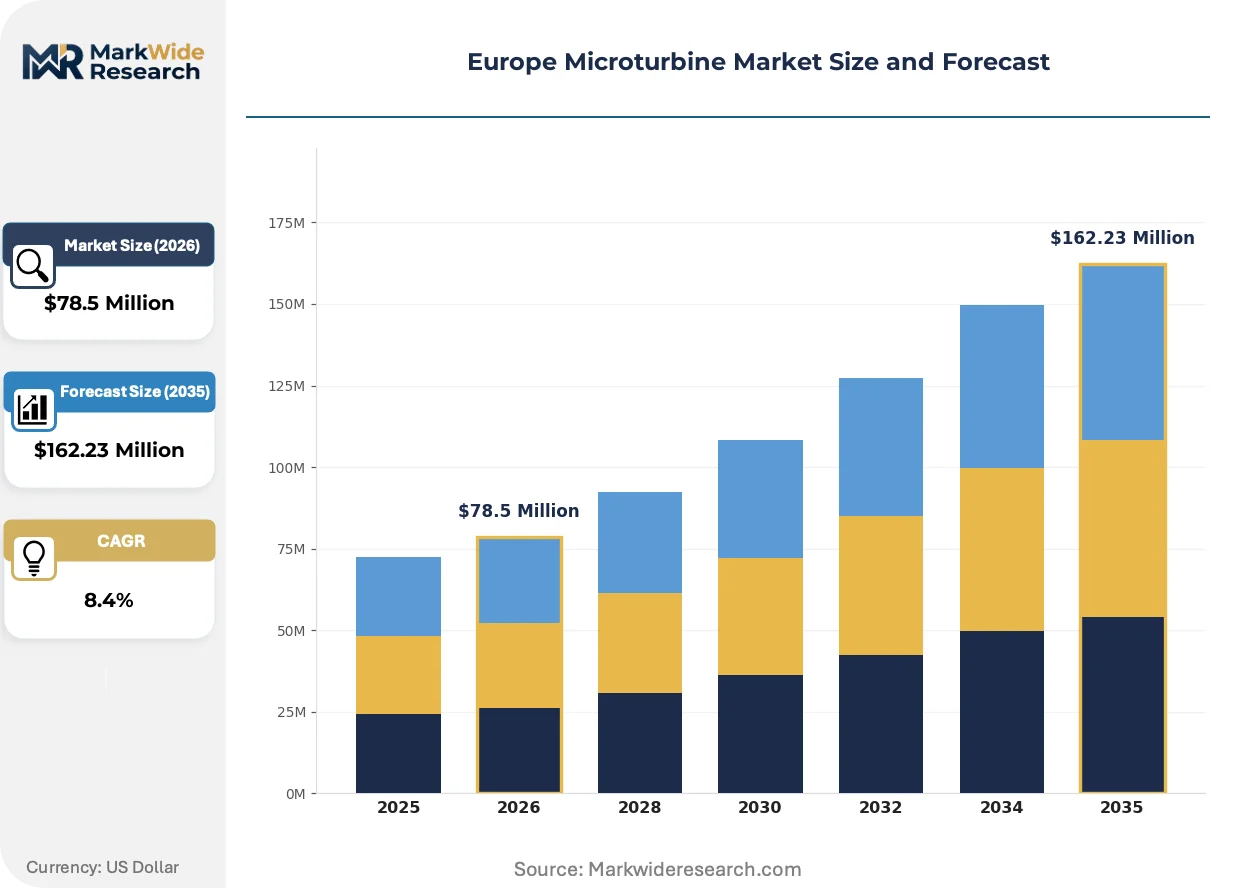
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $162.23 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas, Diesel, Renewable, Hydrogen End User: Industrial, Commercial, Residential, Military Application: Power Generation, Combined Heat and Power, Backup Power, Off-Grid Solutions Technology: Microgrid, Distributed Generation, Energy Storage, Gasification Technology |
| Companies Covered | Ansaldo Energia, Centrax Gas Turbines, MAN Energy Solutions, Micro Turbine Technology BV, Turbec, Aurelia Turbines Oy, Bowman Power Group Ltd, Eneftech Innovation SA, Bladon Microturbine, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microturbine Market Trends and Innovations
Active development of hydrogen combustion architectures is rendering obsolete conventional natural gas-only designs while regulatory pressure on fluorinated working fluids accelerates thermal system redesign.
Radial compressor designs with variable inlet guide vanes are rendering obsolete fixed-geometry configurations that cannot maintain efficiency across partial load profiles. Food processing facilities in Northern Italy are adopting these systems to match seasonal thermal demand swings. The technology is compressing margin pools for standard-efficiency units that cannot demonstrate turndown flexibility in utility interconnection negotiations.
F-Gas Regulation phase-down schedules are forcing refrigerant substitution in microturbine-integrated absorption chillers and heat pumps. Equipment manufacturers are redesigning thermal recovery loops to accommodate natural working fluids with higher pressure ratios. CHP-integrated installations in the Netherlands face the most acute compliance deadlines, driving accelerated procurement of redesigned heat exchange packages.
Energy service contracting is displacing direct equipment purchases among commercial building operators seeking to offload operational risk. Facility managers in German industrial parks are prioritizing heat-rate guarantees over capital expenditure control. This shift concentrates vendor selection criteria on demonstrated operational track records rather than upfront cost minimization.
Europe Microturbine Market Segmentation
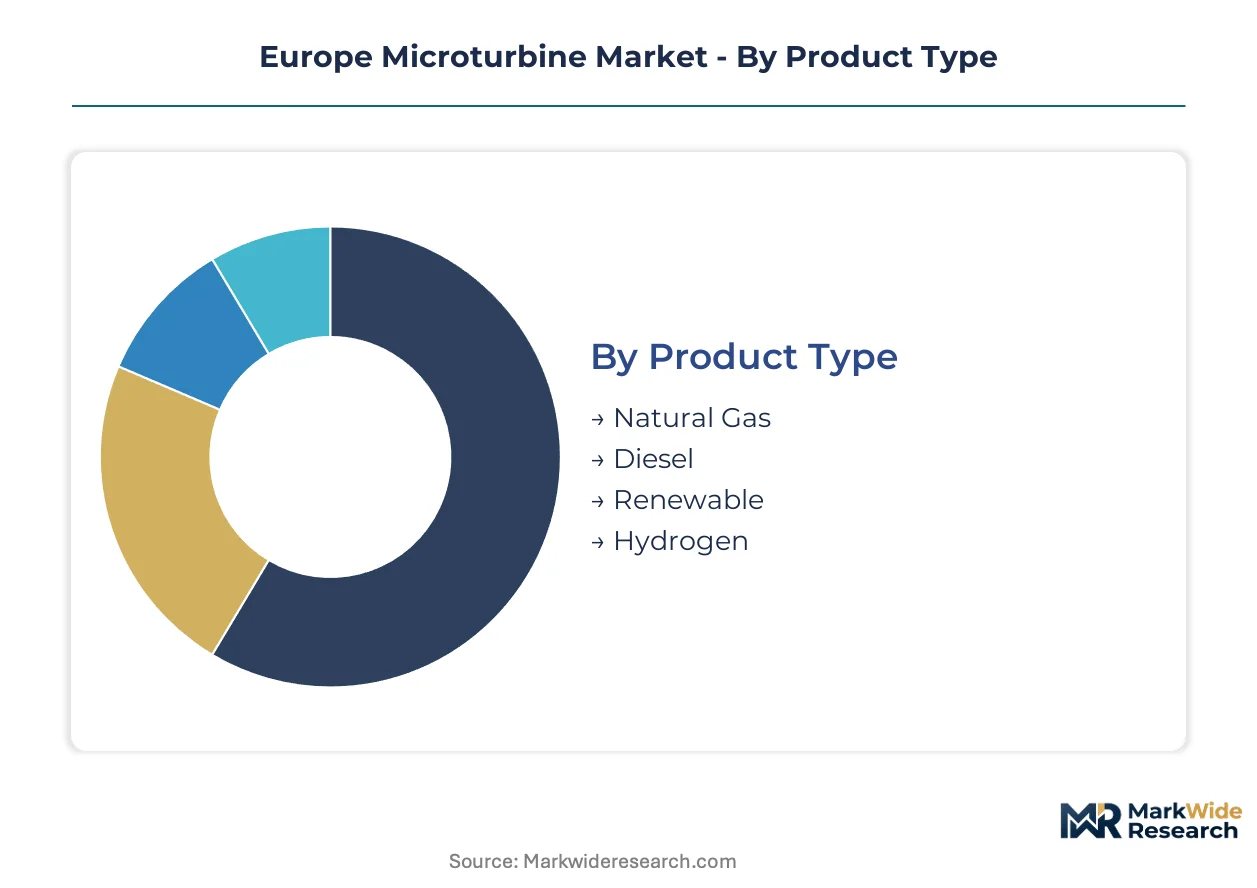
Microturbine procurement patterns diverge sharply across fuel types, end-use sectors, and integration architectures. European operators select configurations based on pipeline access, thermal load profiles, and grid interconnection standards that vary by member state.
Product Type:
Cost tier differentiation separates established pipeline fuels from emerging hydrogen-ready designs requiring modified combustion architectures.
- Natural Gas:Configurations leverage existing distribution infrastructure across Germany and Italy, with single-stage radial compressors optimized for methane calorific values. Industrial CHP installations in the Netherlands favor these units for baseload thermal supply where grid stability mandates prioritize proven dispatch reliability.
- Hydrogen:Hydrogen-ready designs incorporate modified fuel injectors and combustion liners to accommodate variable hydrogen blending ratios. German renewable gas certification schemes and Dutch hydrogen corridor investments are accelerating certified demand for these architectures as pipeline blending mandates approach implementation.
- Diesel:Liquid-fueled variants serve off-grid industrial sites lacking pipeline connectivity, particularly in remote Nordic processing facilities.
- Renewable:Biogas-optimized configurations with corrosion-resistant turbine coatings address agricultural and wastewater treatment applications.
Natural Gas commands the established base. The steepest expansion runs through Hydrogen.
End User:
Application scale and thermal load continuity determine customer-type prioritization across vendor sales organizations.
- Industrial:Food processing, chemical, and paper facilities deploy 250-500 kW units for process steam and mechanical drive applications. German industrial parks and Northern Italian manufacturing clusters represent concentrated procurement zones where energy service contracting models displace direct capital purchases.
- Commercial:District heating networks, hospitals, and data centers require high availability with maintenance intervals exceeding 8,000 hours. Nordic commercial operators in Finland and Sweden specify oil-free bearing technology to minimize lubrication-related downtime in remote installations.
- Residential:Single-family and small multi-family buildings below 50 kW represent limited addressable market due to capital cost barriers.
- Military:Forward operating bases and critical infrastructure protection drive demand for containerized, fuel-flexible units with blackout start capability.
Industrial deployments anchor current revenue concentration. Commercial district heating networks are gaining share fastest.
Application:
Margin pool distribution follows thermal energy utilization efficiency rather than electrical output alone.
- Combined Heat and Power:Exhaust thermal recovery for process steam, absorption chilling, or district heating maximizes fuel utilization rates above 80%. Dutch greenhouse operators and Italian food processors prioritize CHP-integrated configurations to satisfy EU Green Deal efficiency thresholds for sub-1 MW assets.
- Backup Power:Grid-islanded operation during utility outages serves critical facilities where battery duration limitations prove inadequate. German industrial captive power tenders increasingly disqualify reciprocating engines that fail EMA emissions standards, redirecting specification toward microturbine alternatives.
- Power Generation:Standalone electrical output without thermal recovery faces competitive pressure from solar-plus-storage configurations in commercial segments.
- Off-Grid Solutions:Remote mining, telecommunications, and agricultural processing sites deploy modular units where transmission extension proves uneconomical.
CHP applications dominate margin capture. Backup power specifications are climbing the fastest as grid reliability concerns intensify.
Technology:
Integration architecture determines control system complexity and utility interconnection negotiation leverage.
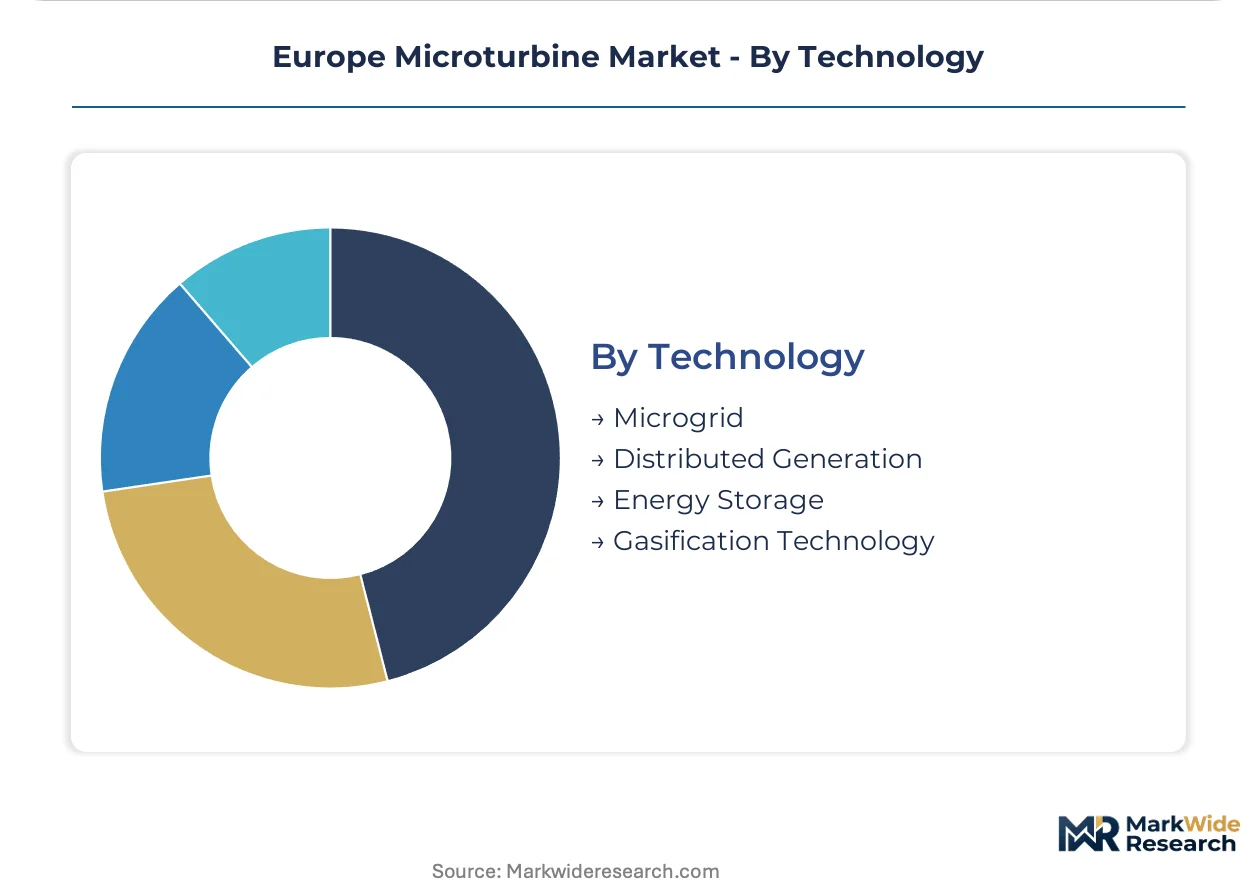
- Distributed Generation:On-site generation assets below 1 MW operate in parallel with utility distribution networks or in islanded mode. Netherlands grid modernization programs channel public investment toward decentralized infrastructure that accommodates bidirectional power flows and voltage regulation services.
- Microgrid:Multiple generation assets with integrated controls and storage provide resilience for industrial parks, military installations, and remote communities. Italian industrial clusters are deploying microgrid architectures to aggregate thermal and electrical loads across contiguous facilities.
- Energy Storage:Hybrid configurations pairing microturbines with batteries address load-following requirements and spinning reserve obligations.
- Gasification Technology:Solid fuel conversion to syngas enables biomass and waste-derived feedstock utilization in specialized industrial applications.
Distributed Generation holds the installed base majority. Microgrid integration is expanding most quickly as resilience premiums justify control system investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea hydrogen pipeline interconnects and Baltic grid reinforcement projects are underwriting Northern Europe's emergence as the primary demand center for decentralized generation assets.
Germany
Industrial parks in North Rhine-Westphalia and Bavaria are deploying 250-500 kW units for process steam under energy service contracting models. The national renewable gas certification scheme is accelerating certified demand for hydrogen-ready designs as pipeline blending mandates approach. Chemical clusters along the Rhine corridor are reconfiguring captive power supply bases to satisfy EU Green Deal efficiency thresholds.
Italy
Food processing facilities in Northern Italy are adopting variable inlet guide vane compressors to match seasonal thermal demand swings. The F-Gas Regulation phase-down is forcing refrigerant substitution in absorption chillers integrated with microturbine exhaust recovery. Ansaldo Energia anchors utility-scale deployments across Southern European industrial zones.
Netherlands
Greenhouse operators and district heating networks prioritize CHP-integrated configurations to maximize fuel utilization rates above 80%. Grid modernization programs channel public investment toward decentralized infrastructure accommodating bidirectional power flows. Dutch hydrogen corridor investments are creating certified demand for modified combustion architectures.
United Kingdom
Centrax Gas Turbines specializes in packaged power solutions sustaining industrial captive power demand across manufacturing clusters. The EMA efficiency standards are disqualifying legacy reciprocating engines from industrial tenders below 1 MW. Data centers in Greater London are specifying high-availability units with maintenance intervals exceeding 8,000 hours.
Finland
Aurelia Turbines Oy differentiates through oil-free bearing technology competing on maintenance intervals in Nordic commercial installations. District heating networks in Helsinki and Tampere specify these systems to minimize lubrication-related downtime in remote configurations. The technology penetrates markets where maintenance interval requirements exceed Southern European norms.
Europe Microturbine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in permanent magnet generators and high-RPM bearings. The vendor base organizes around three strategic archetypes: heritage turbine manufacturers leveraging gas turbine engineering legacies, packaged power specialists delivering turnkey industrial solutions, and technology disruptors advancing oil-free bearing architectures. Consolidation pressure concentrates among East Asian rare earth processors for generator components, while European assemblers defend position through hydrogen combustion licensing and energy service contracting partnerships.
Among heritage turbine manufacturers, Ansaldo Energia and MAN Energy Solutions occupy positions anchored to utility-scale engineering capabilities and industrial captive power heritage. Centrax Gas Turbines exemplifies the packaged power specialist archetype delivering turnkey solutions to United Kingdom manufacturing clusters. Aurelia Turbines Oy sits within the technology disruptor tier, representing Nordic innovation in oil-free bearing architectures for district heating applications demanding extended maintenance intervals.
| Leading Market Players |
|---|
| Ansaldo Energia |
| Centrax Gas Turbines |
| MAN Energy Solutions |
| Micro Turbine Technology BV |
| Turbec |
| Aurelia Turbines Oy |
| Bowman Power Group Ltd |
| Eneftech Innovation SA |
| Bladon Microturbine |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-RPM bearing manufacturing across Germany and Italy is compressing procurement timelines for European microturbine assemblers while simultaneously hardening price postures for precision components. This utilization squeeze propagates through vendor negotiations, forcing equipment manufacturers to absorb cost premiums or elongate delivery schedules for permanent magnet generator assemblies.
Pricing Analysis
The EU Green Deal carbon pricing framework dictates the pricing tier structure across European microturbine procurement, separating hydrogen-ready configurations commanding certification premiums from legacy natural gas units facing margin compression. Price differentiation rests on CE marking tier and thermal efficiency grade, with EMA-compliant CHP-integrated systems capturing standard-tier premiums against basic backup power alternatives. Cost compression in sub-200 kW segments is intensifying because lithium-ion substitution erodes addressable volume. Commercial district heating operators in Nordic markets exhibit lowest price sensitivity due to maintenance interval requirements, while industrial captive power buyers in Germany prioritize heat-rate guarantees over upfront capital minimization.
Supply Chain Analysis
Contract manufacturing for permanent magnet generator components concentrates among East Asian rare earth processors, with final assembly and combustion system integration anchored in Germany, Italy, and the United Kingdom. Raw material dependencies draw from neodymium-iron-boron magnet supply, precision steel forgings for radial compressors, and corrosion-resistant coatings for biogas-optimized turbines. Single-source vulnerability in rare earth element refining exposes European assemblers to export control disruptions. Distribution runs through energy service contractors and direct OEM relationships with industrial park operators, bypassing traditional equipment distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe microturbine market constitutes a defensive moat anchored in regulatory entrenchment, where EU Green Deal efficiency thresholds and F-Gas compliance deadlines erect certification barriers that disqualify non-specialized competitors from industrial tenders.
For Market Incumbents: Pre-empt hydrogen infrastructure lock-in by securing combustion architecture licensing agreements with German and Dutch pipeline operators before blending mandates activate. Deepen backward integration into precision bearing supply through partnerships with Nordic manufacturing specialists, countering East Asian rare earth concentration risk. Battery storage substitution below 200 kW demands accelerated CHP-integrated product positioning to defend margin pools in price-pressured segments. For New Entrants and Emerging Players: Build out oil-free bearing technology portfolios targeting Finnish and Swedish district heating networks where maintenance interval requirements exceed Southern European norms. The Nordic commercial segment offers lowest competitive density among established vendor archetypes. Energy service contracting partnerships with German industrial park operators provide the most penetrable go-to-market channel, displacing direct capital purchase friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogen-ready combustion architecture development, compressing returns for undercapitalized technology disruptors. Long-term viability over the coming decade hinges on demonstrated utility-scale deployment track records and renewable gas certification alignment. Acquisition targets should display packaged power integration capabilities and established EPC relationships. The signal to monitor is Dutch hydrogen corridor investment commitment levels as demand validation indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustion Licensing | Secures technology positioning ahead of German and Dutch pipeline blending mandates. |
| Backward Integration into Bearings | Reduces exposure to East Asian rare earth processor export control vulnerabilities. |
| Energy Service Contracting Expansion | Aligns vendor selection criteria with German industrial park operator risk-offloading preferences. |
| CE Marking Acceleration | Compresses certification cycles before MDR-aligned pressure equipment directives extend timelines further. |
| Nordic Commercial Segment Penetration | Captures district heating network specifications requiring oil-free bearing maintenance intervals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA data, IEA distributed generation reports, FERC interconnection filings, and European hydrogen corridor investment disclosures. Primary interviews engaged utility planning officers at German and Dutch grid operators, IPP project developers specializing in industrial CHP installations, EPC contractors active in North Rhine-Westphalia chemical clusters, and aftermarket service heads at packaged power specialists. Bottom-up unit deployment tracking across member states triangulates against top-down capacity expansion announcements from heritage turbine manufacturers.
Forecast inputs incorporate fuel source transitions, generation capacity tier migrations, project scale distributions, regulatory framework evolution, and regional grid modernization patterns across the analysis window. Segmentation modeling spans natural gas and hydrogen-ready product architectures, industrial and commercial end-use sectors, CHP and backup power applications, and distributed generation versus microgrid integration technologies. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and thermal efficiency premium capture.
Sensitivities concentrate around hydrogen infrastructure build-out delays, F-Gas Regulation phase-down acceleration, and rare earth supply disruption scenarios. Forecasts embed assumptions regarding EU Green Deal carbon pricing trajectory and national renewable gas certification scheme implementation pace. Quarterly review of Dutch hydrogen corridor investment commitments, German industrial park energy service contracting award volumes, and East Asian rare earth export license issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Power Capacitors Market
Power
Russian Federation Power Market
Power
North America Microturbine Market
Power
Brunei Power Market
Power
Power Rental Market
Power
Digital Power Utility Market
Power
Wireless Power Receiver Market
Power
Global UPS Market
Power
Existent Gum Steam Generator Market
Power
Wind Alarm Controller Market
Power
Electric Power Sports Market
Power
Electric Arc Furnaces Market
Power
United States Power Market
Power
Solar Plants Controllers Market
Power
Canada Thermal Power Market
Power
Angola Power EPC Market