
 Qatar Power Market | 2026-2036
Qatar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Power Market Analytics
Qatar's National Renewable Energy Strategy is repositioning utility procurement toward solar and hybrid gas-solar configurations. Mesaieed Power Company leverages its coastal infrastructure to sustain combined-cycle operations at scale. QatarEnergy anchors upstream fuel integration across generation assets. Ras Laffan Power Company dominates the industrial zone with captive desalination-linked capacity.
Qatar power encompasses electricity generation, transmission, and distribution infrastructure serving a desert economy with peak summer loads exceeding winter baselines by substantial margins. Gas turbines constitute the backbone of installed capacity, though steam turbine units serve combined water-power facilities at coastal complexes. Solar photovoltaic installations represent the fastest-expanding generation category as utility-scale projects displace incremental gas burn. Among end users, industrial offtake from LNG trains and aluminum smelters commands the largest share of megawatt-hour consumption and shapes seasonal demand patterns.
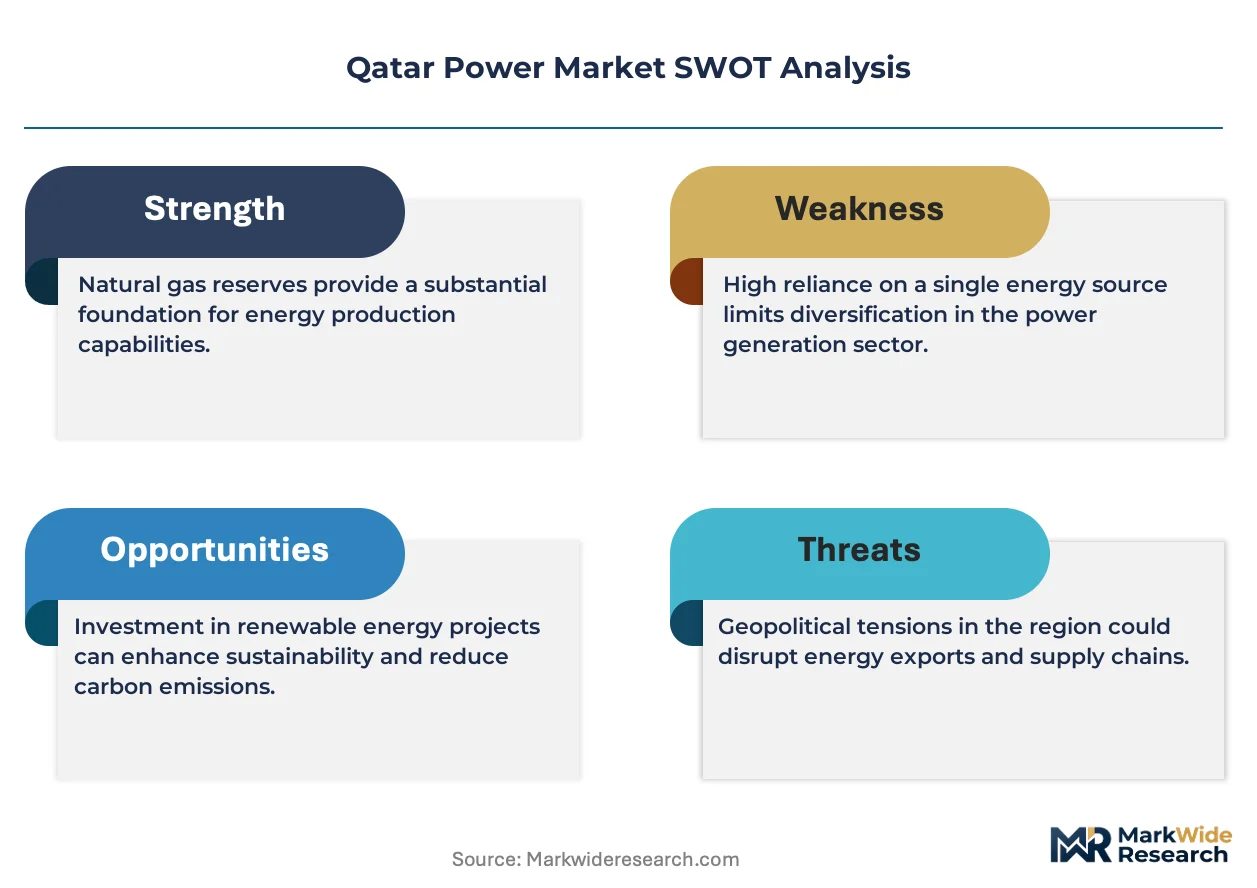
KAHRAMAA enforces grid codes and interconnection standards that determine market access for independent power producers. The Qatar General Electricity and Water Corporation coordinates with the Ministry of Municipality and Environment on emissions benchmarks for new capacity. Stakeholders must monitor how renewable procurement mandates interact with existing long-term gas supply agreements and desalination reliability requirements.
Market Dynamics
Qatar's power sector is pivoting from gas-dominant baseload toward solar-hybrid configurations as KAHRAMAA procurement mandates and National Renewable Energy Strategy targets force utility-scale capacity additions. This structural reconfiguration compresses conventional plant utilization while demanding grid flexibility investments.
Growth Catalysts
- KAHRAMAA Renewable Procurement Mandates:The national grid operator's solar integration requirements are redirecting independent power producer bids toward photovoltaic and battery storage hybrids. Developers must now demonstrate dispatchable clean capacity to secure long-term power purchase agreements.
- Ras Laffan Industrial Cluster Expansion:LNG train debottlenecking and gas-to-liquids capacity additions at this coastal zone are driving captive power demand. Desalination co-generation requirements lock in substantial baseload electricity offtake.
- Photovoltaic Cost Compression:Utility-scale solar engineering-procurement-construction pricing declines are enabling QatarEnergy to displace incremental gas burn for peak shaving. Module efficiency gains reduce land constraints in desert deployment contexts.
Market Restraints
- Gas Supply Contract Lock-In:Long-term take-or-pay agreements with North Field expansion phases constrain fuel-switching flexibility for existing combined-cycle assets. Penalty structures discourage early renewable displacement of contracted volumes.
- Desalination Reliability Requirements:Multi-stage flash distillation plants at Mesaieed and Ras Laffan require uninterrupted thermal energy input. Power system planners must maintain spinning reserve margins that solar intermittency complicates.
- Skilled Technician Scarcity:Concentrated solar thermal and battery inverter maintenance expertise concentrates with EPC contractors rather than local O&M workforces. Training pipeline gaps delay plant commissioning schedules.
Strategic Opportunities
- Al Kharsaah Solar-Storage Hybrid Expansion:The 800 MWac photovoltaic plant with co-located battery systems demonstrates bankable template for subsequent utility-scale tenders. Developers can replicate engineering configurations across Qatar's western corridor.
- Green Hydrogen Export Infrastructure:Ammonia synthesis facilities at Ras Laffan could absorb surplus solar generation during daylight hours. Electrolyzer load flexibility would monetize otherwise curtailed photovoltaic output.
- Smart Grid Digitalization:Advanced metering infrastructure deployments enable demand response participation from commercial and industrial loads. KAHRAMAA's grid code revisions accommodate distributed energy resource aggregation.
Industry Challenges
- Legacy Gas Turbine Cycling Stress:Daily ramping requirements to accommodate solar duck curves accelerate hot gas path degradation in existing combined-cycle units. Maintenance intervals compress as start-stop frequency rises.
- Interconnection Standard Harmonization:Inverter-based renewable assets must meet evolving KAHRAMAA fault ride-through and frequency response specifications. Certification testing timelines delay commercial operation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Power Market |
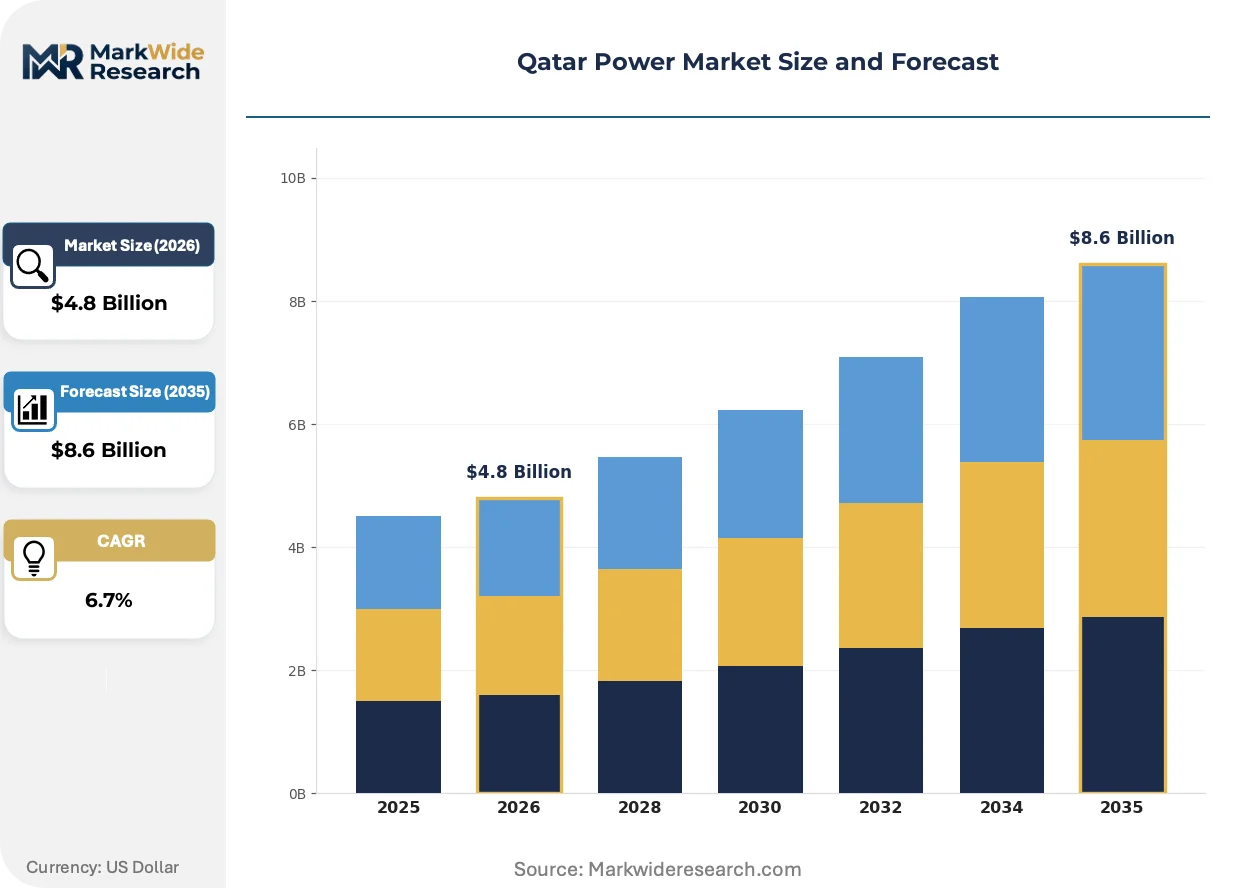
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Generation Type: Gas Turbine, Steam Turbine, Diesel Generators, Solar Photovoltaic End User: Industrial, Commercial, Residential, Government Service Type: Maintenance, Installation, Consulting, Operations Technology: Renewable Energy, Conventional Power, Smart Grid, Distributed Generation |
| Companies Covered | Mesaieed Power Company, Total Energies, Qatar General Water & Electricity Corporation (KAHRAMAA), ExxonMobil, Shell, Nebras Power, QatarEnergy, ConocoPhillips, Ras Laffan Power Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Power Market Evolving Landscape
Qatar's electricity system is undergoing technology substitution and procurement reinvention as renewable mandates intersect with industrial load growth. Three developments are compressing conventional asset lifecycles and rewiring competitive positioning.
Bifacial photovoltaic modules with tracking systems are converging with utility-scale deployment economics in Qatar's high-irradiance desert environment. KAHRAMAA's independent power producer tenders now specify dual-sided panel configurations as baseline technical requirements. This technology convergence is compressing levelized cost thresholds and forcing engineering-procurement-construction contractors to optimize DC/AC ratios for summer peak capture.
Qatar's National Renewable Energy Strategy mandates are tightening emissions benchmarks for new capacity through coordination with the Ministry of Municipality and Environment. Combined-cycle developers must now submit carbon intensity disclosures alongside tariff bids. Industrial zone offtakers at Ras Laffan face procurement pressure to document Scope 2 reductions for LNG export certification requirements.
Long-term power purchase agreement structures are fragmenting as KAHRAMAA experiments with shorter-tenor renewable tenders and merchant exposure tranches. Independent power producers must now underwrite merchant risk for portions of solar output beyond contracted baseload. This contracting evolution concentrates development capital with sponsors possessing balance sheet capacity to absorb merchant price volatility.
Qatar Power Market Segmentation
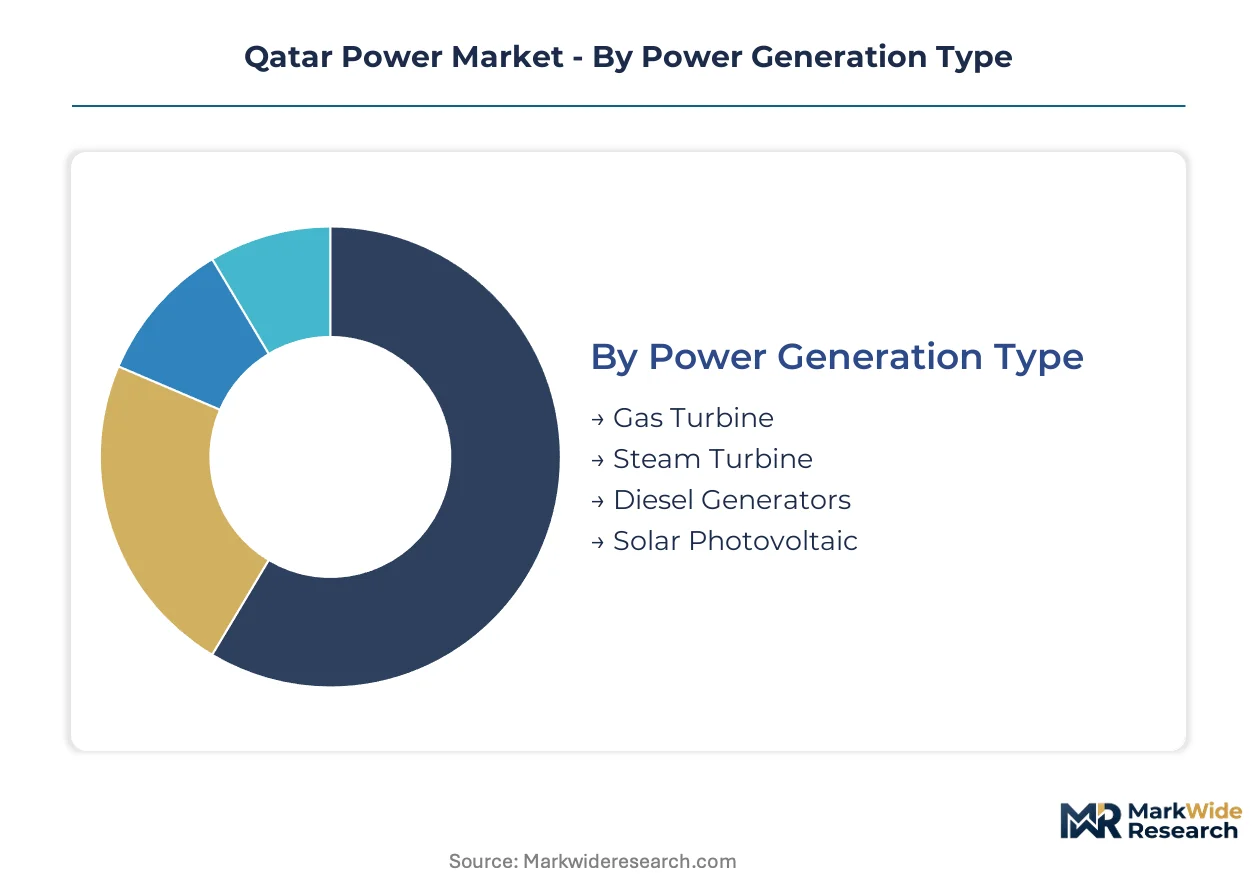
Qatar's power market segmentation reveals how procurement mandates and industrial load concentration reshape competitive positioning across generation assets and service contracts. KAHRAMAA's renewable integration requirements and Ras Laffan's captive demand create distinct revenue pools that diverge from conventional utility economics.
Power Generation Type:
Technology choice in Qatar's desert environment hinges on fuel access, water co-production needs, and KAHRAMAA's emissions benchmarks for new capacity tenders.
- Gas Turbine:Combined-cycle units constitute the backbone of Qatar's installed capacity, with Mesaieed Power Company and Ras Laffan Power Company operating large-scale coastal facilities. Industrial offtake from LNG trains and gas-to-liquids plants at Ras Laffan Industrial City locks in substantial baseload demand for these assets, though daily ramping to accommodate solar duck curves accelerates hot gas path degradation.
- Solar Photovoltaic:Bifacial modules with tracking systems dominate new capacity additions as KAHRAMAA procurement mandates redirect independent power producer bids toward clean configurations. The Al Kharsaah 800 MWac plant demonstrates bankable templates for utility-scale deployment across Qatar's western corridor, with battery co-location addressing intermittency constraints for desalination reliability.
- Steam Turbine:Thermal units serve combined water-power facilities at coastal complexes, providing uninterrupted energy input for multi-stage flash distillation plants.
- Diesel Generators:Backup power systems address critical facility redundancy requirements where grid reliability margins face solar intermittency complications.
Volume sits with Gas Turbine assets; growth tilts toward Solar Photovoltaic configurations.
End User:
Load profiles across customer categories diverge sharply between continuous industrial process demand and peaking commercial-residential consumption.
- Industrial:LNG export facilities, petrochemical complexes, and aluminum smelters command the largest share of megawatt-hour consumption, with Ras Laffan's cluster anchoring demand concentration. QatarEnergy's upstream fuel integration across generation assets and long-term take-or-pay gas supply agreements constrain fuel-switching flexibility for these offtakers.
- Commercial:Peak summer loads from air conditioning and commercial cooling drive seasonal demand patterns that exceed winter baselines by substantial margins, creating opportunities for demand response participation through advanced metering infrastructure.
- Residential:Urban population concentration in Doha and surrounding municipalities shapes distribution network investment priorities for KAHRAMAA.
- Government:Public sector facilities face procurement pressure to document Scope 2 reductions for emissions disclosure requirements under National Renewable Energy Strategy coordination with the Ministry of Municipality and Environment.
Revenue concentrates in Industrial offtake; Commercial segment expansion is climbing the fastest as smart grid digitalization enables new service models.
Service Type:
Contract structures fragment as KAHRAMAA experiments with shorter-tenor renewable tenders and merchant exposure tranches that reshape risk allocation.
- Maintenance:Hot gas path refurbishment and battery inverter servicing concentrate with EPC contractors rather than local O&M workforces, creating training pipeline gaps that delay plant commissioning schedules for concentrated solar thermal assets.
- Installation:Engineering-procurement-construction pricing declines for utility-scale solar enable QatarEnergy to displace incremental gas burn, with DC/AC ratio optimization for summer peak capture driving contractor technical requirements.
- Consulting:Carbon intensity disclosure preparation and long-term power purchase agreement structuring support independent power producers navigating merchant risk for portions of solar output beyond contracted baseload.
- Operations:Grid code compliance and fault ride-through certification testing for inverter-based renewable assets delay commercial operation dates as KAHRAMAA specifications evolve.
Contract value pools in Installation; Maintenance margins are expanding most quickly as legacy asset cycling stress intensifies.
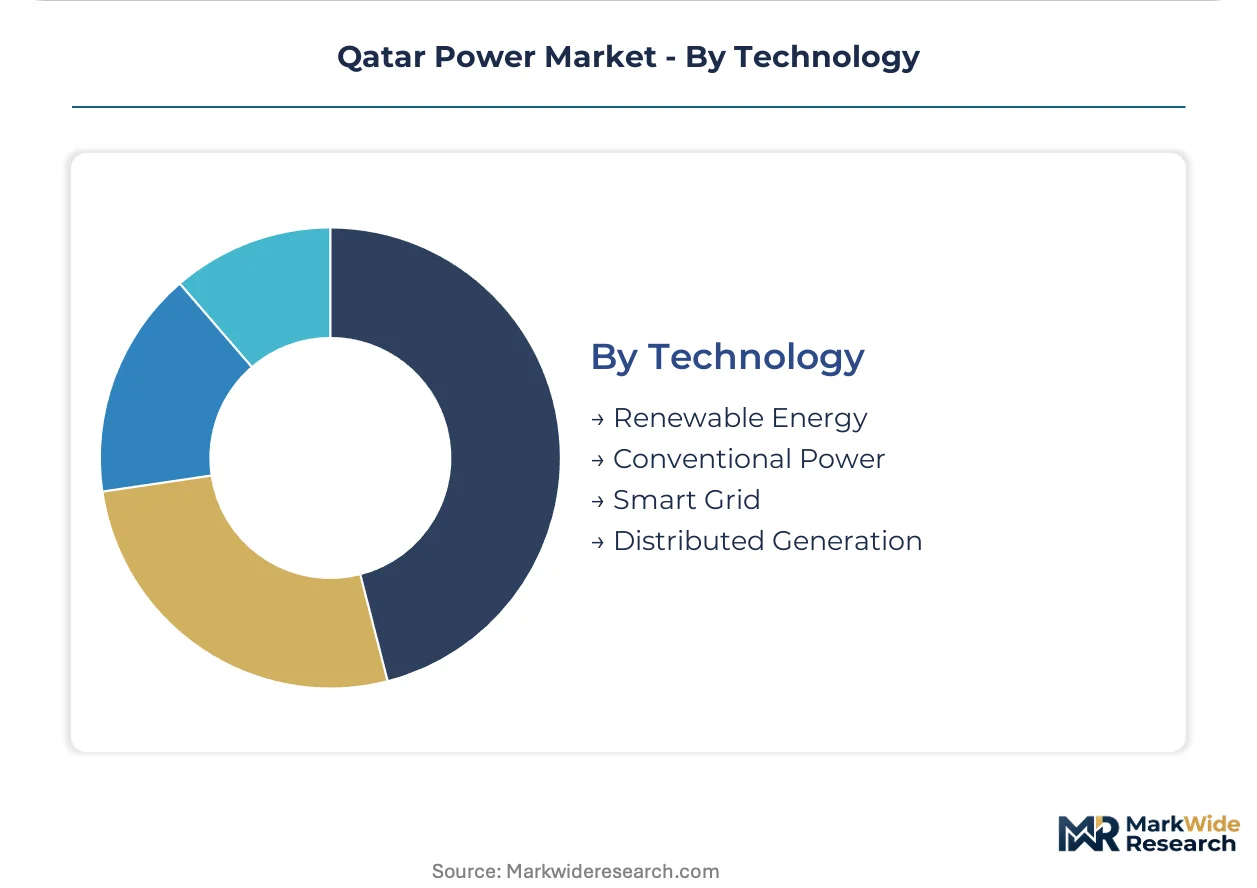
Technology:
System architecture choices determine access to KAHRAMAA interconnection standards and eligibility for renewable procurement mandates.
- Renewable Energy:Solar photovoltaic and battery storage hybrids now constitute baseline technical requirements for independent power producer bids, with developers demonstrating dispatchable clean capacity to secure long-term power purchase agreements.
- Conventional Power:Gas turbine and steam turbine assets face utilization compression as solar-hybrid configurations penetrate the generation mix, requiring grid flexibility investments to maintain spinning reserve margins.
- Smart Grid:Advanced metering infrastructure and distributed energy resource aggregation accommodate demand response participation under revised KAHRAMAA grid codes.
- Distributed Generation:Captive capacity at industrial zones and commercial facilities offers electrolyzer load flexibility for green hydrogen export infrastructure monetization.
Capital deployment favors Conventional Power for reliability; Renewable Energy claims the steepest expansion trajectory as procurement mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ras Laffan Industrial City anchors Qatar's electricity demand concentration, with LNG export terminals and gas-to-liquids complexes driving baseload consumption across the northern coastline. KAHRAMAA's grid infrastructure radiates from this cluster toward Doha's commercial-residential load centers and Mesaieed's coastal generation assets.
Doha Metropolitan Area
Commercial cooling loads and urban population concentration shape peak summer demand patterns that exceed winter baselines substantially. KAHRAMAA coordinates distribution network investments with the Ministry of Municipality and Environment on emissions benchmarks for new capacity. Smart grid digitalization and advanced metering infrastructure deployments enable demand response participation from commercial loads across the capital corridor.
Ras Laffan Industrial City
LNG train debottlenecking and petrochemical expansion drive captive power demand requiring uninterrupted thermal energy input. QatarEnergy anchors upstream fuel integration across generation assets serving this zone. Desalination co-generation facilities at multi-stage flash distillation plants lock in substantial baseload electricity offtake for industrial offtakers.
Mesaieed Industrial Zone
Combined-cycle operations leverage coastal infrastructure to sustain generation at scale for aluminum smelters and downstream manufacturing. Qatar General Electricity and Water Corporation procurement mandates redirect independent power producer bids toward solar and hybrid configurations. Battery storage co-location addresses intermittency constraints for reliability-critical industrial processes.
Al Kharsaah Western Corridor
Utility-scale photovoltaic deployment demonstrates bankable templates for subsequent tenders across Qatar's high-irradiance desert environment. Bifacial modules with tracking systems optimize DC/AC ratios for summer peak capture in this solar resource zone. Developers replicate engineering configurations from the 800 MWac plant with co-located battery systems.
Al Wakrah Southern Municipality
Residential load growth and commercial expansion create distribution network investment priorities beyond Doha's core. KAHRAMAA grid code revisions accommodate distributed energy resource aggregation for demand response. Green hydrogen export infrastructure proposals target ammonia synthesis facilities that could absorb surplus solar generation during daylight hours.
Qatar Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fuel integration depth and long-term contract security. State-backed entities with captive fuel access command structural advantages in baseload provision, while independent power producers compete on renewable procurement compliance. Two archetypes dominate: integrated national champions with upstream-downstream control, and developer-financier consortia assembling solar-storage hybrids. Competitive moves concentrate on strategic partnerships for technology transfer and portfolio diversification into green hydrogen derivatives.
Within the integrated national champion tier, QatarEnergy and KAHRAMAA exemplify state-backed vertical control over fuel supply and grid dispatch. Among independent generation specialists, Mesaieed Power Company and Ras Laffan Power Company occupy positions anchored to coastal industrial zones with captive desalination-linked demand. Nebras Power represents the cross-border developer-financier archetype assembling consortium structures for utility-scale renewable tenders.
| Leading Market Players |
|---|
| Mesaieed Power Company |
| Total Energies |
| Qatar General Water & Electricity Corporation (KAHRAMAA) |
| ExxonMobil |
| Shell |
| Nebras Power |
| QatarEnergy |
| ConocoPhillips |
| Ras Laffan Power Company |
| Others |
Value Network & Pricing Analysis
Bifacial photovoltaic module performance gaps between tier-one and tier-three suppliers compress procurement premiums for KAHRAMAA tenders while concentrating EPC contractor leverage over balance-of-system costs. This tier divergence manifests in divergent warranty terms and bankability premiums that reshape developer capital structures alongside logistics choices for desert deployment.
Pricing Analysis
Value-based pricing anchored to dispatchable clean capacity outcomes dominates KAHRAMAA's independent power producer tenders, with developers bidding guaranteed availability rather than pure energy volume. Price differentiation rests on battery storage co-location depth and grid code compliance certification tier, with full hybrid configurations commanding substantial premiums over solar-only bids. Pricing pressure stems from photovoltaic engineering-procurement-construction cost compression as Chinese module supply expands. Industrial offtakers at Ras Laffan exhibit lowest price sensitivity given captive desalination reliability requirements, while merchant-exposed renewable developers face acute margin compression.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Dammam anchor hub-and-spoke patterns for photovoltaic module logistics into Qatar's western corridor. Geographic supply concentration centers on China for bifacial modules and battery cells, South Korea for inverters, and Germany for grid stabilization equipment. Raw material dependencies include polysilicon feedstock, lithium carbonate, and high-grade steel for tracking structures. Single-source vulnerability from concentrated Chinese polysilicon refining creates tariff exposure risk. Distribution runs through EPC contractor-controlled staging yards rather than developer-owned inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's power sector operates as a cost-of-compliance story where KAHRAMAA's renewable procurement mandates and National Renewable Energy Strategy emissions benchmarks erect substantial barrier-to-entry moats for developers possessing grid code certification and long-term fuel integration.
For Market Incumbents: To counter solar duck curve cycling stress on legacy combined-cycle assets, Mesaieed Power Company and Ras Laffan Power Company should retrofit hot gas path components for enhanced ramping flexibility and secure battery storage co-location rights at existing coastal sites. Backward integration into electrolyzer load flexibility for green hydrogen export infrastructure offers captive demand monetization. For New Entrants and Emerging Players: Digital-channel route through KAHRAMAA's advanced metering infrastructure procurement portals enables demand response aggregation service entry without generation asset ownership. White-space targets concentrate in commercial building energy management and distributed solar-storage hybrids for Al Wakrah municipal facilities. The most penetrable segment sits with smart grid software and inverter maintenance services where skilled technician scarcity delays incumbent response. For Investors and Strategic Acquirers: Re-rating potential sits with developer-financier consortia possessing balance sheet capacity for merchant risk absorption given KAHRAMAA's contracting evolution toward shorter-tenor renewable tenders. Long-term viability over a multi-year horizon favors sponsors with demonstrated Al Kharsaah replication capability and QatarEnergy partnership access. Acquisition target archetype: utility-scale solar EPC contractors with local workforce training pipelines. Signal to watch: KAHRAMAA grid code revisions accommodating distributed energy resource aggregation at commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Al Kharsaah-scale solar-storage hybrid replication secures KAHRAMAA procurement mandate compliance. |
| Power Purchase Agreement | Long-term offtake structures with Ras Laffan industrial cluster lock in baseload revenue streams. |
| Technology Licensing | Bifacial tracking system IP transfer reduces EPC contractor dependency for desert deployment optimization. |
| Backward Integration into Storage | Battery cell supply agreements with South Korean manufacturers mitigate inverter-based intermittency risks. |
| Green Certification Program | Scope 2 emissions documentation aligns with Ministry of Municipality and Environment benchmarking requirements. |
Research Methodology
Multi-period observation of KAHRAMAA tender awards, EPC contractor margin disclosures, and industrial electricity offtake patterns anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer project developers, grid interconnection specialists, and solar EPC technical directors. Secondary validation drew from IEA electricity market reports, FERC-equivalent regulatory filings, project finance database tracking, and customs import records for photovoltaic module shipments. Bottom-up capacity addition modeling and top-down macroeconomic demand projections were triangulated against stakeholder-validated deployment timelines.
Segment-weighting across generation technology, end-user category, service contract type, and system architecture dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed capacity buildout trajectories and industrial load growth assumptions, with solar photovoltaic penetration rates and gas turbine utilization compression calibrated against KAHRAMAA renewable integration targets and desalination reliability constraints.
The model holds under sustained KAHRAMAA procurement mandate enforcement and North Field gas supply contract stability; deviation in global photovoltaic module pricing volatility or electrolyzer technology cost curves would shift capacity mix outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Iran Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Temporary Load Bank Rental Market
Power
Kuwait Power Market
Power
Japan Power Market
Power
Green UPS Market
Power
Modified Sine Wave Home Inverters Market
Power
Global UPS Market
Power
Global Marine Power Systems Market
Power
Statcom Market
Power
Global Ancillary Services Power Market
Power
Power Shelf Market
Power
Power Sled Market
Power
Europe Submarine Power Cables Market
Power
Denmark Power Market
Power
India Uninterruptible Power Supply (UPS) Market