
 Mexico Power EPC Market | 2026-2036
Mexico Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Power EPC Market Foresight
The premium-contractor tier is repositioning around integrated EPC capabilities that bundle engineering, procurement, construction, and commissioning under single accountability, while commodity players compete on standalone construction bids with thinner margin pools. ICA Fluor leverages its joint-venture structure to anchor large-scale thermal and infrastructure projects across Mexico's energy belt. Siemens Gamesa Renewable Energy SA specializes in wind farm delivery, sustaining technology leadership through turbine supply tied to construction execution. Abengoa México dominates solar thermal and photovoltaic EPC, extending its track record from European markets into Mexican renewable auctions.
Mexico Power EPC encompasses the full-scope delivery of power generation infrastructure, spanning front-end engineering design, equipment sourcing, civil and electromechanical construction, and operational handover at specified performance parameters such as heat rate, capacity factor, and grid code compliance. Its primary purpose is to transfer construction risk from asset owners to contractors while guaranteeing output and schedule certainty. Commissioning services command premium pricing relative to standalone construction, as they bundle performance testing and warranty activation that utilities and independent power producers require for financial close. Solar and wind energy sources are attracting disproportionate EPC investment, while thermal retains volume dominance through CFE's baseload modernization program.
The Comisión Reguladora de Energía sets interconnection standards and permitting timelines that determine project bankability, while the Secretaría de Energía shapes long-term procurement auctions through its planning and policy directives. Mexico's grid code and environmental impact assessment requirements under SEMARNAT lengthen pre-construction phases, filtering contractor pools toward firms with regulatory navigation capabilities. Stakeholders must monitor how forthcoming electricity market rules affect power purchase agreement structures and therefore EPC contract risk allocation between developers and construction firms.
Market Dynamics
CFE's procurement pivot toward combined-cycle baseload and renewable auctions is compressing contractor qualification timelines while elevating single-accountability EPC bundling over fragmented subcontracting chains.
Growth Catalysts
- Industrial load concentration:Export-oriented manufacturing clusters in Baja California and Nuevo León require dedicated generation assets with guaranteed interconnection timelines.
- SEMARNAT environmental clearance:Streamlined impact assessments for renewable projects are accelerating solar and wind farm approvals relative to thermal alternatives.
- Grid code modernization:Updated interconnection standards under CFE technical specifications are mandating advanced inverter capabilities that favor integrated EPC providers.
Market Restraints
- Steel and copper input volatility:Electromechanical construction costs fluctuate with commodity indexes, squeezing fixed-price EPC margins on multi-year projects.
- Specialized labor scarcity:Certified commissioning engineers and high-voltage technicians concentrate in Mexico City and Monterrey, creating regional bottlenecks.
- Land tenure complexity:Ejido communal land agreements in rural solar development zones extend site acquisition timelines beyond typical financing windows.
Strategic Opportunities
- Energy storage co-location:Battery integration with existing solar farms in Sonora and Chihuahua opens retrofit EPC contracts outside greenfield auction cycles.
- Nearshoring power demand:Automotive and electronics manufacturers establishing operations in Guanajuato and Querétaro seek captive generation assets with rapid deployment schedules.
- Transmission reinforcement:SEN grid expansion into the Yucatán Peninsula creates substation and line construction opportunities disconnected from generation auction volatility.
Industry Challenges
- Permitting synchronization:Coordinating CRE interconnection approvals with SEMARNAT environmental licenses and municipal construction permits delays project mobilization.
- Performance guarantee enforcement:Heat rate and capacity factor warranties require extended contractor liability periods that strain surety bonding capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Power EPC Market |
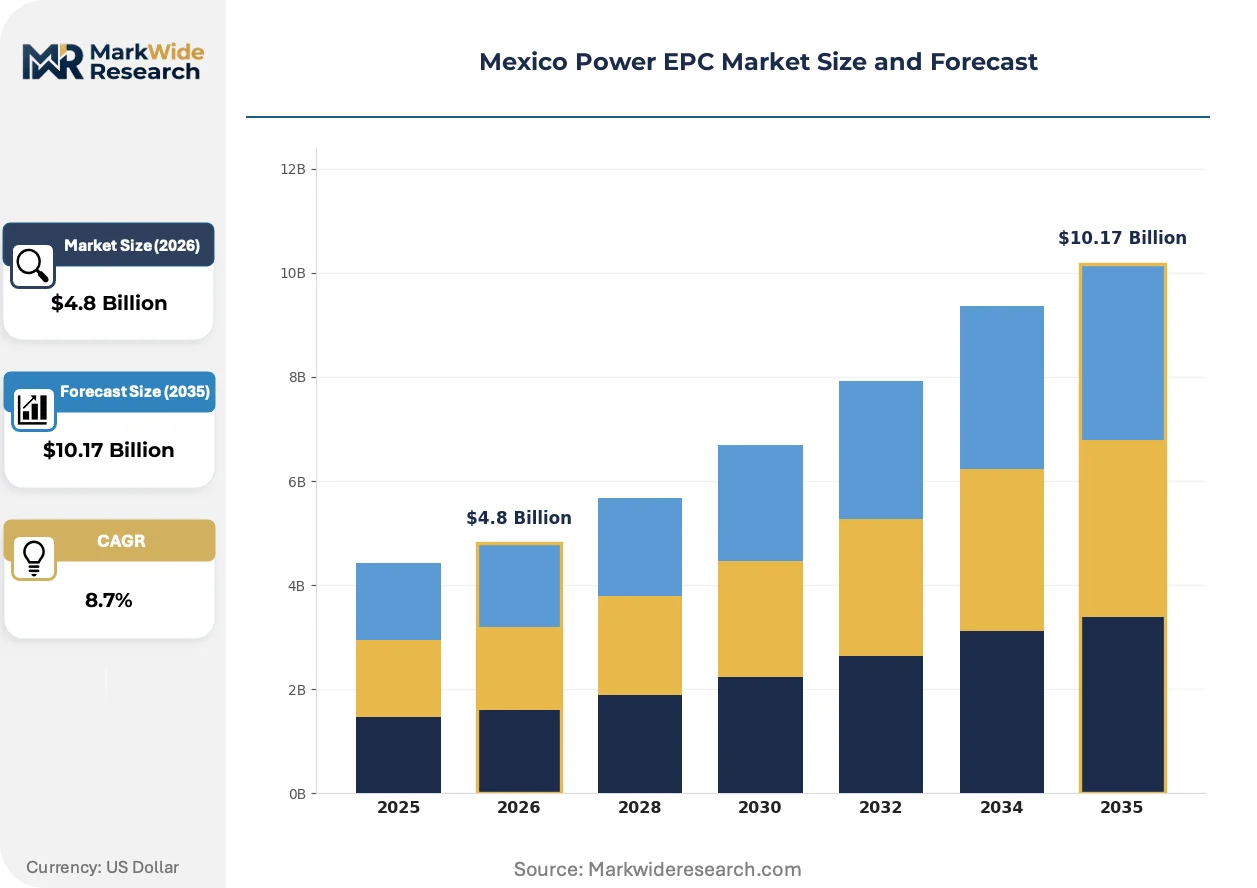
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning Energy Source: Solar, Wind, Hydro, Thermal Client Type: Government, Private Sector, Utilities, Independent Power Producers Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Siemens Gamesa Renewable Energy SA, ICA Fluor, Vestas Wind Systems A/S, Abengoa México, Techint Ingeniería y Construcción, SENER Engineering Group, Acciona, S.A., Elecnor México, Técnicas Reunidas, S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Power EPC Market Shifts & Advancements
Technology packaging and risk transfer mechanisms are restructuring how power infrastructure reaches financial close, with implications for contractor capability requirements and contract structures.
Containerized battery energy storage systems are modularizing project delivery timelines for solar-plus-storage configurations in northern Mexico. Independent power producers are adopting skid-mounted inverter stations to compress electromechanical installation phases from months to weeks. This standardization is modularizing EPC scope boundaries, allowing developers to unbundle engineering from construction and source components from multiple vendors under self-managed integration.
SEMARNAT's updated environmental impact criteria for renewable projects are tightening noise and visual assessment thresholds for wind developments in Oaxaca and Yucatán. Developers must now submit avian migration studies and community consultation records before construction permits issue. These requirements are extending pre-construction phases by six to twelve months, filtering contractor pools toward firms with dedicated regulatory affairs teams and established state-level relationships.
Power purchase agreement structures are migrating toward shorter tenors and merchant price exposure, altering how EPC contractors negotiate performance guarantees. Developers in Nuevo León and Baja California are accepting higher construction risk premiums in exchange for faster completion schedules that capture spot market price spikes. This risk transfer dynamic is visible most acutely in combined-cycle projects where contractors now shoulder fuel efficiency warranties across wider operating load ranges.
Mexico Power EPC Market Segmentation
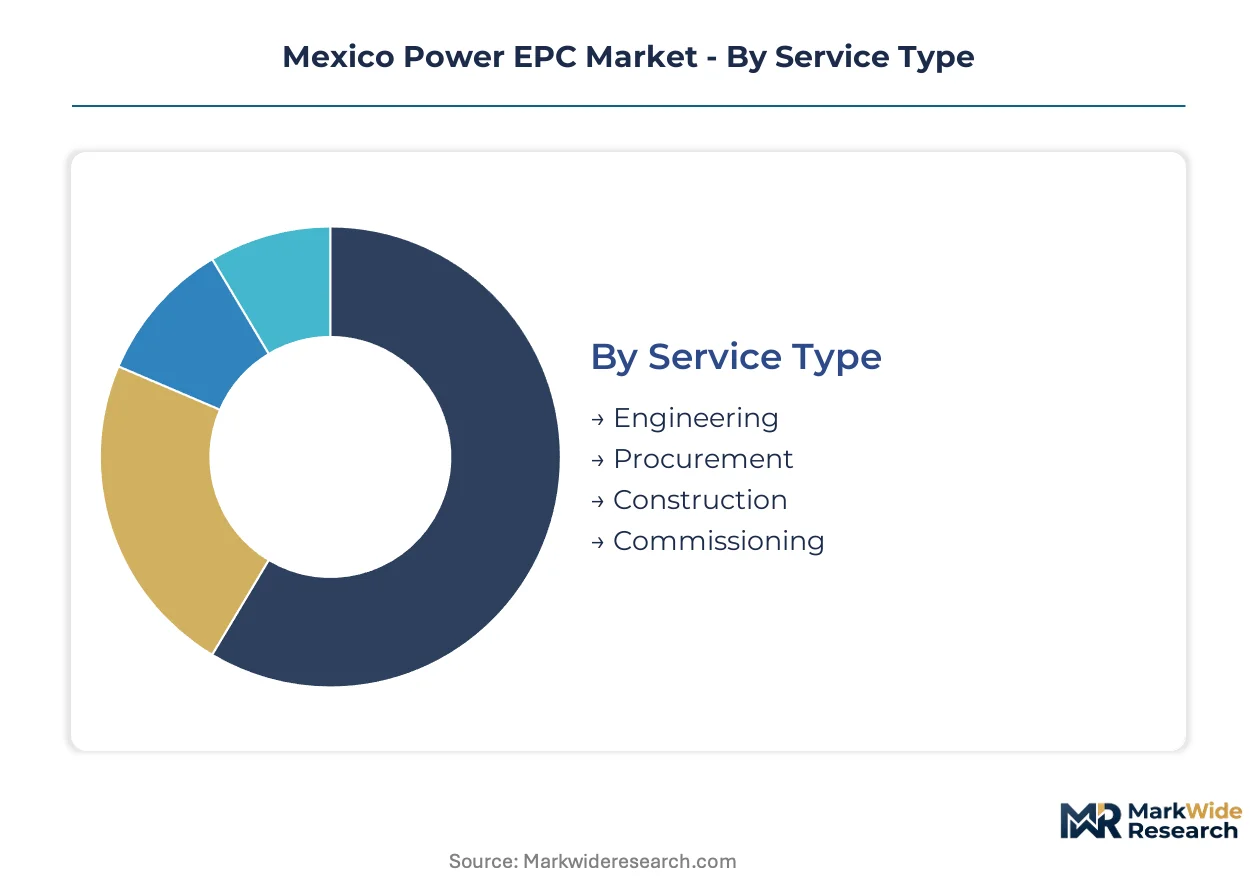
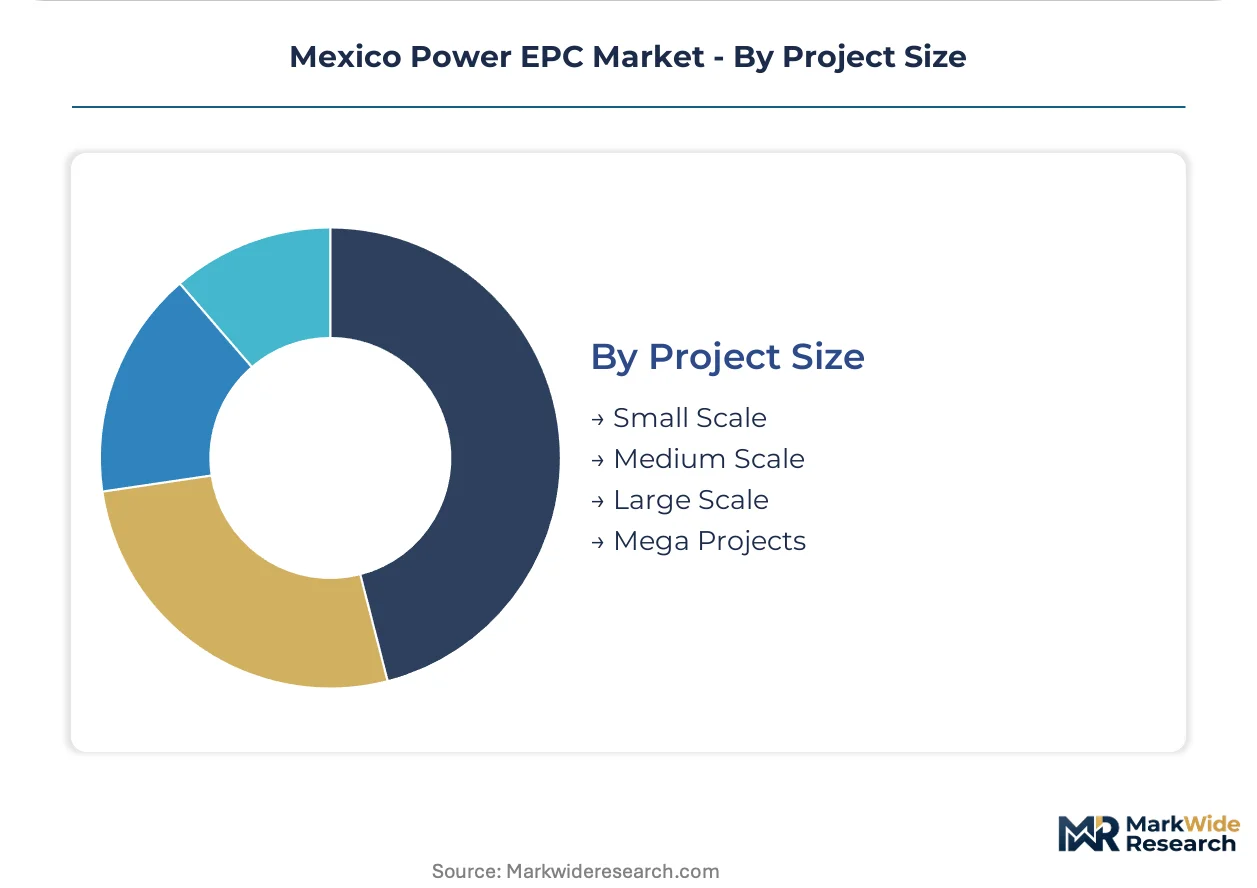
Mexico's power EPC market segments along four critical dimensions that determine contractor selection criteria, risk allocation structures, and margin profiles. Each segmentation axis reflects distinct procurement behaviors across CFE auctions, private industrial offtakers, and renewable energy developers operating under CRE interconnection standards.
Service Type:
Buyer procurement decisions pivot on risk transfer scope—whether asset owners seek standalone construction labor or full single-accountability EPC bundling.
- Engineering:Front-end design services encompass feasibility studies, basic and detailed engineering, and grid code compliance modeling. Demand concentrates among independent power producers in Nuevo León who require bankable documentation for project finance before construction mobilization.
- Procurement:Equipment sourcing and vendor qualification services cover turbine supply, inverter stations, and high-voltage switchgear. CFE's combined-cycle baseload program drives procurement bundling with construction to compress supplier qualification timelines.
- Construction:Civil works and electromechanical installation span foundation pouring, turbine erection, and substation buildout. Ejido land tenure complexity in rural solar zones extends site mobilization schedules beyond typical financing windows.
- Commissioning:Performance testing, warranty activation, and grid synchronization services command premium pricing relative to standalone construction phases. Heat rate and capacity factor guarantees require extended contractor liability periods that strain surety bonding capacity.
Volume sits with Construction; growth tilts toward Commissioning.
Energy Source:
Technology selection determines EPC contractor capability requirements, with each source imposing distinct civil works intensity and equipment lead times.
- Solar:Photovoltaic and concentrated solar thermal plants dominate Abengoa México's project pipeline, with modular panel installation compressing construction schedules relative to thermal alternatives. SEMARNAT's streamlined environmental clearances for solar accelerate approvals versus thermal permitting timelines.
- Wind:Onshore wind farms in Oaxaca and Yucatán require specialized turbine erection crews and avian migration studies under updated SEMARNAT criteria. Siemens Gamesa Renewable Energy SA sustains technology leadership through turbine supply tied to construction execution.
- Hydro:Small run-of-river and large reservoir projects demand geotechnical expertise and extended civil works phases. Site-specific geological constraints limit contractor pool depth for complex hydroelectric infrastructure.
- Thermal:Combined-cycle natural gas plants anchor CFE's baseload modernization program, sustaining volume dominance despite longer construction cycles. ICA Fluor leverages its joint-venture structure to anchor large-scale thermal projects across Mexico's energy belt.
Revenue concentrates in Thermal; expansion accelerates most quickly in Solar.
Client Type:
Contracting entity shapes payment security, performance guarantee structures, and dispute resolution mechanisms.
- Government:Federal and state agencies procure generation assets through public tenders with sovereign-backed payment terms. CFE procurement pivots toward combined-cycle baseload and renewable auctions, compressing contractor qualification timelines.
- Private Sector:Automotive and electronics manufacturers establishing operations in Guanajuato and Querétaro seek captive generation assets with rapid deployment schedules to support nearshoring power demand.
- Utilities:State utility CFE and regional distribution companies require grid code compliance and guaranteed interconnection timelines. Updated CFE technical specifications mandate advanced inverter capabilities that favor integrated EPC providers.
- Independent Power Producers:Merchant and contracted developers negotiate shorter-tenor power purchase agreements with elevated construction risk premiums. Developers in Nuevo León and Baja California accept higher risk transfer in exchange for faster completion schedules.
Contract flow favors Utilities; risk-adjusted returns expand fastest among Independent Power Producers.
Project Size:
Scale thresholds determine financing structure, contractor bonding requirements, and regulatory oversight intensity.
- Small Scale:Distributed generation and industrial captive plants below utility-scale thresholds. Manufacturing clusters in Baja California deploy small-scale assets to manage export-oriented load profiles.
- Medium Scale:Commercial and light industrial installations requiring standardized EPC modules. Skid-mounted inverter stations compress electromechanical installation phases from months to weeks.
- Large Scale:Utility-scale renewable and thermal plants subject to CRE interconnection standards and SEMARNAT environmental licenses. Permitting synchronization across regulatory bodies delays project mobilization.
- Mega Projects:Multi-gigawatt complexes and integrated generation-transmission systems. SEN grid expansion into the Yucatán Peninsula creates substation and line construction opportunities disconnected from generation auction volatility.
Project count peaks at Large Scale; margin expansion concentrates in Mega Projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monterrey anchors the northern industrial corridor where export manufacturing clusters drive captive power demand. The metropolitan area concentrates combined-cycle and renewable EPC contracts from automotive and electronics producers.
Nuevo León
Automotive assembly plants and steel foundries in Apodaca and Santa Catarina require dedicated generation assets with guaranteed interconnection timelines. CFE technical specifications mandate advanced inverter capabilities that favor integrated EPC providers with grid code navigation experience. The Monterrey-Saltillo corridor hosts the densest concentration of private power purchase agreements in northern Mexico.
Baja California
Export-oriented maquiladoras in Tijuana and Mexicali deploy small-scale distributed generation to manage volatile electricity tariffs. SEMARNAT streamlined environmental clearances accelerate solar farm approvals relative to thermal alternatives. The Tecate-Tijuana industrial zone attracts battery storage co-location retrofit contracts outside greenfield auction cycles.
Sonora
Mining operations in Cananea and Nacozari de García require baseload reliability that thermal EPC contractors address through combined-cycle configurations. The state's solar irradiance profile supports photovoltaic development in Puerto Peñasco where land tenure complexity extends site acquisition timelines. Hermosillo serves as the regional hub for electromechanical contractor mobilization.
Jalisco
Guadalajara's electronics manufacturing expansion creates nearshoring power demand for rapid-deployment captive generation. The state's regulatory affairs infrastructure supports faster permitting synchronization than rural solar zones. El Salto and Tlajomulco host industrial parks negotiating direct EPC contracts bypassing traditional utility procurement channels.
Yucatán Peninsula
SEN grid expansion into Campeche and Yucatán states creates substation and line construction opportunities disconnected from generation auction volatility. Tourism load centers in Mérida and Cancún drive distributed solar demand with shorter contractor qualification timelines. The region's wind resource in Oaxaca-adjacent zones requires avian migration studies that extend pre-construction phases.
Mexico Power EPC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across capability integration, with single-accountability bundling commanding pricing power over fragmented subcontracting chains. The contractor pool stratifies into three tiers: integrated EPC houses with commissioning capabilities, standalone construction specialists, and equipment suppliers extending into installation services. Strategic archetypes include technology-anchored joint ventures, regulatory-navigation specialists with state-level relationships, and scale-driven international entrants. Consolidation pressures favor M&A among mid-tier construction firms, while technology licensing agreements proliferate between turbine suppliers and local installation partners.
Within the integrated EPC tier, ICA Fluor and Abengoa México exemplify divergent capability positioning. ICA Fluor leverages its joint-venture structure to anchor large-scale thermal projects, while Abengoa México extends European solar thermal expertise into Mexican renewable auctions. Siemens Gamesa Renewable Energy SA occupies a technology-anchored position where turbine supply ties to construction execution. These three represent the premium-contractor repositioning around bundled accountability that CFE procurement increasingly demands.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy SA |
| ICA Fluor |
| Vestas Wind Systems A/S |
| Abengoa México |
| Techint Ingeniería y Construcción |
| SENER Engineering Group |
| Acciona, S.A. |
| Elecnor México |
| Técnicas Reunidas, S.A. |
| Others |
Supply & Pricing Matrix
Steel and copper price indexes cascade through Mexico Power EPC contractor tiers, compressing fixed-price contract margins for multi-year thermal projects while elevating premium pricing for integrated providers with captive equipment sourcing. Commodity volatility feeds into a bifurcated structure where single-accountability EPC bundling commands risk-adjusted premiums over fragmented subcontracting chains.
Pricing Analysis
Heat rate and capacity factor guarantees anchor value-based pricing for commissioning services, with warranty activation tied to operational throughput metrics that utilities require for financial close. Three-tier pricing structure across premium, standard, and economy levels separates integrated EPC houses with regulatory navigation capabilities from standalone construction specialists and equipment suppliers extending into installation. Cost compression in the commodity construction tier is intensifying because steel and copper input volatility squeezes fixed-price margins on CFE baseload programs. Independent power producers in Nuevo León exhibit highest price sensitivity, seeking rapid deployment schedules that trade risk premiums for schedule certainty, while government tenders tolerate extended contractor liability periods.
Supply Chain Analysis
Regional distribution centers in Monterrey and Mexico City anchor hub-and-spoke patterns for electromechanical components, with high-voltage switchgear and turbine assemblies flowing through these hubs to project sites across northern border states. Manufacturing concentration centers on China for solar inverters, Germany for gas turbines, and the United States for advanced grid synchronization equipment. Raw material dependencies span steel from domestic mills, copper from Chilean smelters, and specialized alloys from South Korean foundries. Single-source vulnerability sits with precision inverter components where CRE grid code mandates limit qualified suppliers. Distribution runs through CFE-approved vendor lists that filter contractor procurement choices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's power EPC sector occupies a technology-transition phase where containerized battery energy storage systems displace legacy thermal peaking infrastructure, restructuring contractor capability requirements and contract risk allocation.
For Market Incumbents: Acquire commissioning engineering teams with certified heat rate testing capabilities to defend against modular EPC unbundling that independent power producers favor. Secure backward integration into inverter station manufacturing to capture margin pools that equipment suppliers currently extract. The threat of skid-mounted standardization compressing project timelines demands captive control over electromechanical integration.
For New Entrants and Emerging Players: Begin with battery storage retrofit contracts in Sonora and Chihuahua solar zones where greenfield auction cycles do not gate project access. Target the Yucatán Peninsula transmission reinforcement segment where SEN grid expansion creates substation construction opportunities disconnected from generation procurement volatility. A go-to-market angle anchored in SEMARNAT regulatory affairs capabilities accelerates permitting timelines that incumbent construction specialists struggle to compress.
For Investors and Strategic Acquirers: The window for entry favors mid-tier construction firms with established state-level relationships and dedicated environmental licensing teams. Long-term viability hinges on exposure to renewable auction pipelines and storage co-location retrofit cycles rather than thermal baseload dependence. The signal to watch is CFE procurement pivot timing toward distributed generation assets that bypass traditional transmission interconnection queues.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Turbine suppliers anchor construction execution partnerships through intellectual property transfer to local installers. |
| Vertical Integration into Storage | EPC contractors capture battery co-location margins through in-house integration capabilities at solar retrofit sites. |
| Green Certification Program | SEMARNAT streamlined clearances accelerate project approvals for contractors with established environmental compliance track records. |
| Long-term Supply Agreement | Steel and copper offtake contracts hedge commodity volatility that squeezes fixed-price EPC margins. |
| Joint Venture | International technology providers leverage local construction partners to navigate CFE grid code compliance requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across utility planning officers, IPP project developers, EPC contractors, and grid operators validating demand assumptions. Secondary sources included CRE interconnection databases, SEMARNAT environmental license records, CFE procurement disclosures, and steel and copper trade flow documentation. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic load growth projections.
Granularity-level modeling deployed capacity-tier segmentation for generation assets, regulatory framework distinctions between CFE auctions and private offtake structures, and regional grid type variations across SEN interconnected zones. CAGRs derived from project finance closure velocity and equipment lead time compression trends across the analysis window. Forecast inputs incorporated nearshoring manufacturing load growth in automotive and electronics clusters and battery storage cost trajectory assumptions.
Underlying measurement precision varies by segment; commissioning services and mega-project categories carry tighter precision than small-scale distributed generation where ejido land tenure complexity introduces site acquisition uncertainty. Forecasts reflect documented assumptions regarding CFE procurement pacing, SEMARNAT clearance timelines, and commodity price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Static Synchronous Compensator (STATCOM) Market
Power
Mexico Power Market
Power
Uzbekistan Power Market
Power
Harmonic Filter Market
Power
Wind Alarm Controller Market
Power
Brunei Power Market
Power
Argentina Power Market
Power
Nigeria Power Market
Power
Critical Power Market
Power
Power Rental Market
Power
HVDC Capacitor Market
Power
Italy Power Market
Power
Global UPS Market
Power
Water Turbine Market
Power
Brazil Power Market
Power
Japan Uninterrupted Power Supply (UPS) Market