
 Australia Power Market | 2026-2036
Australia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Power Market Analysis
Behind-the-meter solar and battery aggregation is fragmenting the traditional centralized generation model that has dominated Australian electricity supply for decades. AGL Energy Ltd. leverages its extensive retail customer base to bundle virtual power plant services across residential postcodes. Origin Energy Ltd. anchors its strategic position through upstream control over gas-fired peaking assets that balance intermittent renewable output. Snowy Hydro Ltd. dominates pumped hydro storage dispatch, providing system inertia that stabilizes the National Electricity Market frequency.
Australia power encompasses electricity generated, transmitted, and distributed across an islanded grid spanning six interconnected state-based networks, with synchronous generation maintaining frequency between 49.85 and 50.15 Hz under normal operating conditions. The primary purpose is to supply reliable alternating current to industrial loads, commercial buildings, and residential consumers across vast distances exceeding 5,000 kilometers from generator to load. Renewable Energy generation leads capacity additions, though Thermal Power retains margin concentration through firming contracts during evening peak periods. Distributed Generation installations represent the fastest-expanding segment as rooftop solar penetration exceeds one-third of Australian dwellings.
The Australian Energy Market Commission and Australian Energy Regulator jointly govern market rules, transmission access pricing, and revenue caps for regulated network businesses. The Clean Energy Finance Corporation directs concessional capital toward grid-scale storage and firming projects that meet investment mandate criteria. Stakeholders must monitor the evolution of capacity mechanism designs and their implications for generator revenue streams.
Market Dynamics
Behind-the-meter solar and battery aggregation is fragmenting the centralized generation model that has dominated Australian electricity supply for decades. The Australian Energy Market Commission's capacity mechanism redesign is forcing incumbent generators to revalue firming assets.
Growth Catalysts
- Renewable Energy Target:The national framework mandates specific generation thresholds that accelerate wind and solar farm development across Queensland and South Australia.
- Mining electrification:Western Australian iron ore and lithium operations anchor industrial load growth requiring reliable baseload substitution.
- Grid-scale storage:Lithium-ion battery installations provide frequency control ancillary services that stabilize the National Electricity Market.
Market Restraints
- Transmission congestion:The 5,000-kilometer span between generator and load creates bottlenecks on interconnectors linking Queensland to New South Wales.
- Gas supply uncertainty:Eastern Australian domestic gas reservation policies constrain fuel availability for peaking plant operators.
- Synchronous generation retirement:Coal plant closures reduce system inertia below thresholds required for frequency stability during contingency events.
Strategic Opportunities
- Virtual power plant aggregation:Distributed solar-plus-storage systems in South Australia enable residential fleets to bid into wholesale markets.
- Green hydrogen offtake:The Hydrogen Headstart program creates production credits for electrolyzer projects serving export markets.
- Regional microgrids:Remote communities in Western Australia and the Northern Territory require standalone power systems replacing diesel generation.
Industry Challenges
- Network access queuing:Connection application backlogs delay renewable projects seeking registration with the Australian Energy Market Operator.
- Workforce transition:Coal-dependent regions face shortages of electricians and power systems engineers qualified for inverter-based resource integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Power Market |
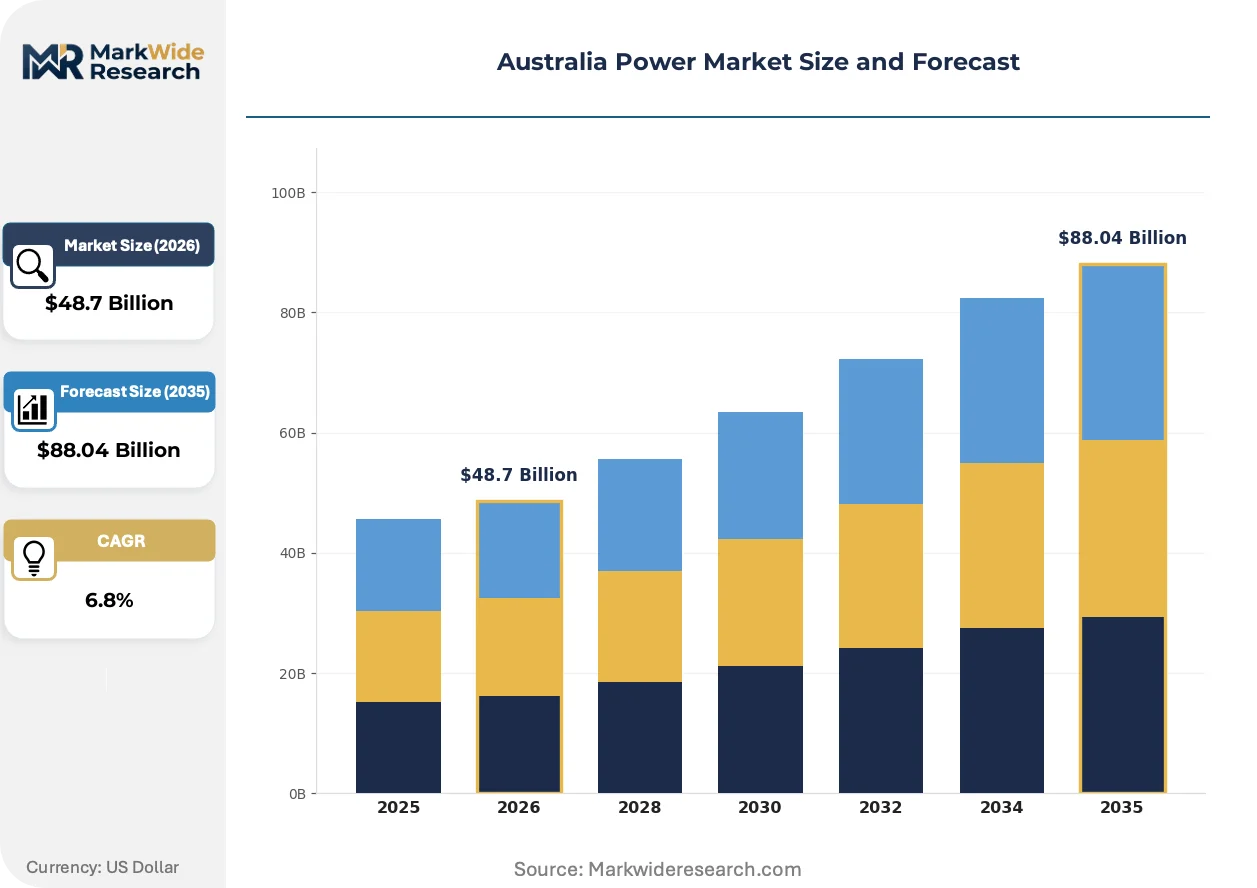
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Thermal Power, Hydro Power, Nuclear Power End User: Residential, Commercial, Industrial, Government Installation: Onshore, Offshore, Distributed Generation, Utility-Scale Service Type: Generation, Transmission, Distribution, Maintenance |
| Companies Covered | AGL Energy Ltd., Origin Energy Ltd., EnergyAustralia Holdings, Snowy Hydro Ltd., Alinta Energy Pty Ltd., CleanCo Queensland Ltd., TransGrid, AusNet Services Ltd., Powerlink Queensland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Power Market Emerging Trajectories
Distributed energy resources are rewiring competitive boundaries between retailers, network operators, and technology vendors. Control software and data analytics now determine value capture more than physical asset ownership.
Virtual power plant platforms aggregate thousands of residential battery systems into dispatchable capacity pools. Origin Energy and AGL Energy enroll customers through retail tariffs that automate charging cycles. This architecture is virtualizing the traditional distribution network operator role, compressing capital requirements for peaking capacity.
The National Electricity Law amendments introduce a capacity mechanism rewarding firm generation availability. The Australian Energy Regulator will administer auctions requiring verified dispatch capability from participating assets. Thermal generators and battery developers compete for contracts securing revenue during renewable drought periods.
Large energy users now procure electricity through synthetic PPAs combining wholesale market exposure with renewable certificate bundles. Mining companies in the Pilbara and manufacturing facilities in Victoria negotiate directly with wind and solar farms. This bypasses traditional retailer intermediaries, concentrating price risk with sophisticated buyers capable of managing spot market volatility.
Australia Power Market Segmentation
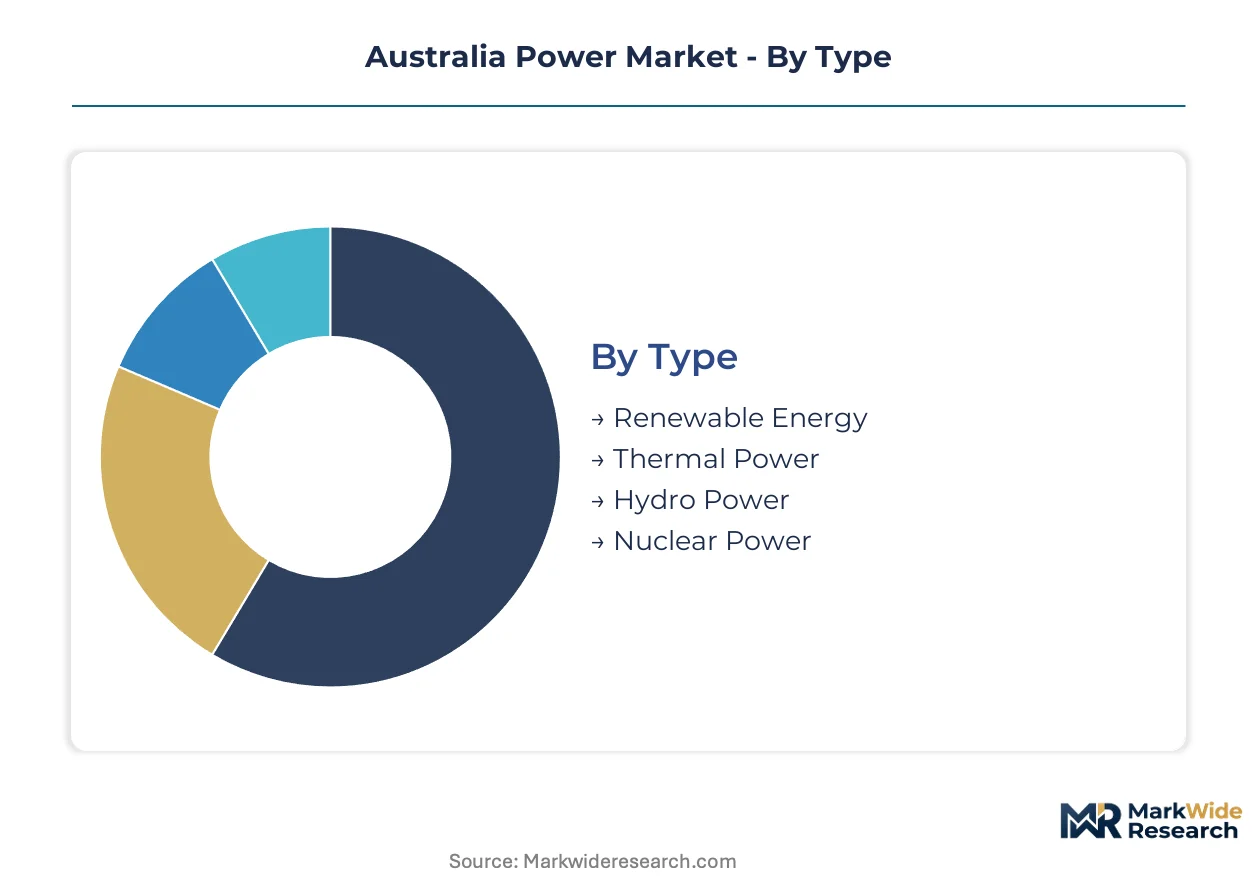
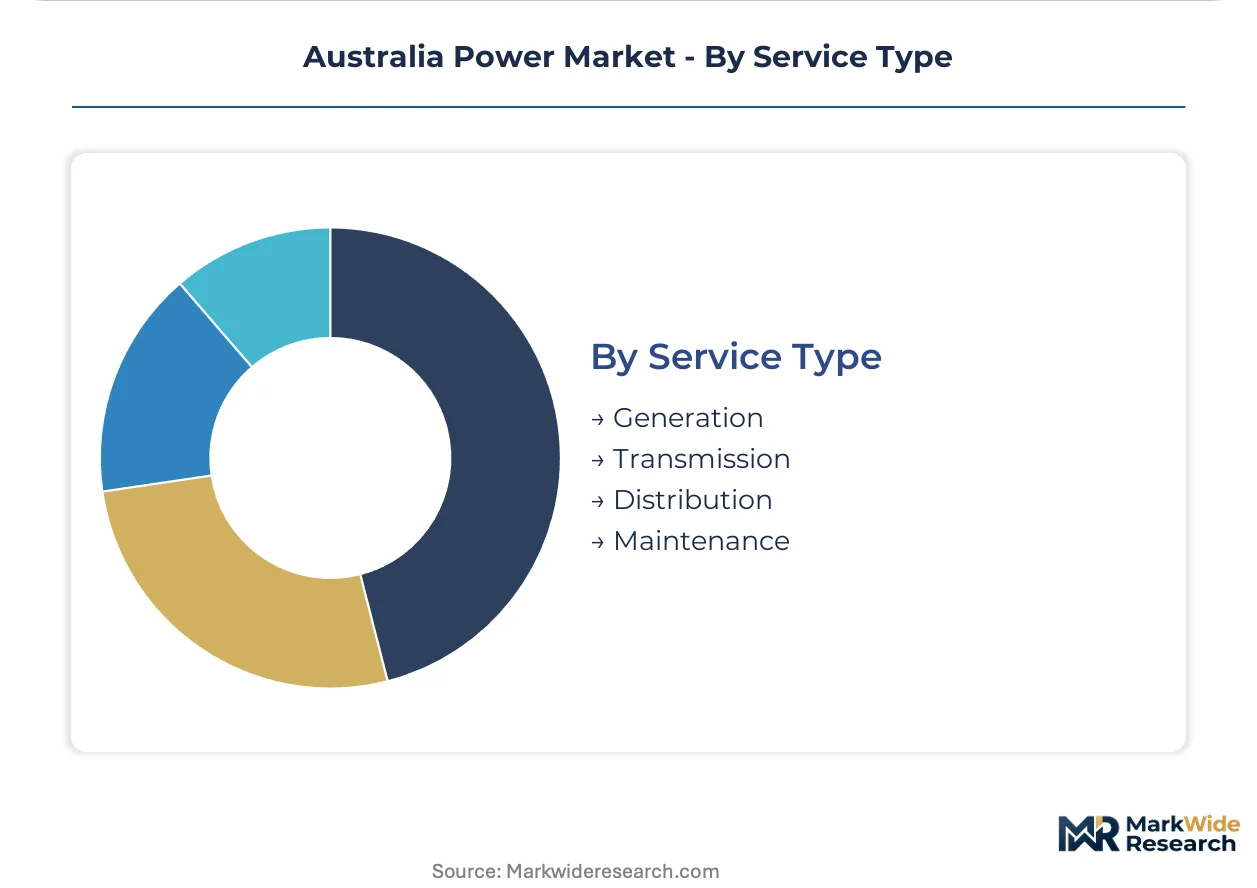
Power market segmentation in Australia reveals how generation technology, customer scale, and grid connection architecture determine revenue capture and regulatory exposure. Understanding these dimensions clarifies where capital deploys most efficiently across the National Electricity Market.
Type:
Use-case spectrum spans intermittent renewables requiring firming contracts through baseload thermal assets maintaining frequency stability.
- Renewable Energy:Wind and solar farms dominate capacity additions under the Renewable Energy Target, with Queensland and South Australia hosting the largest project pipelines. Grid-scale battery co-location addresses the duck curve mismatch between midday solar surplus and evening peak demand.
- Thermal Power:Black and brown coal generators provide synchronous inertia essential for frequency control, though plant retirements in Victoria and New South Wales accelerate each year. Gas-fired peaking plants bridge renewable drought periods during extended cloud cover or wind lulls.
- Hydro Power:Snowy Hydro operates the nation's largest pumped storage fleet, delivering rapid ramping capability for ancillary services markets.
- Nuclear Power:Legislative prohibitions under the Australian Radiation Protection and Nuclear Safety Act block commercial deployment, confining activity to research reactors only.
Established volume favors Thermal Power; emerging adoption favors Renewable Energy.
End User:
Customer scale determines tariff structure sophistication and behind-the-meter investment appetite across the value chain.
- Residential:One-third of Australian dwellings host rooftop solar, with South Australia penetration exceeding other states. Virtual power plant aggregation through retailers like AGL and Origin converts distributed assets into wholesale market participants.
- Industrial:Mining operations in Western Australia's Pilbara and Queensland's Bowen Basin anchor baseload demand, with iron ore and lithium processing requiring 24/7 reliability. Large energy users increasingly bypass retailers through synthetic PPAs with wind and solar farms.
- Commercial:Office buildings and shopping centers deploy battery storage to manage network demand charges and participate in demand response programs.
- Government:Public infrastructure including hospitals and water treatment facilities procure renewable electricity through centralized state procurement frameworks.
Industrial load commands the highest per-connection revenue; residential distributed generation expands the fastest.
Installation:
Grid connection architecture shapes capital intensity, permitting timelines, and access to transmission infrastructure.
- Utility-Scale:Grid-connected solar and wind farms exceeding 100 MW capacity connect to high-voltage transmission networks, with the Australian Energy Market Operator managing registration and dispatch scheduling. Queensland's Renewable Energy Zones concentrate development activity.
- Distributed Generation:Rooftop solar and commercial battery systems aggregate behind the meter, reducing network peak demand and deferring infrastructure augmentation. Western Australia's South West Interconnected System integrates high distributed penetration.
- Onshore:Land-based wind and solar projects dominate the development pipeline, with planning approval processes varying across state jurisdictions.
- Offshore:Floating wind feasibility studies progress in the Bass Strait and off the coast of Western Australia, though no commercial projects operate yet.
Utility-Scale delivers the lowest levelized cost; Distributed Generation captures the steepest expansion trajectory.
Service Type:
Value chain position determines exposure to regulated returns versus competitive market pricing.
- Generation:Competitive wholesale market participation exposes asset owners to spot price volatility, with the National Electricity Market settling prices every five minutes. Battery developers arbitrage price spreads between low and high demand periods.
- Transmission:Regulated revenue caps apply to high-voltage network businesses under Australian Energy Regulator determinations, with the Energy Connect project linking South Australia to New South Wales.
- Distribution:Lower-voltage network operators face revenue decoupling as rooftop solar reduces volumetric electricity sales, prompting tariff redesign toward capacity-based charging.
- Maintenance:Asset life extension services for aging coal plants and predictive analytics for renewable farms create specialized contracting opportunities.
Generation captures merchant upside; Transmission offers regulated stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in mining and minerals processing dominate electricity procurement across Australia's five mainland states, with each jurisdiction deploying distinct regulatory frameworks and infrastructure investment programs to manage the energy transition.
New South Wales
Data centers and manufacturing facilities in Western Sydney drive baseload demand growth, with the state's Electricity Infrastructure Roadmap legislating Renewable Energy Zones in the Central West and New England regions. AusNet Services manages transmission upgrades connecting these zones to the Sydney load center.
Victoria
Aluminum smelters in the Latrobe Valley and Geelong manufacturing anchor industrial consumption, as the Essential Services Commission administers the Victorian Renewable Energy Target. Offshore wind feasibility studies progress in Gippsland waters, targeting first power by the early 2030s.
Queensland
Iron ore and coal seam gas operations in the Bowen Basin and Surat Basin sustain 24/7 industrial load, with CleanCo Queensland and Powerlink coordinating the Queensland SuperGrid infrastructure program. Renewable Energy Zones in the Darling Downs and North Queensland concentrate solar and wind development.
Western Australia
Pilbara iron ore miners and emerging lithium processors in the Goldfields require reliable off-grid and grid-connected supply, with the South West Interconnected System integrating record distributed solar penetration. The Western Australian Government's Whole of System Plan guides transmission investment priorities.
South Australia
Automotive manufacturing suppliers and wine industry processors in Adelaide and the Barossa Valley shape commercial demand patterns, with the Australian Energy Market Operator managing the world's highest grid-scale battery penetration. Virtual power plant aggregation through retailers converts residential solar-plus-storage into wholesale market capacity.
Australia Power Market Vendor Landscape
Channel-controlling players compete with product-specialist players across generation, retail, and network service layers. The market structure shows moderate consolidation among vertically integrated gentailers holding both generation assets and retail customer bases, while specialist renewable developers and network operators occupy distinct competitive positions. Strategic archetypes include integrated gentailers bundling wholesale and retail services, pure-play renewable developers monetizing green certificates, and regulated network operators earning fixed returns on transmission infrastructure. Dominant competitive moves involve portfolio diversification into firming assets and strategic partnerships aggregating distributed energy resources.
Among integrated gentailers, AGL Energy Ltd. and Origin Energy Ltd. exemplify the vertically integrated archetype combining generation ownership with retail market presence. Snowy Hydro Ltd. occupies a unique position as a government-owned corporation dominating pumped hydro storage and renewable generation dispatch.
| Leading Market Players |
|---|
| AGL Energy Ltd. |
| Origin Energy Ltd. |
| EnergyAustralia Holdings |
| Snowy Hydro Ltd. |
| Alinta Energy Pty Ltd. |
| CleanCo Queensland Ltd. |
| TransGrid |
| AusNet Services Ltd. |
| Powerlink Queensland |
| Others |
Supply Flow & Price Mechanics
Commodity-linked fuel cost volatility determines both wholesale electricity price spreads and supply chain investment patterns across the National Electricity Market. Thermal generator fuel procurement strategies and renewable project equipment sourcing decisions cascade into divergent pricing tiers for firm versus intermittent supply.
Pricing Analysis
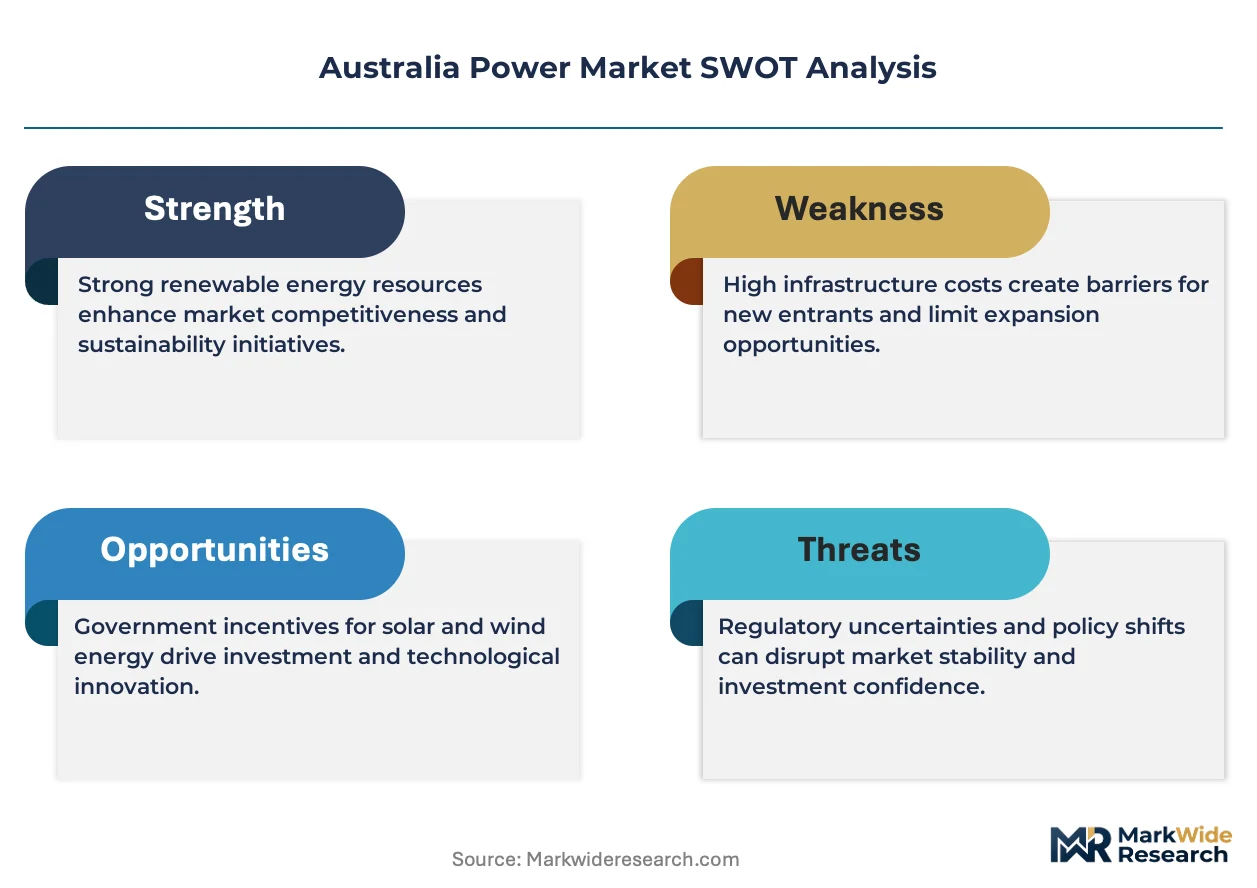
Cost-plus contracts with Newcastle coal indexation dominate baseload generator revenue structures, while renewable developers negotiate long-term offtake agreements at fixed rates with annual CPI escalators. Price differentiation rests on firmness guarantees and grid connection priority, with peaking plant operators capturing premiums for dispatchable capacity during renewable drought periods. Cost compression in utility-scale solar is intensifying because module import competition and EPC margin erosion compress developer returns. Industrial miners exhibit lowest price sensitivity due to synthetic PPA structures, while commercial retailers face highest sensitivity to spot market volatility.
Supply Chain Analysis
Upstream polysilicon and lithium carbonate feedstock draws from Chinese chemical processing hubs, South Korean cathode manufacturing, and Australian spodumene concentrate exports. Inverter and power electronics sourcing rests on Taiwanese semiconductor foundries and German engineering design houses. Single-source vulnerability concentrates in transformer manufacturing, where lead times extend beyond project commissioning schedules. Distribution runs through EPC contractors integrating imported equipment with domestic civil works and grid connection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Power Market represents an early-cycle expansion story as distributed solar-plus-storage penetration accelerates behind-the-meter deployment faster than centralized capacity additions.
For Market Incumbents: Pre-empt virtual power plant platform consolidation by acquiring residential battery aggregation software capabilities before retailer-bundled services lock in customer switching costs. Defend position by securing firming asset dispatch priority through Australian Energy Market Operator ancillary services pre-qualification. Prioritize upstream control over gas storage and pipeline capacity to anchor peaking plant fuel security. For New Entrants and Emerging Players: Pursue regional microgrid development in Western Australian mining camps and Northern Territory remote communities where diesel displacement economics favor standalone power systems. Target the commercial battery segment in South Australia and Queensland where network demand charge management creates immediate payback visibility. Lead with energy-as-a-service contracting models that eliminate customer capital deployment barriers. For Investors and Strategic Acquirers: The Australian Energy Market Commission capacity mechanism redesign reshapes the acquisition landscape by creating contracted revenue streams for firm generation assets. Frame long-term viability around portfolio balancing capabilities spanning renewable development, storage co-location, and peaking plant operation. Prioritize targets with demonstrated grid-scale battery deployment experience and AEMO registration track records. Monitor capacity mechanism auction clearing prices as the inflection indicator for firming asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation | AGL and Origin convert residential battery fleets into wholesale market dispatchable capacity pools. |
| Renewable Energy Zone Development | Queensland SuperGrid and NSW Central West zones concentrate transmission investment and project pipelines. |
| Grid-Scale Battery Co-location | Snowy Hydro and specialist developers arbitrage price spreads while providing frequency control ancillary services. |
| Synthetic PPA Structuring | Pilbara miners bypass retailers to negotiate direct renewable supply with wholesale market exposure management. |
| Pumped Hydro Expansion | Snowy Hydro leverages existing reservoirs to deliver rapid ramping capability and system inertia services. |
Methodological Framework
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interview cycles. Secondary validation drew from Australian Energy Market Operator dispatch data, Australian Energy Regulator revenue determination filings, Clean Energy Finance Corporation investment mandate disclosures, and project development database tracking. Bottom-up capacity addition modeling triangulated against top-down demand forecast reconciliation.
Scenario-bracketing framed analytical outputs across the projection horizon, with high and low cases reflecting renewable build rate assumptions and industrial load growth trajectories. Segmentation dimensions spanned fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derived from installed capacity run rates and capacity factor evolution across the modeling period. Forecast inputs incorporated transmission constraint modeling and firming requirement quantification under accelerated coal retirement pathways.
Macroeconomic conditions sit as an overlay; deviation in exchange rate movements affecting equipment import costs and mining commodity prices affecting industrial electricity demand would shift the trajectory. Forecasts reflect documented assumptions regarding policy continuity for the Renewable Energy Target and Hydrogen Headstart program. Cross-checking against Australian Bureau of Statistics electricity generation data and AEMO market reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Direct Current Power System Market
Power
Wind Alarm Controller Market
Power
Substation Automation System Market
Power
Qatar Power Market
Power
Europe Microturbine Market
Power
North America Power Market
Power
Smart PV Inverters Market
Power
Kuwait Power Market
Power
Power Capacitors Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Mexico Power Market
Power
Europe Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Modular PSA Nitrogen Generator Market
Power
Oxy-Hydrogen Generators Market