
 Steam Turbine MRO Market | 2026-2036
Steam Turbine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Turbine MRO Market Analysis
Power purchase agreement restructurings and long-term service agreement financing is tilting procurement toward integrated OEM-service bundles. Siemens Energy leverages its captive blade manufacturing to anchor overhaul contracts in Europe and North America. GE Vernova competes through digital monitoring platforms that extend predictive maintenance contracts. Mitsubishi Power specializes in advanced alloy rotor repairs for ultra-supercritical units across Asian utility fleets.
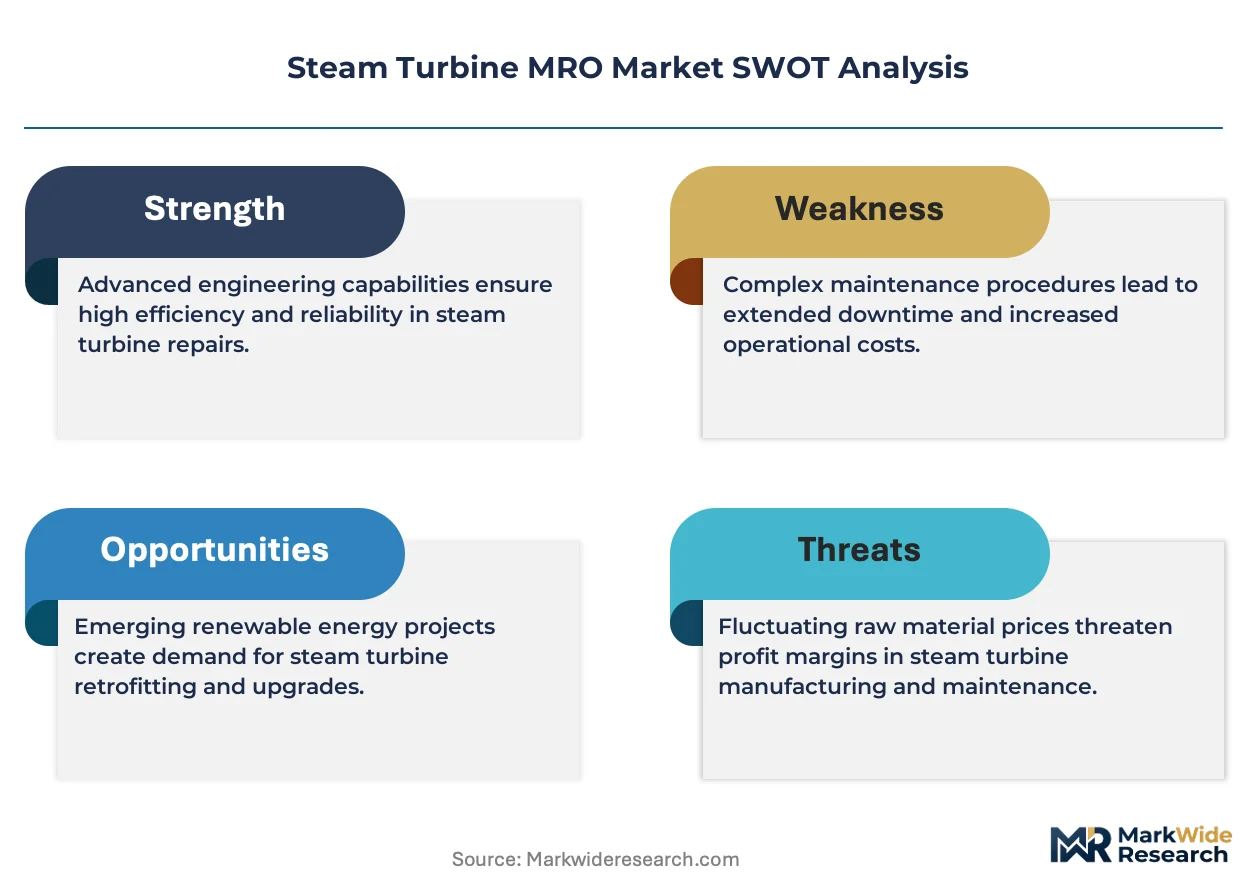
Steam turbine maintenance, repair, and overhaul encompasses inspection, component replacement, and performance restoration of thermal power generation rotating machinery, typically involving high-alloy steel rotors operating at inlet temperatures exceeding 540°C and steam pressures above 24 MPa to sustain baseload electricity output. Overhaul services command the largest revenue share due to scheduled major inspections mandated by insurance and grid reliability protocols, while rotor segment work captures premium margins given metallurgical complexity and limited certified repair shop capacity. Condensing technology installations dominate the installed base requiring MRO, though heat recovery steam turbine maintenance is expanding with combined-cycle plant additions.
The EPA enforces emissions limits that force turbine efficiency upgrades or retirement decisions, while India's Central Electricity Authority mandates periodic boiler and turbine inspections under CEA technical standards. ISO 9001 and ASME PTC-6 testing protocols shape contractor qualification and warranty terms for performance guarantees. Stakeholders must weigh residual asset life against carbon policy trajectories when committing capital to major overhauls versus replacement investments.
Market Dynamics
Power plant operators face intensifying pressure to extend aging turbine life cycles while carbon policy trajectories force premature retirement decisions on coal-fired units. The tension between residual asset value and emissions compliance is restructuring maintenance investment patterns across baseload thermal fleets.
Growth Catalysts
- EPA Emissions Standards:Updated limits on coal-fired units are accelerating retrofit demand for efficiency upgrades and component replacements across United States utility fleets.
- India Thermal Fleet Modernization:State-run utilities under CEA technical standards are expanding overhaul budgets to address aging supercritical and subcritical installations.
- Grid Reliability Mandates:Insurance protocols and grid operator requirements are enforcing scheduled major inspections that sustain overhaul service volumes.
Market Restraints
- Specialized Repair Shop Concentration:Certified capacity for high-alloy rotor segment work concentrates in limited facilities, creating bottlenecks and extending lead times.
- Carbon Policy Uncertainty:Ambiguous retirement timelines for coal assets in multiple jurisdictions are freezing multi-year overhaul commitments.
- Renewable Substitution:Solar and wind capacity additions are compressing baseload operating hours and degrading the economics of major turbine investments.
Strategic Opportunities
- Heat Recovery Steam Turbine Expansion:Combined-cycle plant additions are creating new MRO demand segments distinct from traditional condensing unit services.
- Digital Monitoring Convergence:Integration of sensor networks with predictive analytics is enabling performance-based service contract structures.
- Asian Ultra-Supercritical Fleet:Advanced alloy repair demand is concentrating in utility fleets operating units above 600°C inlet temperatures.
Industry Challenges
- Metallurgical Expertise Scarcity:Certified welders and engineers capable of high-temperature alloy repair are aging out of the workforce faster than training pipelines replenish.
- ASME PTC-6 Compliance Complexity:Performance testing protocol adherence for warranty guarantees requires specialized contractor qualifications that extend procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Turbine MRO Market |
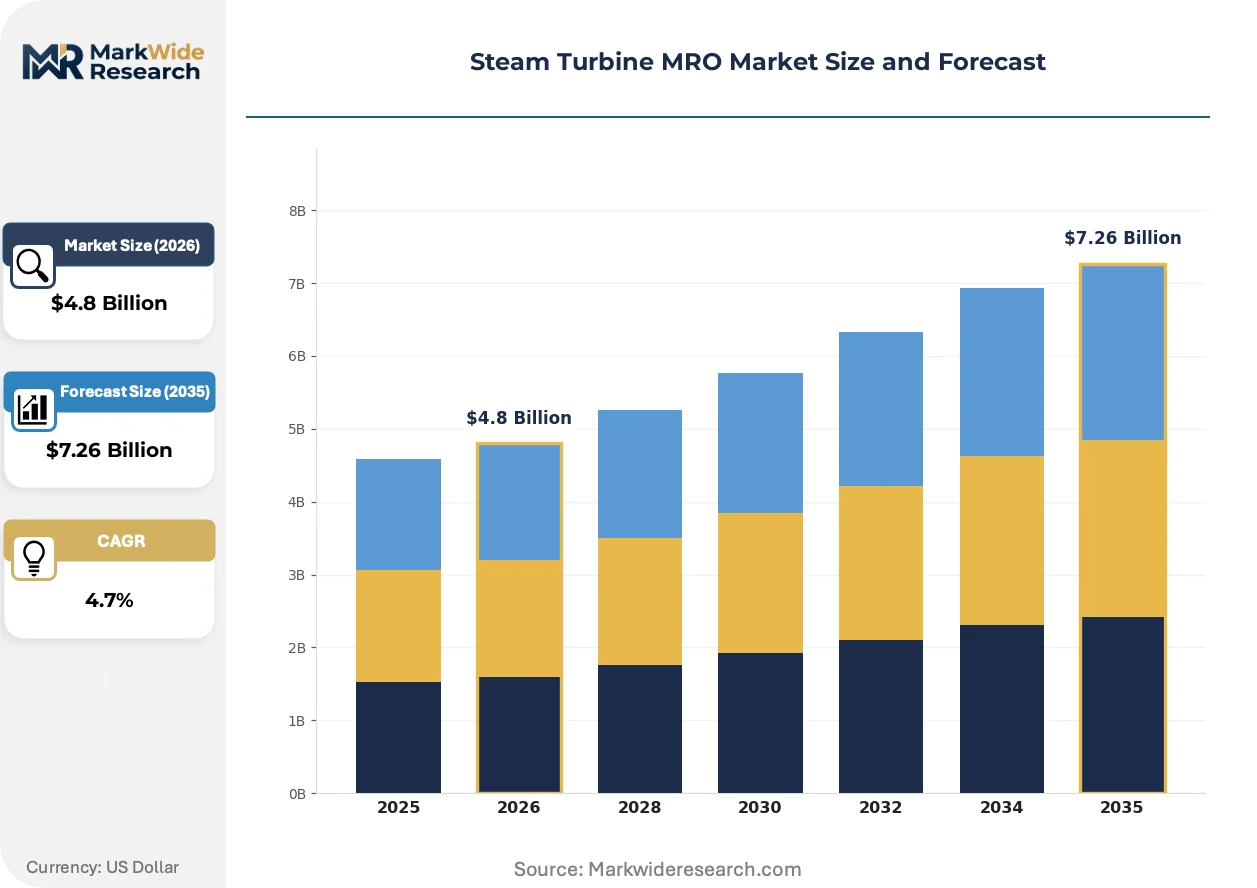
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Overhaul, Repair, Maintenance Component: Rotors, Bearings, Seals, Valves End User: Power Plants, Manufacturing Facilities, Oil & Gas, Marine Technology: Condensing, Back Pressure, Extraction, Heat Recovery |
| Companies Covered | Siemens Energy, GE Vernova, Mitsubishi Power, Bharat Heavy Electricals Limited, Dongfang Electric Corporation Limited, Shanghai Electric, EthosEnergy, Harbin Electric, Sulzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Turbine MRO Market Emerging Trajectories
Additive manufacturing processes are entering rotor repair workflows, challenging conventional machining and welding approaches. These shifts are compressing repair timelines while raising qualification barriers for incumbent service providers.
Directed energy deposition and powder-bed fusion techniques are enabling in-situ restoration of eroded blade profiles and cracked rotor sections. Major utilities in Germany and Japan are piloting these methods for critical path schedule reduction. The technology is rendering obsolete traditional weld-overlay and component replacement sequences that required extended outage windows.
The EPA's updated emissions standards for fossil fuel power plants are forcing efficiency upgrade investments or accelerated retirement decisions. Turbine vendors must now certify performance improvements against stricter heat rate benchmarks to maintain operating permits. United States coal fleet operators are prioritizing digital monitoring retrofits over mechanical overhauls to demonstrate compliance.
Long-term service agreement financing is displacing transactional overhaul procurement across European and North American utility fleets. Integrated OEM-service bundles now dominate capital budgeting conversations, compressing independent contractor market access. This concentration is most visible in Germany, where Siemens Energy's captive blade manufacturing anchors multi-year maintenance contracts.
Steam Turbine MRO Market Segmentation
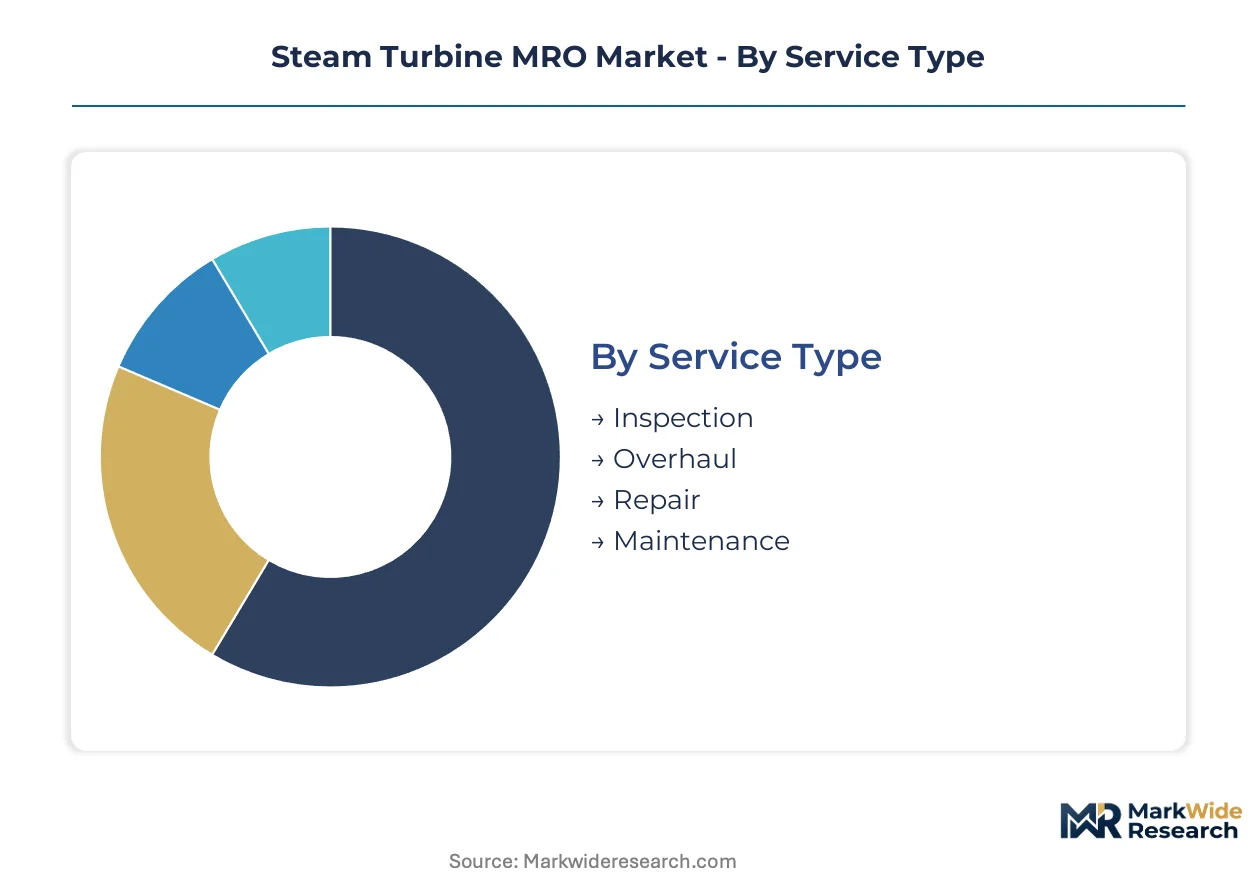
Steam turbine MRO procurement varies sharply by operational intensity and asset criticality. Service bundling decisions, component replacement cycles, and technology vintage all reshape vendor selection criteria and contract structures across end-use segments.
Service Type:
Service intensity spans from routine condition monitoring through complete performance restoration, with contract duration and technical risk allocation shifting across the spectrum.
- Overhaul:Scheduled major inspections involving rotor removal, blade refurbishment, and casing re-machining restore design efficiency after 100,000+ operating hours. United States utility fleets under EPA emissions mandates are accelerating overhaul commitments to demonstrate heat rate improvements and maintain operating permits.
- Repair:Unscheduled interventions address blade erosion, seal degradation, and bearing distress identified through vibration monitoring or performance deviation. Indian state-run utilities under CEA technical standards are expanding repair budgets as aging supercritical units exceed original design life.
- Inspection:Non-destructive testing protocols using ultrasonic and magnetic particle methods detect crack propagation in high-alloy rotors operating above 540°C inlet temperatures.
- Maintenance:Preventive schedules encompassing lubrication system service, control valve calibration, and gland seal replacement sustain availability metrics under grid reliability protocols.
The dominant share belongs to Overhaul, while Repair is closing the gap fastest as predictive monitoring shifts failure detection earlier in degradation cycles.
Component:
Component hierarchy follows metallurgical complexity and replacement lead time, with forged alloy parts commanding premium pricing and extended procurement cycles.
- Rotors:High-alloy steel forgings operating at steam pressures above 24 MPa require specialized welding and heat treatment capabilities concentrated in limited certified facilities. Asian ultra-supercritical fleets above 600°C inlet temperatures are driving demand for advanced alloy repair expertise.
- Bearings:Tilting-pad and journal bearing replacements address oil film instability and white metal fatigue, with turnaround time critical for baseload plant economics.
- Seals:Labyrinth and carbon ring configurations minimize steam leakage losses, with retrofit designs targeting efficiency gains under emissions compliance pressure.
- Valves:Governor and stop valve refurbishment restores precise steam flow control, with digital actuator upgrades displacing legacy hydraulic systems.
Rotor work captures the highest margin tier, though Seal demand is expanding most quickly as efficiency retrofit programs prioritize leakage reduction.
End User:
End-use concentration determines outage scheduling flexibility and contract bundling preferences, with grid-connected assets facing stricter reliability mandates than industrial cogeneration.
- Power Plants:Utility-scale thermal generators face insurance-mandated inspection intervals and grid operator availability requirements that sustain scheduled overhaul volumes. United States coal fleet operators are prioritizing digital monitoring retrofits over mechanical investments to manage carbon policy uncertainty.
- Oil & Gas:Refinery and petrochemical steam turbine drivers operate in process-critical roles where unplanned outages trigger cascading production losses.
- Manufacturing Facilities:Industrial cogeneration units balance electricity export against process steam demand, with maintenance windows constrained by production schedules.
- Marine:Naval and commercial propulsion turbines face saltwater corrosion challenges and classification society survey requirements distinct from stationary applications.
Power Plants anchor procurement volume, while Oil & Gas is gaining share fastest as downstream capacity expansion in the Middle East and Asia drives new installation MRO demand.
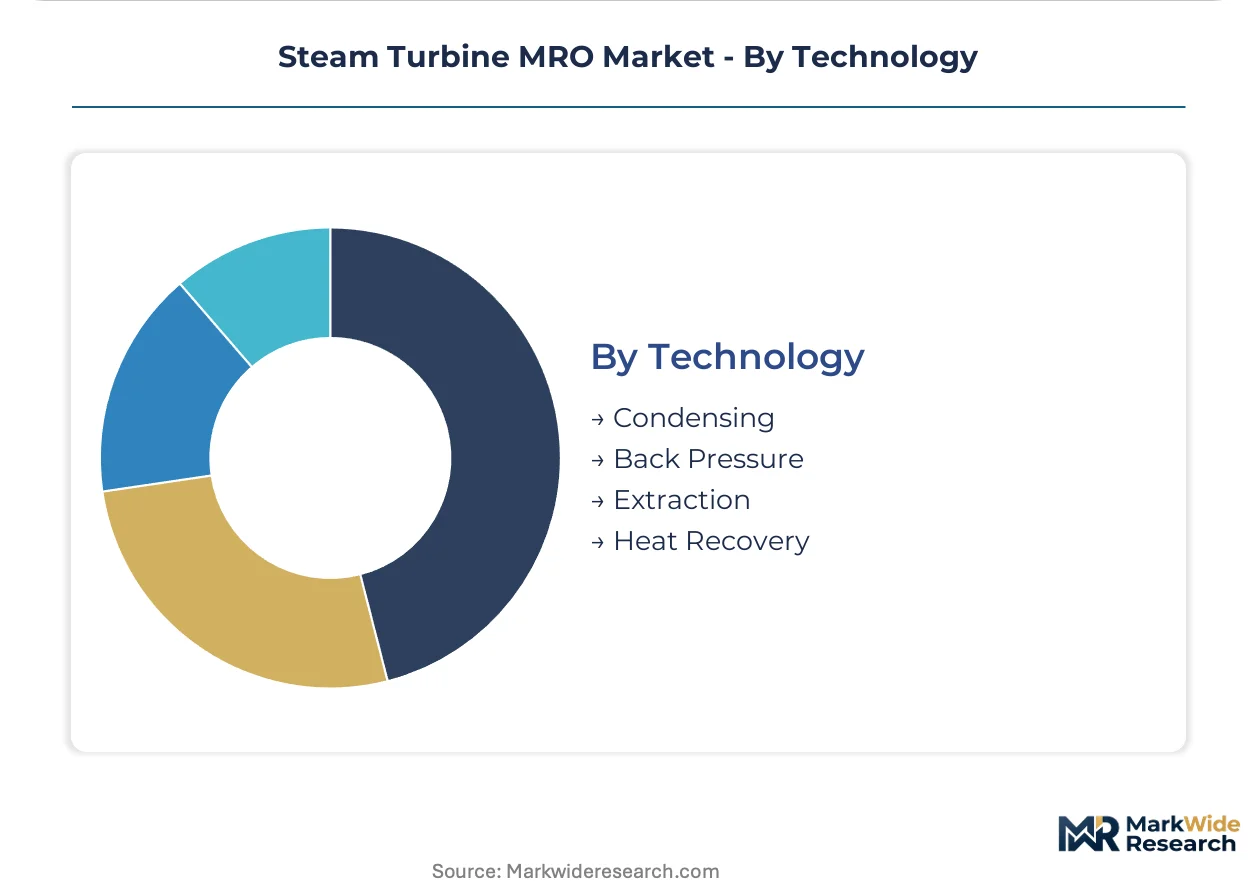
Technology:
Technology segmentation reflects thermodynamic cycle design and operating parameter envelope, with each configuration presenting distinct degradation modes and restoration protocols.
- Condensing:Vacuum-sustained exhaust configurations dominate the installed base, with air ingress and cooling water chemistry driving blade corrosion and deposit accumulation. Germany and Japan are piloting additive manufacturing repairs for eroded last-stage blades to compress critical path schedules.
- Heat Recovery:Combined-cycle bottoming turbines operate at lower inlet temperatures but higher cycling frequency, creating thermal fatigue challenges in casing and rotor interfaces. Combined-cycle additions across Asia and the Middle East are expanding this service segment distinct from traditional baseload unit protocols.
- Extraction:Controlled bleed designs for process steam supply require precise governor valve maintenance to sustain extraction pressure stability.
- Back Pressure:Exhaust steam delivery for industrial process heat eliminates condenser maintenance but intensifies blade erosion from wet steam conditions.
Condensing technology retains the largest installed base, though Heat Recovery is climbing the fastest as combined-cycle deployment outpaces conventional thermal additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions mandates are accelerating retrofit investments across United States coal fleets, while India's Central Electricity Authority enforces boiler and turbine inspection protocols that expand overhaul budgets. Germany and Japan are piloting additive manufacturing repairs to compress critical path schedules for aging baseload units.
United States
Utility operators under EPA emissions standards are prioritizing digital monitoring retrofits over mechanical overhauls to demonstrate heat rate improvements. FERC grid reliability protocols enforce scheduled major inspections that sustain overhaul service volumes. The Ohio River Valley and Texas Gulf Coast host concentrated coal and combined-cycle fleets where operators weigh residual asset value against carbon policy uncertainty.
Germany
Coal phase-out timelines are compressing maintenance investment windows while forcing efficiency upgrade commitments on remaining baseload units. The EU Green Deal and national coal exit legislation mandate emissions compliance benchmarks that turbine vendors must certify against. Siemens Energy anchors multi-year service contracts through captive blade manufacturing capabilities concentrated in industrial clusters across Bavaria and North Rhine-Westphalia.
India
State-run utilities under CEA technical standards are expanding overhaul budgets to address aging supercritical and subcritical installations exceeding original design life. The PLI scheme for manufacturing and domestic content requirements shape procurement preferences for indigenous service providers. Maharashtra and Gujarat host dense concentrations of thermal capacity where Bharat Heavy Electricals Limited and domestic OEMs compete for modernization contracts.
China
Dual carbon goals and MIIT efficiency standards are forcing turbine efficiency upgrades or retirement decisions across provincial utility fleets. GB standards and SAMR certification requirements govern contractor qualification for high-temperature alloy repairs. The Yangtze River Delta and Shandong Peninsula concentrate ultra-supercritical capacity above 600°C inlet temperatures that demand advanced metallurgical expertise.
Japan
METI energy security priorities sustain baseload thermal operations despite renewable expansion, preserving overhaul demand for high-efficiency units. JIS standards and periodic inspection mandates under the Electricity Business Act enforce rotor and blade replacement cycles. Chubu and Kansai industrial corridors host combined-cycle and ultra-supercritical fleets where Mitsubishi Power specializes in advanced alloy rotor repairs.
Steam Turbine MRO Market Vendor Landscape
On the supply side, the industry is consolidating around integrated OEM-service bundles that displace transactional procurement. Major turbine manufacturers leverage captive component manufacturing and digital monitoring platforms to anchor long-term maintenance contracts. Two strategic archetypes dominate: full-service OEMs with backward-integrated component supply, and specialized repair contractors with certified high-alloy welding capabilities. Competitive moves center on technology licensing partnerships for additive manufacturing repairs and geographic expansion through regional service hub establishment.
Among European-anchored full-service providers, Siemens Energy and GE Vernova exemplify the integrated OEM archetype through multi-year service agreement financing. Mitsubishi Power occupies a position representing Asian ultra-supercritical specialization. EthosEnergy and Sulzer sit within the independent contractor tier, competing on turnaround speed and certified repair shop access where OEM bundles face procurement resistance.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| Mitsubishi Power |
| Bharat Heavy Electricals Limited |
| Dongfang Electric Corporation Limited |
| Shanghai Electric |
| EthosEnergy |
| Harbin Electric |
| Sulzer |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European rotor repair facilities is compressing pricing power for high-alloy welding services while extending lead times for Asian ultra-supercritical fleet operators. This utilization asymmetry drives procurement fragmentation, with Indian and Chinese utilities accepting premium pricing for certified capacity while North American operators delay commitments amid carbon policy uncertainty.
Pricing Analysis
Certification level under ASME PTC-6 and ISO 9001 protocols creates the primary spread between premium OEM-anchored contracts and independent repair shop quotations. Three-tier pricing structure across premium, standard, and economy levels reflects warranty term length, turnaround guarantee, and digital monitoring bundling. Cost compression in the independent contractor tier is intensifying because OEMs are financing long-term service agreements at below-market rates to lock out competitors. Industrial cogeneration operators in manufacturing facilities exhibit highest price sensitivity due to production-schedule constraints, while utility-scale power plants under grid reliability mandates accept premium pricing for outage certainty.
Supply Chain Analysis
High-alloy steel forgings for rotor segments draw from specialized foundries concentrated in Germany, Japan, and the United States. Nickel-based superalloys, precision bearings, and digital control systems feed from aerospace and automotive supplier networks with limited power-generation-dedicated capacity. Single-source vulnerability concentrates in certified welding consumables for 600°C-plus inlet temperature repairs. Distribution runs through OEM captive service networks and independent repair hubs, with regional qualification requirements fragmenting procurement across jurisdictional boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cyclical recovery anchored to EPA emissions compliance deadlines and India's CEA-mandated inspection cycles, with overhaul demand inflecting as baseload units approach statutory maintenance windows.
For Market Incumbents: Pre-empt independent contractor encroachment by expanding captive blade manufacturing capacity in India and the Middle East, where domestic content requirements and combined-cycle buildouts concentrate procurement. Lock in multi-year service agreements before carbon policy uncertainty freezes utility capital commitments, leveraging backward integration into high-alloy forging supply to defend margin position against price-competitive Asian OEMs. For New Entrants and Emerging Players: Pursue heat recovery steam turbine maintenance as the most penetrable segment, where combined-cycle cycling frequency creates thermal fatigue repair demand distinct from established condensing unit protocols. Target Middle Eastern oil and gas downstream expansion, where process-critical turbine roles prioritize turnaround speed over OEM brand loyalty. Enter through additive manufacturing repair partnerships that compress critical path schedules for aging German and Japanese baseload units. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because independent repair shop concentration in certified high-alloy welding creates roll-up opportunity as workforce aging accelerates generational transfer. Focus acquisition screening on European and North American contractors with ASME PTC-6 qualification and established utility relationships. Watch EPA retirement timeline clarity as the inflection signal that releases pent-up overhaul demand or accelerates asset abandonment.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Certification | Enables in-situ rotor repair for ultra-supercritical units above 600°C, compressing outage windows. |
| Long-Term Service Agreement Financing | Locks out independent competitors through below-market rate bundling of OEM component supply. |
| Regional Service Hub Establishment | Positions contractors near India's Maharashtra and Gujarat thermal clusters under CEA inspection mandates. |
| Digital Monitoring Platform Integration | Extends predictive maintenance contracts through sensor network convergence with performance guarantees. |
| Advanced Alloy Repair Expertise Licensing | Transfers metallurgical capabilities to Asian utility fleets operating supercritical installations. |
Methodological Framework
Cross-validation between primary interviews with utility planning officers, EPC contractors, aftermarket service heads, and OEM procurement teams anchors the qualitative findings against secondary validation from EIA capacity data, IEA power generation statistics, FERC reliability filings, and EPA emissions compliance records. Bottom-up triangulation aggregates individual plant overhaul schedules and contract announcements, while top-down calibration checks against national thermal fleet age profiles and regulatory mandate timelines.
Calibration against historical CAGRs from comparable capital equipment maintenance markets shapes the projection framework across service type, component hierarchy, end-use concentration, and technology vintage segmentation throughout the forecast period. Modeling incorporates operating hour accumulation curves, insurance-mandated inspection intervals, and carbon policy scenario branches. Forecast inputs include grid reliability protocol evolution and metallurgical workforce replacement rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments for utility capital budgeting or commodity price volatility for high-alloy steel inputs would shift the trajectory. Cross-checking against IEA power sector investment benchmarks and regional utility regulatory filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Power Shelf Market
Power
High Voltage DC Power System Market
Power
Argentina Power Market
Power
Angola Power EPC Market
Power
Brazil Power Market
Power
United States Power Market
Power
Europe Microturbine Market
Power
Kuwait Power Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
North America Microturbine Market
Power
Denmark Power Market
Power
Portugal Power Market
Power
North America CHP Market
Power
Global UPS Market
Power
Existent Gum Steam Generator Market
Power
Oxy-Hydrogen Generators Market