
 Power Shelf Market | 2026-2036
Power Shelf Market Size, Share, and Industry Trends Forecast 2026-2036
Power Shelf Market Insights
Power electronics engineering talent scarcity is unwinding across the supply base as data center buildouts accelerate faster than vocational pipelines refill. Schneider Electric leverages its European R&D footprint to sustain design leadership in modular power architectures. Delta Electronics anchors Asia-Pacific production through captive manufacturing in Taiwan and Thailand.
A power shelf is an integrated electromechanical enclosure housing rectifiers, distribution buses, and monitoring circuitry to deliver conditioned DC power to server racks or telecom equipment, typically rated from 48V to 400V depending on application. Its primary purpose is to consolidate power conversion, backup integration, and thermal management into a standardized form factor that slots into 19-inch or 23-inch rack systems. Mounted systems dominate commercial deployments due to their compatibility with existing data center infrastructure and lower installation overhead. Metal construction, predominantly aluminum and steel alloys, leads material selection for thermal conductivity and electromagnetic shielding requirements.
FCC Part 15 emissions standards in the United States and CE marking under the EU Low Voltage Directive constrain product entry by mandating conducted and radiated noise thresholds. China's GB standards for information technology equipment impose additional efficiency minimums that shape design priorities for suppliers targeting domestic deployment. Stakeholders must monitor how regional efficiency mandates diverge and whether harmonization efforts emerge through IEC working groups.
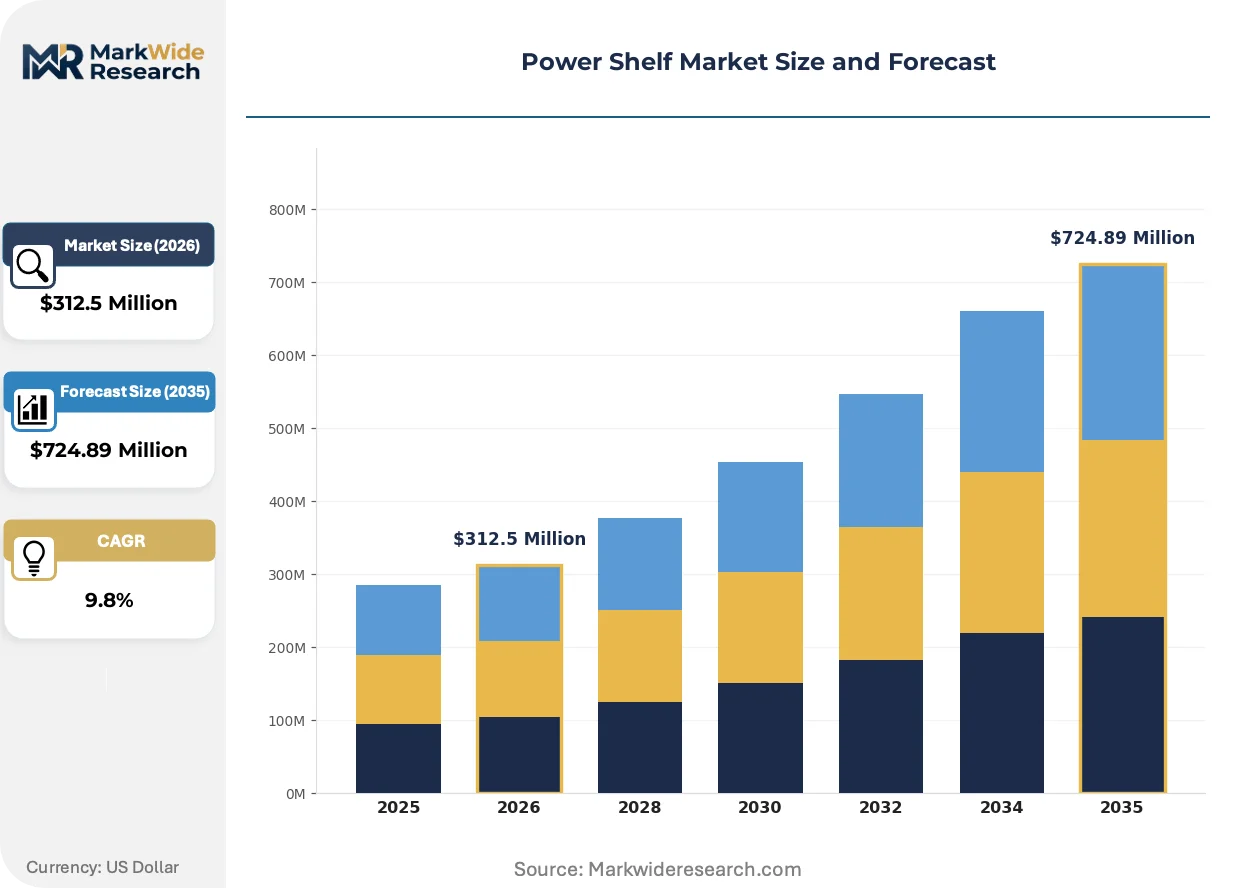
Market Dynamics
The transition from 48V to 400V DC architectures in hyperscale data centers is compressing power shelf form factors while multiplying thermal density requirements. This voltage elevation is forcing simultaneous redesigns of rectifier modules, busbar geometries, and cooling interfaces across the supply base.
Growth Catalysts
- EU Energy Efficiency Directive:Tightening standby power thresholds for electrical infrastructure are mandating higher-efficiency rectifier designs in German industrial corridors and Dutch server farms.
- Data center buildout acceleration:Rack-level power distribution investments by North American cloud operators are pulling demand for standardized 19-inch and 23-inch form factors.
- Silicon carbide (SiC) MOSFETs:Wide-bandgap semiconductor adoption is enabling higher switching frequencies that reduce passive component volume in 400V architectures.
Market Restraints
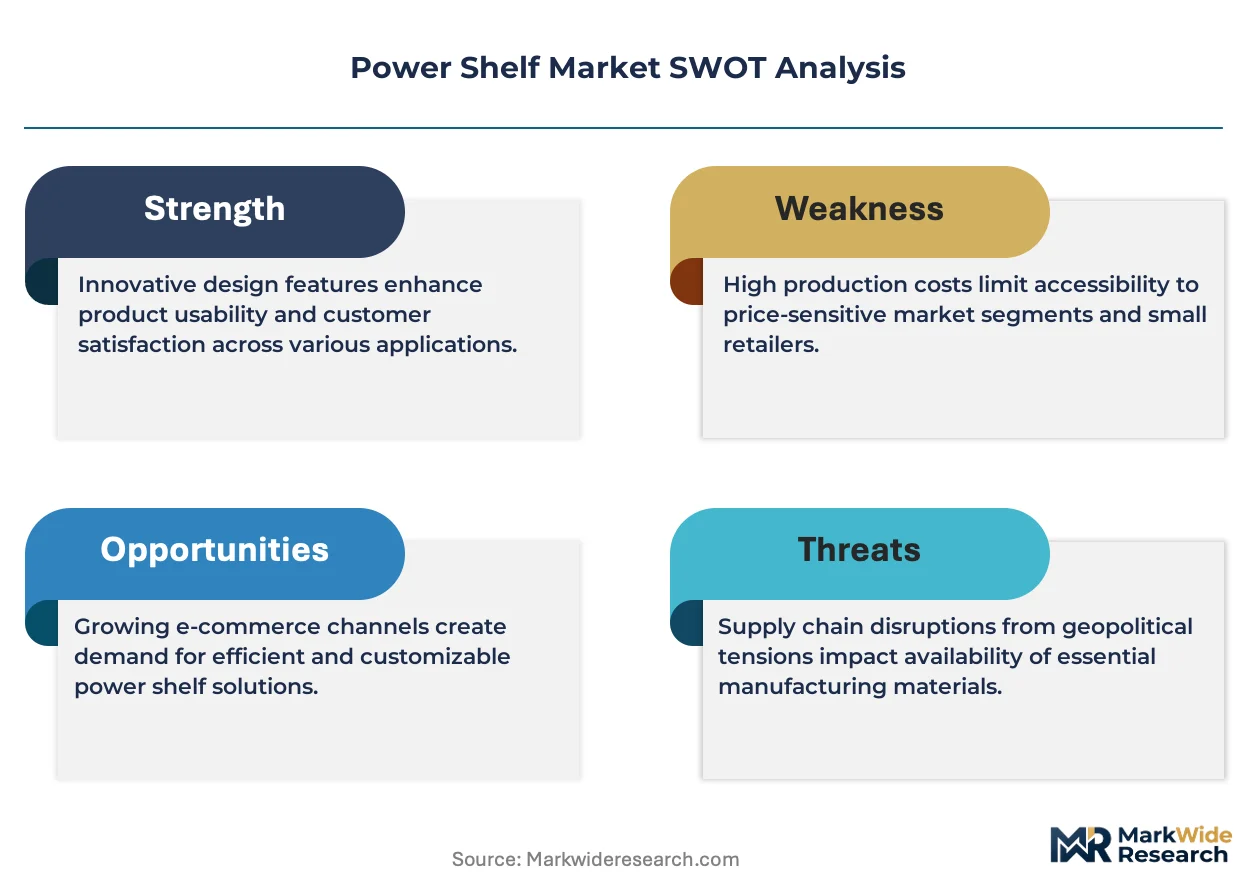
- Copper and aluminum price volatility:Busbar and chassis material costs fluctuate with commodity markets, squeezing margin stability for metal-intensive enclosure production.
- Taiwanese foundry concentration:Power semiconductor wafer fabrication clusters heavily on the island, creating single-point vulnerability for SiC and GaN device sourcing.
- Electromagnetic compatibility certification:FCC Part 15 emissions testing and CE marking under the EU Low Voltage Directive impose multi-month validation timelines before commercial deployment.
Strategic Opportunities
- India's data center expansion:The country's PLI scheme for electronics manufacturing is attracting power shelf assembly investments to serve domestic cloud infrastructure buildouts.
- Liquid cooling convergence:Integration of direct-to-chip thermal management with high-voltage DC distribution creates bundled system opportunities in AI training clusters.
- China GB standards efficiency mandates:Domestic efficiency minimums for information technology equipment are creating specification premiums for suppliers that exceed baseline thresholds.
Industry Challenges
- Power electronics engineering scarcity:Vocational pipeline refill rates lag behind data center construction velocity, stretching design team capacity across OEMs and contract manufacturers.
- Legacy 48V system integration:Retrofitting existing telecom central offices with 400V-capable shelves requires custom adapter architectures that fragment product roadmaps.
- IEC harmonization delays:Diverging regional efficiency test methodologies between European working groups and North American standards bodies prolong multi-market certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Shelf Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $724.89 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Shelves, Adjustable Shelves, Standalone Units, Mounted Systems End User: Retail Stores, Warehouses, Restaurants, E-commerce Material: Metal, Plastic, Wood, Composite Application: Display, Storage, Refrigeration, Organization |
| Companies Covered | Huawei Digital Power, LITEON Technology, Schneider Electric, Siemens, ABB, Eaton, Delta Electronics, GE, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Shelf Market Trends and Innovations
Power shelf architectures are compressing vertically as voltage ratings climb, forcing convergence between thermal management and electromagnetic design disciplines. This structural shift is redrawing competitive boundaries between traditional power supply vendors and thermal solution specialists.
Gallium nitride (GaN) power transistors are displacing silicon MOSFETs in intermediate bus converters. Hyperscale operators in Oregon and Virginia are qualifying GaN-based shelves for 400V input stages. The technology is miniaturizing magnetic components by 40-60% compared to silicon equivalents, enabling higher rack density without expanding physical footprint.
REACH substance restrictions and RoHS recast directives in Europe are eliminating hexavalent chromium finishes and certain flame retardants from enclosure coatings. Manufacturers serving EU data centers are migrating to trivalent chrome passivation and halogen-free PCB substrates. German industrial corridor retrofits show the steepest compliance-driven specification upgrades, with operators rejecting non-compliant bids regardless of cost position.
Specification authority is migrating from facilities engineering to IT procurement teams as power shelves become software-defined infrastructure elements. Colocation providers in Northern Virginia and Frankfurt are demanding API-accessible telemetry and predictive maintenance contracts bundled with hardware. This purchasing pattern shift compresses traditional channel margins and rewards vendors with embedded firmware development capabilities.
Power Shelf Market Segmentation
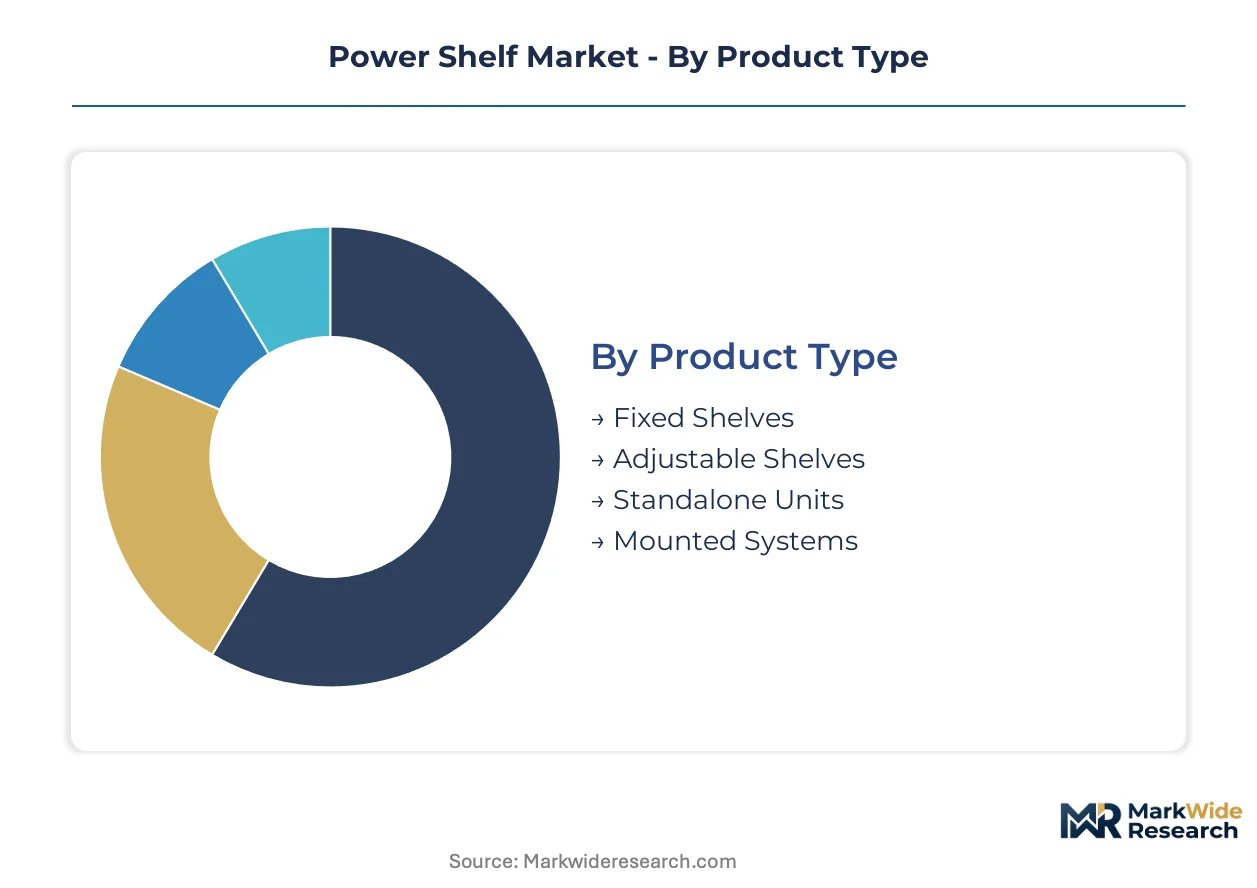
Power shelf segmentation reveals how voltage architecture choices and enclosure specifications fragment procurement patterns across data center, telecom, and industrial verticals. Material selection and mounting configurations directly determine thermal performance ceilings and electromagnetic compliance pathways.
Product Type:
Margin pools concentrate in integrated systems that consolidate rectification, distribution, and monitoring into single-sku procurement packages.
- Fixed Shelves:Rigid chassis designs with predetermined busbar layouts suit standardized 48V legacy installations. Demand clusters in German industrial corridor retrofits where operators prioritize compatibility over reconfigurability.
- Adjustable Shelves:Modular architectures allow field-reconfigurable voltage taps and breaker positioning. North American hyperscale operators in Oregon and Virginia specify these for 400V migration pathways that accommodate future rack rebalancing without full replacement.
- Standalone Units:Self-contained power conversion skids serve edge computing nodes outside traditional data center footprints.
- Mounted Systems:Rack-integrated form factors dominate commercial deployments through lower installation overhead and existing 19-inch infrastructure compatibility.
The dominant share belongs to Mounted Systems, while Adjustable Shelves is closing the gap fastest.
End User:
Volume concentration tracks capital expenditure cycles in digital infrastructure buildouts rather than traditional commercial real estate.
- Retail Stores:Edge computing installations for inventory management and customer analytics drive compact 48V shelf demand. Deployment concentrates in omnichannel fulfillment networks where localized processing reduces latency for real-time pricing systems.
- Warehouses:Automated material handling and robotics charging infrastructure pull high-current 400V architectures. Fulfillment centers in Northern Virginia and the Netherlands specify liquid-cooled shelves for continuous-duty conveyor and AGV power delivery.
- Restaurants:Kitchen automation and digital ordering platforms create distributed power requirements.
- E-commerce:Last-mile sortation facilities and micro-fulfillment centers deploy standardized rack power for server clusters.
Warehouse applications command the highest unit values, while Retail Stores is expanding most quickly through edge infrastructure proliferation.
Material:
Cost tier stratification separates aerospace-grade alloys from commodity enclosures across certification-grade applications.
- Metal:Aluminum and steel alloys provide thermal conductivity and electromagnetic shielding for high-density 400V installations. REACH and RoHS recast directives in Europe are eliminating hexavalent chromium finishes, pushing German operators toward trivalent chrome passivation.
- Plastic:Glass-reinforced polymers serve low-voltage signal distribution and non-thermal-critical junction boxes. Demand concentrates in cost-sensitive edge deployments where weight reduction outweighs heat dissipation requirements.
- Wood:Historic preservation and aesthetic requirements in retail environments drive niche specification.
- Composite:Carbon-fiber-reinforced enclosures address aerospace and military applications requiring strength-to-weight optimization.
Metal construction retains the largest installed base, though Plastic is gaining share fastest in distributed edge infrastructure.
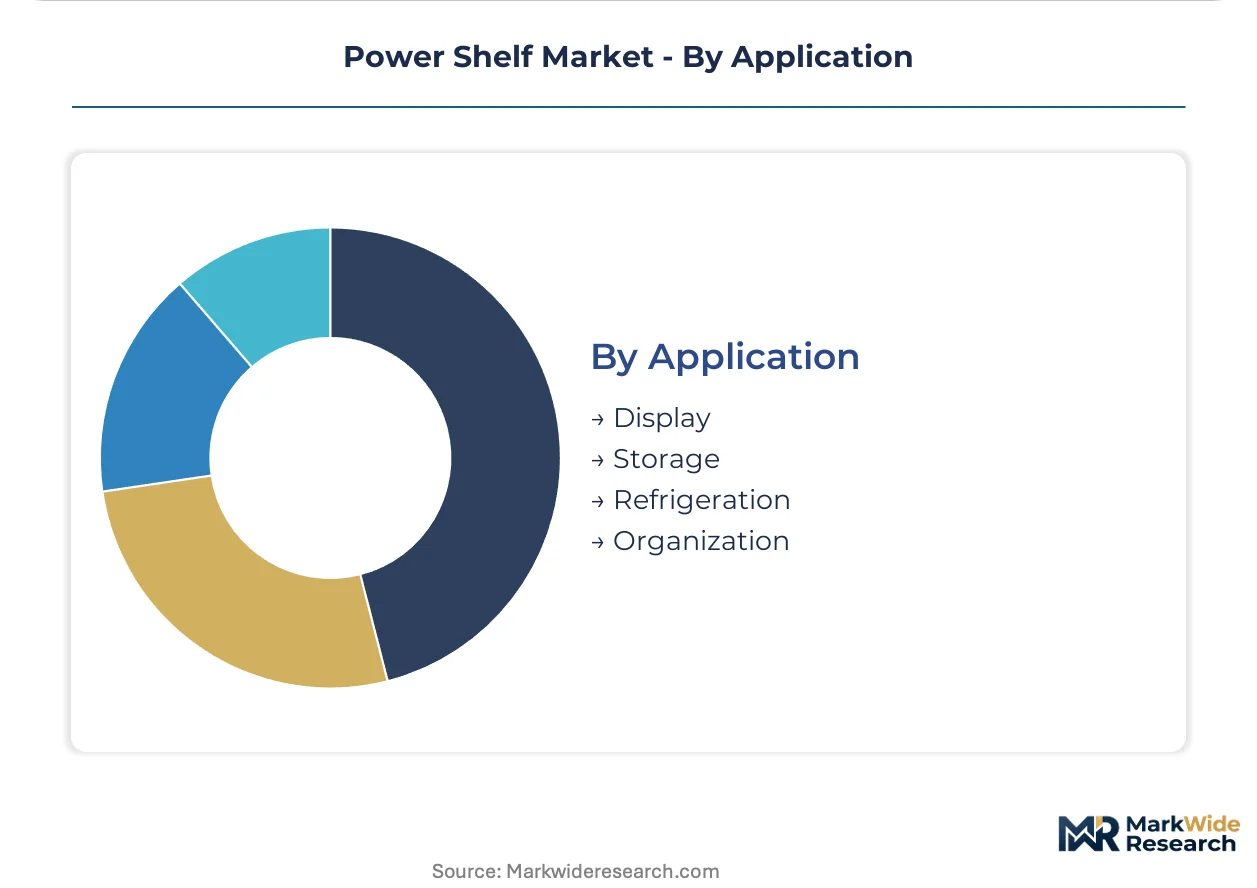
Application:
Specification authority migrates from facilities engineering to IT procurement as power shelves become software-defined infrastructure elements.
- Display:Exhibition and retail environments require silent operation and aesthetic integration. Frankfurt and Northern Virginia colocation providers bundle API-accessible telemetry with hardware for predictive maintenance contracts.
- Storage:Data center rack power for server and storage arrays dominates commercial volume. FCC Part 15 emissions testing and CE marking under the EU Low Voltage Directive impose multi-month validation timelines.
- Refrigeration:Cold chain monitoring and compressor control in food service create 48V distribution requirements.
- Organization:Cable management and power distribution consolidation in telecom central offices.
Storage applications generate the highest revenue concentration, while Display is climbing the fastest through colocation provider procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: North American hyperscale operators prioritize 400V migration pathways, European industrial corridors enforce efficiency mandates through regulatory compliance, and Asia-Pacific manufacturing hubs anchor component supply chains for wide-bandgap semiconductors.
United States
Hyperscale data center construction in Oregon and Northern Virginia drives demand for adjustable 400V power shelves with API-accessible telemetry. FCC Part 15 emissions standards constrain product entry through multi-month validation timelines. Oregon's cloud computing clusters are qualifying GaN-based architectures for high-density server racks.
Germany
Industrial corridor retrofits concentrate procurement for fixed 48V shelves compatible with legacy telecom infrastructure. REACH substance restrictions and RoHS recast directives eliminate hexavalent chromium finishes from enclosure coatings. The Ruhr Valley manufacturing belt shows the steepest compliance-driven specification upgrades, rejecting non-compliant bids regardless of cost position.
China
Domestic cloud infrastructure buildouts pull demand for metal-constructed shelves meeting GB standards efficiency minimums. MIIT information technology equipment regulations impose additional efficiency thresholds that shape design priorities. Yangtze River Delta data center clusters are retrofitting facilities with liquid-cooled 400V architectures for AI training workloads.
India
Data center expansion under the PLI scheme for electronics manufacturing attracts power shelf assembly investments to serve domestic cloud infrastructure. BIS certification requirements and CEA electrical infrastructure guidelines constrain product entry timelines. Maharashtra's Mumbai-Pune corridor hosts the fastest-growing concentration of colocation facilities specifying rack-integrated form factors.
Japan
Telecom central office modernization creates demand for legacy 48V system integration with custom adapter architectures. METI energy efficiency guidelines and JIS standards shape procurement specifications for industrial applications. Tokyo-Osaka corridor operators are compressing power shelf form factors while multiplying thermal density requirements for edge computing nodes.
Power Shelf Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated R&D capabilities determining design leadership in modular power architectures. The upper tier commands specification authority through embedded firmware development and captive semiconductor sourcing, while mid-scale fabricators compete on metalworking precision and regional certification speed. Two strategic archetypes dominate: vertically integrated power electronics conglomerates with foundry relationships, and thermal-management specialists converging on electromechanical integration. Competitive moves concentrate on capacity expansion in Taiwan and Thailand manufacturing clusters, and strategic partnerships between enclosure fabricators and wide-bandgap semiconductor suppliers.
Within the integrated conglomerate tier, Schneider Electric exemplifies European R&D footprint leverage in modular architectures, while Delta Electronics anchors Asia-Pacific production through captive manufacturing in Taiwan and Thailand. Huawei Digital Power occupies a position representing Chinese domestic supply chain integration for GB standards compliance. These three entities illustrate how geographic production clustering aligns with regional regulatory specialization.
| Leading Market Players |
|---|
| Huawei Digital Power |
| LITEON Technology |
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| Delta Electronics |
| GE |
| Vertiv |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Taiwanese foundries serving wide-bandgap semiconductor production shapes both supply concentration and price floors across power shelf tiers. Metal-intensive enclosure fabrication draws from commodity-linked aluminum and steel markets, compressing margin stability when raw material volatility intersects with hyperscale procurement consolidation.
Pricing Analysis
Long-term offtake agreements dominate procurement between North American cloud operators and integrated power electronics vendors, locking in volume commitments against spot-market aluminum volatility. Three-tier pricing structure across premium, standard, and economy levels separates API-telemetry-enabled shelves from basic fixed-configuration units, with hyperscale buyers least sensitive to unit cost and edge computing deployers most price-responsive. Cost compression in standard-tier metal enclosures is intensifying because Chinese GB standards compliance investments are raising baseline manufacturing expenses. Project-based pricing persists for legacy 48V retrofits in German industrial corridors where custom adapter architectures fragment procurement scale.
Supply Chain Analysis
Just-in-time inventory strategies prevail among North American hyperscale operators, while European industrial buyers maintain strategic stockpiles of SiC MOSFETs against Taiwanese foundry concentration risk. Component sourcing draws from Taiwan for wide-bandgap semiconductors, Thailand for final assembly, and China for aluminum extrusions and PCB substrates. Single-source vulnerability in SiC wafer fabrication creates supply chain risk that propagates through 400V architecture rollouts. Distribution runs through direct vendor relationships with data center developers and colocation providers, bypassing traditional electrical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American hyperscale operators and European colocation providers, compressing channel margins and rewarding vendors with embedded firmware capabilities. This consolidation demands differentiated strategic responses across incumbent, entrant, and investor archetypes.
For Market Incumbents: Compound design leadership in modular power architectures by deepening captive semiconductor sourcing relationships and expanding API-accessible telemetry development. SiC MOSFET supply concentration threatens production continuity; backward integration into wide-bandgap device qualification programs in Taiwan and Thailand manufacturing clusters defends margin position against component cost volatility. For New Entrants and Emerging Players: Lead with liquid-cooled 400V shelf integration for AI training clusters in India's Mumbai-Pune corridor, where PLI scheme incentives and domestic cloud buildouts create specification white space. Edge computing nodes outside traditional data center footprints offer the most penetrable application tier; pursue direct-to-developer sales models that bypass established electrical distribution channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal-management specialists converging on electromechanical integration over pure-play power supply vendors. Long-term viability hinges on software-defined infrastructure capabilities and regional certification speed across FCC, CE, and GB standards regimes. The signal to watch is hyperscale operator qualification timelines for GaN-based architectures, which indicate technology transition velocity and vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Semiconductor Partnership | GaN and SiC device sourcing agreements with Taiwanese foundries secure 400V architecture supply continuity. |
| Liquid Cooling Integration | Direct-to-chip thermal management bundling addresses AI training cluster density requirements in Oregon and Virginia. |
| API-Accessible Telemetry Development | Predictive maintenance contracts with Northern Virginia colocation providers shift procurement authority to IT teams. |
| Regional Certification Acceleration | Parallel FCC Part 15 and CE marking validation compresses multi-month timelines for German industrial corridor retrofits. |
| India PLI Scheme Manufacturing Investment | Assembly localization serves domestic cloud infrastructure buildouts under BIS and CEA compliance frameworks. |
Research Methodology
The analysis maps fixed, adjustable, and standalone power shelf configurations, each validated through data center facilities engineers, cloud procurement officers, power electronics design leads, and thermal management specialists. Primary fieldwork combined structured interviews with secondary validation against SEC hyperscaler capex disclosures, EIA electrical infrastructure data, EU Energy Efficiency Directive regulatory filings, and customs records for aluminum and copper trade flows. Bottom-up unit economics triangulated against top-down market sizing across voltage architecture, material selection, and end-use verticals.
Consistency checks validated volume and value outputs against external benchmarks including hyperscale operator rack deployment disclosures and foundry capacity utilization reports. The analytical framework modeled product type, voltage architecture, material grade, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating SiC MOSFET adoption curves, data center construction pipelines, and efficiency mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale capital expenditure cycles or stable Taiwanese semiconductor foundry operations would require recalibration. Forecasts reflect assumptions regarding 400V migration velocity, REACH and RoHS compliance timelines, and PLI scheme continuity in India. Revision becomes warranted when wide-bandgap semiconductor supply concentration or aluminum price volatility crosses thresholds that alter OEM procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Static Synchronous Compensator (STATCOM) Market
Power
Qatar Power Market
Power
Solar UPS Market
Power
North America CHP Market
Power
Saudi Arabia Power Market
Power
India Power Market
Power
Kuwait Power Market
Power
Rotating Phase Converter Market
Power
Japan Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Smart Power Market
Power
Modular PSA Nitrogen Generator Market
Power
Russian Federation Power Market
Power
Residential Micro Inverter Market
Power
Water Turbine Market
Power
Robotic Power Source Market