
 Global Construction Robot Market | 2026-2036
Global Construction Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Robot Market Analysis
The EU Green Deal is repositioning the cost-of-entry calculus for European contractors, forcing capital allocation toward automated systems that can document embodied carbon reductions across project lifecycles. Komatsu leverages its integrated machine control ecosystem to anchor market presence in autonomous earthmoving. Built Robotics competes through pure-play autonomy stacks retrofitted onto existing equipment fleets. Caterpillar sustains dominance via manufacturing scale and dealer channel control across North American infrastructure corridors.
Construction robots encompass programmable electro-mechanical systems engineered to execute physical tasks on job sites, typically operating with positional accuracy within millimeters and payload capacities ranging from fifty kilograms for material handlers to multiple tonnes for autonomous excavators. Their primary commercial purpose centers on substituting labor in hazardous, repetitive, or precision-critical operations while generating machine-readable performance data for project management. Autonomous excavators currently occupy the largest product category, though aerial robotics for structural inspection is recording the fastest expansion as building height regulations tighten across urban jurisdictions. Collaborative robotics applications in structural assembly concentrate margin pools where human-robot workcell integration reduces cycle times without full site reconfiguration.
FDA workplace safety guidelines, OSHA fall-protection standards, and ISO 10218 robot safety frameworks collectively shape product certification requirements and deployment protocols for construction automation. Japan's METI productivity targets and South Korea's KOSHA industrial safety mandates further accelerate regulatory pull for certified autonomous systems in public infrastructure procurement. Stakeholders must monitor how evolving liability frameworks for autonomous machine incidents reshape insurance structures and contractor risk appetite.
Market Dynamics
Labor scarcity across developed economies is compressing contractor margins and forcing capital reallocation toward autonomous earthmoving and precision assembly systems that generate auditable productivity data.
Growth Catalysts
- EU Green Deal embodied carbon mandates:European contractors must document material waste reductions across project lifecycles, pulling investment toward precision automation with machine-readable carbon accounting.
- Japan's METI productivity targets:Public infrastructure procurement now favors certified autonomous systems, accelerating deployment of autonomous excavators and bricklaying robots in Tokyo-Osaka megaregions.
- Urban height regulation tightening:Singapore and South Korean commercial high-rise developers are expanding robot deployment for facade installation and rebar tying as manual labor costs escalate.
Market Restraints
- LiDAR and sensor input cost volatility:Precision navigation hardware remains exposed to semiconductor supply chain disruptions, inflating unit economics for mid-tier contractors.
- Technical limitation in unstructured terrain:Autonomous excavators struggle with geotechnical variability exceeding pre-mapped parameters, requiring human override protocols that dilute labor savings.
- OSHA and ISO 10218 certification friction:Multi-jurisdictional safety framework compliance extends deployment timelines by months, deferring ROI realization for fleet operators.
Strategic Opportunities
- Underpenetrated Indian infrastructure corridor:National highway and metro expansion projects lack automation penetration, creating first-mover advantage for earthmoving autonomy providers.
- Regulatory tailwind from South Korea KOSHA mandates:Industrial safety certification requirements for public works are creating procurement preference for certified robotic systems.
- Technology convergence of digital twin and predictive maintenance:Real-time structural modeling fused with autonomous equipment health monitoring is opening subscription revenue streams beyond hardware sales.
Industry Challenges
- Mechatronics and systems integration skill gap:Contractor workforces lack technicians capable of diagnosing hydraulic-pneumatic-electronic faults in collaborative robotics workcells.
- Capex intensity of fleet retrofitting:Existing equipment autonomy stack integration requires substantial upfront investment without guaranteed productivity gains in first-year deployment.
- ISO 10218 and FDA workplace safety certification timelines:Documentation and testing protocols for multi-robot job site coordination remain underdeveloped, delaying commercial rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Robot Market |
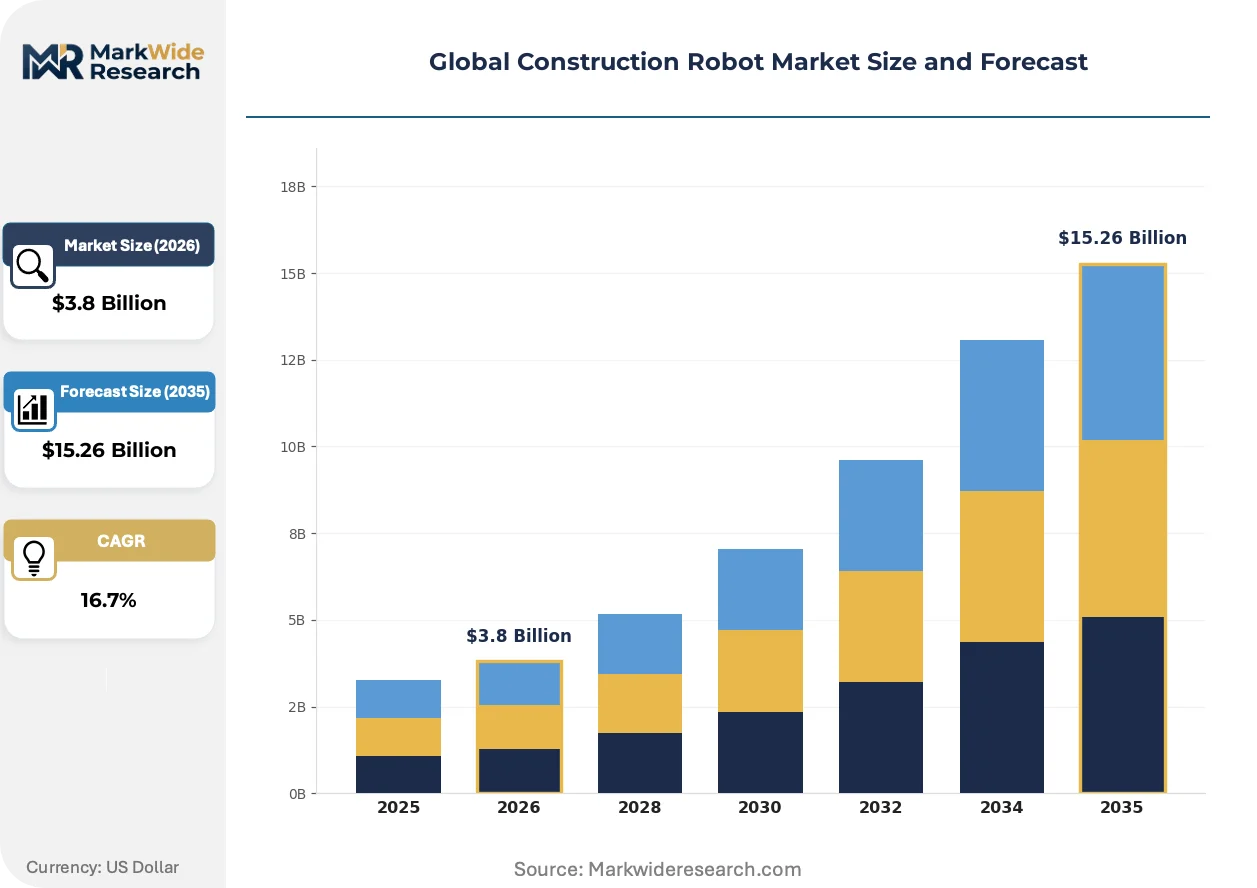
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerial Robotics, Autonomous Excavators, Bricklaying Robots, Material Handling Robots Application: Demos, Earth Moving, Structural Assembly, Site Cleaning Technology: AI-Powered, Collaborative Robotics, Autonomous Navigation, Robotics Process Automation End User: General Contractors, Specialty Contractors, Construction Managers, Construction Companies |
| Companies Covered | Komatsu, Caterpillar, Brokk AB, Husqvarna, ABB, Built Robotics, Doosan Robotics, Construction Robotics, Boston Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Robot Market Emerging Trajectories
Digital twin integration with autonomous equipment fleets is compressing project planning cycles and enabling real-time structural performance monitoring across distributed job sites.
Teleoperation backup systems for autonomous excavators are automating emergency intervention protocols when geotechnical sensors detect unmapped subsurface anomalies. Japanese contractors operating in seismic zones are mandating these hybrid control architectures, compressing insurance premium differentials between autonomous and manual fleets.
REACH substance restrictions and EU AI Act risk classification frameworks are reshaping component sourcing for European construction robot manufacturers. Battery chemistry and sensor material selections now require supply chain documentation that extends procurement cycles, pushing OEMs toward pre-certified subsystem vendors.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier European contractors. Munich and Amsterdam infrastructure clusters are piloting usage-based billing for autonomous rebar-tying systems, transferring obsolescence risk from balance sheets to OEMs while locking in multi-year data sharing agreements.
Global Construction Robot Market Segmentation
Construction robot segmentation reveals how technical specifications, deployment contexts, and buyer economics fragment investment priorities across the value chain. Distinct capability requirements separate earthmoving autonomy from precision assembly applications, while end-user scale determines whether procurement favors capital purchase or equipment-as-a-service models.
Product Type:
Mechanical payload capacity and positional accuracy specifications define competitive positioning within each product category, with navigation architecture complexity driving unit economics.
- Autonomous Excavators:Hydraulic earthmoving platforms integrate GNSS-RTK positioning and machine control systems to execute cut-fill operations within centimeter tolerances. Demand concentrates in Japanese public infrastructure procurement under METI productivity mandates, where certified autonomous fleets qualify for preferential bidding.
- Aerial Robotics:Multi-rotor and fixed-wing unmanned systems carry LiDAR payloads and high-resolution imaging for structural inspection at heights exceeding fall-protection thresholds. Singapore commercial high-rise developers deploy these systems for facade assessment as manual labor costs escalate and height regulations tighten.
- Bricklaying Robots:Gantry-mounted systems with adhesive dispensing and brick placement end-effectors achieve millimeter alignment repeatability for masonry courses.
- Material Handling Robots:Automated guided vehicles and robotic arms manage palletized logistics with fifty-kilogram to multi-tonne payload ranges depending on chassis configuration.
Autonomous excavators lead on scale; aerial robotics lead on momentum.
Application:
Site phase sequencing and hazard exposure levels determine automation feasibility, with early-stage earthworks commanding different technical architectures than finishing trades.
- Earth Moving:Mass excavation and grading operations leverage machine control integration to reduce survey staking labor and achieve design surface profiles without manual grade checking. European contractors facing EU Green Deal embodied carbon mandates deploy these systems to document material movement precision and waste reduction across project lifecycles.
- Structural Assembly:Steel erection and prefabricated component placement require collaborative robotics workcells combining human dexterity with robotic payload capacity. South Korean commercial developers expand deployment here as KOSHA safety certification creates procurement preference for certified robotic systems in high-rise construction.
- Demos:Selective dismantling and deconstruction robotics execute precision demolition in constrained urban sites.
- Site Cleaning:Autonomous sweepers and debris removal systems maintain work area accessibility during active construction phases.
Earth moving dominates current fleet deployment; structural assembly shows steepest expansion trajectory.
Technology:
Control system architecture separates adaptive autonomy from deterministic automation, with sensor fusion requirements scaling proportionally to environmental unpredictability.
- Autonomous Navigation:SLAM-based positioning combined with 3D perception enables operation in partially mapped environments without continuous human oversight. Japanese seismic zone contractors mandate teleoperation backup architectures, compressing insurance premium differentials between autonomous and manual earthmoving fleets.
- AI-Powered:Machine learning models trained on construction-specific visual datasets enable anomaly detection and predictive task planning for unstructured terrain adaptation.
- Collaborative Robotics:Force-limited manipulators with ISO 10218 safety certification enable human-robot workcell integration without full site reconfiguration.
- Robotics Process Automation:Software-based workflow automation handles document processing and compliance reporting distinct from physical task execution.
Autonomous navigation anchors commercial deployment; AI-powered systems are gaining share fastest.
End User:
Balance sheet capacity and project portfolio duration shape procurement modality preferences, with large-scale operators favoring fleet ownership and mid-tier contractors shifting toward subscription models.
- General Contractors:Prime contractors with multi-year project backlogs amortize autonomy stack investments across sufficient utilization hours to justify capital deployment. Munich and Amsterdam infrastructure clusters pilot equipment-as-a-service contracting for autonomous rebar-tying systems, transferring obsolescence risk to OEMs while locking in multi-year data sharing agreements.
- Construction Companies:Developer-owned construction divisions integrate robotics into captive project pipelines with standardized design specifications enabling repetitive automation deployment.
- Specialty Contractors:Trade-specific operators in rebar, concrete finishing, or facade installation deploy narrow-task robotics for concentrated skill substitution.
- Construction Managers:Third-party project oversight entities specify robotic performance standards without direct equipment ownership.
General contractors lead on fleet scale; construction companies lead on integration depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled construction labor shortages in Japan, South Korea, and Germany anchor regional deployment patterns for autonomous earthmoving and precision assembly systems.
Japan
Tokyo-Osaka megaregion contractors face acute demographic contraction in skilled trades. METI productivity targets now embed certified autonomous system requirements into public infrastructure procurement. Kanto contractors deploy autonomous excavators and bricklaying robots under seismic-zone teleoperation mandates that compress insurance premium differentials.
South Korea
Commercial high-rise developers in Seoul and Busan confront escalating manual labor costs for facade installation and rebar tying. KOSHA industrial safety mandates create procurement preference for certified robotic systems in public works. Seoul Capital Area construction clusters expand collaborative robotics deployment for structural assembly workcells.
Germany
Munich and Amsterdam infrastructure contractors pilot equipment-as-a-service models for autonomous rebar-tying systems. EU Green Deal embodied carbon mandates force capital reallocation toward precision automation with machine-readable carbon accounting. Bavarian earthmoving operators integrate machine control systems to document material waste reductions across project lifecycles.
Singapore
Urban height regulation tightening accelerates aerial robotics deployment for structural inspection at elevations exceeding fall-protection thresholds. Commercial high-rise developers expand robot deployment for facade installation as foreign worker quotas constrict manual labor supply. Marina Bay and Jurong Lake District construction clusters concentrate autonomous system adoption.
United States
OSHA fall-protection standards and infrastructure corridor labor scarcity compress contractor margins across Texas and California megaregions. North American earthmoving autonomy providers compete through retrofit stacks on existing equipment fleets. Southwest and Pacific Northwest construction clusters generate demand for autonomous navigation systems with teleoperation backup architectures.
Global Construction Robot Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive manufacturing scale and established dealer networks. Tier-one earthmoving OEMs leverage integrated machine control ecosystems to anchor market presence, while pure-play autonomy specialists compete through retrofit software stacks on existing equipment fleets. Strategic moves concentrate on technology licensing partnerships and equipment-as-a-service contracting models that transfer obsolescence risk from balance sheets to OEMs.
Within the diversified industrial tier, Komatsu and Caterpillar exemplify scale-driven positioning through manufacturing breadth and channel control across Japanese and North American infrastructure corridors. Built Robotics occupies the pure-play autonomy archetype, retrofitting existing equipment fleets with navigation software stacks. Among demolition and specialty robotics specialists, Brokk AB and Husqvarna represent focused equipment fabricators serving constrained urban site requirements.
| Leading Market Players |
|---|
| Komatsu |
| Caterpillar |
| Brokk AB |
| Husqvarna |
| ABB |
| Built Robotics |
| Doosan Robotics |
| Construction Robotics |
| Boston Dynamics |
| Others |
Supply Flow & Price Mechanics
Steel price indices and rare earth element benchmarks cascade through construction robot manufacturing tiers, compressing margins for mid-tier autonomy stack providers while concentrating pricing power with integrated OEMs that source hydraulic systems and LiDAR sensors through captive supply agreements in Japan and Germany.
Pricing Analysis
The bundled-vs-unbundled service split separates capital purchase models from equipment-as-a-service contracting prevalent among Munich and Amsterdam infrastructure clusters. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 10218 certification grade and after-sales telemetry integration. Cost compression in mid-tier excavator autonomy stacks intensifies because semiconductor supply chain disruptions inflate LiDAR input costs. Mid-tier European contractors exhibit highest price sensitivity, while Japanese public infrastructure prime contractors absorb premium pricing for METI-certified autonomous fleets.
Supply Chain Analysis
Workforce availability constraints in Japanese precision manufacturing zones and Bavarian hydraulic component clusters tether production capacity to regional vocational pipeline output. Component sourcing draws from South Korean battery cell manufacturers, Chinese rare earth processors, and German sensor subsystem fabricators. Single-source vulnerability concentrates in LiDAR sensor modules where semiconductor foundry allocation determines OEM delivery schedules. Distribution runs through captive dealer networks controlled by tier-one earthmoving manufacturers and direct-to-fleet retrofit partnerships for pure-play autonomy providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Construction Robot Market operates as a regulatory compounder where EU Green Deal embodied carbon mandates and Japan METI productivity targets mechanically pull capital toward certified autonomous systems regardless of near-term commodity price cycles.
For Market Incumbents: Anchor market position through backward integration into hydraulic-electric actuation systems and machine control firmware ecosystems that lock out retrofit competitors. Defend against pure-play autonomy specialists by embedding teleoperation backup architectures as standard features, compressing insurance premium differentials that otherwise favor manual fleet operators. Prioritize certification investment in ISO 10218 and KOSHA frameworks to capture South Korean and Japanese public procurement preference. For New Entrants and Emerging Players: The price-point gap between premium integrated OEM systems and economy-tier retrofit stacks creates white-space opportunity in Indian highway and metro expansion corridors where automation penetration remains minimal. Target equipment-as-a-service contracting for mid-tier European contractors seeking to transfer obsolescence risk from balance sheets. Deploy collaborative robotics workcells for structural assembly applications in Seoul Capital Area construction clusters where KOSHA safety mandates accelerate certified system procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play autonomy software specialists possessing SLAM navigation IP and construction-specific visual datasets that tier-one OEMs lack. Long-term viability hinges on recurring revenue streams from predictive maintenance subscriptions fused with digital twin integration rather than hardware sales cyclicality. Watch for inflection where equipment-as-a-service contracting penetration in European infrastructure clusters exceeds capital purchase volumes, signaling structural shift in buyer procurement modality.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers obsolescence risk to OEMs while locking multi-year data sharing agreements with Munich contractors. |
| Teleoperation Backup Architecture | Compresses insurance premium differentials for Japanese seismic-zone contractors deploying autonomous excavators. |
| ISO 10218 Certification Investment | Unlocks procurement preference in South Korean public works under KOSHA industrial safety mandates. |
| Digital Twin Platform Integration | Enables real-time structural monitoring and subscription revenue streams beyond hardware unit sales. |
| Indian Infrastructure Corridor Entry | Captures first-mover advantage in national highway and metro expansion projects lacking automation penetration. |
Methodological Framework
Coverage spans Japan, South Korea, Germany, Singapore, and the United States, with primary inputs from each construction cluster combining interviews with fleet operations directors, OEM product strategy leads, and public infrastructure procurement officers alongside secondary validation through METI productivity reports, EU Green Deal implementation guidance, and KOSHA safety certification databases. Bottom-up and top-down triangulation cross-references equipment shipment data with contractor capital expenditure disclosures and regulatory procurement preference frameworks.
Rate-of-change decomposition separates volume expansion from value capture across the analysis window, modeling product type segmentation by mechanical payload and navigation architecture complexity, application segmentation by site phase sequencing, and end-user segmentation by balance sheet capacity and project portfolio duration. CAGRs derive from trend extrapolation of autonomous fleet deployment rates in Japanese public infrastructure and equipment-as-a-service contracting adoption curves in European mid-tier contractor segments, incorporating semiconductor supply chain disruption scenarios and regulatory certification timeline assumptions.
Caveats apply where LiDAR sensor input cost volatility or multi-jurisdictional ISO 10218 certification friction could materially shift the outlook for mid-tier contractor adoption timelines. Forecasts reflect assumptions regarding regulatory pull persistence and labor scarcity compression across developed economy construction corridors. Material deviation in EU Green Deal enforcement intensity or Japanese demographic contraction velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Bot Services Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market