
 Recruiting Automation Software Market | 2026-2036
Recruiting Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Recruiting Automation Software Market Analytics
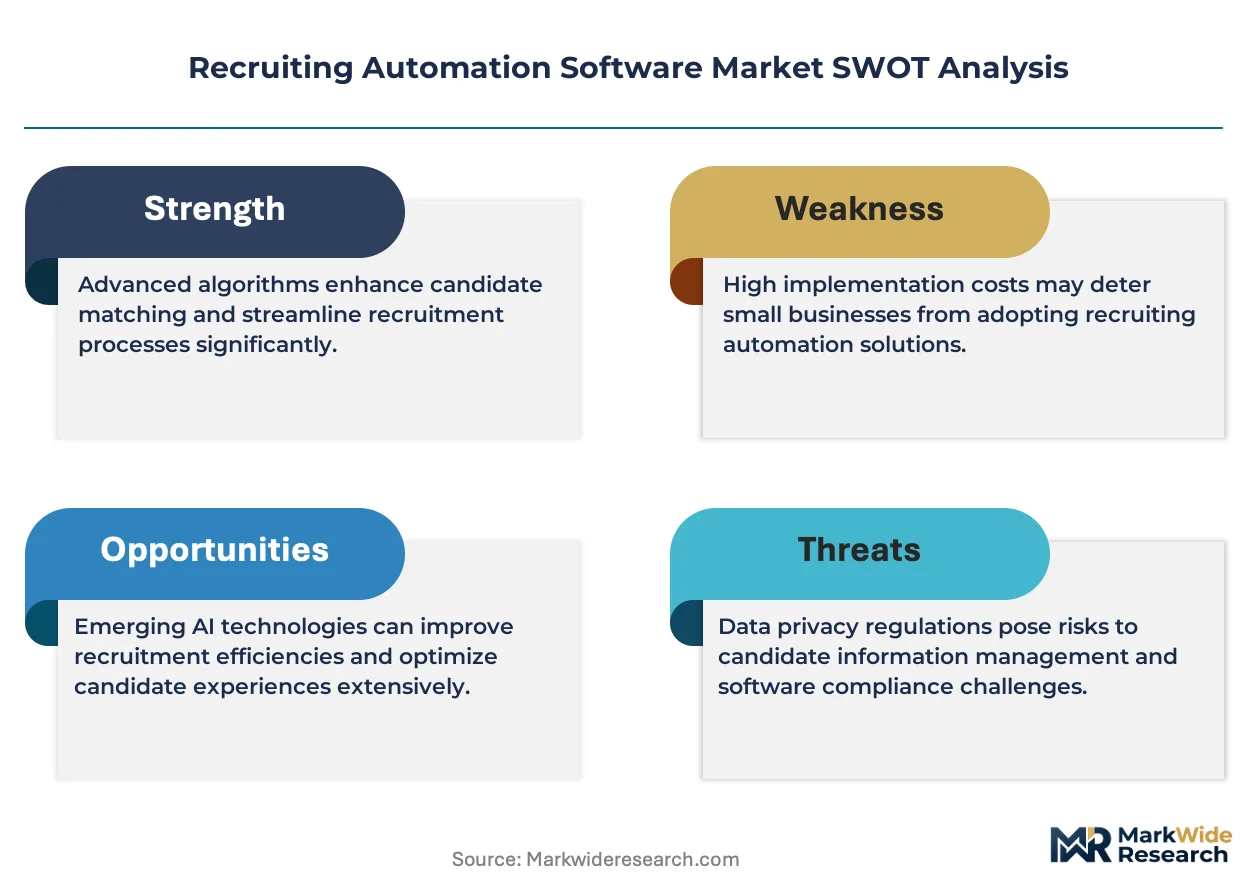
Buyer concentration among Fortune 500 employers is restructuring procurement patterns across the recruiting automation landscape. iCIMS leverages its enterprise-scale implementation footprint to dominate complex global hiring workflows. Greenhouse differentiates through open API architecture that sustains deep integration with existing HR technology stacks. Eightfold anchors its position with AI-driven talent intelligence that specializes in internal mobility and skills-based matching.
Recruiting automation software encompasses platforms that algorithmically manage candidate sourcing, screening, scheduling, and pipeline analytics through configurable workflow engines and machine learning models. These systems reduce time-to-fill metrics by automating repetitive touchpoints while maintaining audit trails for compliance documentation. Cloud-based deployment leads segment adoption due to lower capital requirements and faster implementation cycles, while applicant tracking system functionality captures the deepest incumbent spend as organizations modernize legacy databases. Analytics modules represent the fastest-expanding margin pool as talent acquisition teams demand predictive hiring intelligence.
The EU AI Act imposes strict conformity obligations on automated candidate evaluation tools, compelling vendors to document training data provenance and human oversight protocols. In the United States, the EEOC enforces anti-discrimination scrutiny of algorithmic hiring decisions under Title VII, while state-level frameworks like Illinois' Artificial Intelligence Video Interview Act mandate consent and transparency disclosures. Stakeholders must monitor evolving algorithmic accountability standards across multiple jurisdictions to ensure product roadmaps align with emerging compliance architectures.
Market Dynamics
Algorithmic hiring decisions are reshaping vendor compliance architectures as the EU AI Act's risk classification framework imposes conformity obligations on automated candidate evaluation tools. Enterprise procurement teams now mandate audit trails for training data provenance and human oversight protocols before platform adoption.
Growth Catalysts
- EU AI Act Conformity Requirements:Vendors investing in transparency documentation and bias auditing capabilities gain preferred vendor status among Fortune 500 compliance officers. Documentation infrastructure becomes a competitive differentiator in enterprise RFPs.
- Skills-Based Matching Algorithms:Healthcare and technology sectors deploy internal mobility platforms to address talent scarcity. AI-driven skills inference reduces reliance on credential-based screening.
- Cloud Migration in Staffing Operations:North American staffing firms replace on-premise applicant tracking systems with SaaS deployments. Lower capital requirements accelerate procurement cycles for mid-market buyers.
Market Restraints
- Algorithmic Bias Liability Exposure:EEOC enforcement under Title VII creates litigation risk for employers deploying unvalidated screening models. Legal departments delay full automation of candidate evaluation workflows.
- Integration Complexity with Legacy HRIS:Decades-old payroll and benefits systems lack API compatibility with modern recruiting platforms. Custom middleware development inflates implementation timelines.
- Data Residency Requirements:Germany's Federal Data Protection Authority and France's CNIL impose strict cross-border transfer limitations. Multi-national employers face fragmented deployment architectures.
Strategic Opportunities
- Contingent Workforce Management:Gig economy platforms require automated credential verification and compliance tracking. Vendor management system integration represents an adjacent expansion vector.
- Natural Language Processing Convergence:Large language models combined with structured assessment data enable conversational candidate screening. Early adopters in high-volume retail hiring compress time-to-offer metrics.
- Illinois Video Interview Act Precedent:State-level transparency mandates create compliance software demand. Jurisdictions including Maryland and New York City adopt similar disclosure requirements.
Industry Challenges
- Explainable AI Engineering Talent:Vendors struggle to recruit machine learning engineers with both technical depth and domain expertise in employment law. Compensation inflation in the Bay Area and Seattle concentrates scarce talent.
- Multi-Jurisdictional Compliance Synchronization:Product teams must architect simultaneous conformity with EU AI Act, EEOC guidance, and emerging state frameworks. Roadmap prioritization conflicts between legal and engineering stakeholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recruiting Automation Software Market |
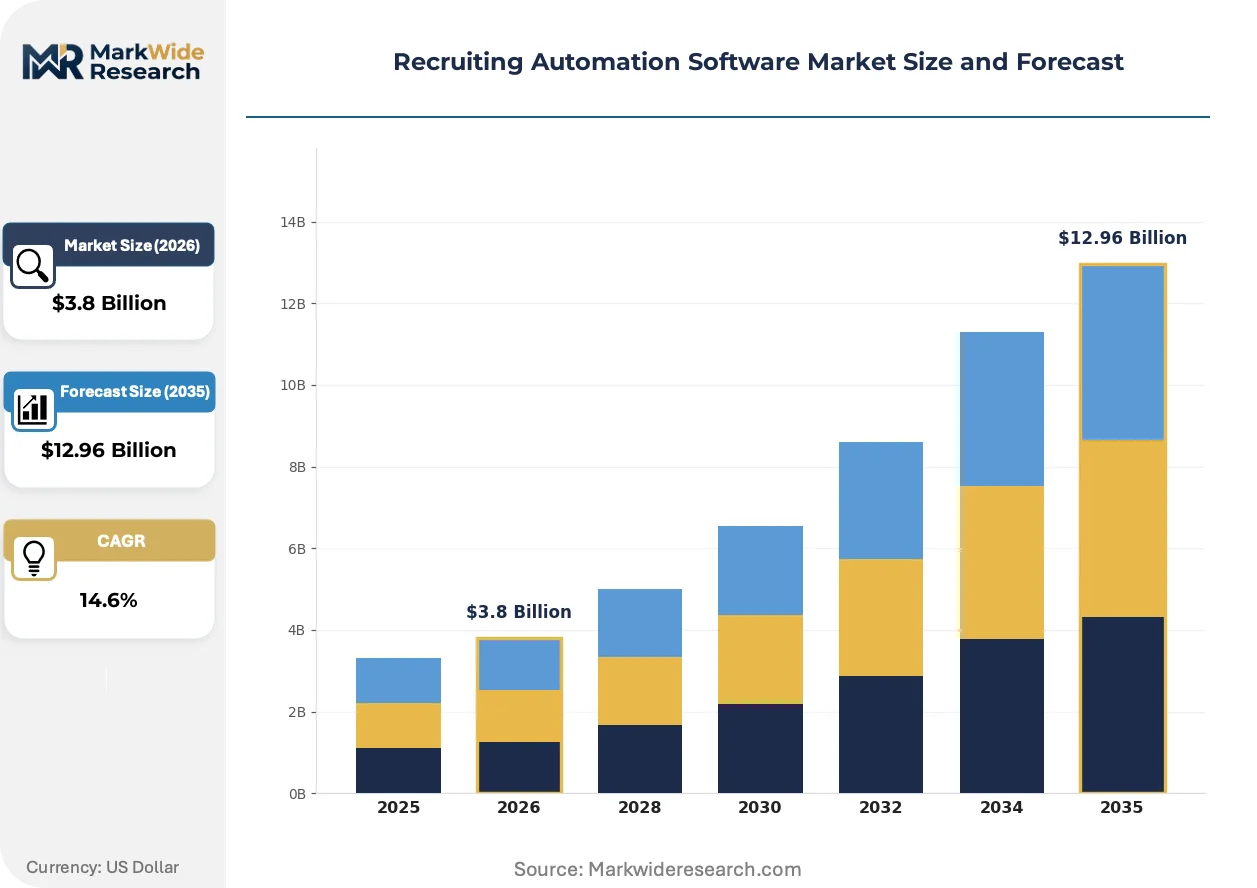
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Enterprises, Staffing Agencies, Educational Institutions Functionality: Applicant Tracking System, Interview Scheduling, Candidate Sourcing, Analytics Integration Level: APIs, ATS Compatibility, CRM Integration, Job Boards |
| Companies Covered | iCIMS, Ashby, Greenhouse, SeekOut, Eightfold, Lever, BambooHR, Phenom, Workday, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recruiting Automation Software Market Evolving Landscape
Generative AI capabilities are compressing content creation cycles for job descriptions and candidate communications. Vendors race to embed these tools without triggering regulatory scrutiny of automated decision-making.
Conversational AI agents are integrating into scheduling and initial screening workflows. Mid-market employers in logistics and customer service adopt these tools to manage high application volumes. The technology is integrating voice synthesis and sentiment analysis to simulate human recruiter interactions, reducing no-show rates for interview appointments.
The EU AI Act's high-risk system classification for employment decisions mandates conformity assessments and CE marking. Vendors must establish quality management systems and maintain logs of automated outputs. European enterprise buyers now require documentation of human-in-the-loop protocols before contract execution, shifting procurement evaluation criteria toward compliance infrastructure.
Subscription pricing models are displacing perpetual licenses in mid-market segments. Buyers prefer predictable operational expenditure over capital-intensive upfront deployment. This shift is most pronounced among Series B and C technology companies scaling hiring operations rapidly without dedicated IT procurement functions.
Recruiting Automation Software Market Segmentation
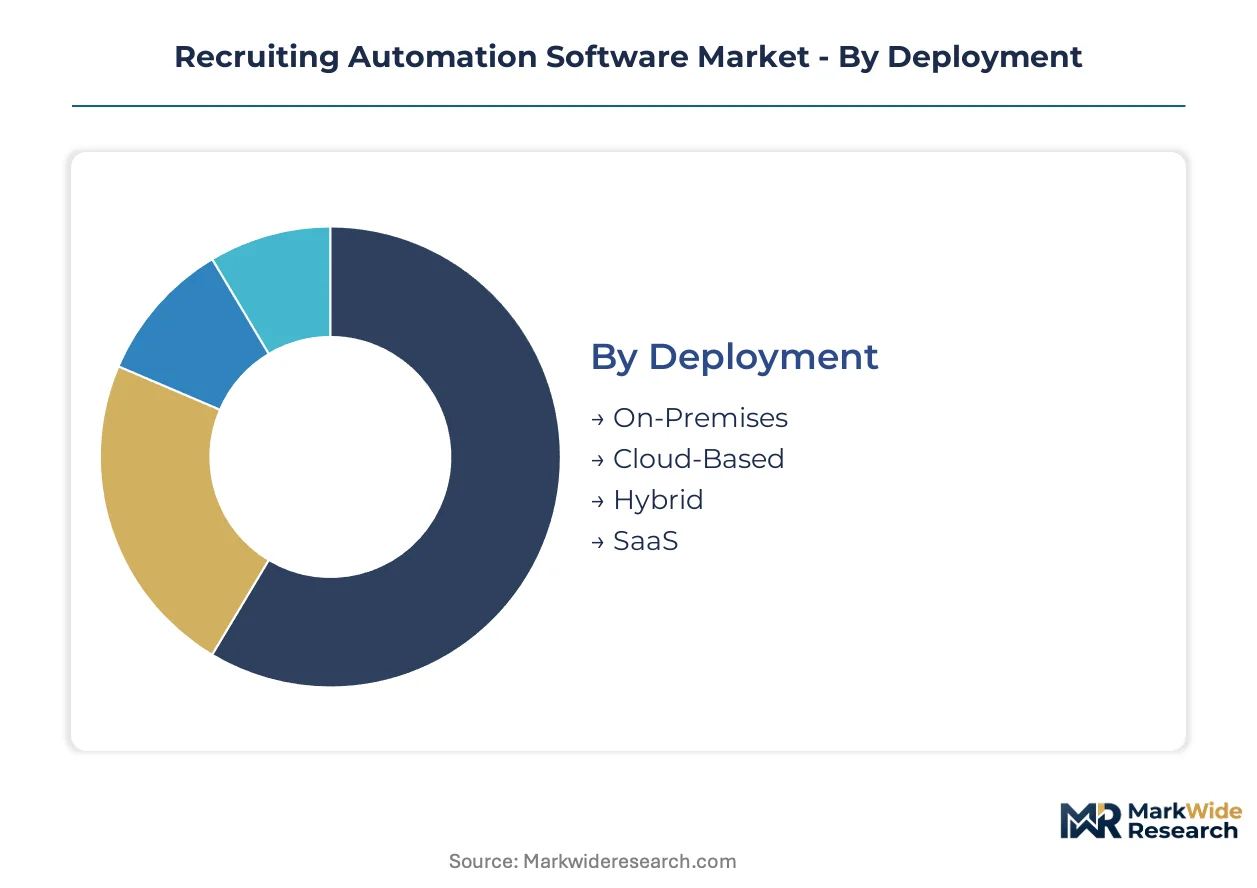
Recruiting automation software vendors architect product portfolios around deployment economics, buyer scale, and integration complexity. Segmentation reveals where capital requirements concentrate and which buyer segments drive margin expansion.
Deployment:
Capital intensity varies sharply across deployment models, with on-premises installations demanding the heaviest upfront infrastructure investment.
- On-Premises:Organizations maintain servers and data centers behind corporate firewalls. German automotive manufacturers and French defense contractors favor this model for data sovereignty compliance under CNIL and BfDI oversight.
- Cloud-Based:Multi-tenant architectures eliminate hardware procurement cycles. Healthcare systems in Texas and technology startups in California compress implementation timelines through browser-based access.
- Hybrid:Sensitive candidate data resides on-site while analytics processing shifts to public cloud. Japanese conglomerates with legacy mainframe investments deploy this architecture to preserve sunk costs.
- SaaS:Subscription pricing aligns vendor incentives with customer retention. Series B software companies in Massachusetts and Illinois staffing firms scale seat counts without procurement committee approval.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in SaaS.
End User:
Buyer sophistication determines feature requirements and sales cycle length, with enterprises demanding the most extensive customization.
- Small Businesses:Self-service onboarding and templated workflows dominate purchasing criteria. Restaurant chains in Florida and retail franchises in Ohio prioritize mobile-first interfaces over deep configurability.
- Enterprises:Global hiring workflows require multi-language support and role-based permissions. Fortune 500 manufacturers in Michigan and pharmaceutical headquarters in New Jersey mandate SOC 2 Type II certification.
- Staffing Agencies:High-volume requisition processing demands batch operations and client-specific branding. Industrial staffing firms in Georgia and IT placement specialists in Washington state optimize for candidate redeployment.
- Educational Institutions:Seasonal hiring peaks around academic calendars drive scheduling automation priorities. Public university systems in California and private colleges in Massachusetts seek federal work-study integration.
Enterprise accounts generate the deepest revenue per seat. Small Businesses are expanding most quickly.
Functionality:
Module bundling strategies reflect which capabilities buyers treat as table stakes versus premium upgrades.
- Applicant Tracking System:Centralized candidate databases with workflow automation form the core infrastructure replacement play. Legacy system migrations in Pennsylvania banking and Ohio insurance drive replacement demand.
- Interview Scheduling:Calendar synchronization and automated reminders reduce administrative overhead. Logistics employers in Tennessee and call center operators in Arizona deploy this to manage high-volume hourly hiring.
- Candidate Sourcing:Boolean search and passive talent identification tools expand pipeline reach. Technology recruiters in Seattle and biotech talent acquisition in Boston leverage this for specialized skill scarcity.
- Analytics:Predictive models and diversity dashboards command premium pricing. Chief Human Resource Officers in Virginia and Texas demand source-of-hire attribution and quality-of-hire forecasting.
Applicant Tracking System modules capture the largest installed base. Analytics represents the fastest-growing trajectory.
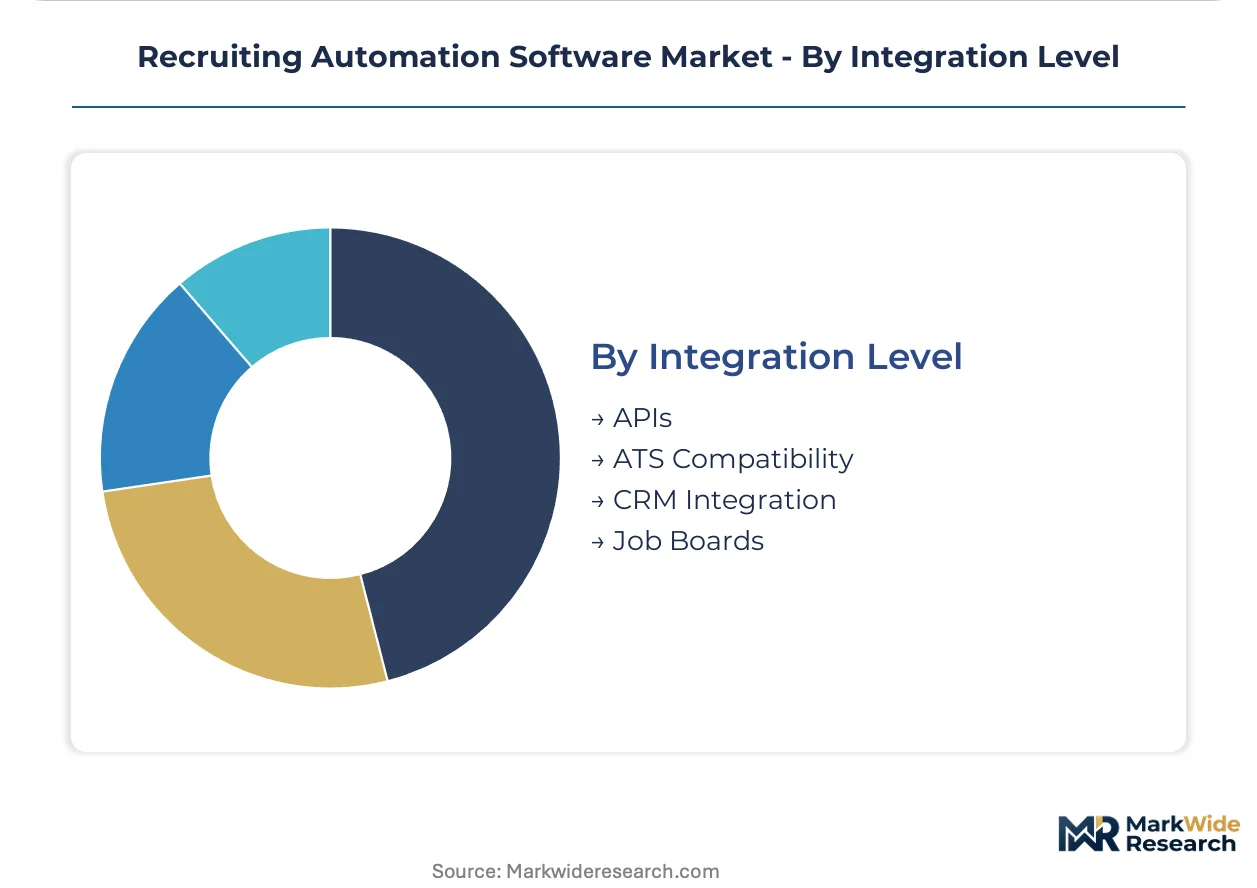
Integration Level:
Technical architecture choices determine which ecosystem partnerships unlock enterprise procurement.
- APIs:RESTful and GraphQL endpoints enable custom development. FinTech employers in New York and e-commerce platforms in Washington build proprietary screening tools atop vendor infrastructure.
- ATS Compatibility:Pre-built connectors to legacy systems reduce migration friction. Healthcare networks in North Carolina and government contractors in Virginia require seamless data portability.
- CRM Integration:Synchronization with sales and marketing databases supports talent community nurturing. Professional services firms in Illinois and consulting partnerships in Washington DC align recruiting with business development pipelines.
- Job Boards:Native posting to Indeed, LinkedIn, and niche boards accelerates requisition distribution. Hospitality chains in Nevada and retail operators in Texas prioritize multi-site publishing efficiency.
API connectivity anchors the most complex enterprise deals. ATS Compatibility is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement intensity in the United States outpaces German adoption rates by a factor of three, while India's SaaS penetration accelerates faster than any major economy. Regulatory divergence between EU conformity frameworks and US state-level mandates fragments vendor deployment strategies.
United States
Fortune 500 employers in Michigan and New Jersey drive enterprise-scale ATS replacements, with pharmaceutical headquarters and automotive manufacturers demanding SOC 2 Type II certification. The EEOC enforces Title VII scrutiny of algorithmic hiring decisions, compelling legal departments to mandate human-in-the-loop documentation. Texas healthcare systems and California technology startups compress implementation timelines through browser-based cloud access.
Germany
Automotive manufacturers and defense contractors favor on-premises deployments for data sovereignty compliance. The Federal Data Protection Authority (BfDI) imposes strict cross-border transfer limitations, forcing multi-national employers toward fragmented deployment architectures. Industrial clusters in Bavaria and North Rhine-Westphalia anchor compliance-heavy procurement patterns.
United Kingdom
London-based financial services firms and professional services partnerships demand API connectivity for proprietary screening tool development. Post-Brexit regulatory divergence complicates EU AI Act alignment for UK-headquartered multi-nationals. The Midlands and Scotland host expanding technology sector hiring operations.
India
Series B and C software companies in Karnataka and Maharashtra scale seat counts without procurement committee approval through SaaS subscription models. The country's technology services exporters adopt AI-powered candidate screening to maintain cost competitiveness. Bengaluru and Hyderabad clusters concentrate vendor implementation partnerships.
France
CNIL oversight shapes data residency requirements for automated employment decision systems, with Île-de-France headquarters operations leading compliance investment. Luxury goods manufacturers and aerospace suppliers in Auvergne-Rhône-Alpes deploy skills-based matching for specialized technical roles. French enterprise buyers now require CE marking documentation before contract execution.
Recruiting Automation Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise-scale implementation capabilities concentrate among vendors with decade-long Fortune 500 relationships, while mid-market SaaS providers capture rapid seat expansion through self-service onboarding. Three strategic archetypes dominate: full-suite platform vendors, point-solution AI specialists, and legacy ATS modernizers. M&A activity targets API-first architectures and contingent workforce management capabilities.
Within the AI-native specialist tier, Eightfold and SeekOut exemplify skills-inference positioning, while Greenhouse occupies a position among API-centric platform vendors. iCIMS anchors the enterprise-scale archetype with complex global hiring workflow capabilities. These named entities represent divergent bets on whether buyers prioritize deep configurability, open integration, or predictive intelligence.
| Leading Market Players |
|---|
| iCIMS |
| Ashby |
| Greenhouse |
| SeekOut |
| Eightfold |
| Lever |
| BambooHR |
| Phenom |
| Workday |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure cost indices from hyperscalers cascade through SaaS vendor pricing tiers, compressing margins for mid-market recruiting automation providers while enterprise buyers leverage volume scale for preferential rate cards. This cost pressure differential separates vendors with captive data center partnerships from those exposed to spot compute pricing volatility.
Pricing Analysis
Capacity additions in North American hyperscale regions are reshaping price floors for cloud-hosted recruiting platforms, enabling tiered subscription structures that stratify across premium enterprise, standard mid-market, and economy self-service levels. Price differentiation hinges on SOC 2 certification tier and API call volume thresholds, with compliance documentation commanding substantial premiums. Pricing pressure stems from open-source alternative proliferation in the developer-tools segment. Small businesses exhibit acute price sensitivity, while Fortune 500 procurement teams prioritize audit infrastructure over per-seat cost.
Supply Chain Analysis
Large language model inference capacity rests on GPU cluster availability concentrated in the United States, Taiwan, and South Korea, with training data pipelines drawing from proprietary talent databases and public workforce statistics. Critical dependencies include transformer model weights, vector database infrastructure, and synthetic data generation tools. Single-source vulnerability concentrates in NVIDIA hardware supply for training workloads. Distribution runs through direct enterprise sales teams and self-service digital channels for seat expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recruiting automation market functions as a geographic-arbitrage play where EU AI Act compliance costs in European jurisdictions create pricing premiums that subsidize expansion into lighter-regulated Asian SaaS markets.
For Market Incumbents: Deepen explainable AI engineering capabilities to preempt EEOC enforcement actions under Title VII scrutiny. Fortify data residency infrastructure for German BfDI and French CNIL requirements. Consolidate API-first acquisition targets to defend against modular point-solution disaggregation. For New Entrants and Emerging Players: Conversational AI screening agents offer a technology-first wedge into high-volume retail and logistics hiring segments underserved by legacy ATS incumbents. Target Illinois and New York City markets where video interview transparency mandates create compliance-software demand gaps. Pursue channel partnerships with staffing agency networks for rapid seat accumulation. For Investors and Strategic Acquirers: Consolidation pressure builds where API-first architectures enable platform embedding across adjacent HR technology stacks. Long-term viability favors vendors with simultaneous EU AI Act conformity and US state-level disclosure compliance. Watch for EEOC algorithmic enforcement actions as inflection indicators for liability-driven vendor attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Platform Development | EU AI Act conformity assessments now mandate human-in-the-loop documentation for high-risk employment systems. |
| API-First Architecture Acquisition | Greenhouse-style open integration enables embedding within existing Workday and SAP HRIS ecosystems. |
| Contingent Workforce Module Launch | Gig economy credential verification expands addressable market into vendor management system adjacencies. |
| Multi-Jurisdictional Compliance Certification | CE marking and state-level disclosure readiness unlocks Fortune 500 procurement committee approval. |
| Skills Inference Engine Investment | Eightfold-style internal mobility platforms capture healthcare and technology sector talent scarcity spending. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with talent acquisition executives, HR technology procurement officers, compliance legal counsel, and platform engineering leads alongside secondary validation through SEC filings, EU regulatory databases, and hyperscaler infrastructure disclosures. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against enterprise HR software spend estimates anchored market sizing.
Rate-of-change decomposition across the analysis window modeled deployment model transitions, functionality module attachment rates, and regional regulatory adoption patterns. Segmentation dimensions included organization size tier, vertical industry concentration, integration complexity level, and compliance framework exposure. CAGRs derived from regression against historical SaaS penetration curves and staffing industry technology spend elasticity, with forecast inputs incorporating EU AI Act implementation timelines and US state-level disclosure mandate propagation.
The model holds under stable regulatory enforcement intensity; deviation in EEOC litigation volume or EU conformity assessment backlogs would shift vendor competitive positioning materially. Forecasts reflect assumptions regarding cloud infrastructure cost trajectories and enterprise hiring cycle recovery patterns. A small set of named triggers warrants ongoing watch: algorithmic bias liability precedent, data residency restriction expansion, and generative AI capability commoditization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
RFID Kanban Systems Market
Automation
Global Form Automation Software Market
Automation
North America Marketing Automation Software Market
Automation
Home Automation and Controls Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Indonesia Automation and Control System Market
Automation
Playout Automation Market
Automation
Global Database Automation Systems Market
Automation
Global Process Automation and Instrumentation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Helpdesk Automation Market
Automation
Automation Testing Market
Automation
Global Business Process Automation Software Market
Automation
Global Warehouse Barcode System Market
Automation
AR Automation Market
Automation
Workflow Automation Market