
 IoT Home Automation Market | 2026-2036
IoT Home Automation Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Home Automation Market Intelligence
The European Union's Cyber Resilience Act is expanding the compliance burden for device manufacturers, altering market entry costs. Alphabet Inc. (Google) leverages its Android and Google Assistant ecosystem to anchor its position in smart home control. Samsung Electronics Co., Ltd. differentiates through its SmartThings platform, integrating its vast portfolio of consumer electronics. Honeywell International Inc. sustains its strength in specialized HVAC and security systems for automated homes.
IoT home automation involves a network of internet-connected devices that monitor and manage residential systems and appliances remotely. These systems utilize wireless protocols like Wi-Fi, Zigbee, and the emerging Thread standard to enable communication between sensors, actuators, and a central hub. Security & Surveillance applications and Energy Management represent mature, high-value segments for residential owners. Within product types, smart thermostats and voice assistants show high penetration, while smart lighting offers significant volume growth opportunities.
Device compliance is shaped by radio frequency regulations from the US FCC and product safety standards like the EU's CE marking. Data privacy is also a critical regulatory frontier, governed by frameworks such as GDPR in Europe and subject to increasing scrutiny by the FTC in the United States. Navigating the patchwork of regional cybersecurity and data handling mandates remains the central strategic challenge for hardware and software providers.
Market Dynamics
The emergence of the Matter protocol as a unifying standard for device communication is the central force shaping the IoT home automation market. This standard addresses the historical fragmentation that created technical barriers and limited consumer adoption across different brands and ecosystems.
Growth Catalysts
- Energy Efficiency Mandates:Government incentives and programs, such as the Energy Star rating in the United States, encourage the adoption of smart thermostats and lighting controls, providing a direct financial benefit to residential owners through reduced utility costs.
- Wireless Protocol Advancement:The maturation of low-power, mesh-networking standards like Thread provides a more reliable and responsive foundation for connecting a high density of devices within a home, improving the user experience over previous-generation protocols.
- Accelerated Urbanization:Demand concentrates in high-income urban centers in countries like Germany and the United States, where tech-savvy consumers in dense housing environments seek convenience, security, and efficient management of smaller living spaces.
Market Restraints
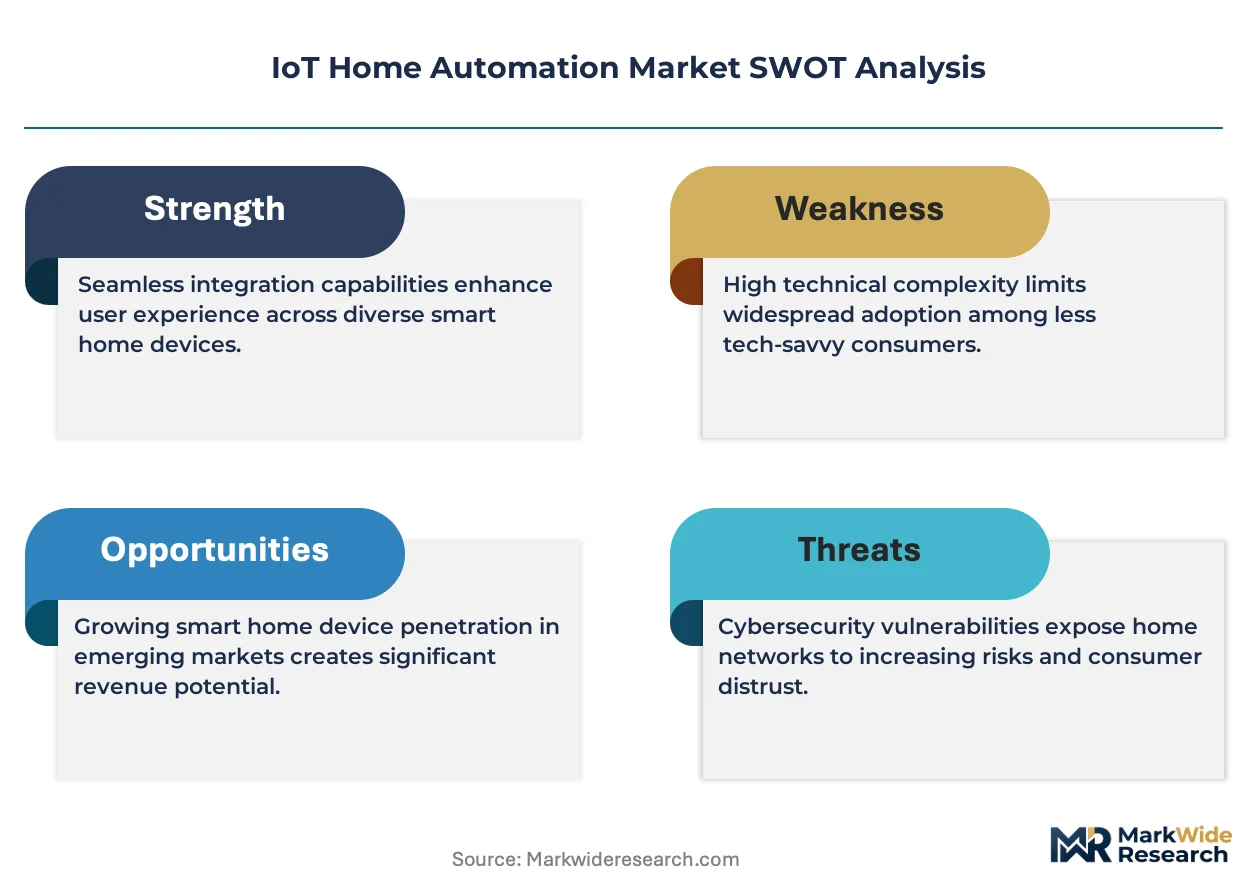
- High Upfront Investment:The initial purchase and installation cost for comprehensive, multi-device smart home systems remains a significant barrier for mainstream adoption, especially outside of the high-income residential segment or new construction projects.
- Data Privacy and Trust Deficits:Consumer apprehension regarding data collection, usage, and security persists, creating a restraint on adoption. Navigating complex privacy frameworks like GDPR in Europe and scrutiny from the US FTC requires significant compliance investment from vendors.
- Fragmented User Experience:Despite standardization efforts, the large installed base of legacy devices that do not support new protocols creates persistent interoperability gaps, leading to a complex and often frustrating experience for users attempting to build a unified system.
Strategic Opportunities
- Aging-in-Place Solutions:The integration of home automation with ambient assisted living applications presents a major opportunity. Systems for remote health monitoring, automated safety alerts, and voice-controlled assistance can serve the growing elderly population in developed nations.
- AI-Powered Proactive Automation:Leveraging artificial intelligence and machine learning to move from reactive commands to predictive, autonomous home management is a key growth frontier. This includes systems that learn user routines to optimize energy use or preemptively identify maintenance needs.
- Expansion into Emerging Markets:While demand is currently concentrated, a significant opportunity exists in the rising middle-class segments of urban centers in Latin America and Southeast Asia. Tailored, lower-cost solutions focused on security and energy savings can unlock new volume.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is ensuring new IoT devices can communicate effectively with existing, non-smart residential infrastructure, such as older HVAC systems, electrical wiring, and security hardware, which often requires costly custom integration.
- Managing Cybersecurity Vulnerabilities:The proliferation of connected devices exponentially increases the potential attack surface for cyber threats within a home network. Vendors face the challenge of providing continuous security updates and patches across a diverse portfolio of products.
- Navigating Regulatory Compliance:Hardware providers must manage a complex patchwork of certifications, including radio frequency rules from the US FCC and product safety requirements for CE marking in the EU, which adds cost and time to market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Home Automation Market |
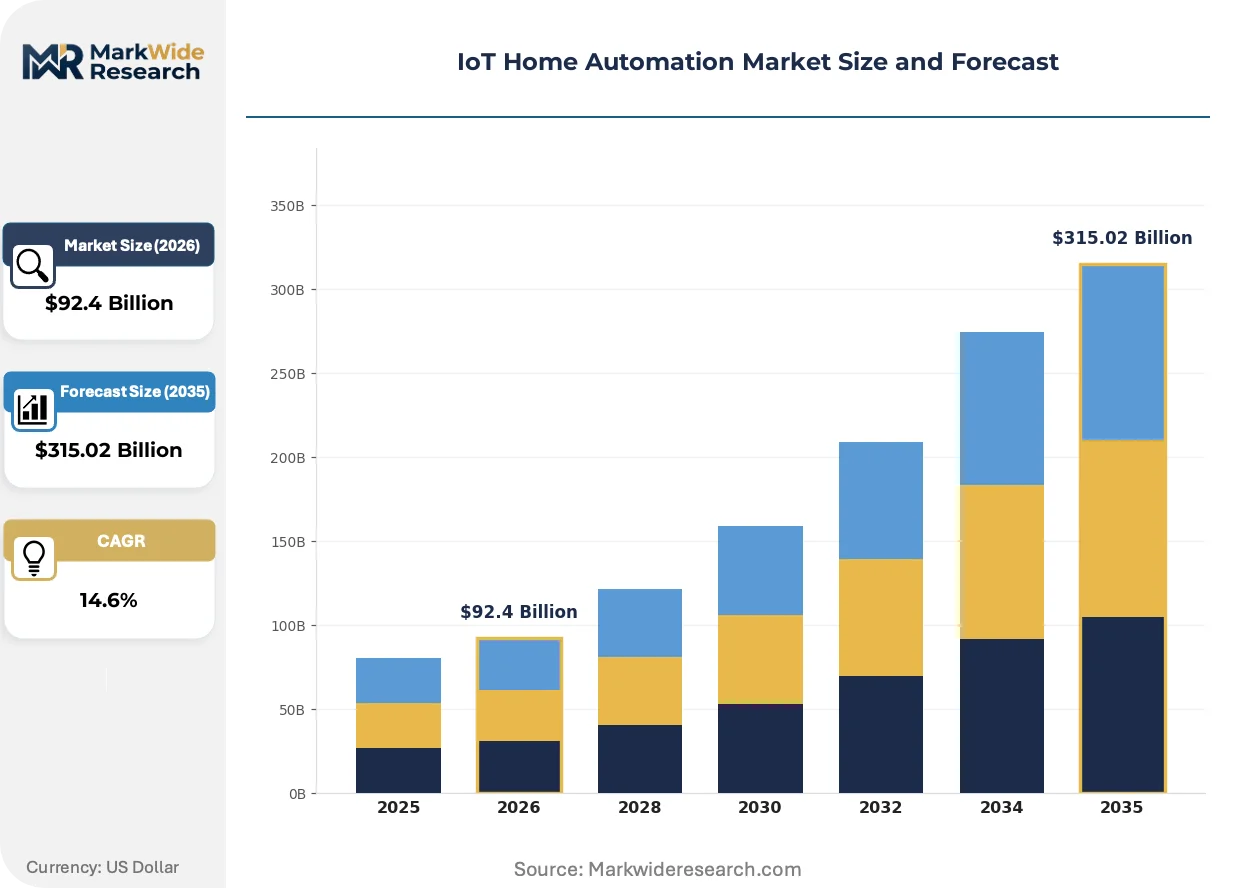
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $315.02 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Security Cameras, Voice Assistants, Smart Lighting, Automated Locks, Energy Monitors Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Low Energy, Thread, LoRaWAN Application: Energy Management, Security & Surveillance, Entertainment Control, Lighting Automation, HVAC Control, Home Health Monitoring End User: Residential Owners, Property Managers, Homebuilders, Smart Device Integrators |
| Companies Covered | Amazon.com, Inc., Alphabet Inc. (Google), Apple Inc., Samsung Electronics Co., Ltd., Honeywell International Inc., Schneider Electric SE, Siemens AG, Johnson Controls International plc, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Home Automation Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from standalone gadgetry toward integrated, intelligent ecosystems. This transition prioritizes seamless interoperability and the delivery of ambient, predictive services that operate in the background of a consumer's daily life.
Edge computing is becoming a core architectural element in new smart home devices. This technology enables on-device data processing, which reduces latency for critical applications like security alerts and improves privacy by minimizing data transmission to the cloud. Residential owners are adopting smart cameras and voice assistants with on-board AI, and this trend is consolidating device intelligence away from centralized cloud platforms.
New regulations are reshaping the responsibilities of device manufacturers. The European Union’s Cyber Resilience Act, for example, establishes baseline cybersecurity requirements for all products with digital elements sold in the region. This forces manufacturers to integrate security-by-design principles from the initial stages of product development. The smart appliance and connected toy segments are particularly affected by these heightened compliance standards.
Consumer purchasing behavior is evolving from one-time hardware sales toward recurring revenue models. A preference for subscription-based services that offer enhanced features, cloud storage, or professional monitoring is disrupting traditional retail channels. This shift is most prominent in the home security and surveillance segment within the United States, where vendors are bundling hardware with long-term service contracts.
IoT Home Automation Market Segmentation
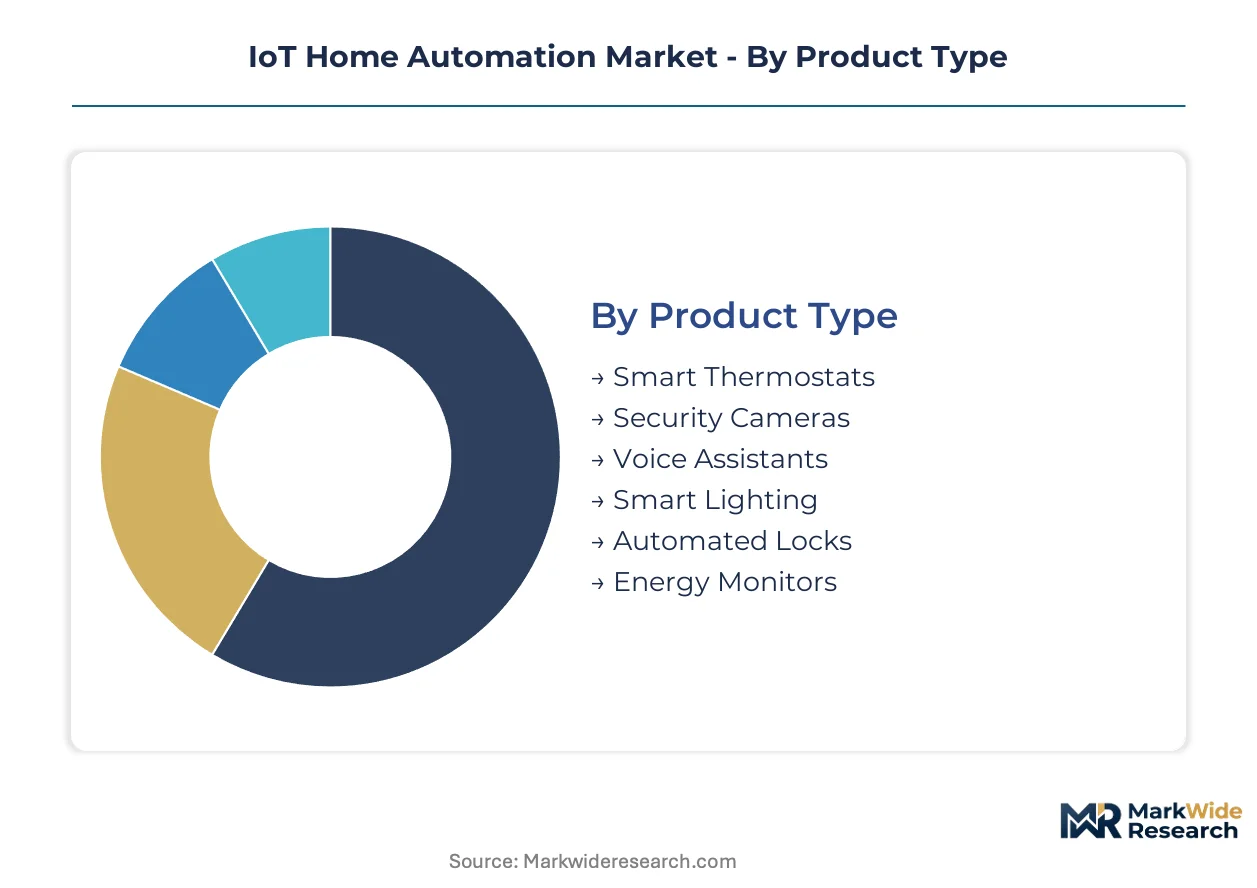
The IoT home automation market categorizes solutions based on their core functionality, underlying communication methods, target users, and specific product offerings. Understanding these distinct segments illuminates varying investment requirements, adoption drivers, and strategic opportunities for hardware and software providers. This segmentation also highlights areas of high consumer interest and technical complexity.
Product Type:
The capital intensity across product types varies significantly, with advanced security systems and comprehensive lighting installations demanding substantial upfront financial outlays.
- Smart Thermostats:These devices regulate home heating and cooling systems, often integrating with external weather data and user preferences to optimize energy consumption. Demand concentrates in regions like the United States and Germany, driven by energy efficiency mandates and utility cost savings for residential owners.
- Security Cameras:Network-connected cameras provide visual monitoring of indoor and outdoor spaces, offering features like motion detection, night vision, and cloud storage for recorded footage. Residential owners in urban centers prioritize these for enhanced property protection and remote surveillance capabilities.
- Voice Assistants:These AI-powered devices, such as those leveraging Google Assistant, enable hands-free control of smart home devices and access to information through spoken commands.
- Smart Lighting:Connected light bulbs and fixtures offer remote control, scheduling, and color customization, appealing to consumers seeking convenience and ambiance control.
- Automated Locks:Electronically controlled door locks provide keyless entry, remote access management, and integration with broader home security systems for residential safety.
- Energy Monitors:These devices track electricity consumption at the appliance or whole-home level, empowering residential owners to identify energy waste and manage utility bills.
Smart Thermostats absorb the bulk of installed capacity; Security Cameras are expanding most quickly.
Technology:
Technology segmentation reveals which communication protocols achieve high penetration rates and which are critical for high-volume device deployments.
- Wi-Fi:This widely adopted wireless networking protocol leverages existing home internet infrastructure, enabling high-bandwidth communication for devices like security cameras and smart TVs. Its ubiquity drives high penetration across diverse smart home product types.
- Thread:This low-power, mesh networking protocol provides a reliable and scalable foundation for connecting numerous smart home devices, offering improved responsiveness and local control. The Matter protocol's reliance on Thread is accelerating its adoption for future interoperable devices.
- Zigbee:A low-power, mesh network standard, Zigbee is common in smart lighting and sensor applications, providing robust device communication.
- Z-Wave:Another mesh networking technology, Z-Wave specializes in home automation, offering reliable communication for security and control devices.
- Bluetooth Low Energy:BLE enables short-range, low-power connections, frequently used for direct device-to-smartphone control and initial setup of smart devices.
- LoRaWAN:This long-range, low-power wide-area network protocol suits specific applications like remote sensor monitoring in larger properties or rural settings.
Wi-Fi technology holds a dominant position in device connectivity due to its widespread availability; Thread is gaining significant traction as a future-proof standard.
Application:
Application segments differentiate based on the primary value proposition delivered to the end-user, often aligning with specific customer priorities like safety or cost savings.
- Security & Surveillance:This segment encompasses smart cameras, motion sensors, and automated locks, providing residential owners with remote monitoring and enhanced property protection. Demand in urban areas like the United States is particularly strong, driven by safety concerns.
- Energy Management:Solutions in this area, including smart thermostats and energy monitors, optimize utility consumption and reduce costs for residential owners. Government incentives like the Energy Star rating in the US further encourage adoption.
- Entertainment Control:This includes smart TVs, sound systems, and media streamers integrated for unified control, enhancing the user's leisure experience.
- Lighting Automation:Systems that control indoor and outdoor lighting via schedules, sensors, or voice commands, primarily focusing on convenience and ambiance.
- HVAC Control:Specialized systems manage heating, ventilation, and air conditioning, often integrated with smart thermostats for climate optimization.
- Home Health Monitoring:Emerging applications involve sensors and devices that assist with remote health monitoring for elderly residents, offering safety and peace of mind.
Security & Surveillance applications consistently drive initial smart home adoption; Home Health Monitoring offers substantial future value.
End User:
End-user categories define distinct purchasing behaviors and service integration needs, influencing vendor strategies for product features and support models.
- Residential Owners:Individual homeowners who purchase and install smart devices for personal use, primarily seeking convenience, security, and energy efficiency benefits. This segment represents the largest volume of direct consumer sales.
- Smart Device Integrators:Professionals who design, install, and configure comprehensive smart home systems for clients, often involving complex multi-device setups and custom solutions. They influence product selection and drive higher-value installations.
- Property Managers:Entities overseeing multiple rental units or commercial properties, utilizing smart home solutions for remote access, energy monitoring, and maintenance efficiency.
- Homebuilders:Construction companies that integrate smart home technology into new residential developments, offering pre-installed systems as a selling point.
Residential Owners dominate direct hardware purchases; Smart Device Integrators significantly influence system complexity and vendor choice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Governmental incentives, such as the Energy Star program in the United States, are driving market concentration by encouraging smart home technology adoption. These programs, alongside high-income urban centers, create fertile ground for IoT home automation expansion. Residential owners seek convenience and energy efficiency benefits in these concentrated areas.
United States
Residential owners in major metropolitan areas prioritize smart home solutions for security and energy management. The US FCC regulates radio frequency emissions for connected devices, ensuring market entry compliance. Silicon Valley and other tech hubs foster innovation in AI-powered automation and new device integration.
Germany
High consumer demand for energy efficiency and convenience drives smart thermostat and lighting control adoption among German homeowners. Germany's national energy efficiency policies encourage smart home investments through various subsidies. Munich and Berlin serve as innovation centers for smart home software and hardware development.
China
Urban consumers in China increasingly adopt smart home devices for security and convenience, particularly within new residential developments. The MIIT regulates IoT device connectivity and data transmission standards across the country. Major tech cities like Shenzhen and Beijing are central to smart device manufacturing and AI integration.
United Kingdom
UK residential owners seek smart home solutions for energy savings and enhanced property security. The UK government promotes smart meter rollouts and energy efficiency initiatives, indirectly supporting smart home adoption. London's tech ecosystem attracts investment in smart home platforms and service providers.
Japan
Japanese households show interest in smart appliances and home health monitoring solutions, driven by an aging population and technological readiness. METI oversees industrial standards and promotes IoT adoption across various sectors, including home automation. Tokyo and Osaka remain key centers for consumer electronics innovation and smart home integration.
IoT Home Automation Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping a competitive landscape marked by both broad ecosystem plays and niche innovations. The market structure features established electronics manufacturers alongside emerging software and service providers. Companies increasingly pursue strategic partnerships and portfolio diversification to expand their reach and integrate varied smart home functionalities across devices. Technology licensing also plays a crucial role in accelerating new product development and market entry, fostering interoperability.
Among technology giants, Alphabet Inc. (Google), an Inc.-registered entity, and Samsung Electronics Co., Ltd., a global electronics conglomerate, exemplify broad ecosystem strategies. These firms leverage their extensive consumer electronics portfolios and widely adopted operating systems to anchor their positions in smart home control. Honeywell International Inc., also an Inc.-registered company, occupies a specialized position, sustaining its strength in industrial controls and integrated building systems for automated homes. These organizations represent different approaches to capturing value, from comprehensive platform offerings to specialized high-value solutions, in the evolving IoT home automation sector.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Alphabet Inc. (Google) |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Siemens AG |
| Johnson Controls International plc |
| LG Electronics Inc. |
| Others |
Cost & Logistics Intelligence
Specialized electronics assembly expertise in regions like China and Vietnam creates distinct labor-cost differentials, which directly influence the pricing tiers for IoT home automation devices. These cost structures dictate the final product value proposition for residential owners.
Pricing Analysis
Premium pricing often applies to IoT home automation devices with short lead times or highly customized features, while standard components see discounts. The market primarily uses a hybrid pricing model, combining per-unit hardware sales with recurring subscription-based services for enhanced features. Brand premium and comprehensive after-sales support drive price differentiation. Pricing softness stems from intense competition and commoditization of basic devices, making residential owners highly price sensitive for entry-level products; integrators prioritize system reliability.
Supply Chain Analysis
Dual-sourcing requirements are becoming more common for critical IoT components, driven by buyers seeking to mitigate risk. Geographic supply concentration for device manufacturing centers on China, Vietnam, and South Korea, depending on a steady supply of semiconductors, various sensors, and plastic enclosures. Single-source vulnerability for specialized microcontrollers represents a structural supply chain risk. Distribution runs through a mix of large omnichannel retailers and specialized smart device integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT home automation market is navigating a significant technology-transition phase, as the Matter protocol displaces legacy fragmented communication standards. This shift promises enhanced interoperability and a more unified user experience.
For Market Incumbents: Anchor existing user bases by continuously enhancing platform integration capabilities, ensuring seamless compatibility across new Matter-enabled devices and older systems. Strategic acquisitions of niche technology firms specializing in AI-powered automation or cybersecurity can counter emerging specialized AI-powered startups. Invest significantly in R&D for edge computing capabilities to improve device responsiveness and data privacy. Control of key distribution channels, such as major retail partnerships, also helps maintain market share.
For New Entrants and Emerging Players: Underserved elderly populations in developed nations represent a white-space target for aging-in-place solutions, integrating remote health monitoring and automated safety alerts. Another opportunity lies in tailored, lower-cost solutions focused on security and energy savings for rising middle-class segments in Latin America. Home health monitoring applications are highly penetrable. Subscription-based service bundles with ongoing support offer a strong go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented capabilities within the IoT home automation sector. Long-term viability over the next 5-10 years depends on ecosystems offering seamless interoperability and predictive intelligence. Acquisition targets should include software platforms specializing in AI analytics or firms with strong intellectual property in edge computing. Widespread Matter protocol adoption across diverse device categories signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse devices under a single ecosystem for Alphabet Inc. and Samsung Electronics Co. |
| Acquisition of Specialist Firm | Honeywell International Inc. can gain niche AI or cybersecurity capabilities from smaller innovators. |
| Geographic Expansion | Penetrates new urban centers in Latin America, expanding reach for established players. |
| Subscription Service Enhancement | Drives recurring revenue and customer loyalty for Amazon.com, Inc.'s smart home offerings. |
| R&D into Edge Computing | Improves data privacy and real-time responsiveness for smart cameras and voice assistants. |
Research Approach
Document review covered SEC 10-K filings, customs/trade data, industry association reports, and government energy efficiency program data, complemented by interviews. Primary data collection involved discussions with product managers, R&D directors, smart device integrators, and regulatory compliance officers. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation. Secondary validation confirmed insights from primary research.
The quantitative model produced volume and value forecasts across the analysis window, integrating historical data and projected growth drivers. Segmentation dimensions modeled included product type, technology, application, end-user, and regional adoption patterns. Compound Annual Growth Rates were derived from these trends. Smart thermostat penetration rates and Matter protocol adoption curves served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and technological disruptions. Forecasts reflect assumptions regarding market growth. Deviation in cybersecurity threats or major economic shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Computer Numerical Control Market
Automation
Home Automation and Controls Market
Automation
Marketing Automation Solutions Market
Automation
Hyperautomation Market
Automation
Home Automation Market
Automation
Global Door and Window Automation Market
Automation
CNC Controller Market
Automation
Helpdesk Automation Market
Automation
Global Water Automation and Instrumentation Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Automation Lifecycle Services Market
Automation
Playout Automation Market
Automation
Automatic Message Handling System Market
Automation
Home Automation System Market
Automation
Dropshipping Automation Software Market
Automation
Global Form Automation Software Market