
 Global Direct Mail Automation Software Market | 2026-2036
Global Direct Mail Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Direct Mail Automation Software Market Foresight
North American cloud infrastructure expansion is rewriting competitive dynamics for direct mail automation vendors. Lob leverages API-first architecture to sustain developer-centric market positioning. Sendoso anchors its presence through physical gifting logistics tied to automated direct mail workflows. PFL competes by integrating tactile marketing into enterprise CRM ecosystems.
Direct mail automation software orchestrates the design, production, and delivery of personalized physical mail through digital workflows, typically integrating variable data printing specifications with postal logistics APIs to bridge offline and online customer engagement channels. Campaign management solutions within the solution type segment dominate current revenue pools, while workflow automation capabilities exhibit the fastest structural growth as enterprises seek to reduce manual touchpoints across distributed marketing teams. Cloud-based deployment leads adoption among mid-market buyers, though hybrid configurations are gaining traction in regulated industries requiring local data residency.
The Federal Trade Commission enforces truth-in-advertising standards that shape direct mail content compliance, while the European GDPR framework mandates explicit consent mechanisms for personalized physical outreach. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor data security posture. Stakeholders must monitor evolving postal rate structures and carbon accounting requirements as sustainability criteria increasingly influence channel selection between physical and digital outreach.
Market Dynamics
Enterprise marketing stacks are forcing direct mail automation vendors to recalibrate platform architectures around real-time data synchronization with customer data platforms, compressing deployment timelines from quarters to weeks.
Growth Catalysts
- GDPR-compliant consent orchestration:European enterprises require automated audit trails for physical outreach permissions, expanding feature budgets for consent-management modules.
- Financial services cross-channel attribution:Banks and insurers deploy direct mail as measurable touchpoints within unified customer journey analytics, bridging offline response data with digital engagement metrics.
- Variable data printing API standardization:Postal logistics providers expose real-time address verification and delivery confirmation endpoints, reducing undeliverable rates and campaign rework cycles.
Market Restraints
- Paper and ink input volatility:Pulp commodity price swings and specialty substrate shortages compress gross margins for campaign production workflows during peak seasonal demand.
- Postal infrastructure concentration:National mail carriers in Germany, Japan, and the United States control last-mile delivery pricing and service level agreements, limiting vendor negotiation leverage.
- Carbon accounting disclosure mandates:EU CSRD requirements impose Scope 3 emissions reporting on physical marketing channels, adding compliance overhead that slows procurement cycles.
Strategic Opportunities
- India's PLI scheme for digital infrastructure:Production-linked incentives for cloud data centers enable localized deployment of direct mail automation platforms serving Asia-Pacific financial services hubs.
- Healthcare patient engagement workflows:Automated appointment reminders and medication adherence mailers integrate with EHR systems, opening vertical-specific platform configurations.
- AI-driven creative personalization:Generative design tools converging with postal APIs enable dynamic content generation at segment-of-one scale without manual creative production.
Industry Challenges
- MarTech integration specialist scarcity:Enterprises lack internal talent capable of mapping direct mail automation APIs into existing Salesforce, HubSpot, or Adobe Experience Cloud instances.
- ISO 27001 certification timelines:Vendor security audits extend enterprise sales cycles by four to six months as procurement teams validate data residency and encryption protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Direct Mail Automation Software Market |
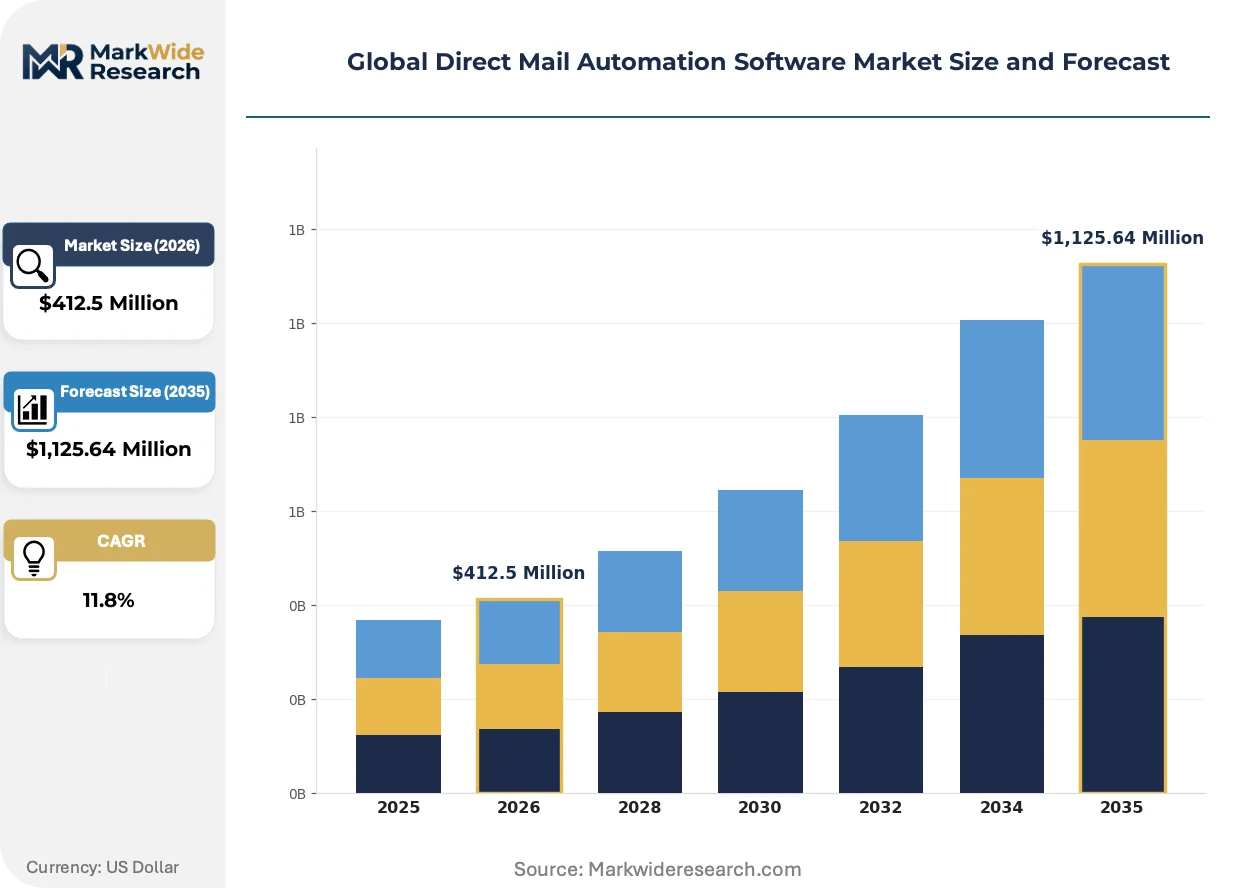
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Campaign Management, Data Analytics, Customer Segmentation, Workflow Automation, Reporting & Dashboard Use Case: Lead Generation, Customer Retention, Cross-Selling, Personalized Promotions, Brand Awareness End User Industry: Financial Services, Telecommunications, Real Estate, Nonprofits, Higher Education |
| Companies Covered | Sendoso, Lob, Postalytics, Reachdesk, Alyce, PostGrid, Inkit, PFL, Postal.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Direct Mail Automation Software Market Shifts & Advancements
Direct mail automation is absorbing capabilities from adjacent marketing technologies, collapsing the boundary between physical and digital campaign orchestration. Platform differentiation now hinges on latency, data fidelity, and cross-channel identity resolution rather than print quality alone.
API-first architecture is hybridizing direct mail workflows with programmatic advertising and email automation stacks. Mid-market SaaS buyers demand sub-second latency between trigger events and mail file generation. This convergence compresses the traditional separation between online retargeting and offline fulfillment, enabling abandoned-cart recovery via physical mail within 24-hour windows.
GDPR Article 7 consent requirements and the EU AI Act's risk classification framework are reshaping vendor feature roadmaps. Automated platforms must now embed explicit consent capture, granular preference centers, and algorithmic decision transparency for personalized content selection. Financial services and healthcare verticals in France, Germany, and the Netherlands face the steepest compliance burdens, driving procurement toward vendors with pre-certified EU data residency architectures.
Enterprise buying committees are consolidating direct mail spend under centralized marketing operations functions, displacing distributed department-level purchasing. Procurement teams now mandate unified billing, consolidated reporting dashboards, and volume-based pricing tiers across business units. This concentration is most visible in United States-based Fortune 500 enterprises, where CMOs are collapsing point solutions into integrated customer experience platforms.
Global Direct Mail Automation Software Market Segmentation
Segmentation in direct mail automation software reflects divergent technical architectures and operational maturity levels across buyer organizations. Deployment preferences vary sharply between regulated industries requiring data sovereignty and growth-stage enterprises prioritizing speed-to-market. Solution type selection correlates directly with marketing team sophistication and existing MarTech integration depth.
Deployment:
Cloud infrastructure expansion across financial services and telecommunications verticals is redrawing the cost-performance frontier for platform delivery models.
- Cloud-Based:Multi-tenant architectures enable rapid provisioning without capital expenditure, with demand concentrating among mid-market SaaS buyers in the United States seeking sub-second latency between trigger events and mail file generation. GDPR Article 44 cross-border data transfer requirements constrain European adoption unless vendors maintain EU-based processing nodes.
- On-Premise:Single-tenant installations within client data centers satisfy HIPAA encryption mandates and FTC data security expectations for healthcare and financial services institutions. German and Japanese buyers favor this model to satisfy national data residency statutes and ISO 27001 audit requirements.
- Hybrid:Split architectures route sensitive customer data through local infrastructure while leveraging cloud analytics for campaign optimization. Real estate investment trusts and higher education advancement offices adopt this configuration to balance compliance with operational flexibility.
- SaaS:Subscription pricing with usage-based tiers dominates nonprofit and small-business procurement, though postal API surcharges and variable data printing volume fees complicate total cost forecasting.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
Solution Type:
Feature bundling strategies reflect enterprise procurement consolidation under centralized marketing operations functions.
- Campaign Management:End-to-end orchestration of design, production, and delivery workflows commands the largest current revenue pools. United States Fortune 500 CMOs mandate unified billing and consolidated reporting dashboards across business units, displacing point solutions.
- Workflow Automation:Distributed marketing teams require automated approval chains and template governance to reduce manual touchpoints. This capability exhibits the steepest expansion trajectory as enterprises compress deployment timelines from quarters to weeks.
- Data Analytics:Cross-channel attribution modules bridge offline response data with digital engagement metrics, particularly within banking and insurance customer journey analytics.
- Customer Segmentation:Real-time synchronization with customer data platforms enables segment-of-one personalization at postal scale.
- Reporting & Dashboard:Procurement teams require ISO 27001-certified audit trails for GDPR-compliant consent orchestration and physical outreach permissions.
Revenue concentration sits with Campaign Management; capability investment flows toward Workflow Automation.
Use Case:
Application patterns map directly to customer lifecycle stage and measurable response channel economics.
- Lead Generation:Automated prospecting mailers integrate with Salesforce and HubSpot instances to capture inbound response data. MarTech integration specialist scarcity extends implementation timelines for complex API mappings.
- Customer Retention:Renewal reminders and loyalty program communications generate predictable volume for postal logistics providers. Financial services firms deploy these as measurable touchpoints within unified attribution frameworks.
- Cross-Selling:Product affinity models trigger personalized offers based on transaction history and digital behavior signals.
- Personalized Promotions:Abandoned-cart recovery via physical mail within 24-hour windows collapses the traditional separation between online retargeting and offline fulfillment.
- Brand Awareness:Nonprofit donors and higher education alumni respond to tactile premium formats that bypass email saturation.
Volume scale favors Customer Retention; innovation intensity concentrates on Personalized Promotions.
End User Industry:
Vertical-specific compliance burdens and procurement authority structures shape platform configuration requirements.
- Financial Services:Banks and insurers face the steepest GDPR and EU AI Act algorithmic decision transparency requirements. French, German, and Dutch institutions drive procurement toward vendors with pre-certified EU data residency architectures.
- Telecommunications:Subscriber churn prevention programs generate high-frequency, low-margin mail volumes that demand postal rate optimization and address verification API integration.
- Real Estate:Agent-level marketing autonomy conflicts with corporate brand governance, creating demand for template-locking and distributed approval workflows.
- Nonprofits:Donor acquisition cost constraints favor SaaS deployment with volume-based pricing tiers and consolidated fundraising reporting.
- Higher Education:Advancement offices integrate automated mailers with Ellucian and Salesforce Education Cloud instances for alumni engagement and annual giving campaigns.
Procurement sophistication peaks in Financial Services; price sensitivity dominates Nonprofit selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC enforces truth-in-advertising standards that shape direct mail content compliance across the United States, while GDPR Article 7 mandates explicit consent capture for European physical outreach. National postal carriers control last-mile pricing in concentrated infrastructure markets.
United States
Fortune 500 marketing operations concentrate procurement authority under centralized CMO functions, displacing distributed department-level purchasing. The FTC monitors direct mail claims under Section 5 of the FTC Act. New York and Chicago financial services hubs drive enterprise adoption of API-first automation platforms.
Germany
Banks and insurers in Frankfurt and Munich require pre-certified EU data residency architectures to satisfy BSI baseline protection standards. The Federal Data Protection Act implements GDPR with additional national provisions. Bavarian manufacturing clusters adopt hybrid deployment models to balance compliance with cloud analytics capabilities.
United Kingdom
London-based fintech firms integrate direct mail automation into unified customer journey analytics stacks. The Information Commissioner's Office enforces UK GDPR consent requirements for personalized physical outreach. Thames Valley technology corridors host mid-market SaaS buyers seeking sub-second trigger-to-mail latency.
India
Mumbai and Bengaluru financial services hubs accelerate adoption of automated direct mail to complement digital outreach campaigns. The RBI issues data localization guidelines affecting cross-border customer data flows. PLI scheme incentives for cloud data centers enable localized platform deployment serving Asia-Pacific banking operations.
Japan
Tokyo insurance conglomerates deploy direct mail as measurable touchpoints within offline-digital attribution frameworks. METI promotes digital transformation subsidies for marketing automation adoption. Osaka manufacturing networks utilize postal API integration for high-frequency, low-margin subscriber retention volumes.
Global Direct Mail Automation Software Market Competitive Landscape
API-first specialists and physical gifting logistics providers split the market into distinct capability domains. Vendor differentiation hinges on latency performance, MarTech integration depth, and postal API coverage rather than print infrastructure ownership. Three archetypes dominate: developer-centric platform vendors, tactile marketing integrators, and campaign management consolidators. M&A activity concentrates on customer data platform connectivity assets, while geographic expansion targets EU data residency certification.
Within the developer-centric tier, Lob leverages API-first architecture to sustain technical positioning among engineering-led procurement teams. Sendoso anchors physical gifting workflows tied to automated direct mail orchestration. PFL occupies a position integrating tactile marketing into enterprise CRM ecosystems, exemplifying the tactile marketing integrator archetype.
| Leading Market Players |
|---|
| Sendoso |
| Lob |
| Postalytics |
| Reachdesk |
| Alyce |
| PostGrid |
| Inkit |
| PFL |
| Postal.io |
| Others |
Supply & Pricing Matrix
Overcapacity in North American cloud infrastructure is compressing deployment timelines and forcing vendors into usage-based pricing tiers that reward volume commitment. This utilization dynamic shifts bargaining power toward enterprise buyers consolidating multi-year contracts while squeezing margins for mid-market SaaS providers lacking postal API rate leverage.
Pricing Analysis
Geographic price spreads between United States and European deployments reflect GDPR Article 44 compliance premiums for EU-based processing nodes. Pricing stratifies across enterprise, mid-market, and small-business tiers with volume-based postal API surcharges and variable data printing fees complicating total cost forecasting. Cost compression in the mid-market tier is intensifying because cloud-native entrants undercut legacy on-premise vendors on provisioning speed. Nonprofit and higher education advancement offices exhibit highest price sensitivity due to donor acquisition cost constraints, while Fortune 500 financial services firms prioritize latency performance and ISO 27001 certification over unit economics.
Supply Chain Analysis
Upstream feedstock dependencies center on specialty paper substrates from Finland and Sweden, ink formulations from Germany and Japan, and cloud compute capacity concentrated in United States hyperscaler regions. The production workflow draws from variable data printing hardware manufactured in Germany and Japan, postal logistics APIs anchored in United States and German national carrier infrastructure, and developer talent pools in India and Eastern Europe. Single-source vulnerability in national postal carrier pricing—particularly Deutsche Post, USPS, and Japan Post—limits vendor negotiation leverage on last-mile delivery economics. Distribution runs through direct vendor sales organizations serving Fortune 500 enterprises, channel partners targeting mid-market SaaS buyers, and self-serve platforms capturing small-business procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct mail automation is absorbing real-time data synchronization capabilities from customer data platforms, creating a high-growth disruption as enterprise marketing stacks compress deployment timelines from quarters to weeks. This technological inflection rewards vendors with API-first architectures and ISO 27001 pre-certification while punishing legacy print-centric incumbents.
For Market Incumbents: Build switching-cost moats through deep CRM ecosystem integration with Salesforce, HubSpot, and Adobe Experience Cloud instances. Defensive moves should prioritize EU data residency certification to capture GDPR-bound financial services procurement in Frankfurt and Munich, alongside ISO 27001 audit streamlining to compress four-to-six-month sales cycles. Threats from cloud-native entrants with sub-second latency architectures demand capacity investment in India PLI-supported cloud data centers serving Asia-Pacific banking hubs. For New Entrants and Emerging Players: India's Mumbai and Bengaluru financial services corridors present underpenetrated demand for localized direct mail automation platforms serving RBI data localization requirements. White-space targets include healthcare patient engagement workflows integrating with Epic and Cerner EHR systems, and real estate agent-level marketing autonomy tools with corporate brand governance lockdown. Go-to-market positioning should emphasize AI-driven creative personalization APIs that enable segment-of-one content generation without manual production overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first platform vendors with developer-centric positioning and postal logistics API coverage spanning North America, Europe, and Asia-Pacific. Long-term viability over the next decade hinges on customer data platform connectivity assets and GDPR pre-certification architecture. Acquisition targets should demonstrate pre-built integrations with Snowflake, Segment, or mParticle. The signal to watch is enterprise procurement consolidation velocity—accelerated CMO centralization of marketing operations spend indicates tipping point for platform rollup strategies.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Sub-second latency between CDP triggers and mail file generation collapses online-offline campaign separation. |
| EU Data Residency Certification | BSI baseline protection compliance unlocks Frankfurt and Munich banking procurement budgets. |
| Healthcare EHR Integration | Epic and Cerner connectivity enables automated appointment reminder and medication adherence workflows. |
| AI-Driven Creative Personalization | Generative design tools reduce manual production overhead for segment-of-one postal campaigns. |
| Postal API Coverage Expansion | Deutsche Post, USPS, and Japan Post endpoint integration reduces undeliverable rates and rework cycles. |
Research Methodology
Operator-level perspectives from marketing operations directors, MarTech integration specialists, postal logistics API product managers, and enterprise procurement officers anchored the qualitative base. These primary interviews combined with secondary validation from SEC 10-K filings of publicly traded marketing technology vendors, hyperscaler capex disclosures revealing cloud infrastructure expansion patterns, and postal regulatory filings from USPS, Deutsche Post, and Japan Post. Bottom-up sizing of vendor-reported customer counts and average contract values triangulated against top-down estimates of enterprise marketing technology spend allocation.
Scenario-bracketing around regulatory enforcement intensity and cloud infrastructure buildout pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, end-user industry vertical, and regional adoption pattern. CAGRs derived from logistic diffusion curves fitted to historical SaaS penetration benchmarks, with inputs from API call volume growth trajectories and postal rate inflation assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants with sub-second latency architectures or hyperscaler-backed direct mail services would shift outcomes. Cross-checking against IDC and Gartner marketing technology spend forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Italy Marketing Automation Software Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Hyperautomation Market
Automation
Computer Numerical Control Market
Automation
Industrial Vending Machines Market
Automation
Global Process Automation and Instrumentation Market
Automation
Self Bag Drop Machine Market
Automation
Global Business Process Automation Software Market
Automation
North America Data Center Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
AR Automation Market
Automation
North America Home Automation Systems Market
Automation
Home Automation and Controls Market
Automation
Global Warehouse Execution System Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Micro Fulfillment Market