
 Automation Lifecycle Services Market | 2026-2036
Automation Lifecycle Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automation Lifecycle Services Market Analysis
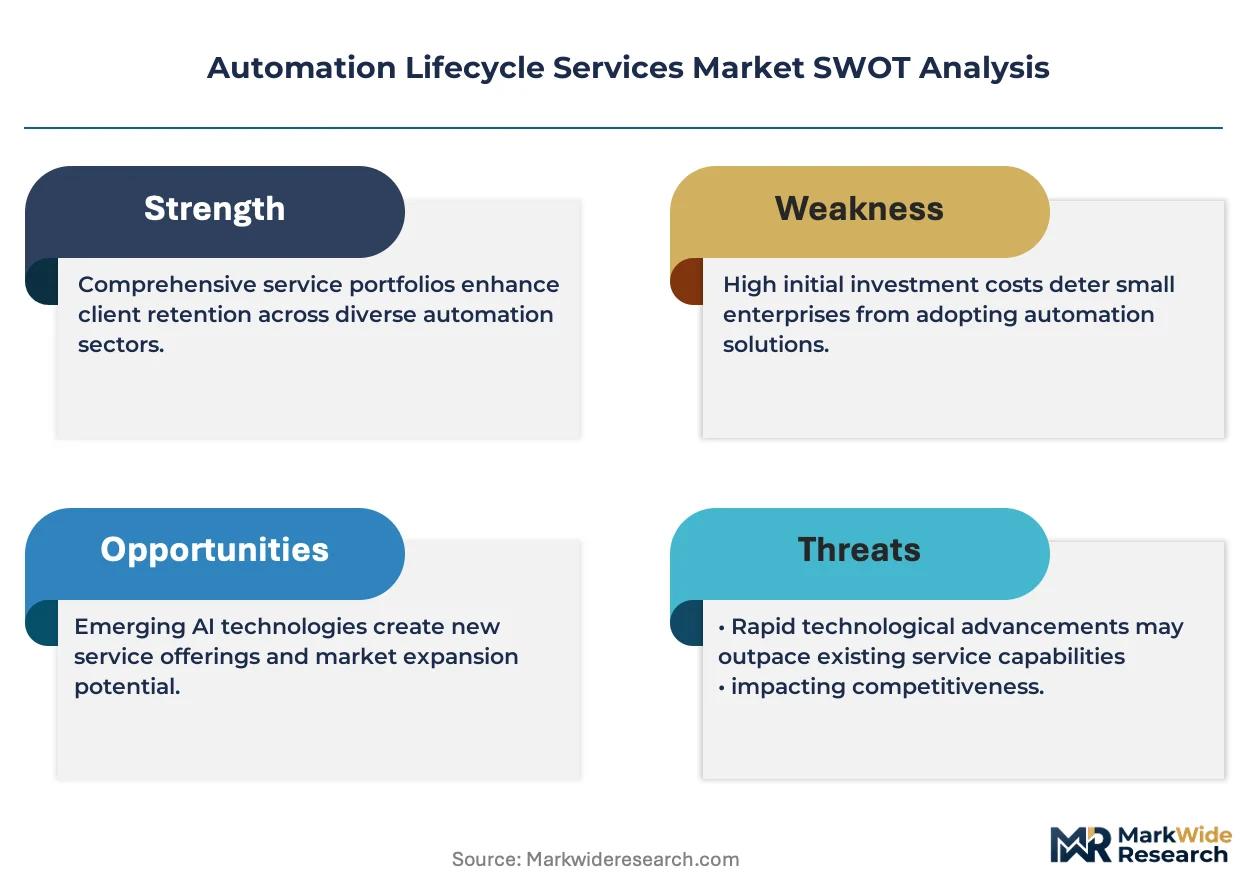
Asset-light service contracting and outcome-based leasing is fragmenting the competitive landscape for automation lifecycle services. Siemens AG leverages its digital twin portfolio to anchor long-term service agreements across process industries. Rockwell Automation, Inc. competes through its FactoryTalk software ecosystem, while ABB Ltd. extends its installed base advantage into predictive maintenance revenue streams.
Automation lifecycle services encompass the full spectrum of technical support required to sustain automated systems from commissioning through decommissioning, including firmware updates, calibration protocols, spare parts logistics, and safety integrity level verification. These services ensure operational continuity in environments where unplanned downtime can exceed $100,000 per hour in continuous process applications. Maintenance services currently dominate revenue generation due to recurring contractual structures, while AI-enabled predictive diagnostics represent the fastest-expanding technology segment as industrial users shift from calendar-based to condition-based intervention models. Cloud computing infrastructure supports this transition by enabling remote monitoring of distributed assets across manufacturing and logistics verticals.
The EU Machinery Directive and IEC 61508 functional safety standards shape service provider certification requirements and limit market access for uncertified operators. OSHA lockout/tagout regulations and FDA 21 CFR Part 11 electronic records requirements in the United States impose additional compliance burdens on lifecycle service contracts in pharmaceutical and food processing environments. Stakeholders must evaluate whether their service partner networks possess current certifications for the specific regulatory jurisdictions where automated assets operate.
Market Dynamics
Asset-light service contracting is fragmenting competitive positioning in automation lifecycle services, as industrial buyers shift capital expenditure toward operational expenditure models and demand outcome-based performance guarantees from service providers.
Growth Catalysts
- EU Machinery Directive compliance mandates:Tightened safety verification requirements for automated systems are compelling manufacturers to outsource lifecycle management to certified service specialists rather than maintain in-house capabilities.
- Predictive maintenance technology maturation:AI-enabled condition monitoring systems now deliver sufficient reliability for automotive producers to adopt performance-based service contracts tied to uptime metrics.
- German industrial cluster density:Concentration of automotive and chemical automation installations in Baden-Württemberg and North Rhine-Westphalia creates localized demand pull for specialized lifecycle service providers.
Market Restraints
- IEC 61508 certification scarcity:Limited pool of accredited functional safety engineers restricts service provider capacity expansion and elongates contract onboarding timelines for new market entrants.
- Legacy system interoperability barriers:Proprietary communication protocols from 1990s-era distributed control systems block seamless integration with modern cloud-based monitoring platforms.
- Spare parts supply concentration:Specialized actuator and sensor components for safety-critical applications source predominantly from single-region suppliers, exposing service contracts to geopolitical disruption risk.
Strategic Opportunities
- Pharmaceutical serialization compliance:FDA 21 CFR Part 11 electronic records requirements create recurring revenue streams for validation and audit-trail maintenance services in drug manufacturing environments.
- Digital twin convergence with edge computing:Real-time physics simulation combined with localized data processing enables predictive intervention models that reduce unplanned downtime below calendar-based maintenance thresholds.
- India industrial automation expansion:PLI scheme incentives for domestic manufacturing are accelerating greenfield facility construction, creating first-mover advantage for lifecycle service providers establishing local technical centers.
Industry Challenges
- Functional safety engineer shortage:SIL verification and proof testing competencies require multi-year apprenticeship pathways that outpace current training program throughput.
- Multi-vendor system integration complexity:Heterogeneous automation architectures combining Siemens, Rockwell, and ABB components demand cross-platform expertise that fragments service team specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation Lifecycle Services Market |
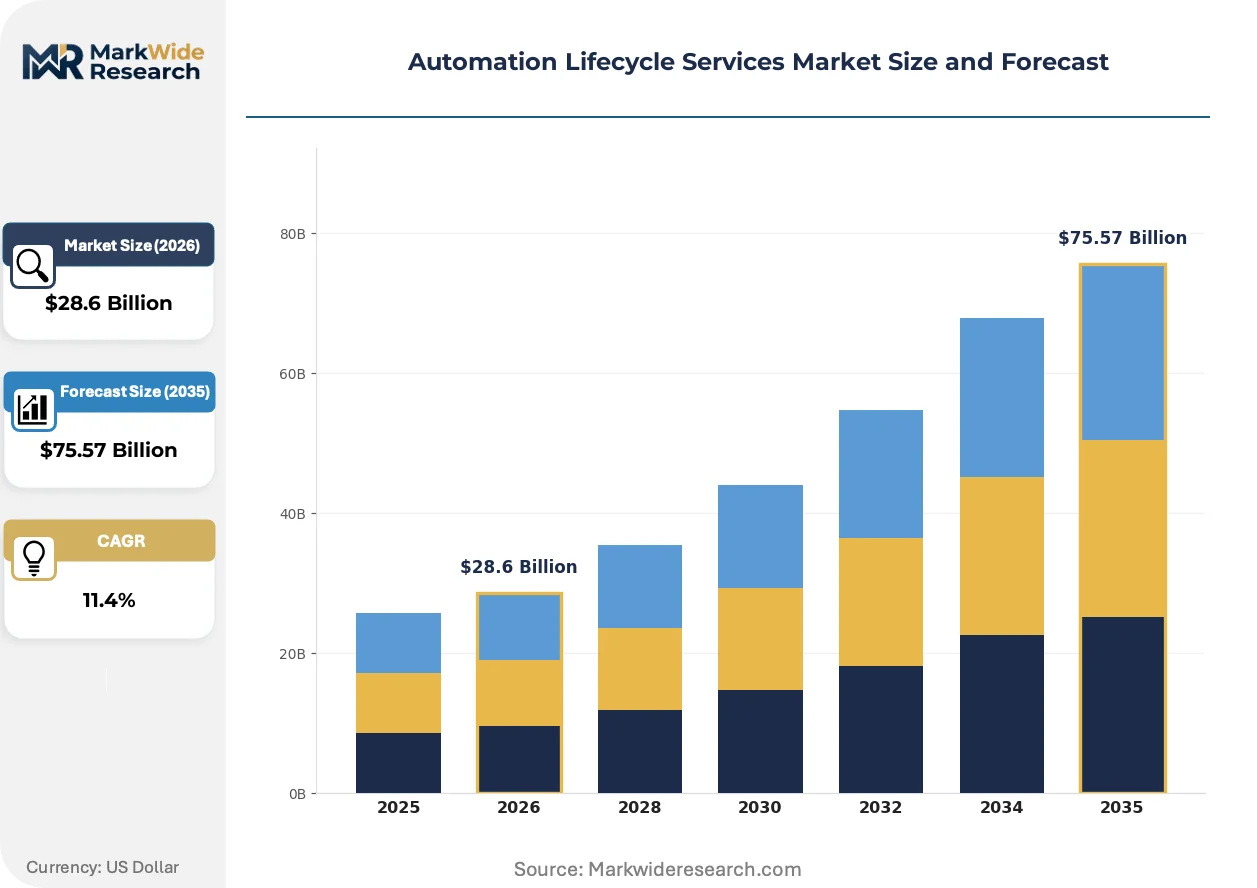
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Maintenance, Support Technology: Robotics, AI, Cloud Computing, IoT Industry Vertical: Manufacturing, Healthcare, Retail, Logistics End User: Small Enterprises, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | Danaher Corporation, Siemens AG, Rockwell Automation, Inc., Honeywell International Inc., Schneider Electric SE, Emerson Electric Co., ABB Ltd., Yokogawa Electric Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation Lifecycle Services Market Emerging Trajectories
Condition-based intervention models are displacing calendar-driven maintenance schedules across process industries, compressing service contract structures and rewiring how automation vendors capture lifetime value from installed equipment.
Edge-deployed AI diagnostics is hybridizing vibration analysis with thermal imaging and electrical signature analysis into unified degradation prediction engines. Chemical processing facilities in the US Gulf Coast are piloting these systems at scale. This convergence is hybridizing previously separate sensor categories into integrated health monitoring platforms that collapse multiple maintenance workflows into single intervention triggers.
REACH substance restriction amendments are phasing out specific lubricant and sealant chemistries used in pneumatic actuation systems. Industrial equipment service providers must reformulate preventive maintenance protocols and retrain field technicians on compliant material substitutions. Food and beverage packaging lines in EU member states are experiencing the most acute compliance pressure due to direct product contact requirements.
Buyer consolidation among contract manufacturers is concentrating purchasing power and unbundling aftermarket services from original equipment procurement. Tier-one automotive suppliers in Germany now negotiate lifecycle service agreements separately from automation hardware acquisitions, pressuring vendor margins. This disintermediation is most pronounced in powertrain assembly operations where equipment standardization across multiple OEM customers enables generic service provider substitution.
Automation Lifecycle Services Market Segmentation
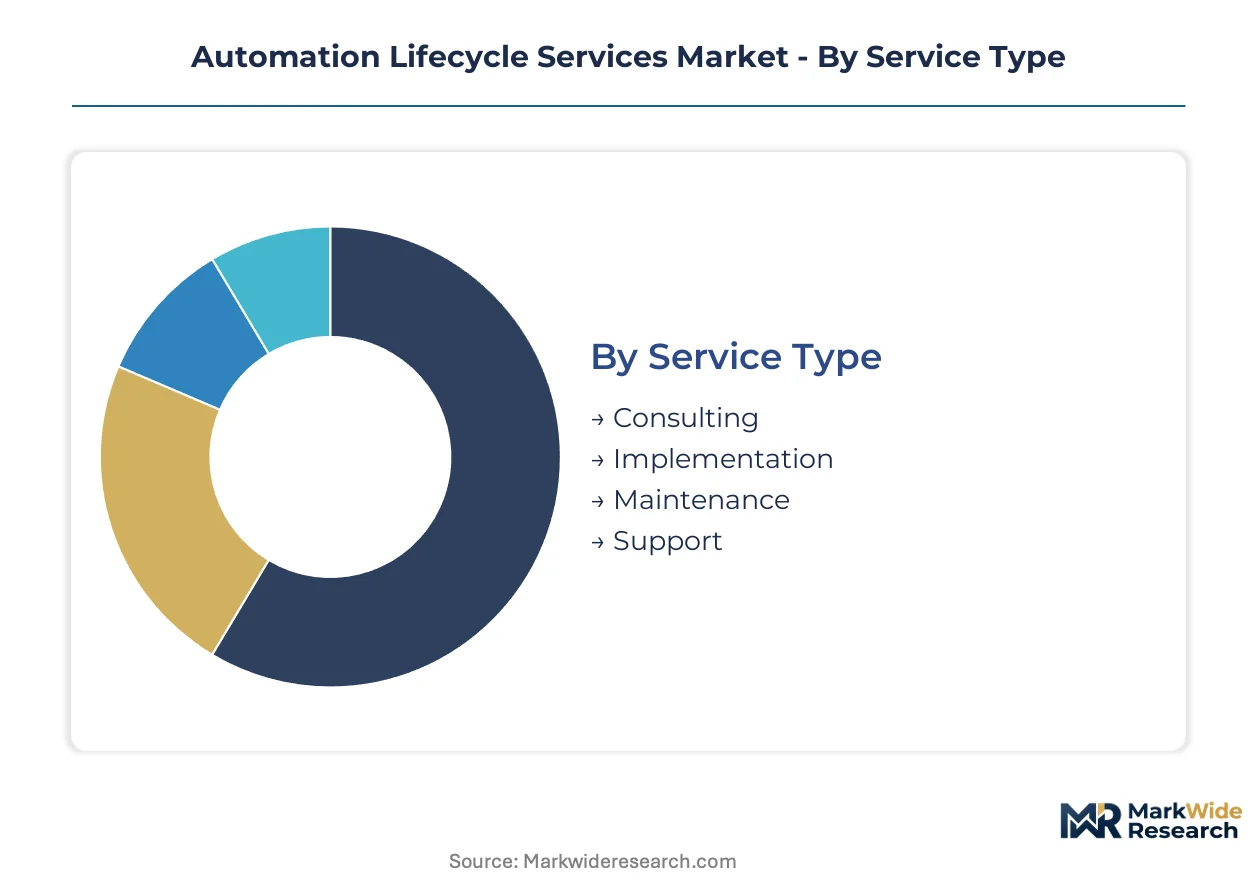
Automation lifecycle services fragment across service delivery models, underlying technologies, target industries, and buyer scale. Each dimension carries distinct margin profiles, certification requirements, and contract structuring norms that shape vendor strategy and competitive positioning.
Service Type:
The use-case spectrum spans advisory engagement through long-term operational support, with contract duration and liability exposure varying sharply across the continuum.
- Consulting:Front-end system assessment and upgrade pathway design. German automotive clusters in Baden-Württemberg concentrate demand as manufacturers map IEC 61508 compliance migration strategies ahead of EU Machinery Directive enforcement deadlines.
- Implementation:Commissioning, integration, and initial validation services. Demand concentrates in India where PLI scheme incentives accelerate greenfield facility construction and first-mover service providers anchor multi-year support agreements.
- Maintenance:Recurring preventive and corrective intervention contracts. Calendar-based schedules still dominate revenue volume though condition-based models are gaining share fastest in continuous process applications.
- Support:Remote diagnostics, firmware updates, and emergency response. Cloud infrastructure enables 24/7 coverage for distributed assets across logistics networks and multi-site manufacturing footprints.
Established volume favors Maintenance; emerging adoption favors Implementation.
Technology:
Cost tier separation runs from capital-intensive hardware integration to software-margin service layers, with hybrid deployments commanding premium pricing.
- Robotics:Kinematic calibration, safety zone verification, and end-effector maintenance. Automotive powertrain assembly lines in Germany unbundle robot lifecycle services from OEM hardware procurement, pressuring traditional vendor margins.
- AI:Predictive diagnostics and degradation modeling. US Gulf Coast chemical processing facilities pilot edge-deployed vibration-thermal-electrical signature fusion at scale, collapsing multiple maintenance workflows into unified intervention triggers.
- Cloud Computing:Remote monitoring infrastructure and data pipeline management. Enables distributed asset visibility but faces interoperability barriers against proprietary protocols from 1990s-era control systems.
- IoT:Sensor deployment, edge connectivity, and telemetry optimization. REACH substance restrictions on lubricants and sealants force reformulation of pneumatic actuator maintenance protocols in EU food packaging environments.
Revenue concentration sits with Robotics; steepest expansion trajectory belongs to AI.
Industry Vertical:
Application severity drives certification depth, with safety-critical environments demanding SIL verification and audit-trail maintenance that general manufacturing escapes.
- Manufacturing:Process control, assembly automation, and quality system sustainment. Dense automation clusters in Germany's chemical and automotive sectors pull specialized lifecycle service provider capacity.
- Healthcare:FDA 21 CFR Part 11 validation and electronic records compliance. Drug manufacturing environments create recurring revenue streams for audit-trail maintenance and serialization system upkeep.
- Retail:Warehouse automation and fulfillment robotics. Less regulated than manufacturing verticals, permitting faster adoption of outcome-based contracting models.
- Logistics:Sortation systems, AGV fleets, and yard management automation. Cloud-based remote monitoring supports geographically distributed asset footprints across multi-node distribution networks.
Contract value concentrates in Manufacturing; regulatory tailwinds favor Healthcare.
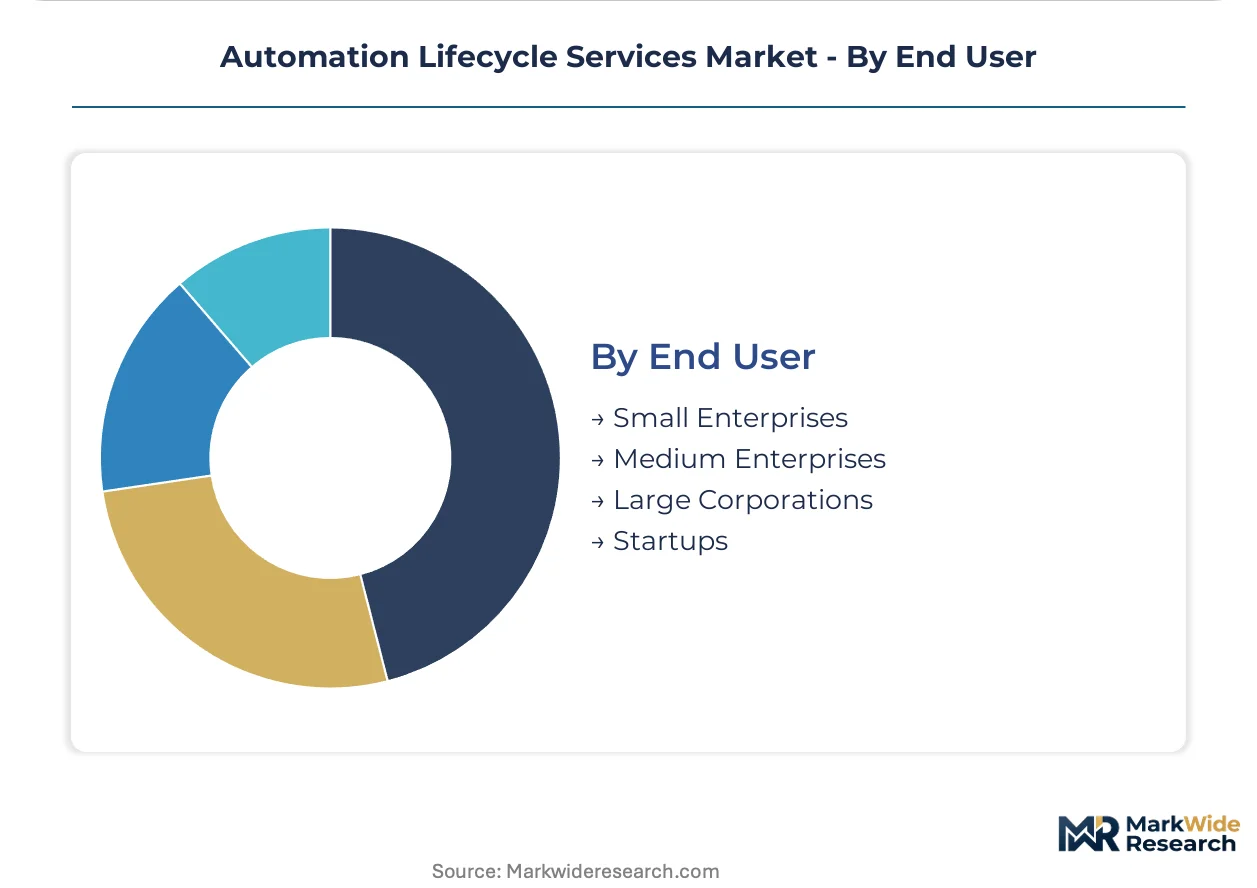
End User:
Customer type determines procurement sophistication, with large corporations unbundling services from hardware while smaller buyers accept bundled vendor packages.
- Small Enterprises:Limited in-house automation expertise drives preference for comprehensive service contracts with predictable opex structures.
- Medium Enterprises:Emerging procurement sophistication enables selective unbundling of maintenance from original equipment acquisition.
- Large Corporations:Tier-one automotive suppliers in Germany now negotiate lifecycle agreements separately from hardware, concentrating purchasing power and pressuring vendor margins.
- Startups:Asset-light models favor outcome-based leasing and performance-guaranteed service tiers over capital-intensive ownership.
Procurement volume anchors Large Corporations; contract innovation originates with Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automation lifecycle services favor net-importing industrial economies with dense manufacturing bases. Germany and the United States run structural deficits in specialized safety engineering talent, sourcing IEC 61508-certified functional safety expertise from smaller EU member states and India. Service trade flows concentrate where regulatory complexity exceeds domestic technical capacity.
Germany
Automotive powertrain automation and chemical processing clusters in Baden-Württemberg and North Rhine-Westphalia absorb the majority of European predictive maintenance contracting volume. The EU Machinery Directive enforcement timeline compels manufacturers to outsource SIL verification to certified specialists rather than maintain captive engineering teams. Tier-one automotive suppliers in Stuttgart now negotiate lifecycle agreements separately from hardware procurement, fragmenting vendor relationships.
United States
FDA 21 CFR Part 11 compliance requirements in pharmaceutical manufacturing and OSHA lockout/tagout enforcement in food processing create dual regulatory demand streams for validation and safety verification services. The US Gulf Coast chemical corridor pilots edge-deployed AI diagnostics at scale, collapsing vibration analysis and thermal imaging into unified degradation prediction engines. Houston-based service providers anchor multi-year contracts with continuous process operators.
China
Dual carbon goals and MIIT smart manufacturing directives accelerate greenfield facility construction in the Yangtze River Delta and Pearl River Delta regions. Domestic automation OEMs expand aftermarket service footprints to capture lifetime value from installed robotics and process control systems. NMPA pharmaceutical serialization requirements mirror FDA electronic records standards, creating compliance service demand in drug manufacturing hubs.
India
PLI scheme incentives for domestic manufacturing trigger greenfield automation deployment in Gujarat and Maharashtra industrial corridors. First-mover lifecycle service providers establish technical centers in Pune and Ahmedabad to anchor multi-year support agreements with new facility operators. CDSCO pharmaceutical manufacturing standards drive validation service demand in API production clusters.
Japan
METI-connected industries policies and aging installed base demographics expand predictive maintenance adoption in automotive and electronics manufacturing. Kanto and Kansai industrial belts concentrate demand for robot kinematic calibration and safety zone verification services. JIS functional safety standards align with IEC 61508, enabling cross-certified service provider entry from European markets.
Automation Lifecycle Services Market Vendor Landscape
On the supply side, the industry is consolidating around multi-industry conglomerates with captive automation hardware installed bases and fragmenting among specialized safety engineering boutiques. Siemens AG, Rockwell Automation, and ABB Ltd. anchor the integrated tier through digital twin portfolios and software ecosystems that lock in long-term service agreements. Independent service providers compete on IEC 61508 certification depth and cross-platform integration expertise. Dominant competitive moves include outcome-based contracting structures that convert capital expenditure to operational expenditure, and strategic partnerships with cloud infrastructure providers to enable remote monitoring scale.
Within the integrated automation tier, Siemens AG and Rockwell Automation occupy positions that exemplify hardware-anchored service bundling, leveraging FactoryTalk and digital twin platforms to capture recurring revenue from process industry installed bases. ABB Ltd. represents the predictive maintenance pivot, extending legacy robotics and power automation footprints into condition-based intervention contracts. Among European-headquartered specialists, Schneider Electric SE and Emerson Electric Co. sit within the energy and process control service archetype, competing through safety system verification and calibration protocol standardization across chemical and pharmaceutical manufacturing environments.
| Leading Market Players |
|---|
| Danaher Corporation |
| Siemens AG |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Emerson Electric Co. |
| ABB Ltd. |
| Yokogawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in IEC 61508-certified functional safety engineering across Germany and the United States compresses supplier response times and hardens pricing power for SIL verification services. Tier-one automotive manufacturers in Stuttgart now accept premium contract rates to secure scarce certified engineering capacity ahead of EU Machinery Directive enforcement deadlines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in automation lifecycle services. Premium tiers command spreads based on IEC 61508 SIL certification depth and cross-platform integration expertise spanning Siemens, Rockwell, and ABB architectures. Cost compression in standard maintenance tiers is intensifying because buyer consolidation among German automotive suppliers unbundles aftermarket services from original equipment procurement. Small enterprises exhibit highest price sensitivity due to limited procurement sophistication, while large corporations absorb premium rates for outcome-based uptime guarantees.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for specialized actuator and sensor components in safety-critical applications. Component sourcing concentrates in Germany, Japan, and China for precision motion control hardware used in robotic calibration protocols. Raw material dependencies include rare earth magnets for servo motors, high-grade lubricants facing REACH substance restrictions, and semiconductor-grade sensors for edge-deployed diagnostics. Single-source vulnerability persists for pneumatic sealant chemistries compliant with EU food contact regulations. Distribution runs through authorized service partner networks anchored by OEM technical centers in industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automation lifecycle services market is recovering from cyclical capital expenditure contraction in process industries. Greenfield facility construction under India's PLI scheme and US Gulf Coast chemical expansion are pulling demand forward.
For Market Incumbents: Entrench installed base advantage by embedding digital twin platforms into multi-year predictive maintenance contracts before buyer consolidation fragments vendor relationships. Acquire IEC 61508 certification capacity in Eastern European talent pools to deflect engineer scarcity pressure. Extend software ecosystem lock-in through FactoryTalk or equivalent platform integration that raises switching costs for process industry operators.
For New Entrants and Emerging Players: Build out cross-platform integration expertise targeting mid-tier automotive suppliers in Germany who have unbundled lifecycle services from hardware procurement. Penetrate pharmaceutical serialization compliance in US and EU markets where FDA 21 CFR Part 11 and EMA equivalent requirements create recurring validation revenue. Lead with edge-deployed AI diagnostics pilots in chemical processing to establish performance credibility before scaling to maintenance contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among safety engineering boutiques with deep IEC 61508 certification portfolios and captive relationships in German automotive clusters. Long-term viability hinges on software-anchored service models that capture lifetime value from installed robotics and process control systems. Watch for inflection when tier-one manufacturers begin consolidating lifecycle service procurement across multiple OEM hardware suppliers, signaling platform-agnostic provider preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens and Rockwell anchor long-term contracts through physics simulation tied to predictive maintenance revenue streams. |
| IEC 61508 Certification Expansion | Service providers in Poland and Czechia capture overflow demand from German automotive and chemical automation clusters. |
| Edge-Deployed AI Diagnostics | US Gulf Coast chemical facilities pilot vibration-thermal-electrical signature fusion to collapse maintenance workflows. |
| Outcome-Based Contracting Models | Tier-one automotive suppliers in Stuttgart negotiate uptime guarantees that convert capital expenditure to operational expenditure. |
| Pharmaceutical Serialization Compliance | FDA 21 CFR Part 11 and EMA validation requirements create recurring audit-trail maintenance revenue in drug manufacturing. |
Methodological Framework
Desk research of regulatory filings, industry association reports, and OEM technical documentation preceded structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork across Germany, the United States, India, and China validated secondary data on certification capacity, contract structuring norms, and technology adoption patterns. Bottom-up service contract value analysis was triangulated against top-down market sizing from automation hardware installed base estimates.
Assumptions regarding EU Machinery Directive enforcement timelines, PLI scheme incentive continuity in India, and predictive maintenance technology maturation curves were held fixed across baseline scenarios while tariff exposure and functional safety engineer supply elasticity were stress-tested. Segmentation modeling incorporated service delivery model, underlying technology, target industry vertical, and buyer scale dimensions. CAGRs were derived from installed base growth projections, contract renewal rate assumptions, and technology substitution curves for condition-based versus calendar-based maintenance.
Stress conditions across IEC 61508 certification pipeline throughput, REACH substance restriction amendment scope, and cloud infrastructure interoperability with legacy control systems were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory enforcement delays or supply chain disruptions for specialized safety components could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Window Automation Market
Automation
Distribution Automation Solutions Market
Automation
Home Automation Market
Automation
Indonesia Automation and Control System Market
Automation
Global Field Force Automation Market
Automation
Helpdesk Automation Market
Automation
IoT Home Automation Market
Automation
Global Automated Sample Storage Systems Market
Automation
Global Zig-Bee Automation Market
Automation
Postal Automation System Market
Automation
Europe Data Center Automation Market
Automation
Global Automated Liquid Handling System Market
Automation
Asia-Pacific Data Center Automation Market
Automation
North America Home Automation Systems Market
Automation
Computer Numerical Control Market
Automation
Europe Marketing Automation Software Market