
 RFID Kanban Systems Market | 2026-2036
RFID Kanban Systems Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Kanban Systems Market Intelligence
Buyer concentration among large automotive OEMs and tier-one suppliers is realigning procurement patterns for RFID Kanban infrastructure. Zebra Technologies leverages its printer-encoder ecosystem to dominate hardware deployment at major assembly plants. SATO competes through specialized label durability for reusable tote applications in high-temperature paint shops. Impinj anchors the silicon layer with RAIN RFID endpoint ICs that power passive tag populations across North American and European manufacturing networks.
RFID Kanban systems integrate radio-frequency identification tags, fixed or handheld interrogators, and software middleware to automate visual replenishment signals without manual card exchange. Passive ultra-high frequency tags operating in the 860-960 MHz band provide read ranges of 3-10 meters, enabling portal-based consumption tracking at assembly line boundaries without direct line-of-sight. Application segmentation shows manufacturing and supply chain management commanding the installed base, while inventory control deployments in pharmaceutical and electronics contract manufacturers represent the fastest-expanding margin pool. Technology segmentation reveals passive RFID sustaining volume leadership due to sub-dollar tag economics, though real-time location systems are displacing traditional Kanban in high-value aerospace component tracking where spatial precision justifies infrastructure cost.
FDA traceability mandates under the Drug Supply Chain Security Act shape healthcare RFID Kanban demand by requiring lot-level electronic records for pharmaceutical inventory. The EU AI Act and Machinery Directive, enforced by national market surveillance authorities in Germany and France, establish conformity requirements for autonomous replenishment algorithms in smart factory deployments. OSHA workplace safety inspections in the United States increasingly reference automated material handling data as evidence of ergonomic hazard mitigation. Stakeholders must monitor how evolving cybersecurity certification for connected industrial devices reshapes vendor qualification criteria and procurement specifications.
Market Dynamics
Automotive OEM consolidation around Stuttgart and Wolfsburg is compressing supplier qualification timelines for RFID Kanban infrastructure, forcing hardware vendors to co-locate technical support teams within manufacturing corridors.
Growth Catalysts
- EU Green Deal circular economy rules:Reusable container tracking mandates are expanding addressable market for durable RAIN RFID tags in German and French manufacturing networks.
- Paint shop automation:High-temperature resistant passive UHF labels enable Kanban digitization in automotive coating processes previously excluded from RFID deployment.
- FDA Drug Supply Chain Security Act:Lot-level electronic record requirements for pharmaceutical inventory are pulling RFID Kanban into healthcare distribution centers.
Market Restraints
- Silicon supply concentration:Passive tag IC fabrication depends on a limited foundry base in East Asia, exposing lead times to geopolitical disruption.
- Metals price volatility:Copper and aluminum antenna substrates face commodity swings that compress tag gross margins at volume.
- Real-time location system substitution:Ultra-wideband spatial tracking is capturing high-value aerospace component tracking where meter-level precision justifies infrastructure cost.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Contract manufacturers establishing capacity near Chennai and Noida require Kanban automation for component flow management.
- Battery cell gigafactories:Electrolyte and separator replenishment workflows in European and North American cell plants represent greenfield RFID deployment.
- EU AI Act conformity requirements:Autonomous replenishment algorithm certification creates service revenue streams for systems integrators supporting smart factory deployments.
Industry Challenges
- RF engineer scarcity:Portal antenna tuning and interrogator placement optimization require specialized field expertise concentrated among legacy industrial automation firms.
- Legacy MES integration:SAP and Oracle manufacturing execution systems demand custom middleware development for bidirectional Kanban signal translation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Kanban Systems Market |
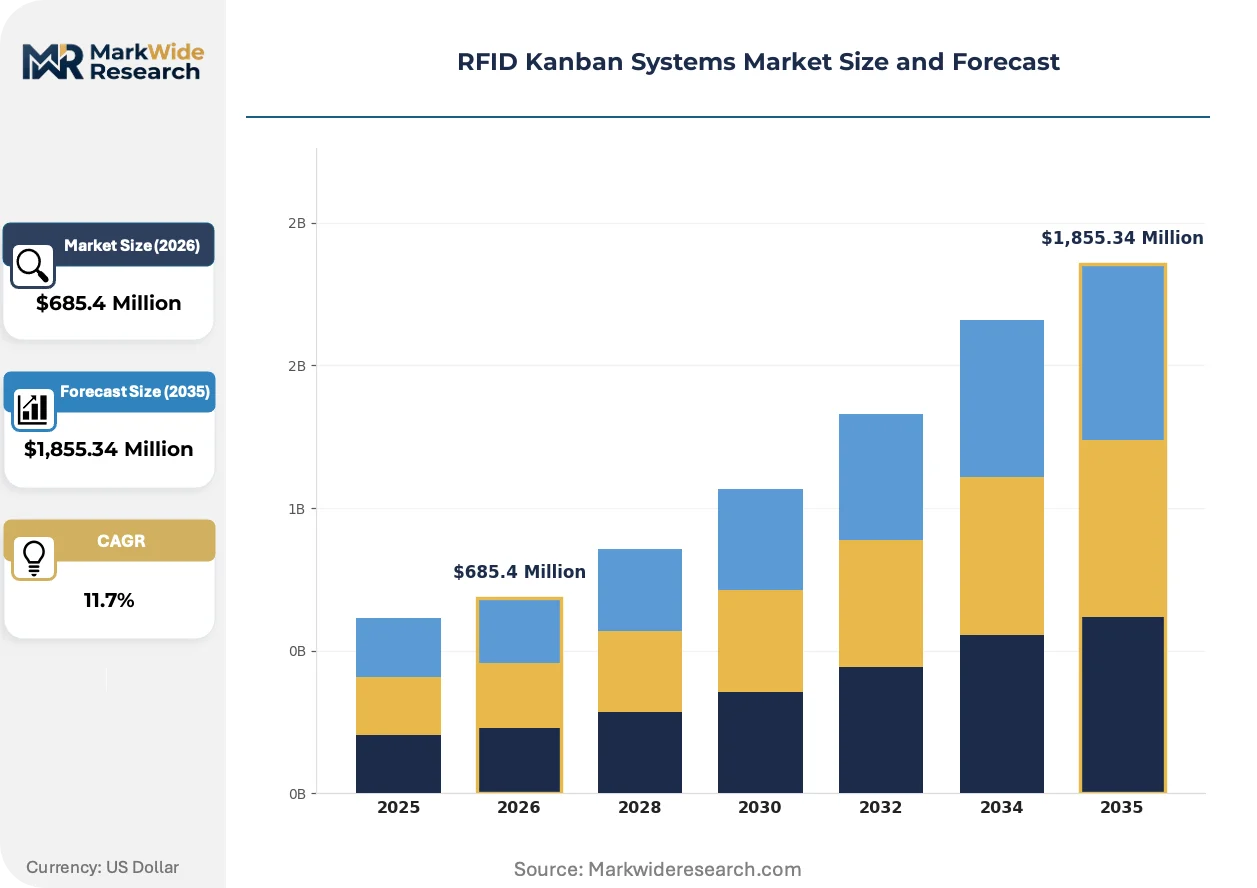
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active RFID, Passive RFID, Semi-Passive RFID, Real-Time Location Systems Application: Manufacturing, Supply Chain Management, Inventory Control, Automotive End User: Retail, Healthcare, Aerospace, Food & Beverage Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | SATO, Pepperl+Fuchs, Zebra Technologies, Checkpoint Systems, Alien Technology, Avery Dennison, Honeywell, MetraTec, Impinj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Kanban Systems Market Strategic Shifts & Innovations
Passive UHF tag economics and real-time location precision are converging to expand RFID Kanban addressability beyond traditional automotive boundaries into pharmaceutical and battery manufacturing workflows.
Sensor-integrated passive RFID tags with temperature and humidity logging capability are rewriting cold chain Kanban protocols for biologic pharmaceuticals. Contract manufacturers in Switzerland and Germany are piloting these tags for insulin and vaccine tote tracking. The technology is compressing manual environmental monitoring labor while generating auditable compliance records for EMA inspections.
REACH substance restrictions on adhesive binders are forcing tag antenna manufacturers to reformulate conductive inks for European market access. Industrial label converters in Germany must now qualify alternative silver flake and carbon-based formulations. Paint shop applications around Stuttgart face the tightest compliance timelines due to high-temperature exposure requirements.
Consolidated procurement desks at tier-one automotive suppliers are unbundling hardware, software, and integration services into separate contract vehicles. Buyers in Wolfsburg and Munich now negotiate tag supply independently from middleware licensing. This pattern is most visible in Germany's automotive corridor where purchasing leverage concentrates among Volkswagen Group and BMW supplier networks.
RFID Kanban Systems Market Segmentation
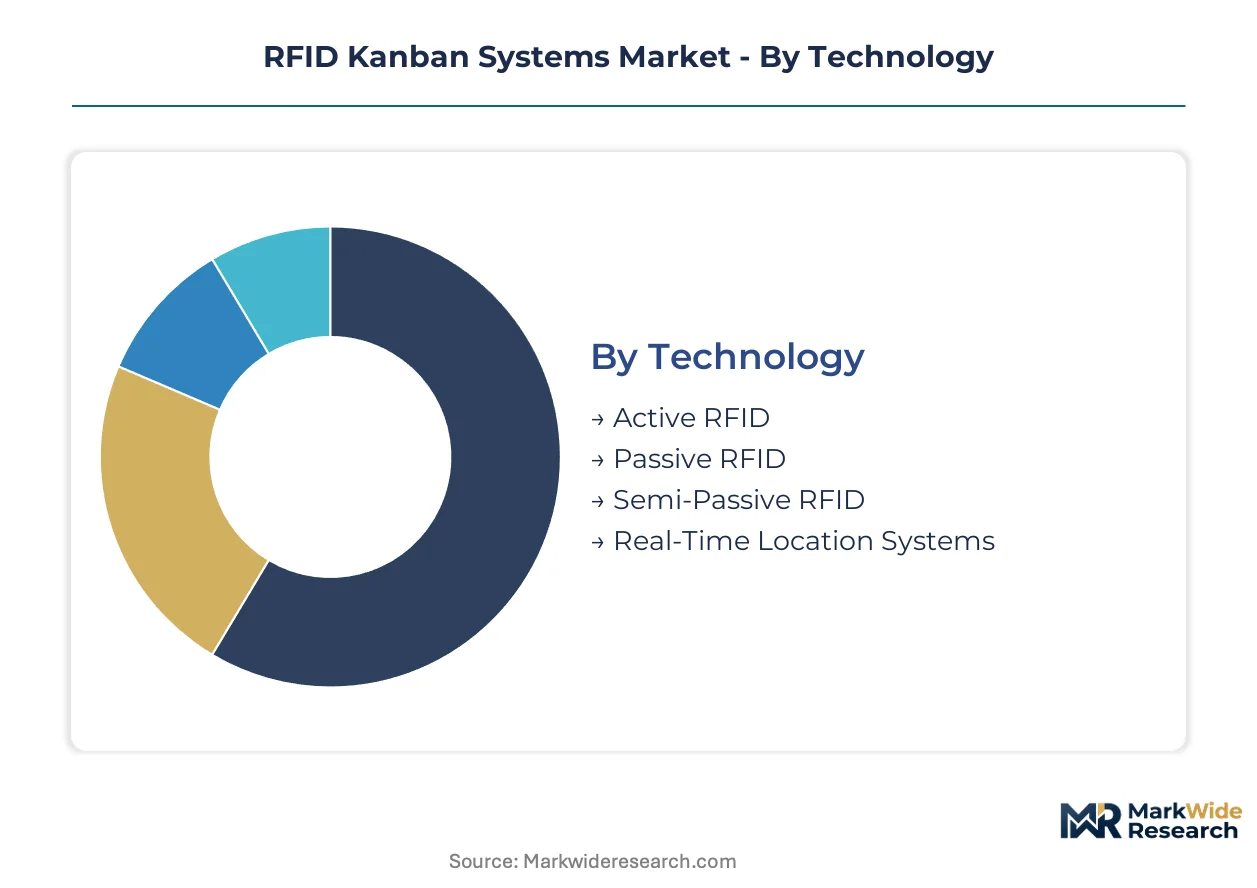
RFID Kanban procurement decisions hinge on tag economics, read-range requirements, and integration complexity with legacy manufacturing execution systems. Buyers weigh passive UHF sub-dollar unit costs against active tag battery maintenance and real-time precision needs. The four segmentation dimensions—technology, application, end user, and deployment—reflect distinct buyer workflows rather than interchangeable product categories.
Technology:
Cost tier determines initial deployment feasibility and total cost of ownership across multi-year manufacturing contracts.
- Passive RFID:UHF tags operating in the 860-960 MHz band require no onboard power source and achieve 3-10 meter read ranges through portal antennas. German automotive assembly plants around Stuttgart and Wolfsburg deploy these for just-in-time component replenishment where sub-dollar tag economics justify high-volume consumption tracking.
- Active RFID:Battery-powered tags transmit at higher power levels, enabling 100-meter read ranges and sensor integration for temperature logging. Swiss pharmaceutical contract manufacturers pilot these for insulin and vaccine cold chain Kanban where environmental monitoring compliance with EMA inspections justifies the infrastructure investment.
- Semi-Passive RFID:Battery-assisted passive designs use onboard power for sensor functionality while relying on reader energy for transmission.
- Real-Time Location Systems:Ultra-wideband and Wi-Fi-based spatial tracking deliver meter-level precision for high-value aerospace component positioning.
Passive RFID leads on scale; real-time location systems lead on momentum in precision-critical environments.
Application:
Volume concentration tracks automotive OEM consolidation patterns and regulatory compliance deadlines in healthcare distribution.
- Manufacturing:Assembly line boundary portals automate visual replenishment signals without manual card exchange. Paint shop automation in German automotive corridors drives demand for high-temperature resistant passive UHF labels previously excluded from RFID deployment.
- Inventory Control:Pharmaceutical and electronics contract manufacturers represent expanding margin pools as FDA Drug Supply Chain Security Act mandates pull RFID Kanban into healthcare distribution centers for lot-level electronic record maintenance.
- Supply Chain Management:Multi-tier supplier networks coordinate component flow through shared Kanban signal platforms.
- Automotive:Tier-one supplier procurement desks unbundle hardware and software contracts independently within Volkswagen Group and BMW supplier networks.
Manufacturing leads on scale; inventory control leads on momentum as regulatory deadlines compress adoption timelines.
End User:
Regulatory exposure and asset value density shape technology selection across vertical workflows.
- Healthcare:FDA traceability mandates under the Drug Supply Chain Security Act require lot-level electronic records for pharmaceutical inventory, pulling passive UHF Kanban into hospital and distribution center workflows.
- Aerospace:Ultra-wideband spatial tracking captures high-value component positioning where meter-level precision justifies infrastructure cost against traditional Kanban.
- Retail:Reusable container tracking for apparel and electronics fulfillment networks.
- Food & Beverage:Cold chain monitoring for perishable inventory rotation.
Healthcare leads on scale; aerospace leads on momentum as precision requirements intensify.
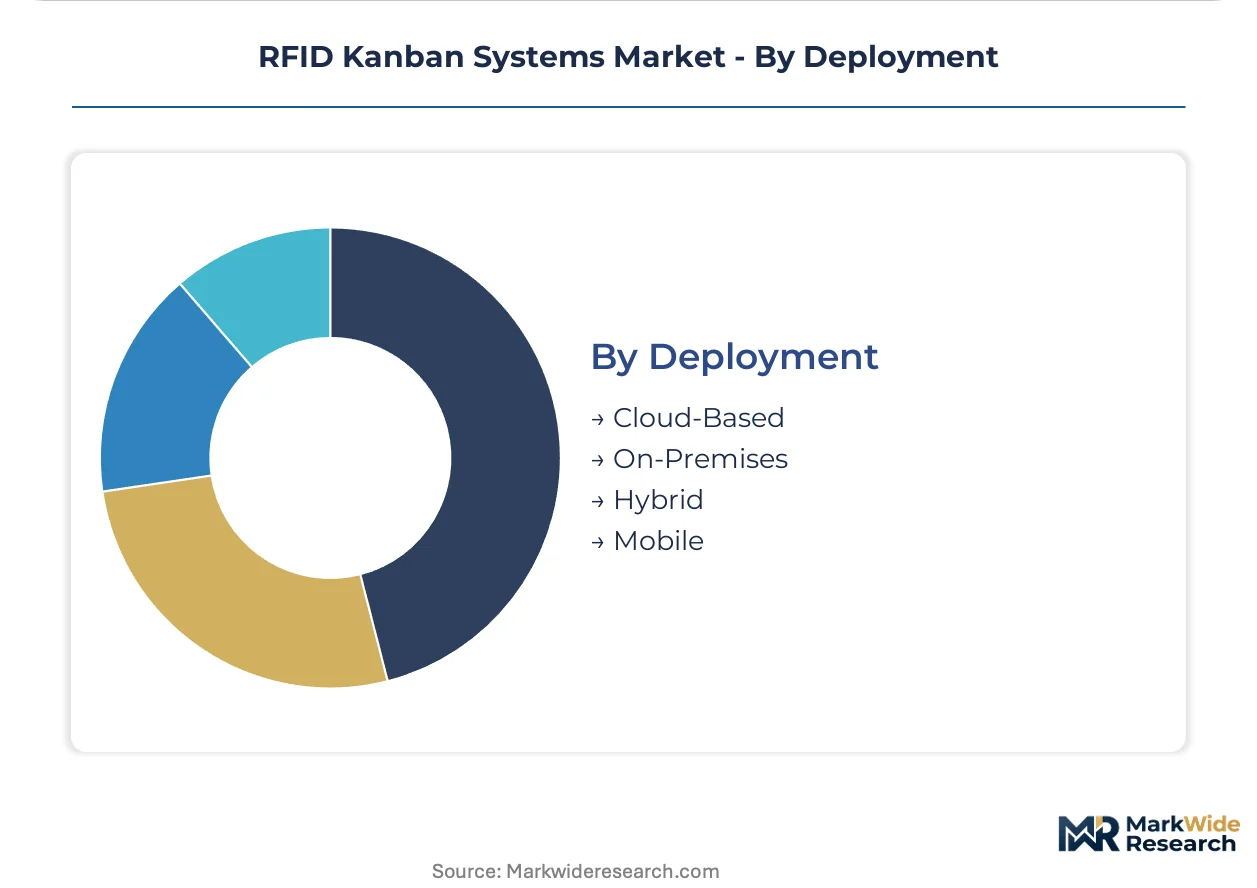
Deployment:
IT governance maturity and data sovereignty requirements determine architecture selection across manufacturing networks.
- On-Premises:SAP and Oracle manufacturing execution system integration demands custom middleware development for bidirectional Kanban signal translation, favoring localized server deployment in data-sensitive automotive and aerospace facilities.
- Cloud-Based:Scalable subscription models reduce capital expenditure for mid-tier contract manufacturers establishing capacity under India's PLI scheme for electronics manufacturing near Chennai and Noida.
- Hybrid:Edge computing architectures process time-sensitive replenishment signals locally while aggregating analytics in cloud environments.
- Mobile:Handheld interrogator deployments enable flexible inventory audits without fixed infrastructure investment.
On-premises leads on scale; cloud-based leads on momentum among emerging manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive RFID Kanban deployment around Stuttgart and Wolfsburg, while the United States pulls pharmaceutical adoption through FDA traceability mandates. China scales manufacturing automation under dual carbon goals, and India expands contract manufacturing corridors under PLI incentives. Battery gigafactories across multiple geographies are emerging as greenfield deployment zones.
United States
Pharmaceutical distribution centers drive RFID Kanban adoption as FDA Drug Supply Chain Security Act deadlines enforce lot-level electronic record requirements. OSHA workplace safety inspections increasingly reference automated material handling data as evidence of ergonomic hazard mitigation. Healthcare logistics clusters around Indianapolis and Memphis deploy passive UHF systems for high-volume drug inventory rotation.
Germany
Automotive OEM consolidation compresses supplier qualification timelines, forcing hardware vendors to co-locate technical support teams within manufacturing corridors. EU Green Deal circular economy packaging rules pressure manufacturers toward reusable container tracking with durable RAIN RFID tags. Paint shop automation in Baden-Württemberg drives demand for high-temperature resistant passive UHF labels previously excluded from RFID deployment.
China
Electronics contract manufacturers scale Kanban automation under MIIT smart factory directives and dual carbon efficiency targets. NMPA pharmaceutical traceability rules parallel FDA mandates, pulling RFID into domestic drug distribution networks. Yangtze River Delta industrial clusters around Shanghai and Suzhou represent the densest concentration of portal-based consumption tracking installations.
India
PLI scheme incentives for electronics manufacturing establish greenfield capacity near Chennai and Noida requiring component flow automation. BIS certification requirements for industrial IoT devices shape vendor qualification criteria for smart factory deployments. Karnataka and Telangana automotive component hubs pilot RFID Kanban for just-in-time supply to export-oriented assembly plants.
Switzerland
Pharmaceutical contract manufacturers pilot sensor-integrated passive RFID tags for insulin and vaccine cold chain Kanban under Swissmedic environmental monitoring requirements. REACH substance restrictions on adhesive binders force tag antenna reformulation for European market access. Basel and Zurich biologics manufacturing clusters generate auditable compliance records for EMA inspections through automated environmental logging.
RFID Kanban Systems Market Key Industry Players
German automation specialists anchor one tier; US silicon and hardware vendors hold another. The market structures around three distinct competitive layers: integrated platform providers, component specialists, and regional systems integrators. Consolidation pressure concentrates among tier-one automotive procurement desks unbundling hardware, software, and integration services. Strategic moves center on co-location of technical support within manufacturing corridors and middleware development for legacy MES integration.
Within the integrated platform tier, Zebra Technologies and SATO exemplify divergent specialization paths. Zebra leverages printer-encoder ecosystem dominance at major assembly plants, while SATO competes through label durability engineering for reusable tote applications. Impinj anchors the silicon layer with RAIN RFID endpoint IC supply across North American and European manufacturing networks. These three occupy positions reflecting hardware, consumables, and semiconductor archetypes respectively.
| Leading Market Players |
|---|
| SATO |
| Pepperl+Fuchs |
| Zebra Technologies |
| Checkpoint Systems |
| Alien Technology |
| Avery Dennison |
| Honeywell |
| MetraTec |
| Impinj |
| Others |
Cost & Logistics Intelligence
RFID engineer concentration in Germany's automotive corridor around Stuttgart and Wolfsburg drives labor-cost premiums that widen pricing spreads between premium-tier integrated platforms and economy hardware configurations.
Pricing Analysis
Capacity additions in India's electronics manufacturing corridors near Chennai and Noida are reshaping price floors for mid-tier cloud-based deployments. Three-tier pricing structure across premium, standard, and economy levels separates SAP-integrated on-premises systems from subscription SaaS models and basic handheld interrogator bundles. Price differentiation stems from CE marking complexity for EU AI Act conformity and volume scale of tag consumption. Pricing pressure stems from copper and aluminum commodity volatility compressing passive tag margins. Tier-one automotive procurement desks in Germany exhibit lowest price sensitivity due to unbundled contract vehicles, while mid-tier contract manufacturers under India's PLI scheme face acute cost constraints.
Supply Chain Analysis
CE marking and FDA 21 CFR Part 11 qualification requirements gate vendor access to European and North American pharmaceutical networks, elongating supplier onboarding timelines. Silicon wafer fabrication concentrates in Taiwan and South Korea, while antenna substrate production and label conversion cluster in China and Germany. Raw material dependencies include copper and aluminum for antenna substrates, silver flake conductive inks, and PET substrate films. Single-source vulnerability in East Asian foundry capacity for RAIN RFID endpoint ICs exposes lead times to geopolitical disruption. Distribution runs through tier-one automotive supplier procurement desks that unbundle hardware, software, and integration services into separate contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as automotive OEM consolidation and pharmaceutical regulatory mandates create durable replacement demand for RFID Kanban infrastructure.
For Market Incumbents: Anticipate real-time location system substitution in aerospace component tracking by deepening middleware capabilities for legacy MES integration. Co-locate technical support teams within Germany's automotive corridor to compress supplier qualification timelines. Invest in high-temperature label durability engineering to defend position against SATO's paint shop specialization. For New Entrants and Emerging Players: Cloud-based SaaS deployment routes offer lowest friction entry into India's PLI-driven electronics manufacturing corridors near Chennai and Noida. Target battery cell gigafactories in Europe and North America as greenfield white-space where electrolyte replenishment workflows lack incumbent lock-in. Pursue EU AI Act conformity certification as a service revenue stream for autonomous replenishment algorithm deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional systems integrators with captive relationships in Germany's automotive corridor but limited national scale. Long-term viability centers on middleware IP for SAP and Oracle MES integration rather than hardware commoditization. Watch for silicon supply disruption signals as inflection indicators for tag pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Platform Integration | SAP and Oracle MES bidirectional signal translation captures tier-one automotive procurement spend. |
| High-Temperature Label Durability Investment | Paint shop automation in Baden-Württemberg opens automotive coating processes to RFID deployment. |
| EU AI Act Conformity Certification | Autonomous replenishment algorithm validation creates recurring service revenue in smart factory deployments. |
| Co-Location of Technical Support | Proximity to Stuttgart and Wolfsburg compresses supplier qualification timelines for OEM consolidation. |
| Sensor-Integrated Tag Development | Temperature and humidity logging generates auditable EMA compliance records for Swiss pharmaceutical cold chain. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at automotive assembly facilities, procurement leads at tier-one supplier networks, RFID systems integrators, and pharmaceutical distribution center operations heads with secondary validation. Secondary sources included FDA Drug Supply Chain Security Act guidance documents, EU AI Act and Machinery Directive conformity frameworks, OSHA workplace safety inspection protocols, SEC 10-K filings from hardware vendors, and customs trade data for RFID component imports. Bottom-up tag volume modeling and top-down manufacturing automation spend analysis were triangulated against reported vendor shipments.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-recovery automation investment cycles. Segmentation dimensions modeled include technology tier, application workflow, end-user vertical, and deployment architecture plus integration complexity with legacy manufacturing execution systems. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU Green Deal circular economy packaging compliance deadlines and FDA lot-level electronic record mandate enforcement timelines.
Silicon supply disruption, metals commodity volatility, and real-time location system substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and automotive OEM consolidation pace. A model refresh is warranted upon material change in REACH substance restriction implementation timelines for adhesive binder reformulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Sample Storage Systems Market
Automation
Europe Marketing Automation Software Market
Automation
Global Water Automation and Instrumentation Market
Automation
Terminal Automation Systems Market
Automation
Cognitive Process Automation Market
Automation
Italy Marketing Automation Software Market
Automation
Global Warehouse Barcode System Market
Automation
Italy Marketing Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Indonesia Automation and Control System Market
Automation
Postal Automation System Market
Automation
Home Automation and Controls Market
Automation
Global Automated Liquid Handling System Market
Automation
Automation Light Grids Market
Automation
Automation-As-A-Service Market
Automation
Distributed Control System Market