
 Global Warehouse Barcode System Market | 2026-2036
Global Warehouse Barcode System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Warehouse Barcode System Market Outlook
Cloud-native inventory platforms is rewriting how warehouse operators orchestrate real-time data flows across distributed fulfillment networks. Zebra Technologies leverages its end-to-end hardware-software ecosystem to dominate enterprise-grade scanning deployments. Honeywell anchors its position through ruggedized mobile computing lines purpose-built for cold-chain logistics. Datalogic competes aggressively in European automated sorting hubs with vision-guided barcode reading systems.
A warehouse barcode system integrates optical data capture devices, encoding symbologies, and inventory management software to identify, track, and locate goods within storage and distribution facilities, typically operating at scan speeds exceeding 60 frames per second in high-throughput environments. Its primary commercial purpose is to eliminate manual data entry errors while enabling real-time inventory visibility across multi-node supply chains. Mobile Computing technology leads technology segment value pools because handheld terminals command premium pricing in labor-intensive picking operations. RFID is displacing traditional laser scanning in automated warehouse gates where line-of-sight constraints slow pallet throughput. E-Commerce end users represent the fastest-growing demand vertical as micro-fulfillment centers proliferate in urban peripheries.
The US Food and Drug Administration enforces serialization requirements under DSCSA that mandate unit-level traceability for pharmaceutical distribution, directly expanding barcode infrastructure investments. The European Union's CE marking framework and REACH chemical tracking obligations compel warehouse operators to maintain auditable chain-of-custody records through standardized barcode systems. China's SAMR enforces GB/T national standards for logistics information encoding that shape product design requirements for equipment vendors. Stakeholders must monitor how AI-driven computer vision is eroding the boundary between traditional barcode scanning and autonomous inventory counting systems.
Market Dynamics
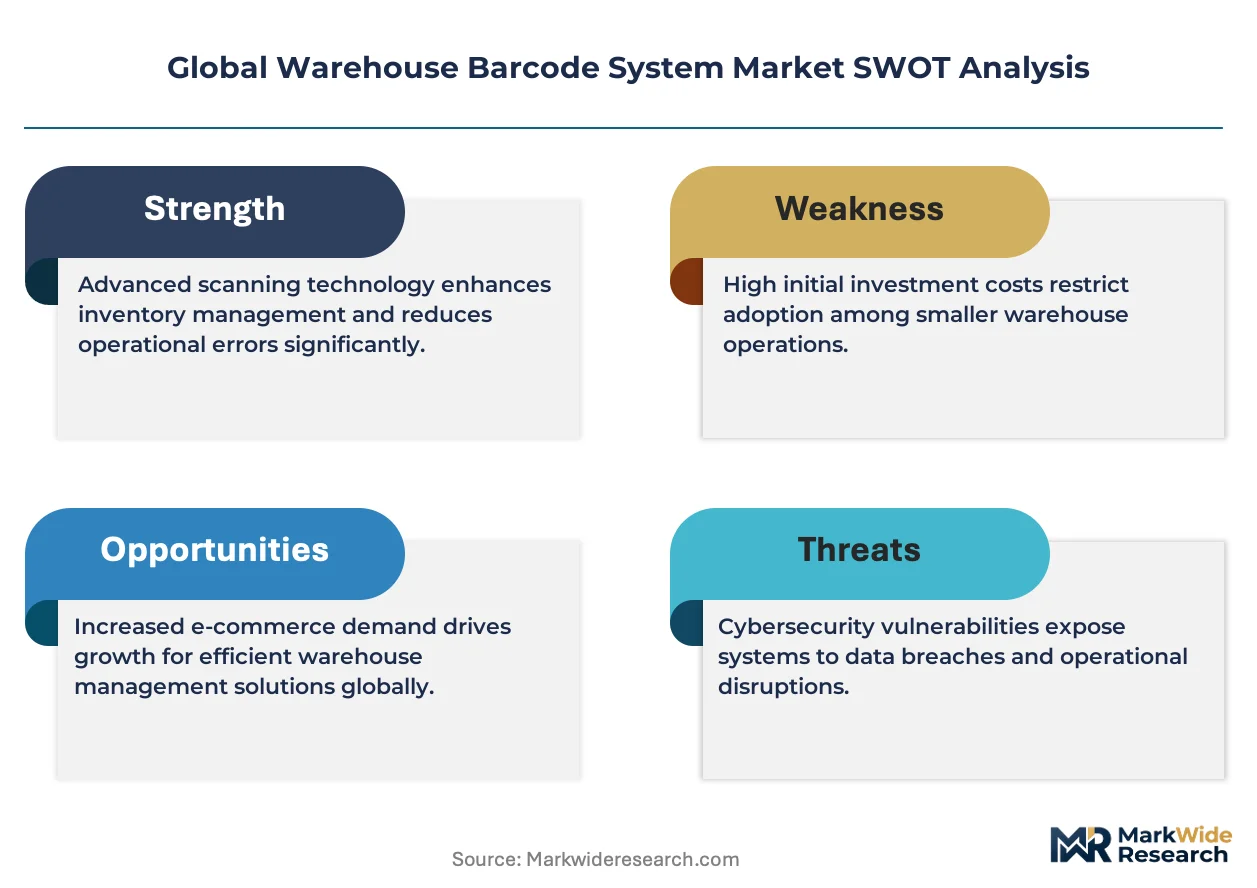
The collision of AI-driven computer vision with legacy laser scanning infrastructure is compressing technology refresh cycles across fulfillment networks. Warehouse operators face immediate pressure to reconcile capital-intensive hardware deployments against software-defined alternatives that promise autonomous inventory tracking without line-of-sight constraints.
Growth Catalysts
- DSCSA serialization mandates:The US FDA enforces unit-level pharmaceutical traceability that forces distributors to deploy enterprise-grade barcode infrastructure across every node of their cold-chain networks.
- Same-day delivery compression:E-commerce fulfillment centers in China's Yangtze River Delta corridor are tripling scan-point density to maintain throughput during peak seasonal surges.
- EU Digital Product Passport:This regulation demands interoperable traceability standards that push manufacturers toward standardized 2D symbologies and cloud-linked encoding systems.
Market Restraints
- Semiconductor supply concentration:Image sensor and processor fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risk.
- RFID tag cost floors:Passive ultra-high-frequency inlays remain uneconomical for single-use carton tracking below certain volume thresholds, limiting automated gate adoption.
- CE marking friction:European conformity assessment timelines for radio-enabled mobile computers extend hardware certification cycles and delay product launches.
Strategic Opportunities
- India logistics modernization:The country's PLI scheme for electronics manufacturing is attracting warehouse automation vendors to establish local assembly for cost-competitive regional supply.
- Vision-RFID convergence:Hybrid systems combining camera-based decoding with radio-frequency validation are opening new application spaces in pharmaceutical authentication.
- Micro-fulfillment urban penetration:Dark store operators in São Paulo and Mexico City are retrofitting compact vertical spaces with high-density scan tunnels for grocery rapid delivery.
Industry Challenges
- Legacy WMS integration:Decades-old warehouse management systems in North American third-party logistics require expensive middleware development to ingest real-time scan streams.
- Computer vision talent scarcity:The shortage of engineers skilled in optical character recognition and edge-AI deployment slows vendor product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Warehouse Barcode System Market |
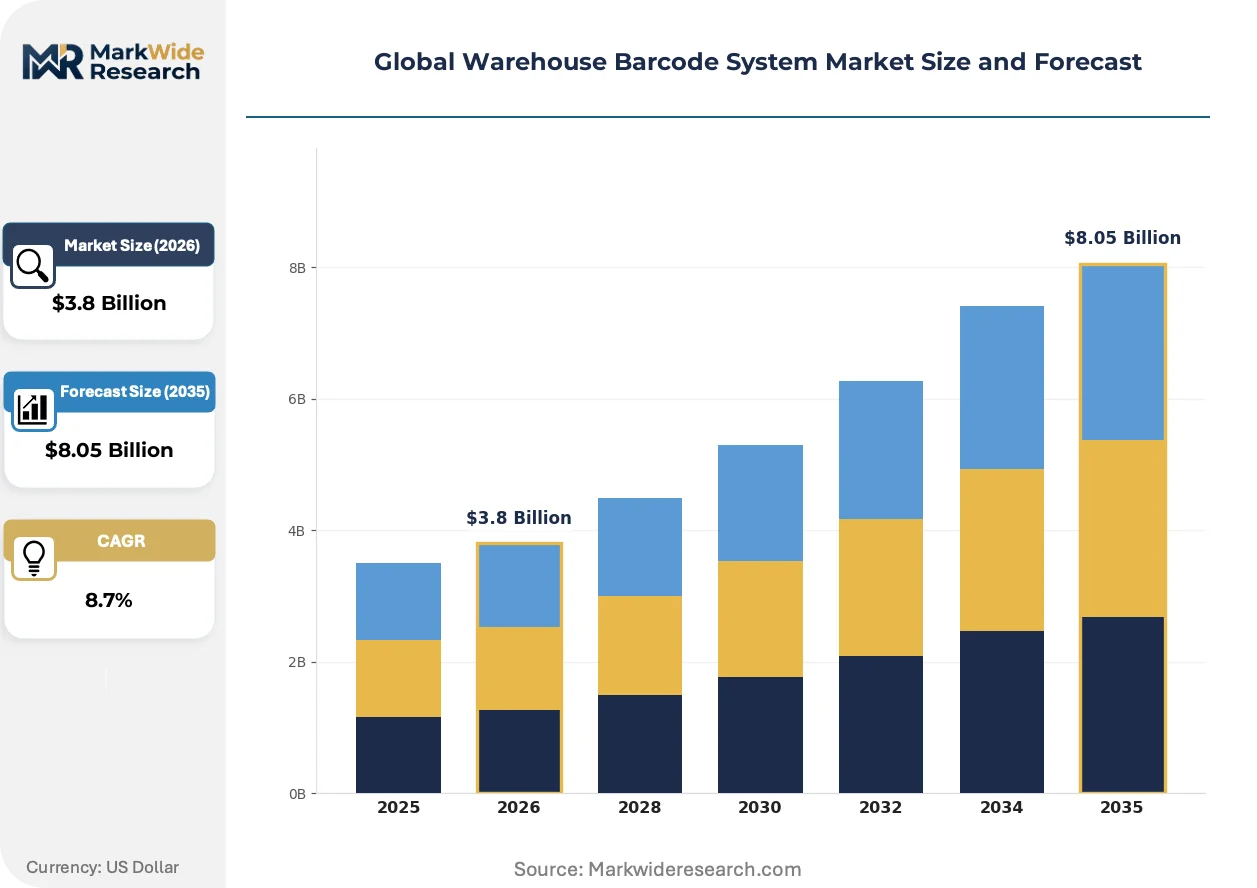
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Barcodes, QR Codes, UPC Codes, Code 39 Technology: Barcode Scanners, Mobile Computing, RFID, Software Solutions End User: Retail, Logistics, Manufacturing, E-Commerce Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Applications |
| Companies Covered | Zebra Technologies, Honeywell, Datalogic, SATO Holdings, Wasp Barcode Technologies, Cognex Corporation, TSC Auto ID Technology, Barcodes Inc., Code Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Warehouse Barcode System Market Strategic Shifts
Edge-AI inference engines are redrawing the boundary between hardware and software value capture in warehouse automation. This shift is fragmenting traditional vendor ecosystems and forcing new partnership configurations around data architecture.
Machine-learning-based decode algorithms are collapsing the performance gap between dedicated barcode scanners and general-purpose vision systems. Grocery micro-fulfillment operators in European urban peripheries are piloting camera-only inventory tunnels that eliminate moving laser components. This compression is enabling month-long rather than year-long deployment cycles for greenfield automation projects.
REACH chemical tracking obligations are mandating granular container-level traceability through European distribution hubs. The regulation forces warehouse operators to maintain auditable chain-of-custody records that link barcode scans to substance safety data sheets. Cold-chain pharmaceutical distributors in Germany and the Netherlands are responding by deploying temperature-logging scan handles that encode environmental data directly into 2D symbology.
Buyer procurement patterns are consolidating vendor relationships around integrated hardware-software-data platforms rather than point-product sourcing. Large third-party logistics providers in the United States are reducing their scanning equipment supplier rosters from six to two in favor of end-to-end ecosystem vendors. This concentration is visible most acutely in pharmaceutical distribution, where DSCSA compliance complexity favors single-vendor accountability for serialization validation.
Global Warehouse Barcode System Market Segmentation
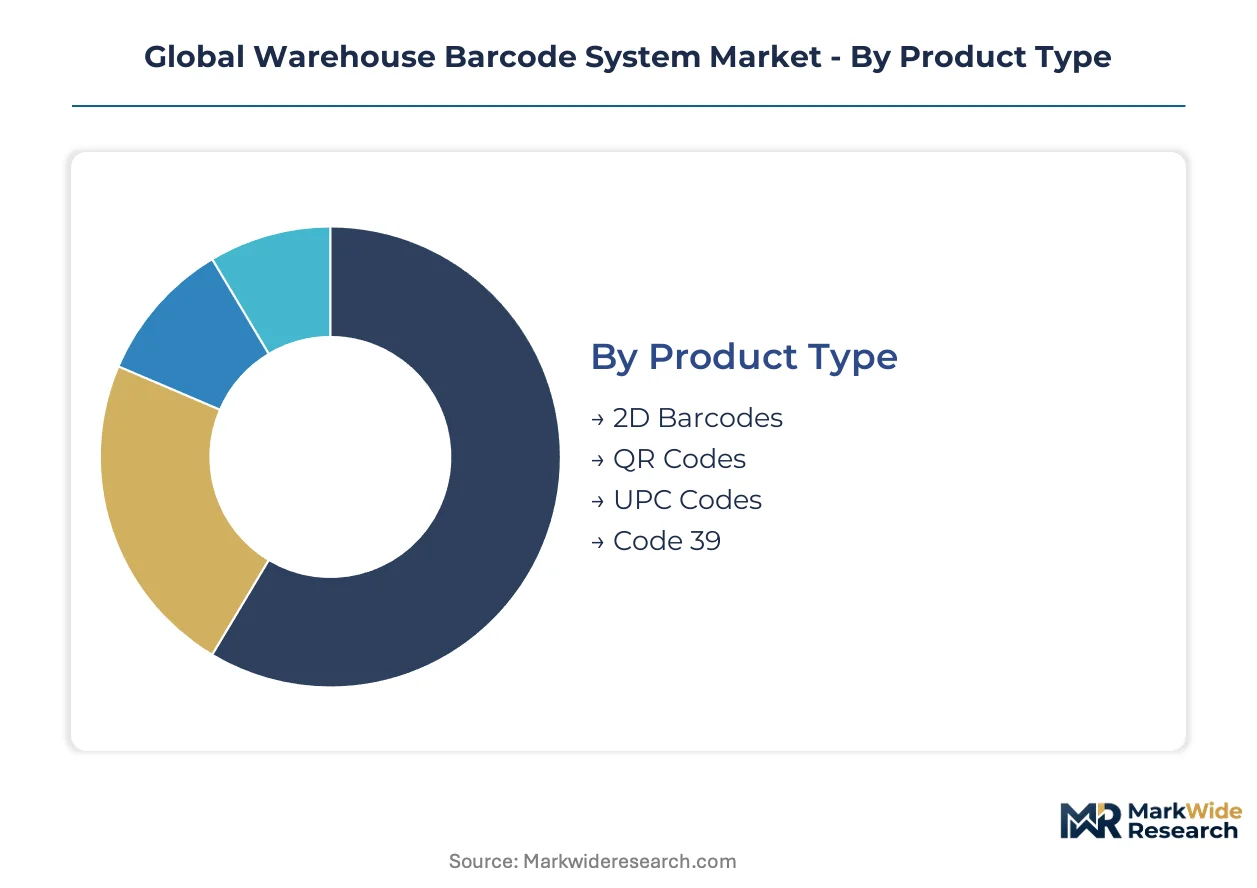
Warehouse barcode systems fragment across symbology standards, capture technologies, and deployment architectures that dictate integration complexity and capital intensity. Each segmentation axis reveals distinct buyer priorities—retailers optimize for checkout speed while pharmaceutical distributors prioritize serialization compliance.
Product Type:
Mature linear symbologies dominate legacy infrastructure while matrix codes expand in traceability-heavy verticals.
- 2D Barcodes:Data Matrix and PDF417 encode thousands of characters in compact footprints, enabling lot-level pharmaceutical serialization under FDA DSCSA mandates. Cold-chain distributors in Germany deploy these symbologies to embed temperature excursion data directly into scannable records.
- QR Codes:Open-standard encoding supports consumer-facing traceability and internal inventory workflows simultaneously. E-commerce fulfillment centers in China's Yangtze River Delta corridor leverage QR density for last-mile package routing.
- UPC Codes:Retail checkout infrastructure remains anchored to this linear standard.
- Code 39:Alphanumeric capability serves automotive and aerospace component tracking.
2D symbologies handle the majority of throughput; QR codes are the fastest mover on share.
Technology:
Hardware-software boundaries blur as edge-AI redefines value capture across the technology stack.
- Barcode Scanners:Laser and area-imaging engines achieve 60+ frames per second decode rates in high-velocity sortation tunnels. Automated parcel hubs in the Netherlands specify IP65-rated fixed-position scanners for 24/7 operational continuity.
- Mobile Computing:Ruggedized handheld terminals command premium pricing in labor-intensive picking operations. Third-party logistics providers consolidate procurement around Android-based devices with integrated imagers.
- RFID:Passive UHF inlays bypass line-of-sight constraints at automated warehouse gates.
- Software Solutions:Cloud-native WMS modules enable real-time inventory orchestration.
Mobile Computing anchors current revenue pools; RFID is climbing the fastest on deployment velocity.
End User:
Vertical-specific compliance regimes and throughput requirements shape technology selection patterns.
- E-Commerce:Micro-fulfillment centers in São Paulo and Mexico City retrofit compact vertical spaces with high-density scan tunnels to support rapid grocery delivery promises. Same-day delivery compression forces tripling of scan-point density during seasonal peaks.
- Logistics:Third-party operators face middleware complexity integrating real-time scan streams into decades-old WMS platforms across North American networks.
- Retail:Point-of-sale integration prioritizes sub-second decode reliability.
- Manufacturing:Work-in-process tracking demands industrial-grade durability ratings.
Logistics commands the largest installed base; E-Commerce shows the steepest expansion trajectory.
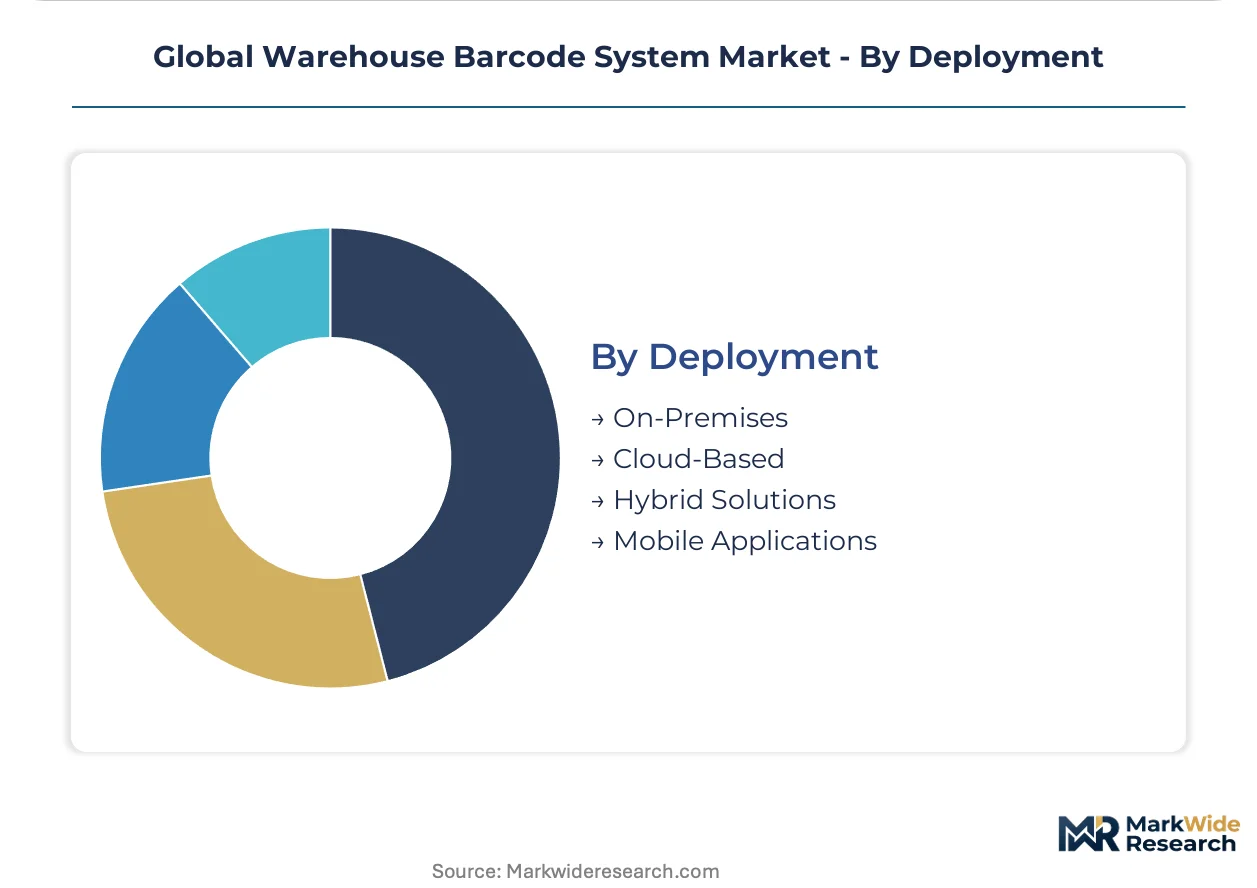
Deployment:
Architecture choices determine data sovereignty posture and integration timeline for warehouse operators.
- Cloud-Based:SaaS inventory platforms enable distributed fulfillment network orchestration without on-site server maintenance. European operators navigate GDPR data residency requirements when selecting hosting regions.
- Hybrid Solutions:Edge processing with cloud analytics balances latency-sensitive scan operations against centralized reporting needs.
- On-Premises:Air-gapped installations persist in defense and classified material handling.
- Mobile Applications:BYOD scanning extends barcode capability without dedicated hardware investment.
Hybrid Solutions absorb the most new project pipeline; Cloud-Based deployments are gaining share fastest among greenfield facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and e-commerce fulfillment operators concentrate procurement decisions in regulatory-heavy jurisdictions where serialization mandates and same-day delivery promises reshape infrastructure requirements.
United States
FDA DSCSA enforcement drives unit-level pharmaceutical traceability investments across cold-chain distribution networks. Third-party logistics providers consolidate scanning equipment supplier rosters from six to two vendors to simplify compliance accountability. Distribution hubs in New Jersey and Pennsylvania deploy temperature-logging scan handles encoding environmental data into 2D symbology.
Germany
REACH chemical tracking obligations mandate granular container-level traceability through distribution hubs. ECHA compliance frameworks force warehouse operators to maintain auditable chain-of-custody records linking barcode scans to substance safety data sheets. Automated parcel hubs in the Netherlands specify IP65-rated fixed-position scanners for 24/7 operational continuity, with German cold-chain operators following suit.
China
SAMR enforces GB/T national standards for logistics information encoding that shape product design requirements for equipment vendors. E-commerce fulfillment centers in the Yangtze River Delta corridor triple scan-point density to maintain throughput during peak seasonal surges. Smart warehouse investments accelerate across Shanghai and Jiangsu province logistics corridors.
India
PLI scheme incentives for electronics manufacturing attract warehouse automation vendors to establish local assembly for cost-competitive regional supply. CDSCO pharmaceutical traceability requirements expand in parallel with FDA-aligned serialization standards. Logistics modernization concentrates in Maharashtra and Gujarat industrial corridors.
Brazil
ANVISA pharmaceutical serialization mandates expand barcode infrastructure investments across distribution networks. Dark store operators in São Paulo retrofit compact vertical spaces with high-density scan tunnels for grocery rapid delivery. Micro-fulfillment penetration accelerates in urban peripheries alongside Mexico City deployments.
Global Warehouse Barcode System Market Competitive Environment
Channel-controlling players compete with product-specialist players across hardware-software-data platform bundles versus point-product sourcing. The vendor ecosystem consolidates around end-to-end ecosystem accountability as large third-party logistics providers reduce supplier rosters. Three archetypes dominate: integrated hardware-software vendors, ruggedized mobile computing specialists, and vision-guided automated sorting providers. Competitive moves center on M&A for technology portfolio expansion and strategic partnerships for cloud-native data architecture integration.
Within the integrated ecosystem tier, Zebra Technologies and Honeywell represent the dominant channel-controlling archetypes. Zebra Technologies anchors enterprise-grade scanning deployments through end-to-end hardware-software ecosystems. Honeywell occupies a position in ruggedized mobile computing purpose-built for cold-chain logistics. Datalogic exemplifies the vision-guided specialization archetype competing in European automated sorting hubs.
| Leading Market Players |
|---|
| Zebra Technologies |
| Honeywell |
| Datalogic |
| SATO Holdings |
| Wasp Barcode Technologies |
| Cognex Corporation |
| TSC Auto ID Technology |
| Barcodes Inc. |
| Code Corporation |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta logistics corridor anchors cost dynamics across the warehouse barcode system market, with freight rate volatility feeding directly into equipment pricing tiers and procurement consolidation patterns among third-party logistics operators.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate hardware procurement between original equipment manufacturers and enterprise distributors. Three-tier pricing structure across premium, standard, and economy levels separates ruggedized cold-chain terminals from consumer-grade scan engines and refurbished legacy units. Pricing pressure stems from RFID tag cost floors limiting automated gate adoption in mid-volume operations. Pharmaceutical distributors show least price sensitivity due to DSCSA compliance liability, while regional logistics operators in India and Brazil negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding imaging sensor assembly capacity across Taiwan, China, and Mexico. Image sensor fabrication draws from TSMC and Samsung foundries in Taiwan and South Korea, while laser diode production centers on Japanese and German component specialists. Single-source vulnerability in CMOS image sensor supply exposes hardware vendors to geopolitical disruption risk. Distribution runs through authorized distributor networks serving enterprise accounts alongside direct OEM relationships with large pharmaceutical and e-commerce fulfillment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warehouse barcode system market is entering a cyclical recovery phase as pharmaceutical serialization mandates and e-commerce fulfillment expansion drive replacement demand across mature installed bases.
For Market Incumbents: Build ecosystem lock-in moats by deepening software-hardware integration around cloud-native inventory platforms. Consolidate channel control through exclusive distribution partnerships with top-tier pharmaceutical distributors facing DSCSA compliance deadlines. Expand ruggedized mobile computing capacity in Mexico and Eastern Europe to capture nearshoring demand from North American logistics operators.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer underpenetrated white-space for cost-competitive scan engine assembly under PLI scheme incentives. Target mid-tier third-party logistics providers in Southeast Asia with Android-based handheld terminals bypassing legacy WMS integration complexity. Pursue white-label partnerships with established WMS vendors to accelerate channel access without direct sales infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with underoptimized barcode system divisions lacking cloud-native software capabilities. Long-term viability hinges on AI-driven computer vision integration displacing dedicated laser scanning hardware over the next decade. Monitor FDA enforcement actions on DSCSA unit-level traceability as inflection indicator for pharmaceutical infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Zebra Technologies and Honeywell are consolidating procurement relationships around end-to-end hardware-software-data ecosystems. |
| Vision-RFID Hybrid System Development | Datalogic and Cognex are capturing pharmaceutical authentication demand combining camera-based decoding with radio-frequency validation. |
| Geographic Manufacturing Footprint Expansion | PLI scheme incentives in India are attracting local assembly investments for cost-competitive regional supply. |
| Edge-AI Inference Engine Deployment | Machine-learning decode algorithms are collapsing performance gaps between dedicated scanners and general-purpose vision systems. |
| Temperature-Logging Hardware Certification | Cold-chain distributors in Germany and the Netherlands are embedding environmental data directly into 2D symbology for REACH compliance. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with warehouse operations directors, supply chain technology procurement leads, and pharmaceutical distribution compliance officers; and secondary validation through FDA DSCSA guidance documents, EU Digital Product Passport regulatory filings, SAMR GB/T standards publications, and SEC 10-K disclosures from publicly traded automation vendors. Bottom-up equipment shipment estimates triangulated against top-down fulfillment center capital expenditure surveys.
Forecast inputs span symbology type, capture technology, end-user vertical, and deployment architecture across the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by installed base turnover cycles and regulatory compliance deadlines. Model sensitivity tests incorporated RFID adoption curves, semiconductor supply constraints, and WMS modernization timelines.
Practitioners should monitor FDA enforcement intensity, EU Digital Product Passport implementation timelines, and Taiwan semiconductor supply disruptions for early signals of forecast revision. Quarterly review of pharmaceutical distributor capital expenditure announcements and e-commerce fulfillment center buildout permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Indonesia Automation and Control System Market
Automation
Europe Marketing Automation Software Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Global Field Force Automation Market
Automation
Global Database Automation Systems Market
Automation
North America Home Automation Systems Market
Automation
Middle East and Africa Workforce Management Market
Automation
Global Door and Window Automation Market
Automation
Laboratory Automation Market
Automation
Global Smart Vending Machines Market
Automation
Workload Scheduling and Automation Market
Automation
Workflow Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Digital Process Automation Market
Automation
Marketing Automation Solutions Market
Automation
Laboratory Benchtop Automation Market