
 Distributed Control System Market | 2026-2036
Distributed Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Control System Market Intelligence
Water treatment utilities are redrawing procurement priorities for distributed control systems as effluent compliance tightens across industrial zones. Emerson Electric leverages its DeltaV platform specialization to anchor positions in chemical processing retrofits. Yokogawa Electric sustains dominance across Asian power generation through CENTUM VP deployments. Siemens competes on digital twin integration with its PCS 7 architecture.
A distributed control system comprises geographically distributed controllers, sensors, actuators, and human machine interfaces linked via industrial communication networks to execute regulatory, sequential, and supervisory control strategies. These architectures process analog and digital I/O signals through redundant controller nodes operating at millisecond scan cycles to maintain continuous process stability in mission-critical infrastructure. Communication network segments command premium positioning as Ethernet-APL and time-sensitive networking protocols displace legacy fieldbus topologies. Supervisory control layers are expanding fastest where cloud-connected historians enable predictive analytics for plant operators.
IEC 61511 functional safety mandates and NIST cybersecurity frameworks compel energy producers to replace pre-2010 controller hardware. The EPA's effluent limitation guidelines drive water treatment operators toward automated DCS architectures with integrated compliance reporting. Plant operators and control system integrators must weigh open-architecture interoperability against vendor-locked lifecycle support when specifying next-generation distributed control investments.
Market Dynamics
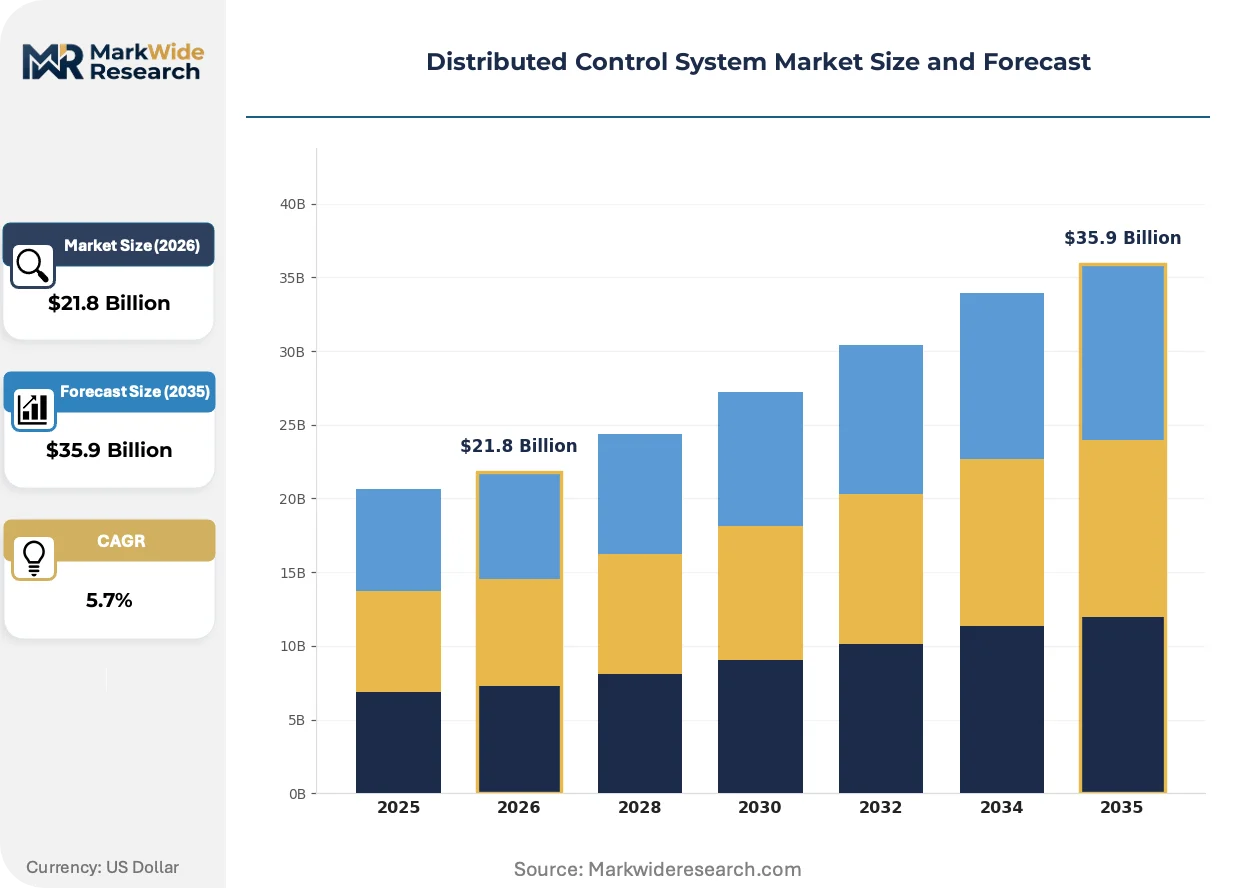
The IEC 61511 functional safety mandate and NIST cybersecurity framework are forcing wholesale replacement of pre-2010 controller hardware across energy and chemical processing infrastructure, compressing upgrade cycles from decade-long intervals to seven-year refresh schedules.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Water treatment operators in the United States must deploy automated DCS architectures with integrated compliance reporting, accelerating procurement for municipal utilities.
- German chemical processing clusters:Aging distributed control architectures in Ludwigshafen and Leverkusen drive replacement cycles for redundant controller nodes and Ethernet-APL migration.
- Time-sensitive networking protocols:IEEE 802.1 TSN standards displace legacy fieldbus topologies in power generation, enabling deterministic communication for supervisory control layers.
Market Restraints
- Controller hardware cost volatility:Semiconductor supply concentration in East Asia creates input cost instability for redundant processor modules and industrial Ethernet switches.
- Vendor-locked lifecycle support:Proprietary programming environments and spare part dependencies trap operators in single-source maintenance contracts spanning 15-20 year asset lives.
- Cybersecurity retrofit complexity:NIST SP 800-82 compliance for legacy installations requires complete network segmentation, multiplying engineering hours for brownfield deployments.
Strategic Opportunities
- Cloud-connected historian architectures:Predictive analytics integration creates new revenue streams for DCS vendors serving plant operators seeking operational intelligence layers.
- India's water infrastructure modernization:Central Electricity Authority mandates and smart city initiatives open procurement channels for supervisory control systems in municipal treatment plants.
- Ethernet-APL and wireless sensor convergence:Two-wire Ethernet for process automation combined with ISA100.11a wireless reduces cabling density in hazardous area installations.
Industry Challenges
- Functional safety engineer scarcity:TÜV-certified professionals capable of IEC 61511 SIL verification are concentrated among a handful of system integrators, extending project timelines.
- Legacy migration integration complexity:Hot-cutover procedures for replacing proprietary DCS architectures with open-standards platforms demand specialized commissioning expertise rarely available in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Control System Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $35.9 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
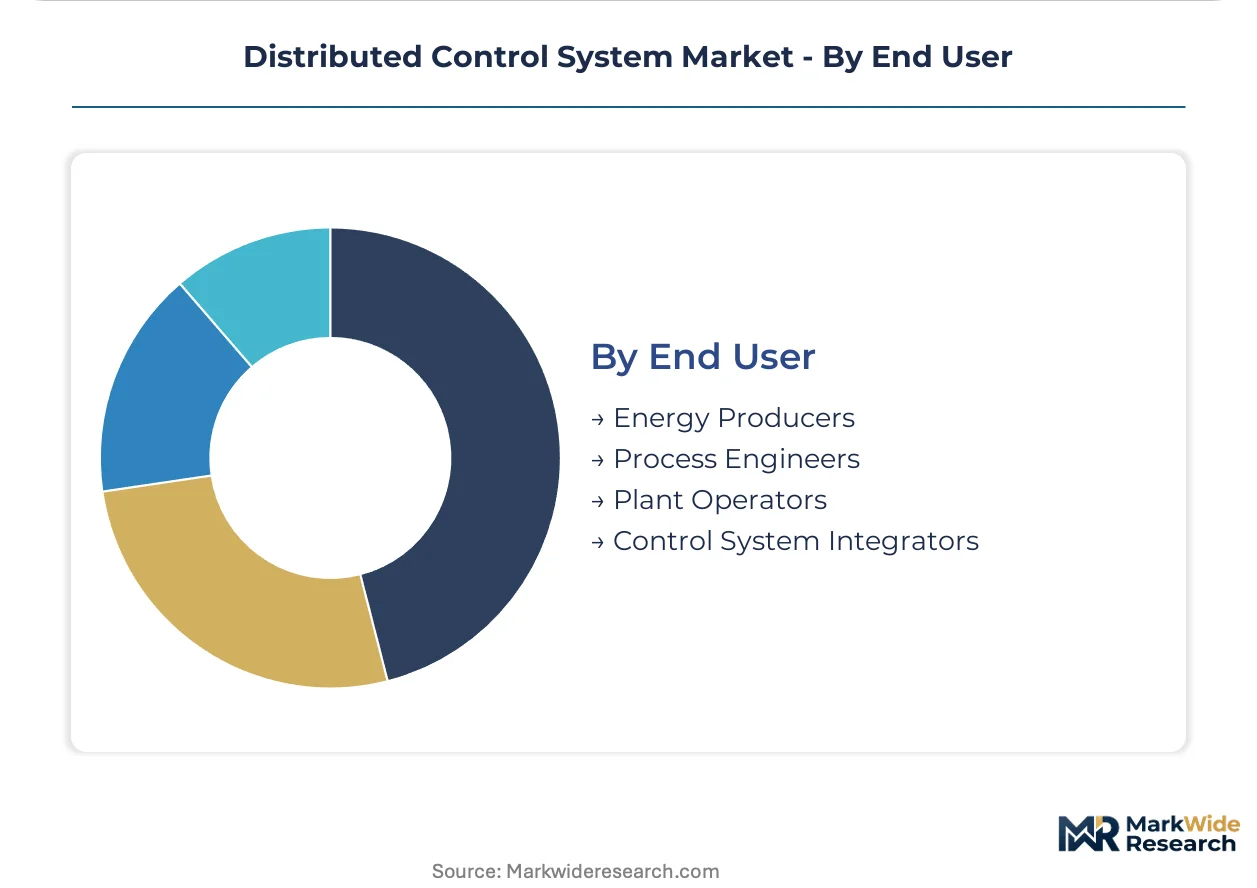
| Segmentation | Control Strategy: Sequential Control, Regulatory Control, Supervisory Control, Logic Control Component: Controllers, Sensors, Actuators, Human Machine Interface, Communication Network Application: Power Generation, Chemical Processing, Water Treatment, Food & Beverage Manufacturing End User: Energy Producers, Process Engineers, Plant Operators, Control System Integrators |
| Companies Covered | Emerson Electric, Yokogawa Electric, Siemens, Hitachi, Rockwell Automation, Schneider Electric, ABB, GE Vernova, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Control System Market Strategic Shifts & Innovations
Industrial communication hardware is miniaturizing while processing density increases, compressing controller footprints and enabling edge-deployed control strategies that bypass centralized server rooms entirely.
Ethernet-APL physical layer technology is miniaturizing field device connectivity from multi-cable fieldbus installations to single two-wire Ethernet runs carrying power and data. Chemical processors in Germany's Ruhr region are adopting APL switches at pace, replacing Foundation Fieldbus H1 segments. The structural consequence is that control system architecture is miniaturizing from hierarchical pyramid models to flattened mesh topologies with distributed intelligence.
The EPA's effluent limitation guidelines revision tightens discharge standards for industrial wastewater, mandating continuous monitoring and automated response capabilities. Power generation operators face capital allocation pressure to integrate compliance reporting directly into DCS historian databases. Water treatment facilities in the Ohio River Valley are responding by specifying DCS platforms with pre-validated environmental reporting modules.
Buyer preference is compressing toward outcome-based performance guarantees rather than capital equipment procurement. Chemical processing operators now contract for guaranteed uptime and regulatory compliance, transferring operational risk to system integrators. This contractual evolution is most visible in the US Gulf Coast petrochemical corridor, where integrated service agreements now dominate greenfield project awards.
Distributed Control System Market Segmentation

Distributed control system procurement flows through distinct technical specifications that determine integration complexity and lifecycle economics. Control strategy selection dictates hardware architecture, while component mix shapes vendor engagement models and service contract structures.
Control Strategy:
Channel mix varies sharply by control complexity—supervisory systems flow through system integrators, while regulatory control often ships direct to plant engineering teams.
- Supervisory Control:Hierarchical oversight layers coordinate multiple regulatory loops across distributed controller nodes, enabling plant-wide optimization. Demand concentrates in German chemical processing clusters where BASF and Covestro facilities require integrated batch management and compliance reporting.
- Regulatory Control:Continuous PID loops maintain process variables within tight tolerances through redundant analog I/O processing. US power generation operators deploy these architectures for turbine governor control following NERC reliability mandates.
- Sequential Control:State-machine logic executes ordered operations for batch reactors and material handling systems.
- Logic Control:Discrete binary operations manage interlocks and safety shutdowns in hazardous area installations.
Supervisory control dominates installed base. Regulatory control is where expansion concentrates.
Component:
Margin profiles diverge by component type—controllers and HMI software carry premium pricing, while sensors and actuators compete on volume throughput.
- Communication Network:Industrial Ethernet switches and time-sensitive networking infrastructure enable deterministic data exchange between distributed nodes. India's municipal water utilities prioritize these investments under CEA smart grid directives, replacing legacy Modbus and Profibus segments.
- Controllers:Redundant processor modules execute millisecond scan cycles with SIL-rated safety integrity. Japanese power producers favor these for nuclear turbine protection systems under METI operational guidelines.
- Human Machine Interface:Operator workstations and mobile visualization platforms consolidate alarm management and trend analysis.
- Sensors:Temperature, pressure, and flow transmitters feed analog signals to controller I/O modules.
- Actuators:Final control elements modulate valve positions and motor drives based on controller output signals.
Controllers anchor vendor profitability. Communication networks are climbing the fastest.
Application:
Application mix determines specification rigor—chemical processing demands SIL certification, while food manufacturing prioritizes hygienic design standards.
- Chemical Processing:Batch reactor control and hazardous area instrumentation require explosion-proof enclosures and integrated safety systems. German facilities in Ludwigshafen drive replacement demand as IEC 61511 mandates force pre-2010 hardware retirement.
- Water Treatment:Continuous effluent monitoring and automated chemical dosing respond to tightening discharge regulations. US operators face EPA limitation guidelines requiring automated compliance reporting integrated into DCS historians.
- Power Generation:Turbine control and emissions monitoring systems balance efficiency with grid stability requirements.
- Food & Beverage Manufacturing:CIP/SIP cycle control and recipe management systems enforce batch consistency and traceability.
Chemical processing commands premium pricing. Water treatment is gaining share fastest.
End User:
Procurement authority varies by end user type—energy producers centralize capital decisions, while control system integrators influence technical specifications.
- Control System Integrators:Third-party engineering firms specify multi-vendor architectures and execute commissioning for brownfield migrations. These actors concentrate in Texas and Louisiana, serving Gulf Coast petrochemical operators with integrated service agreements spanning 15-year asset lives.
- Energy Producers:Utility and independent power plant operators prioritize uptime guarantees and cybersecurity compliance over capital cost minimization.
- Process Engineers:In-house technical staff define functional specifications and validate control loop performance.
- Plant Operators:Frontline personnel influence HMI usability requirements and alarm rationalization priorities.
Control system integrators intermediate the largest contract values. Energy producers drive steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller module fabrication concentrates in Germany, Japan, and the United States, with final assembly and system integration distributed across industrial clusters in China and India. Semiconductor supply bottlenecks in East Asia create input cost volatility that ripples through procurement cycles in European chemical processing and North American power generation.
United States
EPA effluent limitation guidelines compel water treatment operators in the Ohio River Valley to deploy automated DCS architectures with integrated compliance reporting. NERC reliability mandates drive turbine governor control upgrades across independent power producers. Gulf Coast petrochemical corridors in Texas and Louisiana dominate integrated service agreement contracting for brownfield migrations.
Germany
IEC 61511 functional safety mandates force pre-2010 hardware retirement across BASF and Covestro facilities in Ludwigshafen and Leverkusen. The country's chemical processing clusters anchor European demand for redundant controller nodes and Ethernet-APL migration. Ruhr region processors are adopting APL switches at pace, replacing Foundation Fieldbus H1 segments.
China
Central Electricity Authority smart grid directives prioritize industrial Ethernet switch investments for municipal water utilities replacing legacy Modbus segments. MIIT operational guidelines shape nuclear turbine protection system specifications. Yangtze River Delta manufacturing bases are expanding domestic controller module production to reduce import dependency.
India
CEA mandates and smart city initiatives open procurement channels for supervisory control systems in municipal treatment plants across Maharashtra and Gujarat. The country's national power regulator is tightening grid stability requirements that drive turbine control investments. Bangalore and Hyderabad clusters are emerging as system integration hubs serving Southeast Asian export markets.
Japan
METI operational guidelines govern nuclear turbine protection system deployments requiring SIL-rated safety integrity. Japanese power producers favor redundant processor modules for mission-critical infrastructure. Osaka and Nagoya industrial zones sustain dense concentrations of control system engineering expertise for Asia-Pacific project execution.
Distributed Control System Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing captive semiconductor sourcing and multi-decade service infrastructures. The vendor base stratifies across three tiers: full-stack automation houses with integrated safety portfolios, specialized DCS architects with deep process industry expertise, and emerging Asian system integrators competing on commissioning cost. Dominant competitive moves include backward integration into industrial Ethernet switch fabrication and outcome-based service contracting that transfers operational risk from plant operators to vendors.
Within the full-stack tier, Emerson Electric and Yokogawa Electric exemplify divergent geographic anchoring strategies. Emerson occupies a position shaped by DeltaV platform specialization in North American chemical processing retrofits. Yokogawa represents the Asia-centric archetype, with CENTUM VP deployments concentrated in Japanese and Southeast Asian power generation. Siemens sits within the European industrial conglomerate model, competing on digital twin integration with its PCS 7 architecture across German chemical clusters.
| Leading Market Players |
|---|
| Emerson Electric |
| Yokogawa Electric |
| Siemens |
| Hitachi |
| Rockwell Automation |
| Schneider Electric |
| ABB |
| GE Vernova |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Long-term integrated service agreements lock in both supply access and price visibility for DCS deployments, binding plant operators to 15-20 year lifecycle contracts with single-source vendors while insulating procurement teams from semiconductor cost volatility. These contractual structures concentrate pricing power with full-stack automation houses that control captive controller module production.
Pricing Analysis
Volume-discount tiering structures separate SIL-certified safety systems from standard regulatory control packages, with premium pricing attached to TÜV-verified configurations and integrated cybersecurity modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Cost compression in economy-tier controller hardware is intensifying because East Asian semiconductor supply concentration feeds input price instability. Municipal water utilities exhibit highest price sensitivity due to constrained capital budgets, while German chemical processors prioritize uptime guarantees over capital cost minimization.
Supply Chain Analysis
Inbound logistics costs from East Asian semiconductor hubs through Rotterdam and Long Beach port complexes create working capital pressure for European and North American system integrators. Controller module fabrication concentrates in Germany, Japan, and the United States, with redundant processor chips drawing from Taiwan and South Korean foundry capacity. Supply chain risk centers on single-source vulnerability for industrial Ethernet switch ASICs. Distribution runs through authorized system integrator networks that execute commissioning and lifecycle support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DCS procurement is shifting toward platform-economics logic where interoperability standards and open-architecture commitments determine vendor selection, driven by IEC 62443 cybersecurity certification requirements that favor ecosystem breadth over proprietary depth.
For Market Incumbents: Fortify positions through backward integration into industrial Ethernet switch fabrication and captive semiconductor sourcing for redundant processor modules. Emerging Asian system integrators competing on commissioning cost threaten margin structures in Southeast Asian power generation deployments. Certification investment in IEC 62443 SL3 cybersecurity tiers creates switching costs that bind plant operators to established vendor ecosystems. For New Entrants and Emerging Players: Differentiate on rapid brownfield migration capabilities and hot-cutover execution speed where TÜV-certified functional safety engineer scarcity extends incumbent project timelines. India's municipal water infrastructure modernization under CEA smart city directives represents the most penetrable geography, with procurement channels opening for supervisory control systems in Maharashtra and Gujarat treatment plants. Target outcome-based performance contracting that transfers operational risk from plant operators to system integrators. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors vendors with integrated safety portfolios and multi-decade service infrastructures. Long-term viability hinges on positioning for seven-year hardware refresh schedules compressed from decade-long intervals by IEC 61511 mandates. Acquisition target archetype: specialized DCS architects with deep process industry expertise and established relationships in German chemical clusters. Signal to watch: Ethernet-APL adoption velocity in Foundation Fieldbus replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Switch Fabrication | Captive industrial Ethernet production insulates margin structures from East Asian semiconductor volatility. |
| Outcome-Based Service Contracting | Integrated service agreements transfer operational risk and lock in 15-year revenue visibility. |
| IEC 62443 Cybersecurity Certification | SL3-tier certification creates switching costs that favor ecosystem breadth over proprietary architectures. |
| Ethernet-APL Migration Programs | Two-wire Ethernet adoption in German Ruhr chemical clusters displaces legacy Foundation Fieldbus installations. |
| Cloud-Connected Historian Architectures | Predictive analytics integration opens recurring revenue streams beyond capital equipment sales. |
Research Approach
A standing panel of control system integrators, plant engineering directors, and industrial cybersecurity specialists provided ongoing calibration across primary interview programs and secondary validation cycles. Input combined direct engagement with procurement leads at German chemical processors and US municipal utilities with trade data from IEC and NIST documentation repositories, SEC filings of listed automation vendors, and customs records of industrial Ethernet switch imports. Bottom-up project pipeline tracking and top-down macroeconomic factor weighting enabled cross-verification of volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning control strategy complexity, component hardware type, application vertical, and end-user procurement authority. CAGRs were derived from fitted growth curves applied to verified baseline installations, with inputs including EPA effluent guideline revision timelines and METI nuclear operational directive schedules.
Material uncertainties — semiconductor supply disruption, regulatory standard revision timing, and functional safety engineer availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about replacement cycle compression and Ethernet-APL adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
US Workload Scheduling and Automation Market
Automation
Europe Laboratory Automation Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Automatic Message Handling System Market
Automation
Italy Marketing Automation Market
Automation
Automation Lifecycle Services Market
Automation
Automated Cell Block Systems Market
Automation
Network Automation Market
Automation
Industrial Vending Machines Market
Automation
Elevator Control Market
Automation
Hyperautomation Market
Automation
Distribution Automation Solutions Market
Automation
Escalator Control Systems Market
Automation
Automation-As-A-Service Market
Automation
RFID Kanban Systems Market
Automation
Recruiting Automation Software Market