
 Global IoT Routers Market | 2026-2036
Global IoT Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Routers Market Outlook
Industrial-grade specifications is rotating toward the center of procurement decisions as enterprises prioritize reliability over consumer-grade alternatives. Cradlepoint, Inc leverages its cloud-managed architecture to dominate North American transportation deployments. Cisco sustains channel control through certified partner programs targeting smart building integrators. Teltonika anchors European manufacturing demand with DIN-rail designs purpose-built for factory floors.
IoT routers are network gateway devices engineered with embedded cellular modems, dual-band Wi-Fi chipsets, and operating temperature tolerances spanning negative forty to positive seventy degrees Celsius, purpose-built to aggregate sensor traffic and transmit it securely to cloud or edge platforms. The 5G routers segment leads value generation as telecom operators release private network spectrum to industrial buyers. LPWAN routers represent the fastest-growing product type for agricultural and utility metering applications where ultra-low power budgets override bandwidth requirements.
The FCC in the United States certifies radio frequency emissions for cellular and Wi-Fi variants, while the EU Cyber Resilience Act imposes mandatory vulnerability disclosure and secure-by-default configurations on devices sold within member states. Japan's METI enforces JIS standards for electromagnetic compatibility in factory environments. Stakeholders must monitor spectrum allocation decisions by national regulators and align product roadmaps with emerging zero-trust architecture mandates before certification requirements harden.
Market Dynamics
Private 5G spectrum releases by national regulators are fragmenting procurement patterns as industrial buyers bypass traditional carrier contracts for direct network ownership.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory secure-by-default configurations and vulnerability disclosure timelines are forcing hardware vendors to embed security at the chipset level, accelerating replacement cycles for legacy deployments.
- Factory digitization clusters:Germany's Ruhr industrial corridor is consuming ruggedized cellular gateways for predictive maintenance networks, pulling demand for IP67-rated DIN-rail designs.
- Private 5G licensing:National spectrum authorities in Japan, the United States, and Germany are releasing localized frequency blocks that enable enterprises to operate captive networks without carrier intermediation.
Market Restraints
- Semiconductor supply concentration:Cellular modem fabrication depends on a limited number of advanced foundry nodes concentrated in Taiwan and South Korea, creating single-source exposure for industrial-grade chipsets.
- RF certification complexity:FCC Part 15 and EU RED compliance timelines extend 8-14 months per SKU, freezing product roadmaps and delaying revenue recognition for multi-band variants.
- LPWAN substitution pressure:Unlicensed LoRa and Sigfox networks are capturing agricultural and utility metering applications where bandwidth requirements remain below 50 kbps.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for telecom equipment production are attracting contract manufacturers to establish router assembly capacity for domestic and export markets.
- Edge-AI convergence:Integration of TensorFlow Lite runtimes and GPU-accelerated inference engines into gateway hardware is opening machine-vision and acoustic-monitoring applications at the network edge.
- Direct-to-enterprise distribution:Bypassing systems integrators through cloud-managed provisioning platforms is compressing channel margins and capturing customer data for aftermarket services.
Industry Challenges
- Embedded systems security engineering:Firmware signing, secure boot implementation, and side-channel attack mitigation require specialized talent pools concentrated in Israel, Estonia, and select US defense corridors.
- Legacy SCADA integration:Protocol translation between Modbus, Profinet, and modern MQTT stacks demands custom middleware development that extends deployment timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Routers Market |
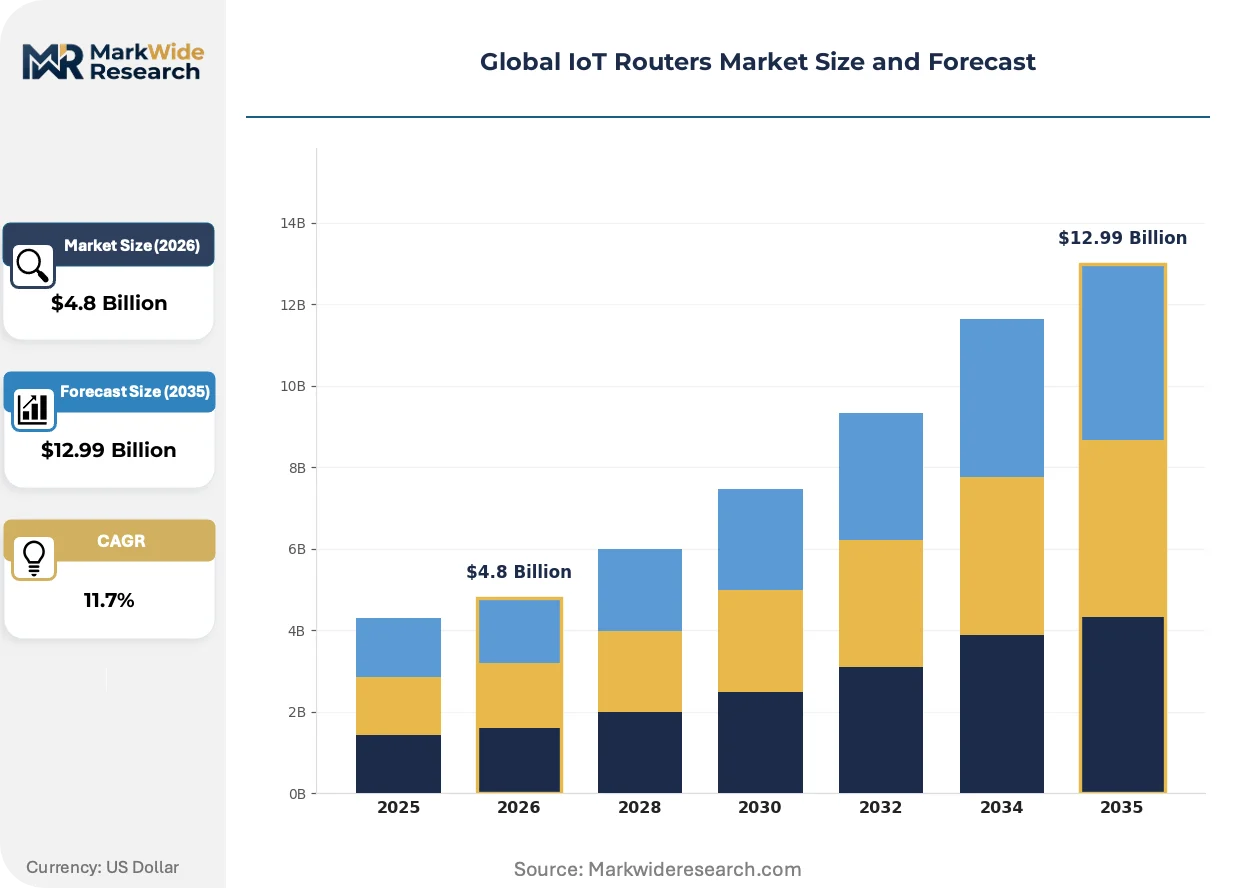
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5G Routers, 4G Routers, Wi-Fi Routers, LPWAN Routers Technology: Cellular, Wi-Fi, Zigbee, Bluetooth End User: Smart Home, Industrial Automation, Healthcare, Transportation Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | MTX (Flexitron Group), Cradlepoint, Inc, Cisco, Huawei, Teltonika, Ursalink Technology Co., Ltd, Shen Zhen azroad Technology Co., Ltd, Xiamen Baima Technology Co., Ltd, Robustel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
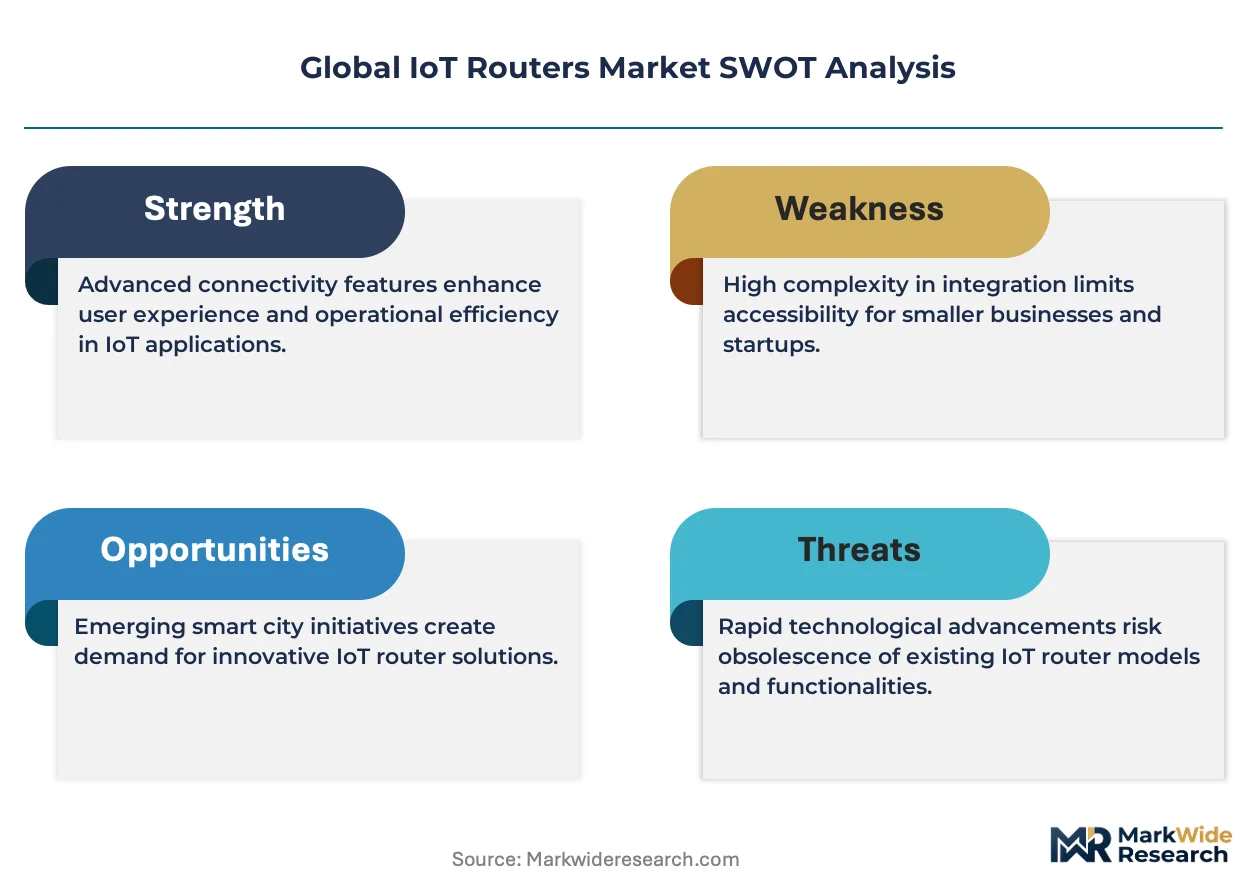
Global IoT Routers Market Strategic Shifts
Hardware architectures are unbundling from monolithic designs as software-defined radio and containerized networking stacks enable function-specific optimization.
Software-defined radio (SDR) platforms are replacing fixed-modem designs in enterprise gateways. Transportation fleets and mobile industrial equipment deploy SDR-based routers to switch between cellular generations without hardware swaps. This flexibility is decomposing the traditional SKU proliferation model that tied vendors to carrier-specific certification cycles.
Japan's METI has tightened electromagnetic compatibility standards for factory-floor equipment under revised JIS C 61000 provisions. Router vendors must now demonstrate immunity to arc-welding interference and variable-frequency drive noise. Automotive and heavy-machinery suppliers in Nagoya and Osaka industrial zones are demanding pre-certified designs to avoid production-line validation delays.
Buyer organizations are consolidating vendor relationships around cloud-native management platforms that unify cellular, Wi-Fi, and Ethernet policy control. Systems integrators and industrial distributors lose attach revenue as enterprises self-provision through web interfaces. This disintermediation is most advanced in North American smart building deployments where facilities teams bypass traditional AV integrators for direct procurement.
Global IoT Routers Market Segmentation
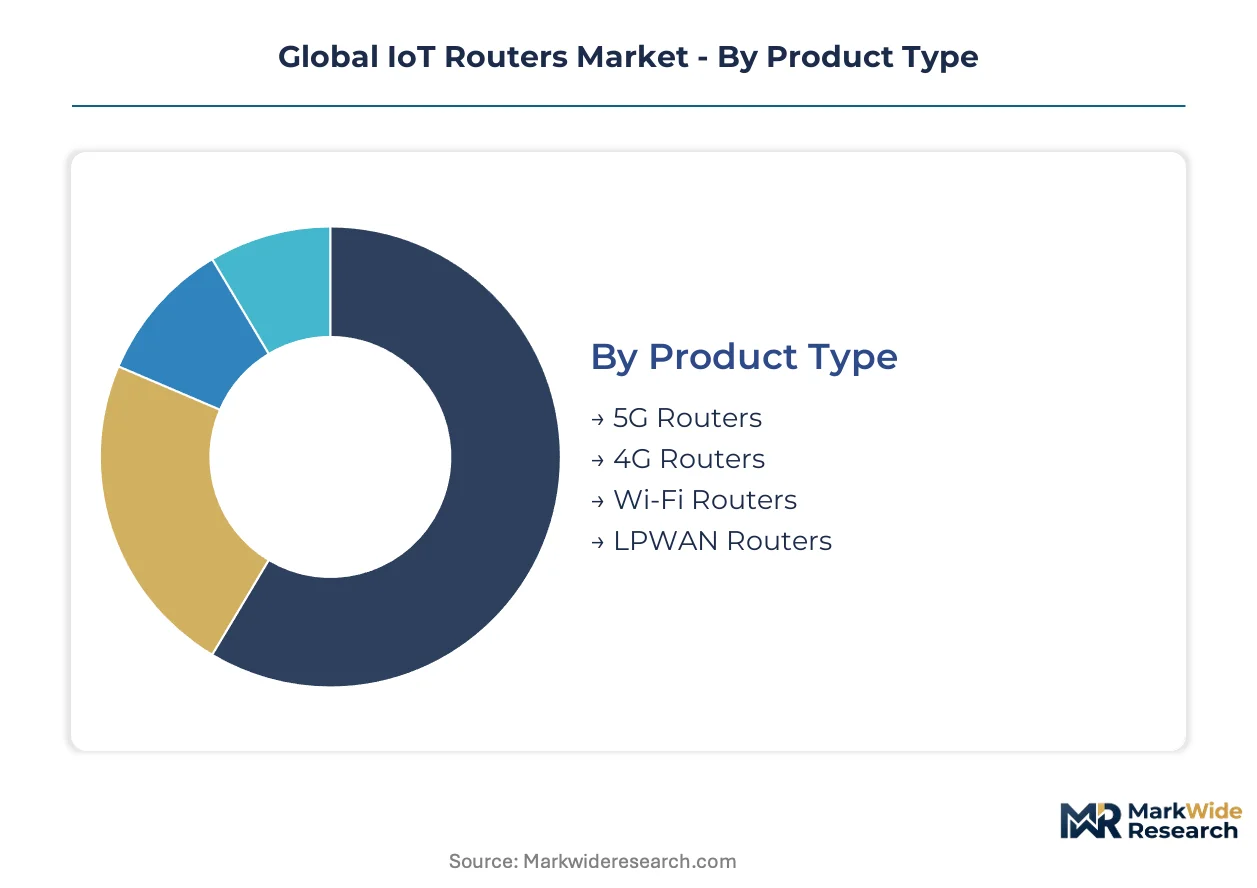
IoT router procurement patterns diverge sharply across product tiers and deployment contexts. Cellular variants command premium positioning in industrial corridors while Wi-Fi and LPWAN alternatives capture volume in consumer and agricultural settings.
Product Type:
Export demand concentrates in 5G and LPWAN variants where German and Japanese industrial buyers drive certification-heavy procurement. Domestic markets absorb higher volumes of 4G and Wi-Fi units through retail channels.
- 5G Routers:These gateways embed millimeter-wave and sub-6 GHz modems with private network slicing capabilities. Demand clusters in Japan's Nagoya automotive belt and Germany's Ruhr corridor where factory operators purchase captive spectrum blocks. METI's tightened JIS C 61000 electromagnetic compatibility standards now mandate arc-welding immunity pre-certification.
- LPWAN Routers:Ultra-low power designs operate on unlicensed sub-gigahertz bands with decade-long battery autonomy. Agricultural cooperatives in France and utility operators in India deploy these for soil moisture and smart metering networks where bandwidth requirements stay below 50 kbps. India's PLI scheme subsidies are attracting contract manufacturers to establish assembly capacity for domestic and Southeast Asian export markets.
- 4G Routers:LTE Category 4 and Category 6 modems dominate transportation fleet deployments across North American logistics corridors.
- Wi-Fi Routers:Dual-band 802.11ax designs serve smart home deployments in suburban United States markets with hardware refresh cycles accelerating.
5G Routers holds the largest share; momentum sits with LPWAN Routers.
Technology:
Cellular technologies absorb the majority of industrial procurement spend while short-range protocols capture cost-sensitive consumer installations.
- Cellular:Embedded modems with eSIM provisioning enable cross-carrier failover without physical SIM swaps. Factory digitization in Germany and transportation fleets in the United States drive demand for ruggedized designs with negative forty to positive seventy degree Celsius operating ranges.
- Wi-Fi:2.4 GHz and 5 GHz chipsets with WPA3 enterprise authentication serve smart building integrators. North American facilities teams increasingly self-provision through cloud-managed platforms, bypassing traditional AV integrators.
- Zigbee:Mesh networking at 2.4 GHz dominates smart home lighting and climate control ecosystems.
- Bluetooth:Low Energy 5.2 implementations support asset tracking and proximity-based access control in healthcare facilities.
Cellular commands the revenue base; Bluetooth is climbing the fastest on healthcare asset tracking demand.
End User:
Industrial Automation and Smart Home deployments operate on fundamentally different procurement cycles, with the former requiring eighteen-month validation timelines and the latter refreshing hardware every thirty-six months.
- Industrial Automation:DIN-rail mounted gateways with IP67 ingress protection aggregate Modbus and Profinet traffic for cloud translation. Germany's industrial corridor consumes the majority of European volume, with protocol translation middleware extending deployment timelines by four to six months.
- Smart Home:Consumer-grade mesh systems with smartphone provisioning dominate North American suburban markets. FCC Part 15 certification timelines constrain product roadmaps for multi-band variants.
- Healthcare:HIPAA-compliant designs with hardware security modules protect patient data streams in hospital networks.
- Transportation:Mobile gateways with GPS dead reckoning and dual-modem failover serve fleet management platforms across United States interstate corridors.
Industrial Automation generates the highest average selling prices; Smart Home delivers the unit volume.
Deployment:
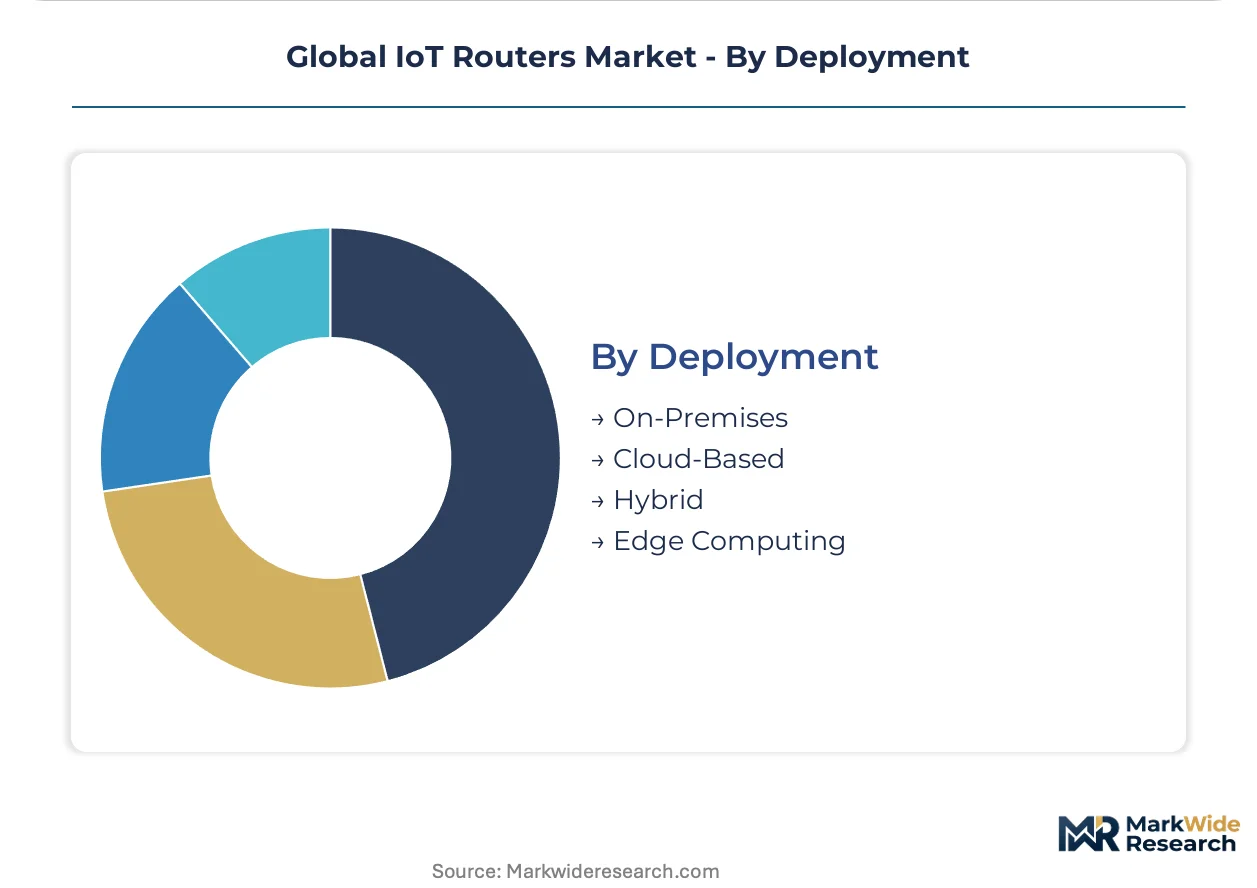
Edge Computing and Hybrid architectures are displacing pure cloud configurations as enterprises process machine-vision and acoustic data locally.
- Edge Computing:TensorFlow Lite runtimes and GPU-accelerated inference engines enable real-time anomaly detection without cloud round-trips. Japanese automotive suppliers in Osaka industrial zones demand pre-certified designs to avoid production-line validation delays.
- Hybrid:Policy-orchestrated splits between local inference and cloud training optimize bandwidth costs. German factory operators favor this model for predictive maintenance networks.
- On-Premises:Air-gapped configurations serve defense and critical infrastructure buyers with zero-trust mandates.
- Cloud-Based:Fully managed SaaS provisioning appeals to mid-market smart building operators without dedicated IT security staff.
Hybrid deployments anchor current infrastructure spend; Edge Computing is expanding most quickly on AI convergence demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Taiwan and South Korean foundries feed assembly operations across Germany, the United States, and Japan, creating a three-legged trade structure where finished routers return to Asian markets for smart city deployments. Import dependency for cellular modems concentrates risk in specific coastal manufacturing zones. Regional procurement patterns diverge sharply between industrial buyers seeking captive 5G spectrum and consumer markets refreshing Wi-Fi hardware on shorter cycles.
United States
Transportation fleets across interstate logistics corridors consume ruggedized LTE gateways with GPS dead reckoning capabilities. FCC Part 15 certification timelines extend eight to fourteen months per multi-band SKU, freezing vendor product roadmaps. Smart building integrators in suburban markets accelerate hardware refresh cycles for dual-band Wi-Fi mesh systems.
Germany
Factory digitization in the Ruhr industrial corridor pulls demand for IP67-rated DIN-rail cellular gateways with Modbus protocol translation. The EU Cyber Resilience Act mandates secure-by-default configurations and vulnerability disclosure timelines for all connected devices sold within member states. Automotive suppliers in Stuttgart industrial zones require pre-certified designs to avoid production-line validation delays.
Japan
METI's revised JIS C 61000 electromagnetic compatibility standards now mandate arc-welding immunity and variable-frequency drive noise resistance for factory-floor equipment. Nagoya automotive belt manufacturers purchase captive 5G spectrum blocks for private network slicing. Osaka industrial zones demand edge-AI convergence with TensorFlow Lite runtimes for real-time anomaly detection.
China
MIIT governs radio frequency allocations for cellular and Wi-Fi variants while GB standards enforce electromagnetic compatibility in industrial environments. Yangtze River Delta manufacturing hubs assemble router hardware for domestic smart city deployments and Southeast Asian export markets. Contract manufacturers leverage scale economics for LPWAN gateway production serving agricultural cooperatives.
India
PLI scheme subsidies for telecom equipment production attract contract manufacturers to establish router assembly capacity for domestic consumption and regional export. TRAI spectrum allocation decisions shape private network deployment timelines for industrial buyers. Utility operators deploy LPWAN routers for smart metering networks where bandwidth requirements remain below fifty kilobits per second.
Global IoT Routers Market Competitive Environment
Listed leaders compete with private specialists across capital access and R&D velocity, creating a tiered structure where scale advantages clash with niche customization capabilities. Publicly traded vendors leverage balance sheet capacity for certification-heavy 5G development while private operators optimize for specific industrial verticals. Three archetypes dominate: cloud-managed platform providers, ruggedized hardware specialists, and contract manufacturing scale players. Competitive moves concentrate on strategic partnerships for spectrum access and portfolio diversification into edge-AI convergence.
Among United States-based vendors, Cradlepoint, Inc and Cisco exemplify distinct positioning archetypes within the cellular gateway segment. Cradlepoint represents the cloud-native management platform approach, while Cisco occupies a position anchored in certified partner channel control. Teltonika, a Lithuania-based private limited company, anchors European manufacturing demand with purpose-built industrial designs. These three entities collectively illustrate the geographic and strategic segmentation governing procurement decisions across North American transportation and European factory automation verticals.
| Leading Market Players |
|---|
| MTX (Flexitron Group) |
| Cradlepoint, Inc |
| Cisco |
| Huawei |
| Teltonika |
| Ursalink Technology Co., Ltd |
| Shen Zhen azroad Technology Co., Ltd |
| Xiamen Baima Technology Co., Ltd |
| Robustel |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan-based foundries lock in modem supply visibility while freezing unit economics across 8-14 month FCC certification windows. Industrial OEMs trading volume commitments for allocation priority compress spot-market flexibility and amplify price dispersion between certified and uncertified hardware tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture IP67-rated DIN-rail designs with JIS C 61000 pre-certification for Japanese automotive suppliers. Price differentiation rests on certification grade and volume scale, with 5G private network variants commanding substantial premiums over LPWAN agricultural units. Cost compression in consumer Wi-Fi tiers intensifies as retail channels absorb excess 4G inventory. Smart home facilities teams exhibit highest price sensitivity, while German factory operators prioritize reliability over per-unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for cellular modem chipsets, feeding assembly operations across Germany, the United States, and Japan. Raw material flows draw from advanced foundry nodes, dual-band Wi-Fi chipsets, and ruggedized enclosure aluminum. Single-source vulnerability concentrates in Taiwan Strait logistics chokepoints where semiconductor fabrication hinges on limited coastal zones. Distribution runs through certified partner programs targeting smart building integrators and direct-to-enterprise cloud-managed provisioning platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native management platforms are redefining router economics as interoperability standards enable multi-vendor policy orchestration, shifting value capture from hardware margins to recurring software revenue streams.
For Market Incumbents: Shield installed base through embedded security certifications under EU Cyber Resilience Act mandates while accelerating edge-AI convergence roadmaps. Cradlepoint-style cloud-managed architectures face encroachment from software-defined radio specialists unbundling carrier-specific SKUs. Prioritize backward integration into secure boot firmware engineering concentrated in Israeli and Estonian talent pools. For New Entrants and Emerging Players: Anchor in India's PLI scheme subsidized assembly capacity for LPWAN agricultural gateways serving Southeast Asian export markets. Agricultural cooperatives in France and utility operators in India represent most penetrable demand clusters with bandwidth requirements below 50 kbps. Pursue direct-to-enterprise distribution through web-based provisioning platforms bypassing systems integrator margins. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined radio platform specialists with transportation fleet reference customers across North American interstate corridors. Long-term viability favors vendors unbundling hardware from carrier certification cycles through containerized networking stacks. Monitor private 5G spectrum allocation decisions by Japan's METI and Germany's Bundesnetzagentur as inflection indicators for enterprise direct-network ownership models.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Hardware Integration | TensorFlow Lite runtimes in Osaka industrial zones enable real-time acoustic anomaly detection without cloud latency. |
| Private 5G Spectrum Acquisition | Nagoya automotive suppliers purchasing captive frequency blocks bypass carrier intermediation for factory-floor networks. |
| Cloud-Native Management Platform | Unified cellular, Wi-Fi, and Ethernet policy control disintermediates traditional AV integrators in North American smart buildings. |
| Secure Boot Firmware Investment | EU Cyber Resilience Act mandates accelerate replacement cycles for legacy deployments lacking chipset-level vulnerability disclosure. |
| India Manufacturing Footprint | PLI scheme subsidies attract contract assembly capacity for domestic smart metering and Southeast Asian agricultural export markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC certification databases, METI JIS standard filings, EU Cyber Resilience Act regulatory texts, and carrier private spectrum allocation records. Primary interviews engaged router hardware engineering directors, industrial automation procurement leads at German automotive suppliers, smart building facilities managers across United States suburban markets, and cloud-managed platform product strategists. Bottom-up unit shipment estimates triangulate against top-down value projections derived from component bill-of-materials analysis.
Segmentation dimensions modeled span product type (5G, LPWAN, 4G, Wi-Fi), deployment architecture (edge computing, hybrid, on-premises, cloud-based), end-use vertical (industrial automation, smart home, healthcare, transportation), and regional regulatory cluster (FCC Part 15, EU RED, METI JIS C 61000). CAGRs across the analysis window derive from logistic diffusion curves fitted to private 5G spectrum release timelines and factory digitization investment cycles. Forecast inputs incorporate software-defined radio adoption velocity and edge-AI inference engine integration rates.
Material uncertainties — semiconductor foundry allocation disruptions, tariff exposure on Taiwan-origin chipsets, and accelerated zero-trust architecture mandates — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and carrier resistance to enterprise direct spectrum ownership. Recalibration cycles align with material shifts in national regulator spectrum allocation decisions and EU cybersecurity enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Satellite IoT Market