
 Fluorite Market | 2026-2036
Fluorite Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorite Market Analysis
Multi-source procurement of metallurgical and acid-grade feedstock is shifting as downstream chemical processors diversify beyond traditional Chinese supply channels. Do-Fluoride Chemicals Co., Ltd. anchors integrated fluorochemical production in China's central provinces, leveraging captive mine-to-acid conversion infrastructure. Masan High-Tech Materials competes from Vietnam with downstream control over high-purity hydrofluoric acid. Minersa Group specializes in European-sourced acid-spar, navigating stringent REACH compliance for specialty fluorochemical buyers.
Fluorite, chemically calcium fluoride (CaF₂) with theoretical fluorine content of 48.9%, occurs in hydrothermal veins and sedimentary deposits processed through gravity separation, flotation, and acid-grade purification to meet 97%+ CaF₂ specifications for hydrofluoric acid production. Acid-Spar dominates value capture given its role as the primary feedstock for fluorocarbons, fluoropolymers, and lithium battery electrolyte salts, while Metallurgical Grade sustains volume throughput in steelmaking flux applications. The Electronics end-use channel is expanding fastest as semiconductor etching gases and lithium-ion battery electrolytes consume ultra-high-purity hydrofluoric acid derivatives.
China's MIIT enforces GB standards on fluorite export quotas and processing efficiency, while the EU F-Gas Regulation and REACH framework restrict fluorinated gas emissions and chemical registration thresholds. These regulatory layers elevate compliance costs for non-integrated traders and favor producers with certified acid-grade capacity and downstream fluorochemical integration. Stakeholders must monitor evolving battery chemistry specifications and refrigerant phase-down timelines to align acid-spar beneficiation investments with qualified offtake channels.
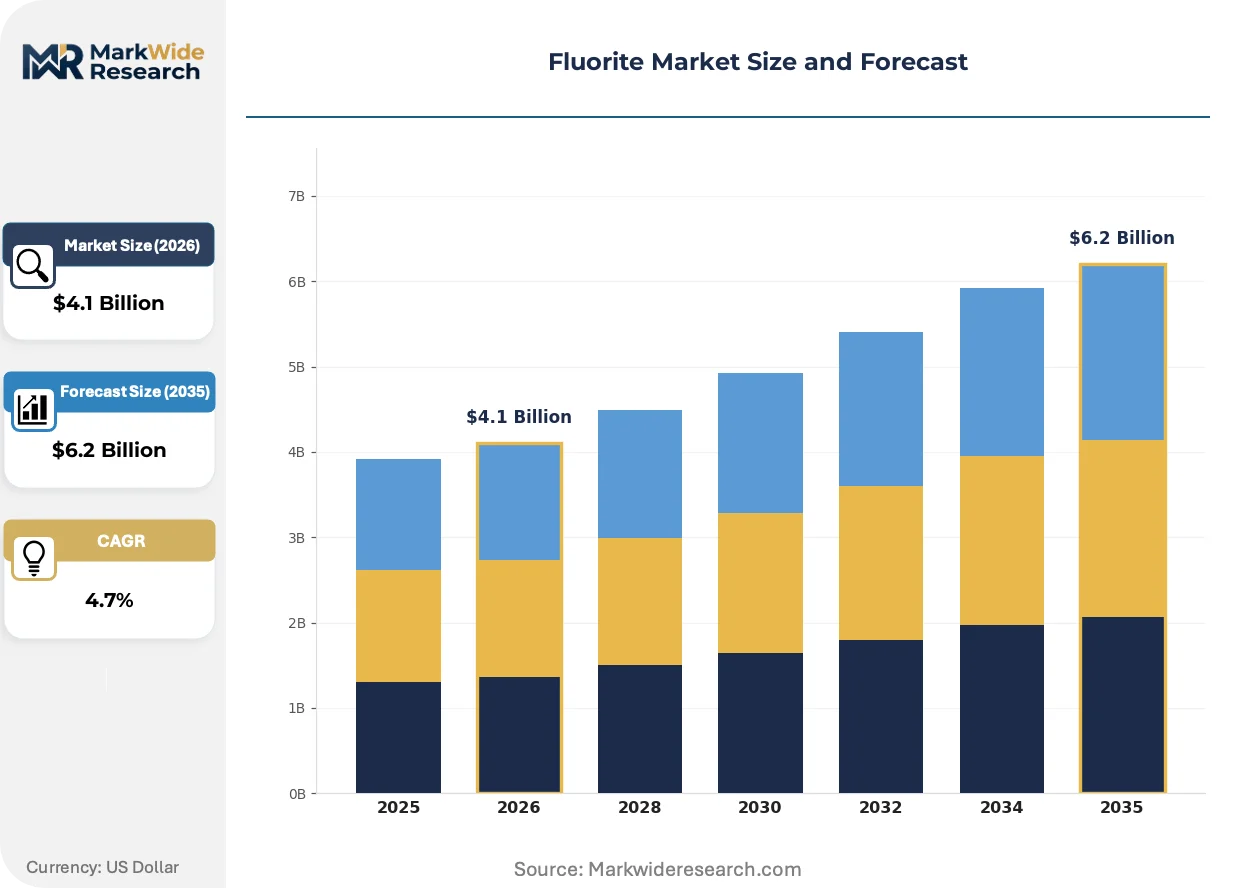
Market Dynamics
Acid-spar beneficiation capacity is concentrating in integrated fluorochemical parks where captive mine-to-acid conversion insulates processors from export quota volatility and REACH compliance friction.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon phase-down schedules redirect fluorite demand toward lower-GWP refrigerant chemistries, expanding qualified offtake channels for acid-grade producers.
- Lithium battery electrolyte salts:Semiconductor etching gases and battery-grade lithium hexafluorophosphate consume ultra-high-purity hydrofluoric acid derivatives, pulling acid-spar through qualified purification tiers.
- Henan and Inner Mongolia:Integrated fluorochemical parks cluster downstream conversion capacity, creating gravity for metallurgical and acid-grade feedstock procurement.
Market Restraints
- Energy cost volatility:Acid-grade purification to 97%+ CaF₂ specifications requires intensive thermal processing, exposing margins to natural gas and electricity price swings.
- Chinese supply concentration:MIIT export quotas and GB standards on processing efficiency create artificial scarcity, forcing non-integrated traders into spot market vulnerability.
- Synthetic fluorspar substitution:Phosphate fertilizer byproduct recovery and industrial waste fluorine reclamation displace virgin acid-spar in select metallurgical applications.
Strategic Opportunities
- Vietnamese acid-spar development:Masan High-Tech Materials demonstrates downstream control over high-purity hydrofluoric acid, offering non-Chinese supply channel diversification.
- Semiconductor etching gases:Advanced node fabrication at 3nm and below requires ultra-high-purity HF derivatives, creating premium tier demand disconnected from commodity pricing.
- EU Green Deal industrial incentives:Carbon border adjustment mechanisms and clean hydrogen subsidies favor European-sourced acid-spar with certified low-carbon beneficiation.
Industry Challenges
- Qualified metallurgist scarcity:Gravity separation and flotation optimization for complex ore bodies requires specialized expertise concentrated in aging Chinese and Mexican engineering cadres.
- Dual certification timelines:Simultaneous REACH registration and MIIT export license maintenance extends product qualification cycles, freezing working capital.
- Legacy HF plant retrofit complexity:Converting existing fluorochemical capacity to battery-grade electrolyte salt specifications demands staged capex with uncertain offtake commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorite Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid-Spar, Metallurgical Grade, Ceramic Grade, Optical Grade End Use Industry: Metallurgy, Glass Manufacturing, Chemical Processing, Electronics Form: Fluorspar Powder, Fluorspar Lump, Fluorspar Granules, Fluorspar Concentrate Application: Aluminum Production, Steelmaking, Refrigerants, Polymer Production |
| Companies Covered | China Kings Resources Group Co., Ltd., Mexichem, Do-Fluoride Chemicals Co., Ltd., Fluorsid Group, Minersa Group, Mongolrostsvetmet LLC, Sinochem Lantian Co., Ltd., Masan High-Tech Materials, Seaforth Mineral & Ore Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorite Market Emerging Trajectories
Fluorite value capture is migrating upstream from commodity trading toward integrated acid-grade purification and specialty fluorochemical derivatives, compressing margins for standalone miners.
Direct shipping ore rejection is electrifying beneficiation economics. Advanced sensor-based sorting and dense medium separation now pre-concentrate run-of-mine material before energy-intensive flotation. Chinese integrated processors deploy these systems at mine mouth, slashing transport costs to distant fluorochemical parks. The technology is electrifying competitive separation between captive infrastructure and merchant traders.
China's MIIT enforces stricter GB standards on fluorite export quotas and processing efficiency, tightening supply discipline. The regulation elevates compliance costs for non-integrated traders while favoring producers with certified acid-grade capacity and downstream fluorochemical integration. Acid-spar processors in Henan and Inner Mongolia provinces respond by deepening mine-to-acid conversion infrastructure.
Buyer concentration among battery electrolyte salt manufacturers rotates procurement gravity toward qualified acid-spar tiers with documented impurity profiles. Long-term offtake contracts displace spot market transactions, locking in supply security for cathode material producers. This pattern concentrates most visibly in China's lithium chemical hubs and South Korean battery material supply chains.
Fluorite Market Segmentation
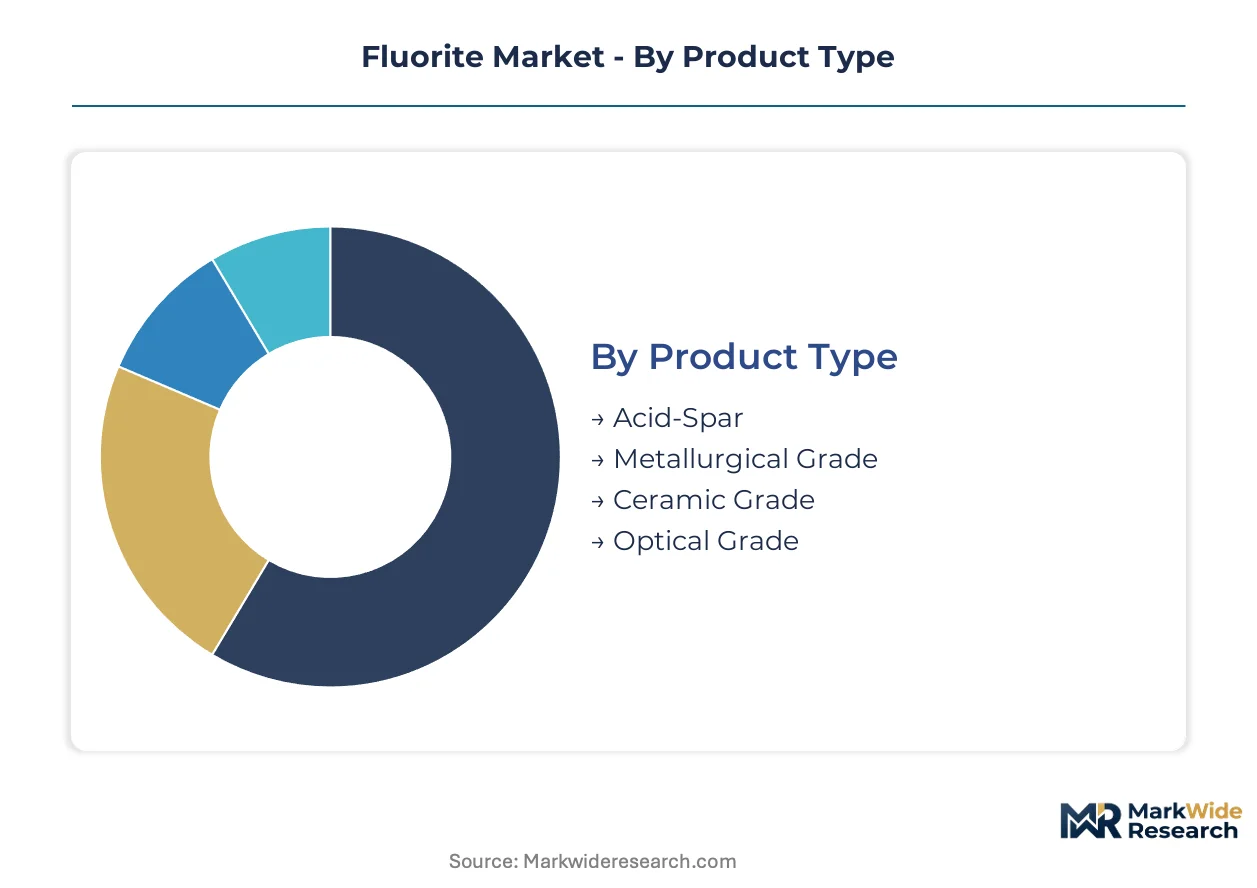
Fluorite segmentation reflects divergent purity requirements across industrial chemistry and metallurgical flux applications. Buyers select grades based on downstream conversion complexity, with acid-grade commanding premium positioning against commodity metallurgical alternatives.
Product Type:
Buyers differentiate by fluorine content thresholds and impurity tolerance for chemical conversion versus bulk metallurgical consumption.
- Acid-Spar:Requires 97%+ CaF₂ purity with controlled silica and sulfur levels to prevent HF plant corrosion. Semiconductor etching gas manufacturers and lithium battery electrolyte salt producers in China's Henan province pull material through certified beneficiation tiers with documented trace element profiles.
- Metallurgical Grade:Operates at 60-85% CaF₂ specifications for steelmaking flux and aluminum smelting bath temperature control. Chinese and Indian steelmakers dominate procurement volumes, though synthetic fluorspar from phosphate fertilizer byproduct recovery is displacing virgin material in select applications.
- Ceramic Grade:Intermediate purity band serving specialty enamel and welding rod coatings with moderate fluorine content requirements.
- Optical Grade:Ultra-high purity for lens and prism fabrication in precision instrumentation, representing niche volume with extreme quality certification.
Metallurgical Grade leads volumes today; Acid-Spar is gaining share fastest.
End Use Industry:
Procurement patterns split between mass-volume metallurgical consumers and specification-driven chemical processors.
- Chemical Processing:Hydrofluoric acid production for fluorocarbons, fluoropolymers, and refrigerant chemistries consumes the highest-purity acid-spar tiers. EU F-Gas Regulation phase-down schedules redirect demand toward lower-GWP refrigerant feedstocks, tightening qualified supplier requirements.
- Electronics:Semiconductor etching gases and lithium-ion battery electrolyte salts require ultra-high-purity HF derivatives with sub-ppb contamination limits. South Korean battery material supply chains and Chinese lithium chemical hubs concentrate procurement gravity.
- Metallurgy:Steelmaking flux and aluminum smelting operations in China and India sustain bulk throughput with lower-grade material specifications.
- Glass Manufacturing:Specialty optical and welding glass applications utilize ceramic-grade fluorite for refractive index modification.
Chemical Processing anchors revenue concentration; Electronics shows the steepest expansion trajectory.
Form:
Physical presentation determines transport economics and beneficiation stage integration with downstream processing infrastructure.
- Fluorspar Concentrate:Post-flotation upgraded material at 97%+ CaF₂ serves acid-grade chemical processors directly, bypassing intermediate handling. Chinese integrated fluorochemical parks in Inner Mongolia prefer concentrate delivery to minimize slurry transport costs.
- Fluorspar Lump:Coarse crushed run-of-mine material feeds metallurgical furnaces and aluminum smelters requiring controlled dissolution rates.
- Fluorspar Powder:Finely milled product for ceramic enamel and welding rod coating applications with surface area requirements.
- Fluorspar Granules:Sized intermediate for specialized chemical reactor feed systems and controlled-release metallurgical applications.
Fluorspar Concentrate captures the highest margin tier; Fluorspar Lump sustains the largest shipment volumes.
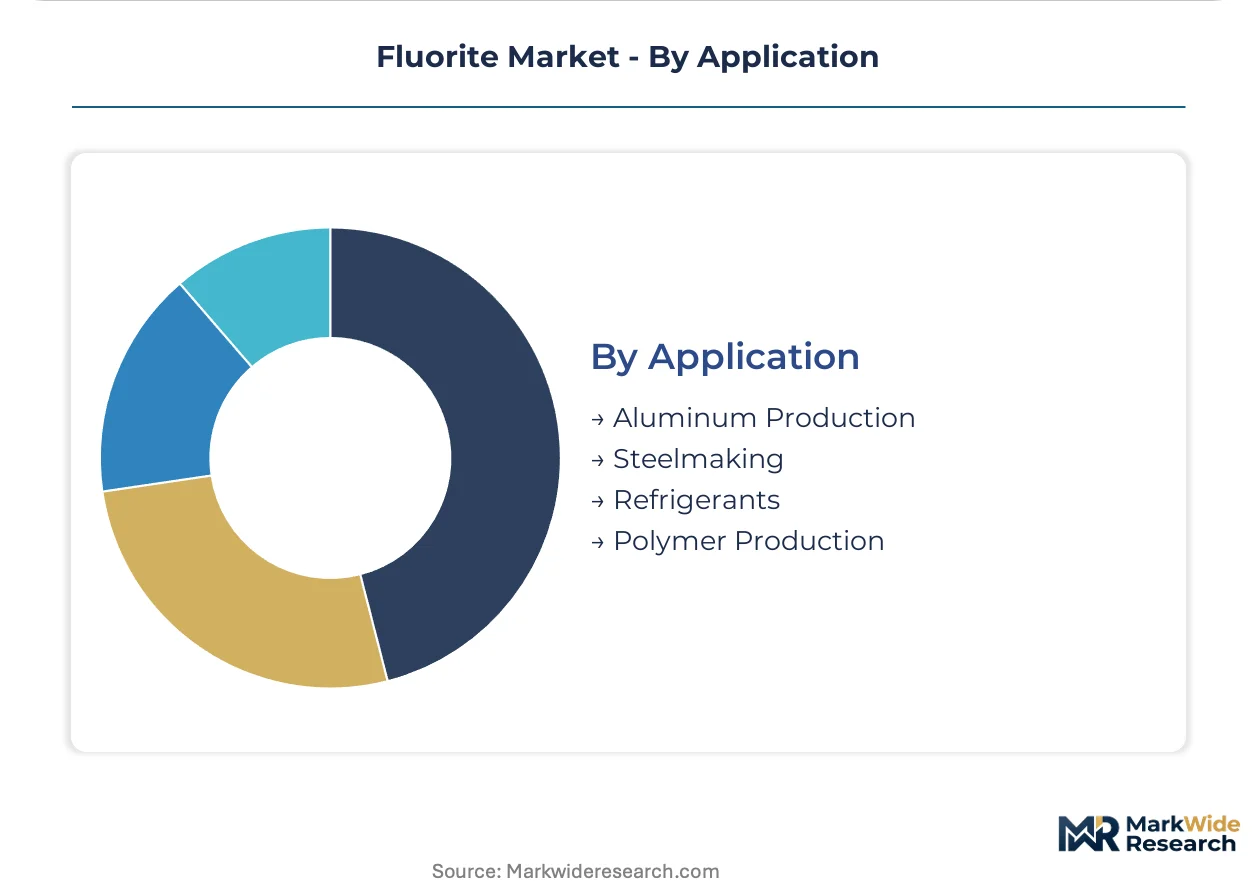
Application:
End-use chemistry dictates beneficiation intensity and certification requirements across industrial value chains.
- Refrigerants:Hydrofluorocarbon and emerging low-GWP alternative production consumes acid-spar through multi-stage HF purification. EU F-Gas Regulation compliance elevates documentation requirements for feedstock traceability.
- Polymer Production:Fluoropolymer manufacturing for chemical processing equipment and semiconductor fabrication facilities requires consistent high-purity HF supply with batch-to-batch reproducibility.
- Steelmaking:Flux applications in basic oxygen furnaces and electric arc operations utilize lower-grade material with tolerance for silica and calcium carbonate gangue minerals.
- Aluminum Production:Electrolytic bath temperature control and viscosity modification in Hall-Héroult cells demands specific particle size distribution.
Steelmaking maintains the broadest volume base; Refrigerants face the most acute regulatory-driven specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fluorite beneficiation investment toward jurisdictions where MIIT export quotas and REACH compliance costs create divergent cost structures for acid-grade producers.
China
Steelmakers in Henan and Inner Mongolia provinces are expanding acid-spar offtake for aluminum smelting and fluorochemical feedstock. MIIT enforces GB standards on export quotas and processing efficiency, tightening supply discipline. Integrated fluorochemical parks in these provinces cluster downstream conversion capacity, creating gravity for metallurgical and acid-grade feedstock procurement.
Vietnam
Masan High-Tech Materials competes with downstream control over high-purity hydrofluoric acid, offering non-Chinese supply channel diversification. The country's national mining regulator oversees environmental compliance for acid-spar development. Vietnamese acid-spar projects concentrate in northern provinces with access to regional fluorochemical markets.
Mongolia
Mongolrostsvetmet LLC anchors regional supply from sedimentary deposits processed through gravity separation and flotation. The central bank and mineral resources authority coordinate foreign investment frameworks for fluorite extraction. Mine-to-border logistics infrastructure connects Mongolian operations to Chinese fluorochemical parks in Inner Mongolia.
United States
Seaforth Mineral & Ore Co. serves specialty fluorochemical buyers navigating stringent EPA and OSHA compliance for acid-grade purification. The EPA regulates fluorinated gas emissions under Clean Air Act provisions affecting refrigerant feedstock demand. Domestic beneficiation capacity concentrates in Illinois and Kentucky, supplying steelmaking flux and limited acid-spar tiers.
Mexico
Mexichem leverages proximity to US chemical processors while managing legacy hydrofluoric acid plant infrastructure. The national environmental regulator enforces emissions standards for fluorochemical production. Sonora and Coahuila host primary beneficiation operations feeding both domestic aluminum smelters and export markets.
Fluorite Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue downstream fluorochemical integration and battery-grade electrolyte salt specifications. The vendor base stratifies across captive mine-to-acid operators, merchant concentrate traders, and specialty high-purity processors. Three archetypes dominate: integrated Chinese state-affiliated entities with export quota privileges, Vietnamese downstream controllers with HF acid capacity, and European REACH-certified specialists serving refrigerant and semiconductor channels. Competitive moves concentrate on backward integration into mining assets and geographic diversification beyond Chinese supply concentration.
Within the integrated tier, Do-Fluoride Chemicals Co., Ltd. and Sinochem Lantian Co., Ltd. exemplify Chinese state-linked structures with captive mine-to-acid conversion infrastructure. Masan High-Tech Materials occupies a downstream-control position, representing the Vietnamese alternative to Chinese supply channels. Minersa Group anchors the European specialist archetype, navigating REACH compliance for specialty fluorochemical buyers. These three entities collectively illustrate the geographic and regulatory segmentation shaping competitive positioning.
| Leading Market Players |
|---|
| China Kings Resources Group Co., Ltd. |
| Mexichem |
| Do-Fluoride Chemicals Co., Ltd. |
| Fluorsid Group |
| Minersa Group |
| Mongolrostsvetmet LLC |
| Sinochem Lantian Co., Ltd. |
| Masan High-Tech Materials |
| Seaforth Mineral & Ore Co. |
| Others |
Supply Flow & Price Mechanics
Qualified metallurgist scarcity in aging Chinese and Mexican engineering cadres widens labor-cost differentials between integrated fluorochemical parks and standalone beneficiation operations, compressing margins at the standard tier while premium acid-spar commands widening spreads.
Pricing Analysis
Distributor margin layers separate acid-spar concentrate from metallurgical lump deliveries, with contract-based long-term offtake dominating qualified battery-grade supply. Price differentiation rests on certification grade and volume scale, with semiconductor etching gas manufacturers least sensitive and steelmaking flux buyers most price-responsive. Cost compression in metallurgical tiers is intensifying because synthetic fluorspar from phosphate fertilizer byproduct recovery displaces virgin material.
Supply Chain Analysis
Freight cost differentials between Mongolian mine-to-border logistics and Vietnamese coastal export routes reshape procurement economics for Chinese fluorochemical parks. Supply draws from China, Vietnam, and Mongolia, with acid-grade purification resting on sulfuric acid, thermal energy, and flotation reagent inputs. Single-source vulnerability concentrates in MIIT export quota administration. Distribution runs through integrated mine-to-acid operators and merchant concentrate traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fluorite hinges on downstream migration toward battery-grade electrolyte salt specifications, where qualified acid-spar tiers capture premium positioning above commodity metallurgical alternatives.
For Market Incumbents: Deploy captive mine-to-acid conversion infrastructure to insulate against MIIT export quota volatility. Deepen backward integration into Mongolian and Vietnamese mining assets to diversify beyond Chinese supply concentration. Accelerate REACH certification maintenance to defend specialty fluorochemical channels against emerging Vietnamese downstream controllers. For New Entrants and Emerging Players: Sensor-based sorting technology at mine mouth offers entry into pre-concentration services for distant fluorochemical parks. Target Vietnamese northern provinces and Mongolian sedimentary deposits for acid-spar development with downstream HF acid partnerships. Pursue white-space in semiconductor etching gas qualification where sub-ppb contamination limits create barrier-protected premium tiers. For Investors and Strategic Acquirers: Battery material producers are the most active acquirer in this space, seeking supply security for lithium hexafluorophosphate output. Long-term viability favors integrated operators with certified acid-grade capacity and documented impurity profiles. Watch EU F-Gas Regulation phase-down acceleration as inflection indicator for lower-GWP refrigerant feedstock demand rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive acid-spar supply insulates Do-Fluoride Chemicals from MIIT quota volatility. |
| Long-term Supply Agreement | South Korean battery material supply chains lock in qualified acid-spar tiers with documented trace profiles. |
| Green Manufacturing Transition | EU Green Deal carbon border adjustments favor European-sourced acid-spar with certified low-carbon beneficiation. |
| Joint Venture | Masan High-Tech Materials demonstrates downstream HF acid control through Vietnamese regulatory compliance. |
| Capacity Expansion | Henan and Inner Mongolia fluorochemical parks cluster conversion infrastructure to capture battery-grade demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fluorochemical plant managers, steelmaker procurement leads, battery material R&D directors, and REACH compliance specialists with secondary validation from customs trade data, SEC 10-K filings, and MIIT GB standard disclosures. Bottom-up volume modeling and top-down value triangulation anchored segmentation across grade tier, end-use industry, and regional production hub dimensions.
Historical reference periods established baseline acid-spar and metallurgical grade volume trajectories, with CAGRs derived from regression analysis across the projection horizon. The analytical framework modeled battery chemistry specifications, refrigerant phase-down timelines, and semiconductor node advancement as industry-specific demand drivers throughout the forecast period.
The model holds under stable MIIT export quota enforcement and EU F-Gas Regulation phase-down schedules; deviation in synthetic fluorspar substitution rates or REACH registration timelines would shift supply-demand balances. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
India 3D Printing Construction Market
Others
Global Healthcare/Medical Simulation Market
Others
Receiving Scales Market
Others
Basketball Apparel Market
Others
Industrial Hooters Market
Others
Cloud Advertising Market
Others
Cloud DVR Market
Others
Middle East Paper Making Machine Market
Others
Communication Base Station Body Market
Others
Buchner Funnels Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
PC As a Service Market
Others
Reinforcement Geosynthetics Market
Others
Stichtite Market