
 Asia Pacific Cloud Infrastructure Testing Services Market | 2026-2036
Asia Pacific Cloud Infrastructure Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cloud Infrastructure Testing Services Market Outlook
Enterprise-grade SLA certification is unwinding legacy testing methodologies across the Asia Pacific cloud infrastructure services landscape. HCLTech leverages its India-centric delivery footprint and deep vertical expertise in financial services to anchor large-scale performance testing engagements for regional banks. Fujitsu sustains competitive positioning through its hybrid cloud specialization and longstanding enterprise relationships across Japan and Southeast Asia. Accenture differentiates by integrating continuous testing pipelines with client cloud transformation programs, occupying a consultative layer above pure-play testing vendors.
Cloud infrastructure testing services encompass the systematic validation of compute, storage, network, and orchestration layers across distributed cloud environments, employing automated probe injection, synthetic transaction simulation, and chaos engineering protocols to verify resilience under production-equivalent load conditions. The primary commercial purpose centers on pre-deployment risk mitigation and ongoing operational assurance for mission-critical workloads subject to strict availability and compliance mandates. Security testing and compliance testing command premium pricing within the service type dimension, reflecting the complexity of cross-border data governance and sector-specific regulatory overlays. Multi-cloud deployment architectures represent the fastest-expanding configuration segment, driven by enterprise strategies to avoid vendor lock-in and optimize workload placement across hyperscaler environments.
Australia's APRA CPS 234 and ASD Essential Eight frameworks, India's Digital Personal Data Protection Act enforcement by the Ministry of Electronics and Information Technology, and Japan's METI-guided cloud security guidelines collectively elevate mandatory testing thresholds for regulated industries. These standards shape procurement requirements by embedding third-party validation and continuous monitoring obligations into cloud adoption contracts. Stakeholders must monitor evolving data localization mandates and cross-border certification reciprocity agreements, as these regulatory variables will determine which testing providers can operate across jurisdictional boundaries without partner-dependent service delivery models.
Market Dynamics
Multi-cloud sovereignty mandates are fragmenting testing requirements across Asia Pacific jurisdictions, forcing providers to rebuild validation frameworks for each national data governance regime rather than operating regional centers of excellence.
Growth Catalysts
- APRA CPS 234:Australian prudential standards mandate pre-production resilience testing for financial institutions, creating recurring revenue streams for compliance-focused service providers.
- BFSI multi-cloud migration:Banking and insurance workloads spanning AWS, Azure, and Alibaba Cloud require continuous interoperability validation that single-vendor testing cannot address.
- Chaos engineering adoption:Distributed system fault injection protocols are becoming standard pre-deployment practice for fintech platforms across Singapore and Hong Kong.
Market Restraints
- Certified engineer scarcity:The shallow talent pool for cloud-native security testers in Vietnam and Indonesia inflates project delivery costs by 40-60% versus established markets.
- Hyperscaler concentration:Testing toolchains dependent on AWS, Azure, and GCP native APIs create vendor lock-in risks that deter enterprise procurement committees.
- Cross-border data friction:India's Digital Personal Data Protection Act restricts where test data replicas can reside, complicating regional service delivery models.
Strategic Opportunities
- Philippines government cloud:The Department of Information and Communications Technology's cloud-first policy for national agencies remains underpenetrated by specialized testing vendors.
- AI workload validation:GPU cluster performance benchmarking for generative AI training pipelines represents an emerging service category without established standards.
- ASEAN cross-border reciprocity:Proposed mutual recognition frameworks for cloud security certifications would enable single-country testing licenses to operate across Southeast Asia.
Industry Challenges
- Container security expertise gap:Kubernetes penetration testing and supply chain attestation require skills that outpace regional certification program output.
- Legacy mainframe integration:Hybrid environments connecting on-premises core banking systems to cloud front-ends demand testing protocols that span incompatible architectural eras.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cloud Infrastructure Testing Services Market |
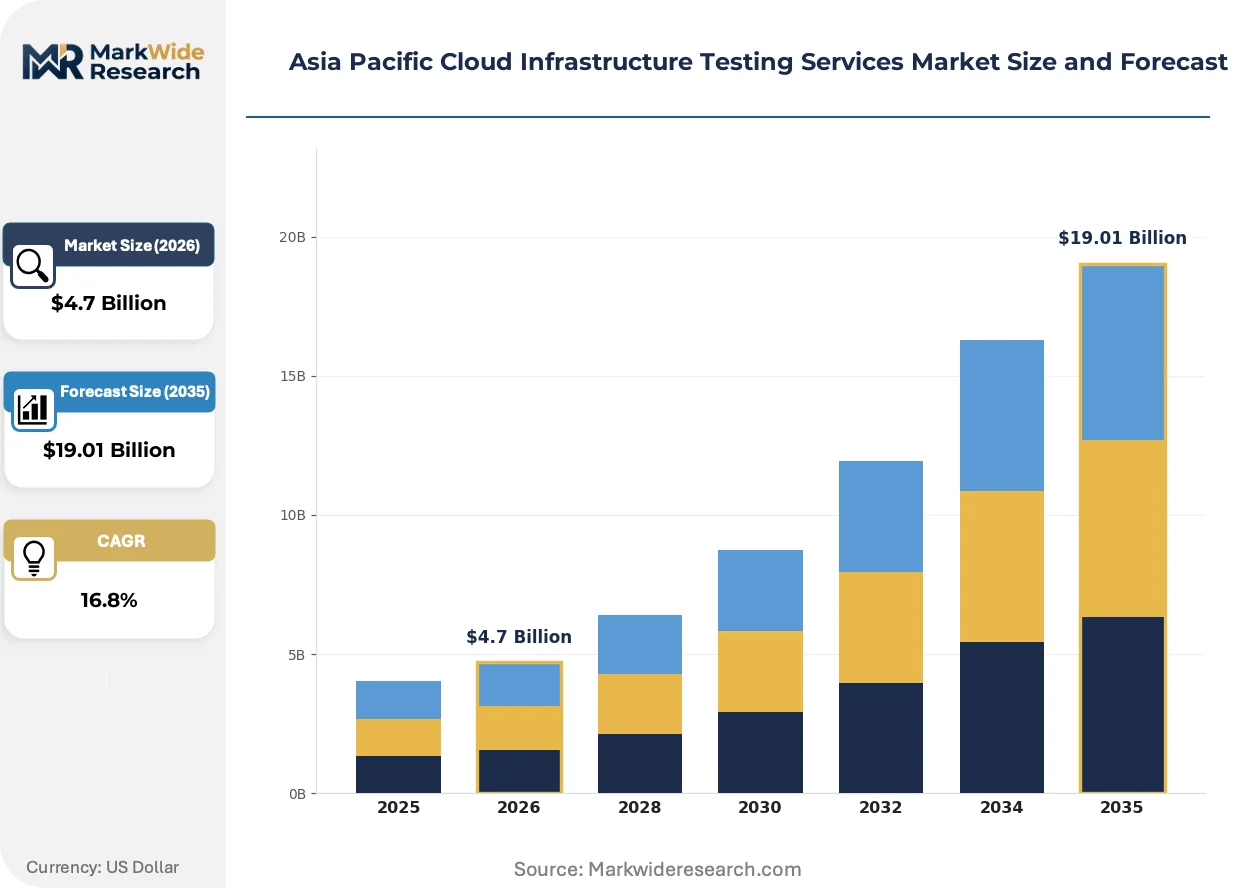
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Testing, Load Testing, Security Testing, Compliance Testing End User: Telecommunications, BFSI, E-Commerce, Healthcare Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Automation Tools, Test Management Software, Virtualization, Continuous Integration |
| Companies Covered | IBM, HCLTech, Accenture, Maximus Consulting, Pentera, Oracle, Fujitsu, Cisco Systems, Broadcom, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cloud Infrastructure Testing Services Market Strategic Shifts
Cloud infrastructure testing is pivoting from pre-release gatekeeping to continuous validation embedded within DevSecOps pipelines, compressing feedback loops and elevating automation maturity requirements for service providers.
Chaos engineering is bifurcating the testing services landscape between boutique specialists and platform-integrated offerings. Netflix's Simian Army methodologies have migrated into enterprise toolchains. Australian fintechs and Japanese insurers now demand game-day exercises that validate failover under production load. The technology is compressing incident response timelines while expanding the scope of what constitutes "tested" infrastructure.
India's Digital Personal Data Protection Act enforcement by the Ministry of Electronics and Information Technology is reshaping data residency validation requirements. Cross-border workload testing now requires explicit jurisdictional attestation. BFSI procurement teams in Mumbai and Bangalore are embedding third-party compliance verification into every cloud migration contract, elevating testing from technical checkpoint to legal prerequisite.
Consumption-based pricing for testing services is displacing fixed-scope engagements across Asia Pacific enterprise accounts. Subscription models tied to monthly active workload volumes are replacing project-based statements of work. This pattern is most visible among Singaporean and Hong Kong financial services firms managing volatile cloud spend across multiple hyperscaler environments.
Asia Pacific Cloud Infrastructure Testing Services Market Segmentation
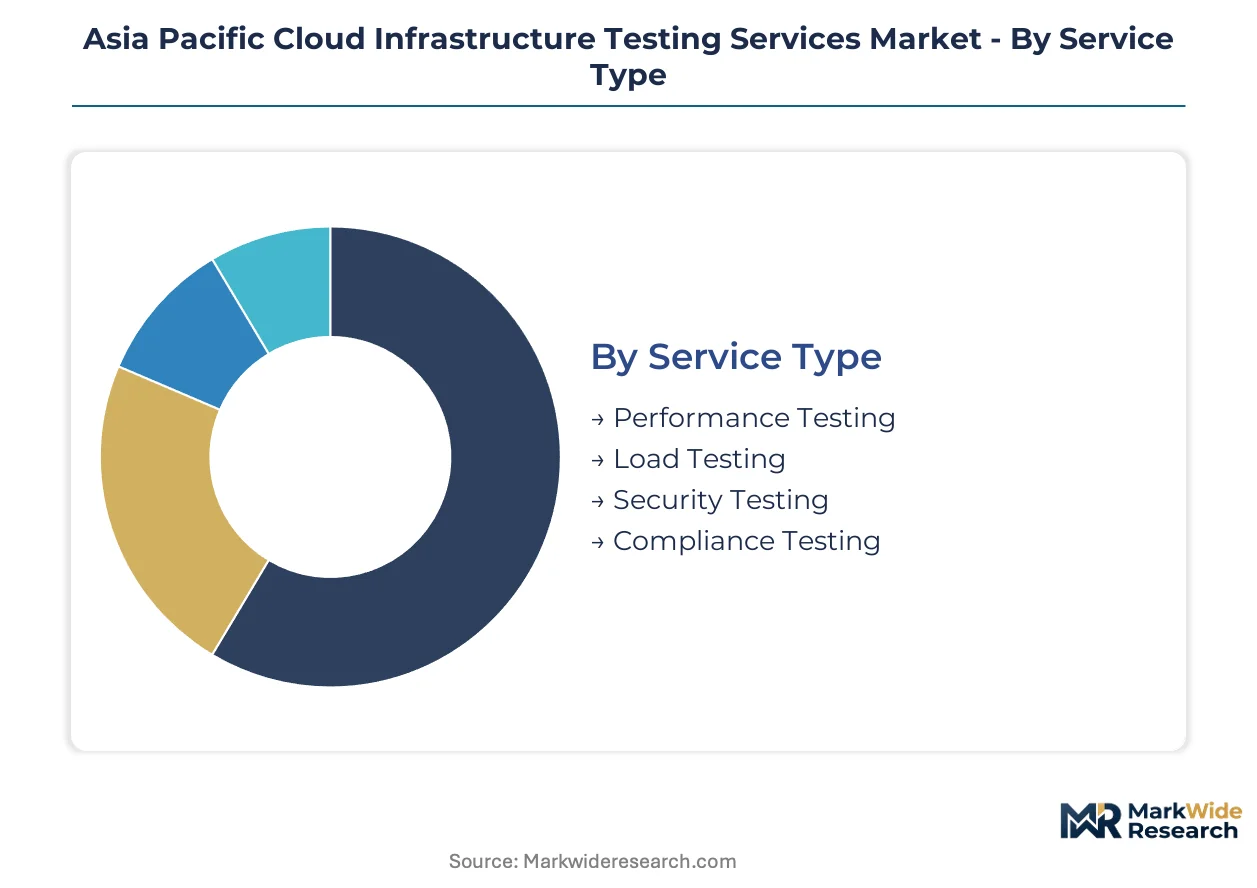
Cloud infrastructure testing services fragment across four operational dimensions, each reflecting distinct procurement priorities and technical requirements. Service type and deployment architecture drive pricing differentiation, while end-user verticals and technology stacks determine capability requirements for providers.
Service Type:
Performance testing and load testing concentrate in domestic Australia and India, where APRA CPS 234 and data sovereignty mandates require localized validation. Security and compliance testing exhibit stronger cross-border delivery patterns, with Singapore and Hong Kong serving as regional hubs for multi-jurisdiction certification.
- Performance Testing:Synthetic transaction simulation and latency benchmarking across compute, storage, and network layers. Australian banks and Indian insurers mandate pre-production validation under APRA and RBI frameworks, creating recurring domestic demand cycles.
- Security Testing:Penetration testing, vulnerability assessment, and threat modeling for cloud-native architectures. Singaporean fintechs and Hong Kong virtual banks drive concentrated procurement for container security and API gateway validation.
- Load Testing:Stress validation under production-equivalent traffic volumes. E-commerce platforms in Indonesia and the Philippines commission seasonal surge testing ahead of promotional events.
- Compliance Testing:Regulatory attestation for data residency and sector-specific mandates. India's Digital Personal Data Protection Act enforcement has elevated this to a contractual prerequisite for BFSI cloud migrations.
Performance testing commands the established base. The steepest expansion runs through compliance testing.
End User:
Cost tier stratification separates mission-critical BFSI workloads from volume-driven e-commerce engagements, with telecommunications occupying a mid-tier position on reliability requirements.
- BFSI:Multi-cloud resilience validation for core banking and insurance platforms. Australian prudential standards and Japan's METI guidelines mandate third-party attestation, embedding testing into procurement contracts.
- Telecommunications:5G network function virtualization and edge computing validation. South Korean and Japanese carriers lead regional investment in cloud-native infrastructure testing.
- E-Commerce:Flash sale readiness and payment gateway stress testing. Southeast Asian platforms require elastic validation frameworks for volatile transaction volumes.
- Healthcare:Patient data protection and clinical system availability assurance. Australia's My Health Record and India's Ayushman Bharat digital infrastructure drive compliance-focused engagements.
BFSI absorbs the premium tier. Healthcare is climbing fastest on regulatory tailwinds.
Deployment:
Technology maturity separates legacy single-cloud validation from emerging multi-cloud orchestration requirements, with hybrid architectures bridging enterprise transition states.
- Multi-Cloud:Interoperability validation across AWS, Azure, Alibaba Cloud, and regional hyperscaler environments. Singaporean and Hong Kong financial institutions prioritize vendor-agnostic testing to optimize workload placement.
- Hybrid Cloud:Integration testing between on-premises legacy systems and cloud-native front-ends. Japanese manufacturers and Australian government agencies require seamless failover validation.
- Public Cloud:Native toolchain validation for single-hyperscaler deployments. Indonesian and Vietnamese enterprises concentrate here for cost efficiency.
- Private Cloud:Dedicated infrastructure assurance for classified workloads. India's government cloud and Australia's defense sector mandate air-gapped validation environments.
Hybrid cloud holds the incumbent position. Multi-cloud is gaining share fastest on enterprise diversification strategies.
Technology:
Supply concentration in automation tooling creates vendor dependencies, while test management software fragments across proprietary and open-source alternatives.
- Automation Tools:Scripted probe injection and synthetic monitoring frameworks. Australian and Indian service providers build competitive differentiation through proprietary automation libraries.
- Continuous Integration:Embedded testing pipelines within DevSecOps workflows. Singaporean fintechs and Hong Kong virtual banks mandate CI-integrated validation for rapid release cycles.
- Test Management Software:Centralized planning, execution, and reporting platforms. Japanese enterprises favor integrated suites from established IT services vendors.
- Virtualization:Container and microservices testing environments. Kubernetes security validation represents an emerging capability gap across Southeast Asia.
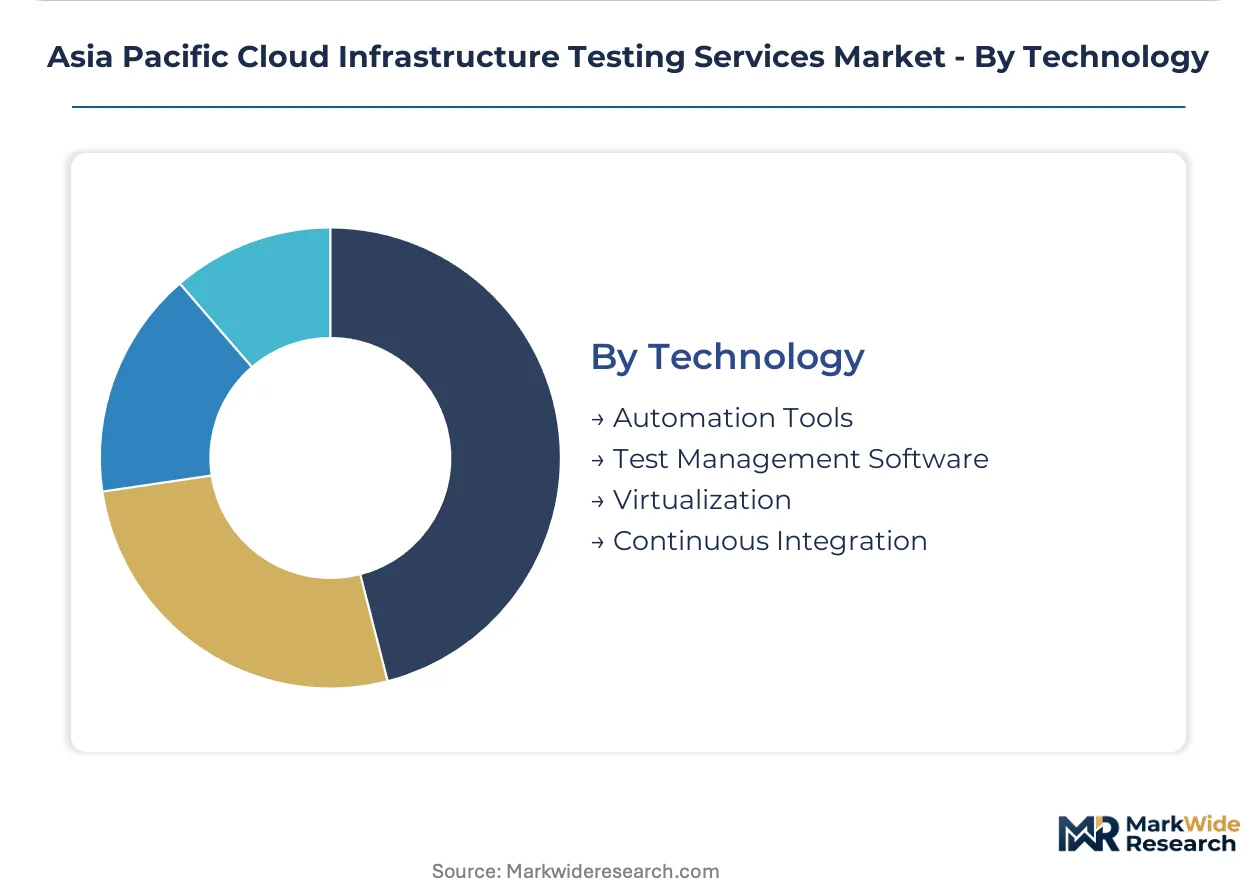
Automation tools anchor current procurement. Continuous integration is expanding most quickly on pipeline modernization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing service delivery concentrates in financial hubs where regulatory density justifies specialized compliance infrastructure. Australia, India, Japan, Singapore, and South Korea each enforce distinct sovereign requirements that fragment regional standardization.
Australia
APRA CPS 234 mandates pre-production resilience validation for all deposit-taking institutions. The Australian Prudential Regulation Authority embeds third-party attestation requirements directly into banking licenses. Sydney's financial district hosts concentrated procurement for multi-cloud failover testing among the four major banks.
India
The Ministry of Electronics and Information Technology enforces Digital Personal Data Protection Act compliance for all cloud-hosted personal data. Domestic data localization requirements compel foreign hyperscalers to establish in-country testing environments. Mumbai and Bangalore BFSI procurement teams now mandate jurisdictional attestation clauses in every cloud migration contract.
Japan
METI-guided cloud security guidelines elevate mandatory testing thresholds for financial and manufacturing sectors. The Ministry of Economy, Trade and Industry coordinates sector-specific validation protocols through industry working groups. Tokyo-based insurers and Osaka manufacturers drive hybrid cloud integration testing demand.
Singapore
The Monetary Authority of Singapore imposes technology risk management guidelines requiring continuous resilience validation for digital banks. Cross-border fund flow monitoring creates demand for multi-jurisdiction compliance attestation. Raffles Place financial institutions procure vendor-agnostic testing to optimize workload placement across AWS, Azure, and Alibaba Cloud.
South Korea
Financial Services Commission regulations mandate stress testing for cloud-hosted core banking systems. The Korea Internet and Security Agency certifies security testing providers for public sector eligibility. Seoul-based fintech platforms and Busan regional banks commission chaos engineering protocols for distributed system validation.
Asia Pacific Cloud Infrastructure Testing Services Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific cloud infrastructure testing services landscape. Global systems integrators occupy the consultative premium tier through continuous testing pipeline integration, while India-centric delivery specialists compete on scale and vertical depth. The market structure reveals three strategic archetypes: hyperscale consultancies with transformation program anchoring, regional specialists with regulatory certification depth, and automation-first platforms with DevSecOps embedding. Dominant competitive moves center on geographic certification expansion to satisfy data sovereignty mandates and proprietary automation library development to reduce marginal testing costs.
Among global systems integrators, IBM, Accenture, and HCLTech exemplify divergent positioning strategies. IBM occupies a position bridging hybrid cloud infrastructure and enterprise security validation through its services integration heritage. Accenture represents the consultative-layer archetype, embedding testing within broader cloud transformation programs rather than competing as a pure-play vendor. HCLTech anchors the India-centric delivery model, leveraging domestic talent density and financial services vertical expertise to capture large-scale performance testing engagements for regional banking institutions. These three players collectively illustrate how scale, geography, and vertical depth create non-overlapping competitive territories in a market where regulatory fragmentation prevents winner-take-all consolidation.
| Leading Market Players |
|---|
| IBM |
| HCLTech |
| Accenture |
| Maximus Consulting |
| Pentera |
| Oracle |
| Fujitsu |
| Cisco Systems |
| Broadcom |
| Others |
Value Chain & Pricing Dynamics
India-centric delivery scale anchors cost structures across the Asia Pacific cloud infrastructure testing services landscape, compressing price floors for commoditized performance validation while elevating premiums for jurisdiction-specific compliance attestation. Australian APRA mandates and India's Digital Personal Data Protection Act create divergent cost-to-serve profiles that fragment regional pricing coherence.
Pricing Analysis
APRA CPS 234 dictates the pricing tier structure for financial services testing across Australia, separating premium compliance attestation from standard performance benchmarking. Pricing stratifies across certified-jurisdiction, multi-cloud orchestration, and single-tenant validation tiers, with Singaporean banks absorbing the highest premiums for cross-border data governance verification. Cost compression in standardized load testing is intensifying because Indian delivery centers replicate automation libraries at marginal cost. Indonesian e-commerce platforms exhibit the sharpest price sensitivity, while Japanese insurers demonstrate the least.
Supply Chain Analysis
Certified engineer pipelines through Bangalore, Manila, and Ho Chi Minh City chokepoint capacity expansion for security testing services across Southeast Asia. Delivery infrastructure draws from India's IT services talent base, Australia's regulatory consulting ecosystem, and Singapore's multi-cloud orchestration specialists. Single-source vulnerability concentrates in the shallow Kubernetes security certification pool across Vietnam and Indonesia. Distribution runs through hyperscaler marketplace integrations and direct enterprise procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cloud interoperability standards are reconstituting this market as a platform-economics arena where ecosystem orchestration capabilities determine vendor viability. The shift from project-based testing to continuous validation pipelines rewards embedded service architectures.
For Market Incumbents: Shield recurring revenue streams by embedding proprietary automation libraries into client DevSecOps toolchains before open-source alternatives achieve feature parity. Acquire certified testing capacity in data-sovereignty jurisdictions like India and Australia to preempt regulatory lockout. Chaos engineering expertise represents the most defensible capability moat as enterprise fault-injection requirements mature. For New Entrants and Emerging Players: Anchor in the Philippines government cloud segment, where the Department of Information and Communications Technology's cloud-first policy remains underpenetrated by specialized testing vendors. Target AI workload validation for generative AI training pipelines, an emerging category lacking established standards or incumbent certification. Lead with consumption-based pricing models to displace fixed-scope engagements among Southeast Asian e-commerce platforms. For Investors and Strategic Acquirers: Boutique compliance specialists with deep APRA, RBI, or METI certification depth command scarcity premiums as data sovereignty mandates proliferate. Long-term viability hinges on geographic certification reciprocity rather than technical differentiation alone. Monitor ASEAN mutual recognition framework negotiations as the critical inflection signal for regional rollup feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Certification Expansion | APRA and RBI attestation capabilities unlock Australian and Indian BFSI procurement pipelines. |
| Proprietary Automation Library Development | DevSecOps-embedded testing tools reduce marginal delivery costs for multi-cloud validation engagements. |
| Chaos Engineering Capability Buildout | Game-day exercise protocols address Singaporean and Hong Kong fintech resilience requirements. |
| AI Workload Validation Investment | GPU cluster benchmarking captures generative AI infrastructure testing demand before standards crystallize. |
| Consumption-Based Pricing Transition | Monthly active workload subscriptions align revenue with volatile cloud spend patterns across hyperscaler environments. |
Study Parameters
Desk research of hyperscaler capex disclosures, regulatory filing databases, and cloud services procurement records preceded structured interviews with CTOs, cloud platform engineers, IT procurement officers, and compliance directors at financial institutions and government agencies. Primary fieldwork across Mumbai, Sydney, Singapore, and Tokyo validated secondary estimates through bottom-up engagement sizing and top-down market reconstruction triangulation.
Variance decomposition across service type, deployment architecture, end-user vertical, and geographic jurisdiction dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs incorporated BFSI multi-cloud migration velocity, regulatory enforcement timelines for India's Digital Personal Data Protection Act, and chaos engineering adoption curves among fintech platforms.
Material uncertainties — regulatory reciprocity agreement delays, hyperscaler API changes disrupting testing toolchains, and certified engineer supply constraints in emerging markets — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance mandate enforcement intensity and enterprise cloud modernization cadence. Practitioners should keep alternative scenarios live as ASEAN cross-border certification frameworks and AI infrastructure standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Printing Machines Market
Others
Prunes Market
Others
Smart Badge Market
Others
Hardwood Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Global Electroshock Weapons Market
Others
Short Video Applications Market
Others
Free Space Optics (FSO) Market
Others
Solar Lighting Tower Market
Others
Global Human Augmentation Market
Others
Air Separation Plant Market
Others
ASEAN Agricultural Logistics Market
Others
Tobacco Packaging Market
Others
Fresh Pears Market
Others
Rope Market
Others
Roasted Wheat Market