
 Hotel Wardrobe Market | 2026-2036
Hotel Wardrobe Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel Wardrobe Market Analysis
Multi-source procurement is shifting toward vertically integrated partnerships as hotel developers seek shorter lead times for custom wardrobe programs. Kimball Hospitality leverages captive North American manufacturing to sustain rapid-turn contract fulfillment for major hospitality brands. Hongye Furniture Group anchors large-scale production capacity across Asian supply corridors. Artone Furniture differentiates through design-forward collections targeting boutique property segments.
A hotel wardrobe denotes a fixed or movable storage enclosure engineered for guest room apparel organization, typically constructed with 18mm-25mm substrate panels, soft-close hinge hardware, and integrated LED lighting systems. The primary commercial purpose centers on maximizing spatial efficiency while reinforcing property brand identity through material finish and hardware selection. Built-in wardrobes capture premium margin pools in luxury and resort deployments where architectural integration commands higher specification value. Modular systems represent the fastest-growing product type as operators prioritize flexible reconfiguration across renovation cycles. Wood and MDF substrates dominate material specifications, though metal framing gains traction in contemporary and minimalist design executions.
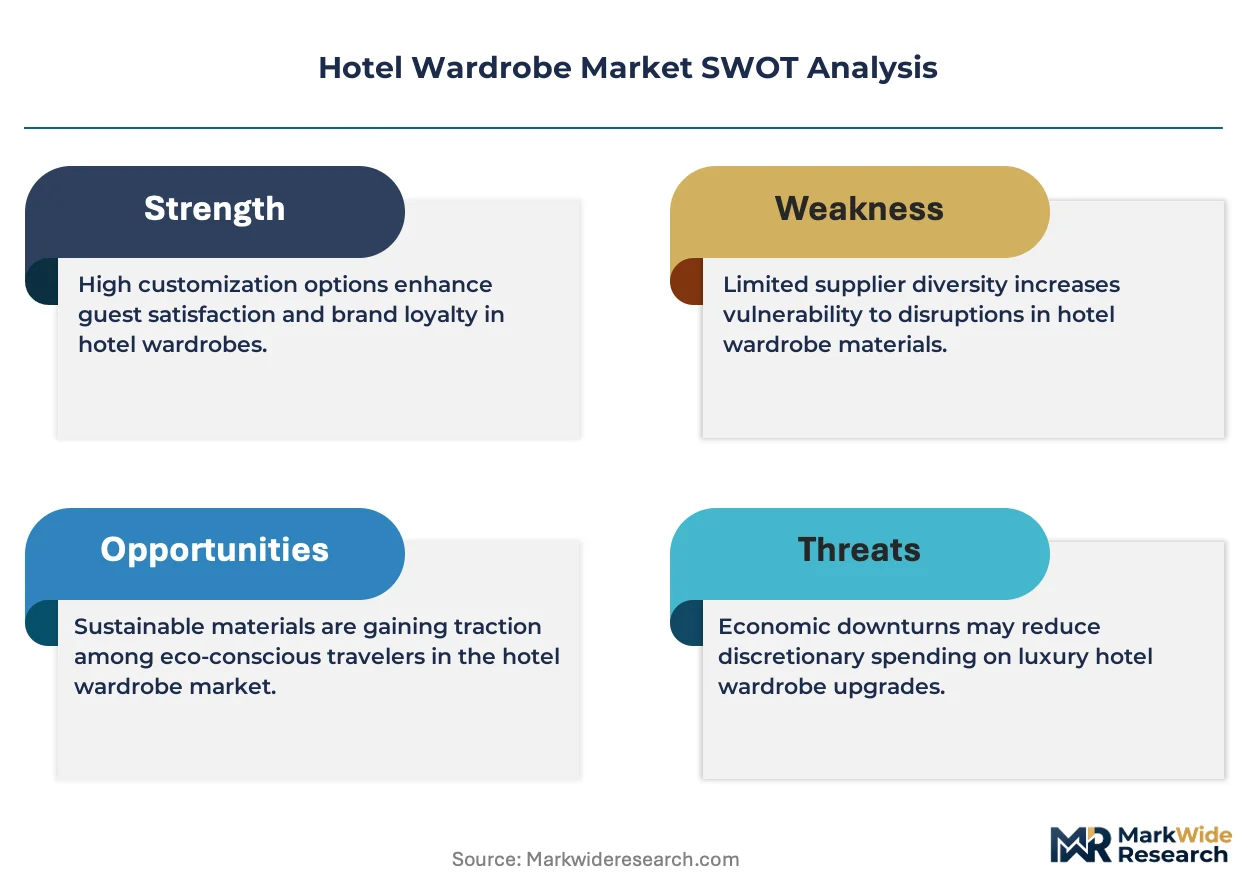
EPA formaldehyde emission standards under TSCA Title VI constrain panel substrate sourcing for US-bound production, while EU ECHA REACH restrictions on certain wood preservatives shape finishing chemistry choices for European hospitality projects. California Air Resources Board (CARB) Phase 2 compliance functions as a de facto national benchmark for low-emission furniture substrates across North American supply chains. Stakeholders must monitor evolving state-level material restrictions and third-party certification thresholds to maintain specification eligibility across multi-jurisdiction hotel portfolios.
Market Dynamics
California's Title 24 building efficiency standards are compressing specification timelines for hospitality developers, forcing wardrobe manufacturers to pre-certify substrate emissions before contract bidding. This regulatory pressure is reshaping competitive positioning toward vertically integrated suppliers with captive testing laboratories.
Growth Catalysts
- Boutique Hotel Expansion:Independent luxury properties in Dubai and Abu Dhabi are specifying custom fitted wardrobes as brand differentiation tools, driving procurement volume for premium architectural millwork.
- EPA TSCA Title VI Compliance:Formaldehyde emission standards for composite wood products have normalized low-emission substrate sourcing across North American hospitality supply chains.
- Modular System Adoption:Hotel operators are prioritizing reconfigurable wardrobe systems to reduce renovation downtime and extend furniture lifecycle across property refresh cycles.
Market Restraints
- Panel Substrate Cost Volatility:MDF and particleboard prices fluctuate with resin chemistry feedstock costs, compressing margin predictability for mid-tier wardrobe manufacturers.
- Asian Supply Concentration:Large-scale production capacity clusters in Guangdong and Zhejiang provinces create geopolitical and logistics risk exposure for Western hospitality developers.
- Technical Integration Limits:Legacy hotel properties face spatial constraints that prevent seamless installation of integrated LED lighting and soft-close hardware systems.
Strategic Opportunities
- Saudi Arabia Hospitality Construction:Giga-project developments along the Red Sea coast are generating specification demand for climate-resistant wardrobe materials with enhanced humidity tolerance.
- Circular Economy Mandates:EU Ecodesign for Sustainable Products Regulation is creating procurement preference for wardrobe systems with disassembly-ready construction and recycled content certification.
- Digital Specification Platforms:Building information modeling integration is enabling real-time customization of wardrobe dimensions during pre-construction phases, reducing field modification costs.
Industry Challenges
- Certification Timeline Compression:CARB Phase 2 and EPA TSCA Title VI testing protocols require 30-60 day laboratory cycles that conflict with accelerated hotel opening schedules.
- Skilled Installation Shortage:Unionized millwork installers in major US metropolitan markets command premium labor rates that inflate total installed cost for built-in wardrobe programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel Wardrobe Market |
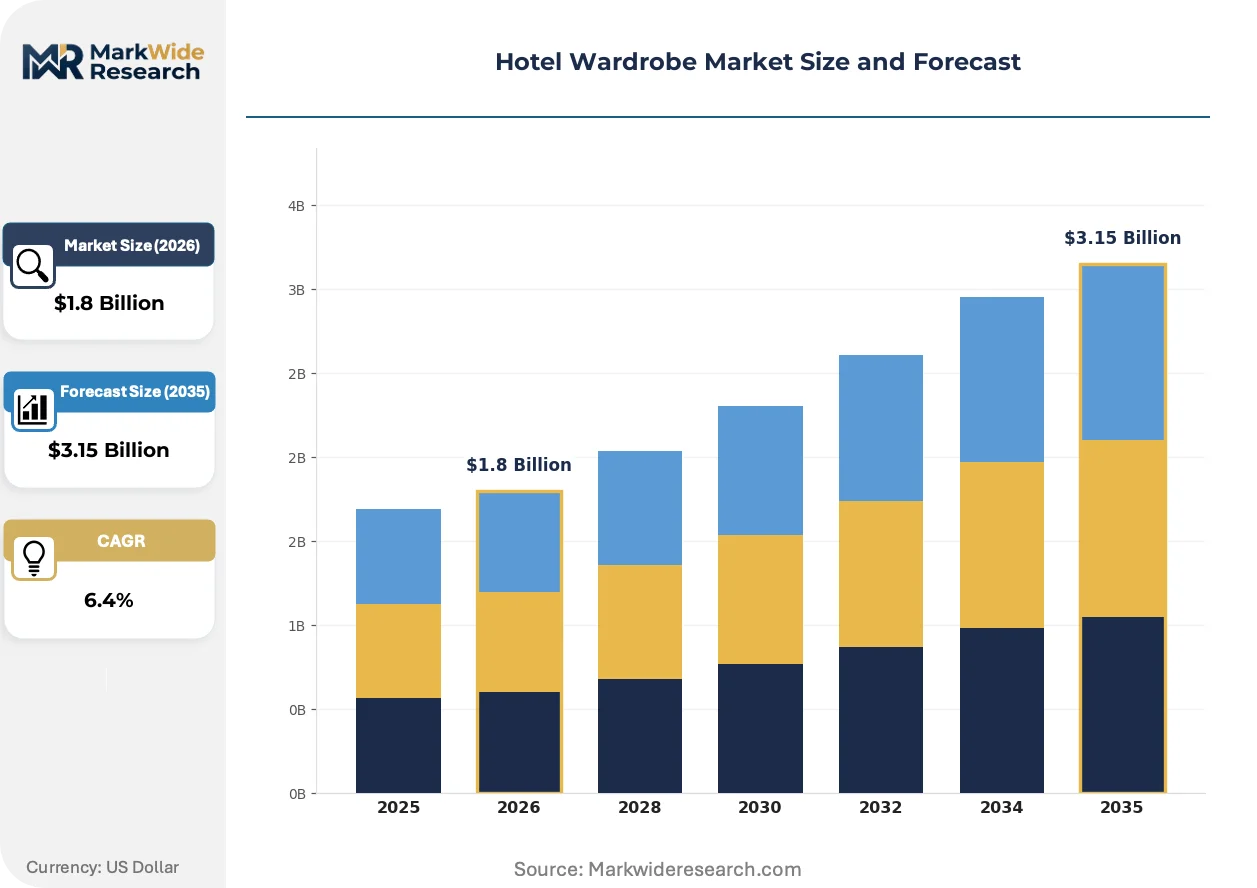
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Sliding Door, Modular Material: Wood, Metal, MDF, Particle Board Design Style: Contemporary, Traditional, Minimalist, Rustic End User: Luxury Hotels, Budget Hotels, Boutique Hotels, Resorts |
| Companies Covered | Kimball Hospitality, Hongye Furniture Group, Artone Furniture, Northland Furniture, Harman Furnishings, Curve Hospitality, Hotel Spec International, Vogue Decor Furniture, Hospitality Furniture Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel Wardrobe Market Emerging Trajectories
Digital fabrication and material science advances are converging to transform wardrobe manufacturing from standardized batch production toward mass-customized fulfillment. These developments are compressing lead times while expanding design flexibility for hospitality specifiers.
Computer numerical control routing combined with robotic edge banding is automating the production of complex wardrobe geometries previously requiring manual craftsmanship. Luxury resort developers in the Maldives and Seychelles are specifying these digitally fabricated units for curved wall integrations. The technology is automating quality consistency across high-mix, low-volume production runs that characterize boutique hotel procurement.
EU ECHA REACH restrictions on chromium VI in wood preservatives are forcing finish chemistry reformulation across European hospitality projects. Manufacturers serving Paris and London hotel markets are migrating toward water-based UV-cured coatings that eliminate hazardous air pollutant classification. This regulatory shift most acutely affects dark-stained wardrobe specifications where traditional acid-catalyzed finishes previously dominated.
Developer procurement teams are consolidating vendor relationships around vertically integrated partners offering design-through-installation accountability. Major hospitality brands in Singapore and Sydney are replacing fragmented multi-source purchasing with single-source wardrobe program contracts. This concentration trend is most visible in upper-upscale segments where brand consistency across property portfolios outweighs unit cost minimization.
Hotel Wardrobe Market Segmentation
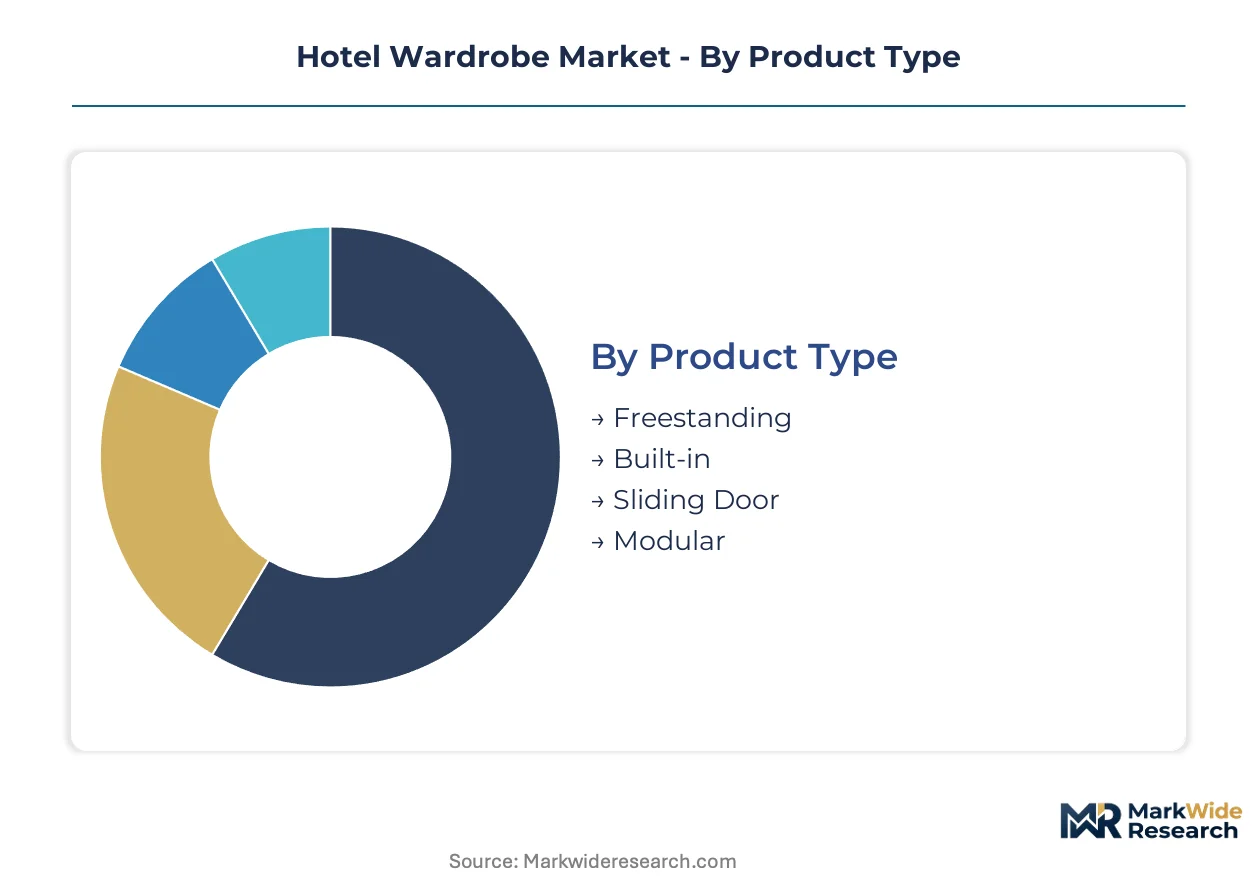
Wardrobe specification patterns diverge sharply across hospitality property tiers, with renovation cycles and brand refresh timelines driving segment selection. Understanding these partitions enables manufacturers to align production capacity with procurement velocity and margin profiles.
Product Type:
Upgrade and replacement cycles vary dramatically by installation permanence, dictating procurement lead times and vendor relationship structures.
- Freestanding:Portable units with independent structural frames allow rapid deployment without wall anchoring. Budget hotel chains in India prioritize these for accelerated property refreshes where minimal downtime governs vendor selection.
- Built-in:Architectural millwork integrated with wall systems commands specification in luxury Dubai developments where spatial optimization and brand cohesion justify extended installation schedules. Saudi Red Sea giga-projects are specifying humidity-resistant substrates for these permanent installations.
- Sliding Door:Space-efficient track systems suit compact urban guest rooms prevalent in Singapore and Hong Kong hospitality construction.
- Modular:Reconfigurable panel systems with standardized connection hardware enable component replacement across renovation cycles. European boutique operators under EU Ecodesign mandates specify disassembly-ready construction for circular compliance.
Built-in wardrobes sit at the top of the volume ranking, with modular systems climbing the fastest.
Material:
Cost tier positioning separates specification pools, with certification requirements filtering options at each price band.
- Wood:Solid hardwood and veneer substrates deliver premium tactile finishes for resort properties in the Maldives and Seychelles. CARB Phase 2 and EPA TSCA Title VI compliance now gates North American hospitality procurement, compressing qualified supplier pools.
- Metal:Powder-coated steel and aluminum framing systems suit contemporary design executions in Australian urban hotels. The segment gains traction where fire-rated construction and minimal maintenance cycles override material warmth preferences.
- MDF:Engineered fiberboard with consistent density enables precise CNC routing for complex geometries. Resin feedstock cost volatility constrains margin stability for mid-tier manufacturers serving European markets.
- Particle Board:Lower-density composite panels with cost advantages for high-volume production. ECHA REACH restrictions on formaldehyde emissions limit specification eligibility in EU hospitality projects.
Wood dominates value concentration, though metal is gaining share fastest in contemporary design segments.
Design Style:
Application context—urban business hotels versus leisure resorts—determines style specification more than property tier alone.
- Contemporary:Clean lines and neutral palettes align with international brand standards across Marriott and Hilton portfolios. Water-based UV-cured coatings replace acid-catalyzed finishes under ECHA chromium VI restrictions.
- Traditional:Ornate molding and rich stain executions persist in heritage property renovations across London and Paris. Dark-stained specifications face acute chemistry reformulation pressures from EU wood preservative regulations.
- Minimalist:Concealed hardware and flush surfaces suit Japanese hospitality aesthetics and Scandinavian-influenced Nordic properties.
- Rustic:Distressed finishes and reclaimed material aesthetics target eco-resort positioning in Costa Rica and Indonesian archipelago developments.
Contemporary styling holds the broadest cross-regional applicability, with minimalist designs expanding most quickly in Asia-Pacific urban construction.
End User:
Customer procurement sophistication and specification authority concentration shape vendor engagement models across hospitality tiers.
- Luxury Hotels:Custom architectural millwork with integrated LED lighting and soft-close hardware commands extended design development cycles. Dubai and Abu Dhabi developments drive specification volume for premium fitted installations with brand-differentiated material selections.
- Budget Hotels:Standardized modular systems with rapid-turn fulfillment requirements dominate procurement. Indian and Southeast Asian expansion programs prioritize unit cost minimization over customization depth.
- Boutique Hotels:Design-forward collections with unique spatial configurations reward flexible manufacturing capabilities. Independent properties in Sydney and Singapore consolidate vendor relationships around single-source accountability.
- Resorts:Climate-resistant construction with enhanced humidity and salt-air tolerance governs material specification. Saudi Red Sea and Maldives developments specify certified substrates for marine environment durability.
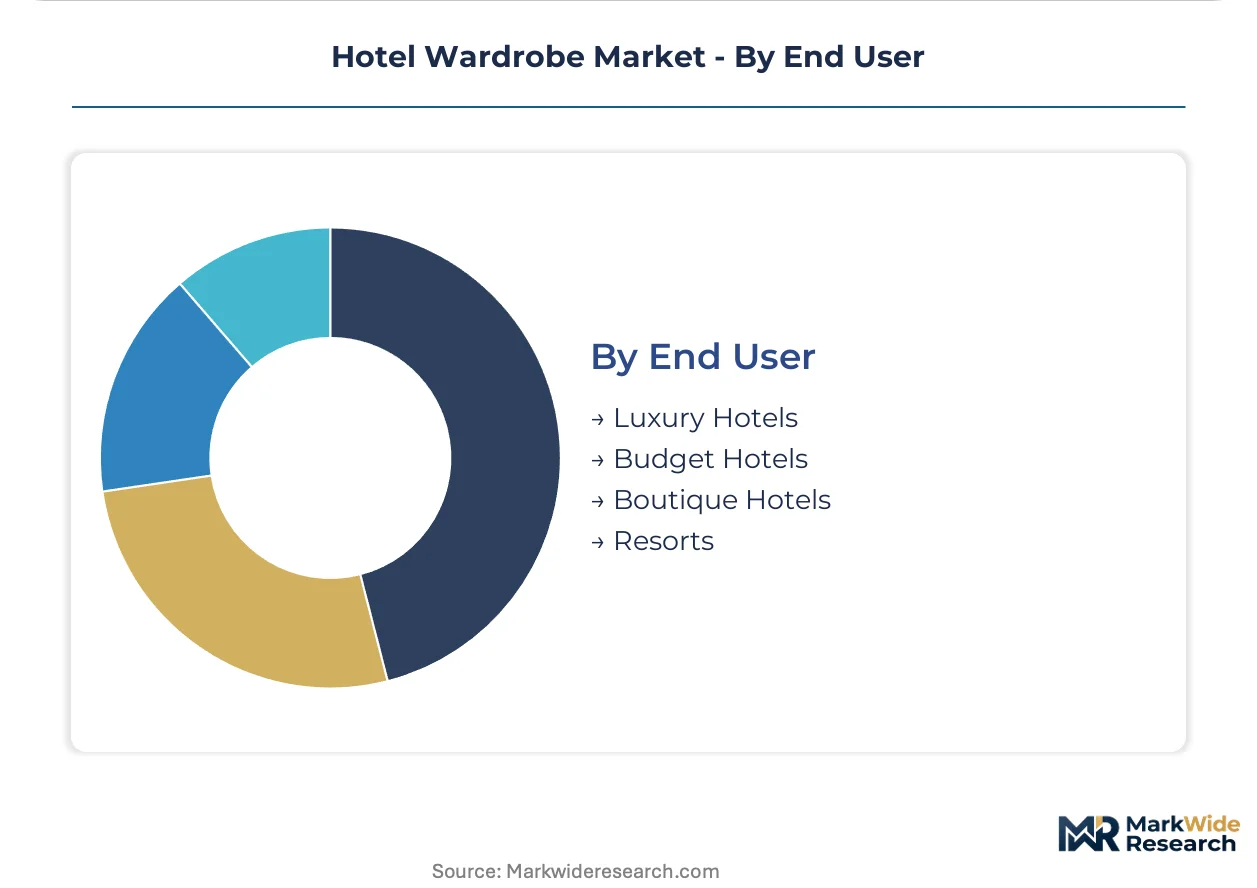
Luxury hotels anchor specification value, with boutique properties demonstrating the steepest expansion trajectory in custom wardrobe procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined certification protocols. Compliance cost differentials between emission-standard regimes now shape facility location decisions more than labor arbitrage alone.
United States
California's Title 24 building efficiency standards mandate low-emission materials in commercial furniture, compressing specification timelines for hospitality developers. EPA TSCA Title VI compliance functions as a de facto national benchmark for composite wood products across North American supply chains. Los Angeles and San Francisco hospitality construction drives demand for certified wardrobe substrates with rapid-turn fulfillment.
United Arab Emirates
Dubai and Abu Dhabi hospitality developments generate specification volume for premium fitted wardrobe installations as boutique hotel chains expand procurement of custom systems. MOHAP building codes emphasize fire-rated construction materials in high-rise hotel applications. Jebel Ali industrial corridor hosts fabrication facilities serving Red Sea giga-project developments with climate-resistant material specifications.
Germany
EU ECHA REACH restrictions on chromium VI in wood preservatives force finish chemistry reformulation for hospitality projects across Berlin and Munich markets. EU Ecodesign for Sustainable Products Regulation creates procurement preference for disassembly-ready wardrobe construction. North Rhine-Westphalia manufacturing clusters specialize in water-based UV-cured coating systems for dark-stained specifications.
China
Guangdong and Zhejiang provinces concentrate large-scale production capacity for global hospitality supply, though geopolitical risk exposure concerns Western developers. GB standards for formaldehyde emissions in wood-based panels align with export market requirements. Shenzhen and Dongguan furniture manufacturing hubs automate CNC routing for complex wardrobe geometries previously requiring manual craftsmanship.
Saudi Arabia
Red Sea coast giga-project developments generate specification demand for climate-resistant wardrobe materials with enhanced humidity tolerance. SFDA building product regulations govern material safety certification for hospitality installations. NEOM construction corridors attract vertically integrated suppliers offering design-through-installation accountability for luxury resort deployments.
Hotel Wardrobe Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular reconfiguration and circular-economy compliance as differentiation vectors. The vendor base stratifies across three capability tiers: captive manufacturing with in-house substrate certification, design-forward boutiques serving independent properties, and scale-driven fabricators optimizing for budget-segment volume. Strategic moves concentrate on backward integration into panel substrate production and single-source contract consolidation replacing fragmented multi-source procurement.
Among North American-based suppliers, Kimball Hospitality exemplifies the vertically integrated archetype with captive manufacturing assets. Hongye Furniture Group anchors the scale-driven tier with production capacity concentrated across Asian supply corridors. Artone Furniture occupies a position within the design-forward segment targeting boutique property specifications with flexible manufacturing capabilities.
| Leading Market Players |
|---|
| Kimball Hospitality |
| Hongye Furniture Group |
| Artone Furniture |
| Northland Furniture |
| Harman Furnishings |
| Curve Hospitality |
| Hotel Spec International |
| Vogue Decor Furniture |
| Hospitality Furniture Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in Guangdong and Zhejiang provinces anchor supply capacity while exercising disciplined pricing power over Western hospitality developers facing compressed certification timelines. Their ownership structure enables patient capital deployment into captive substrate testing laboratories, creating margin buffers against resin feedstock volatility that publicly traded competitors cannot match.
Pricing Analysis
Distributor margins for European-bound wardrobe systems absorb ECHA REACH compliance costs through layered markups that cascade from factory gate to hotel developer. Three-tier pricing structure across premium, standard, and economy levels separates CARB Phase 2 certified substrates from uncertified alternatives and from luxury architectural millwork with integrated LED systems. Pricing pressure stems from MDF resin feedstock volatility compressing mid-tier manufacturer margins. Budget hotel chains in India exhibit highest price sensitivity, while Dubai luxury developers prioritize specification value over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Marriott and Hilton portfolios, bypassing distributor layers for volume commitments above property-wide wardrobe programs. Production gravity centers on China, Vietnam, and Malaysia, with Guangdong province hosting automated CNC routing clusters for complex geometries. Raw material dependencies encompass urea-formaldehyde resins, soft-close hinge hardware, and aluminum track systems. Single-source vulnerability concentrates in Chinese panel substrate supply facing geopolitical friction. Distribution runs through vertically integrated partners offering design-through-installation accountability for boutique hotel segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hotel Wardrobe Market functions as a stable compounder anchored by renovation-cycle replacement demand that recurs regardless of new construction velocity. Regulatory compliance requirements create durable competitive moats around certified substrate suppliers.
For Market Incumbents: Hedge against Asian supply concentration by establishing captive North American manufacturing footprints with in-house EPA TSCA Title VI testing capabilities. Diversify substrate sourcing across multiple resin chemistry suppliers to buffer margin volatility. Certification timeline compression from California Title 24 mandates demands pre-certified inventory positions that only backward integration can sustain. For New Entrants and Emerging Players: The gap between premium fitted installations and economy modular systems offers white-space entry for mid-tier competitors with flexible CNC fabrication. Target Saudi Red Sea giga-projects where climate-resistant material specifications remain undersupplied by incumbent capacity. Pursue single-source contract consolidation opportunities with Singapore and Sydney boutique operators replacing fragmented procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among scale-driven fabricators lacking design-forward capabilities but possessing certified substrate access. Five-to-ten-year viability favors vertically integrated specialists with captive testing laboratories over pure-play distributors. Monitor EU Ecodesign for Sustainable Products Regulation implementation as inflection signal for circular-economy-compliant acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Substrate Production | Captive EPA TSCA Title VI certification compresses bidding timelines for California hospitality developers. |
| Climate-Resistant Material Certification | Saudi SFDA building product regulations mandate humidity-tolerant substrates for Red Sea resort deployments. |
| Single-Source Contract Consolidation | Sydney boutique operators replace fragmented procurement with design-through-installation accountability partners. |
| Water-Based UV-Cured Coating Transition | ECHA REACH chromium VI restrictions force chemistry reformulation for Paris and London hotel markets. |
| Digital Specification Platform Integration | Building information modeling enables real-time wardrobe customization during pre-construction phases. |
Methodological Framework
Direct dialogue with hotel procurement directors, millwork installation contractors, furniture manufacturing plant managers, and regulatory compliance officers grounded qualitative insights. Secondary validation drew from EPA TSCA Title VI certification databases, CARB Phase 2 compliance registries, EU ECHA REACH substance restrictions, hospitality construction permit filings, and trade customs records for panel substrate imports. Bottom-up property-level demand estimation triangulated against top-down sector spending analysis.
Top-down analytical lenses modeled hospitality construction pipelines and renovation cycle frequencies across property tiers. Segmentation dimensions encompassed product type, material substrate, design style, and end-user tier. CAGRs derived from regression analysis of historical specification volumes against regulatory implementation timelines and construction activity indices. Forecast inputs incorporated resin feedstock price trajectories and certification laboratory capacity constraints.
Caveats apply where resin chemistry cost spikes or geopolitical trade restrictions could materially shift the outlook for Asian supply-dependent Western developers. Forecasts reflect assumptions about regulatory enforcement continuity and hospitality construction schedule adherence. Periodic stress-testing of base assumptions against panel substrate price volatility and certification timeline compression is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fiberglass Storage Tanks Market
Others
Brazil Lime Market
Others
Global Contactless Biometrics Technology Market
Others
Quadrant Scale Market
Others
Latin America Automotive HVAC Market
Others
Video-As-A-Service (Vaas) Market
Others
Folding Smartphone Market
Others
India Battery E-Commerce Market
Others
ASEAN Agricultural Logistics Market
Others
Nyerereite Market
Others
Folding Screen Mobile Phone Market
Others
Moveable Water Tap Market
Others
5G Edge Computing Market
Others
Latin America Travel Retail Market
Others
Liquid-Cooled Heat Sink Market
Others
Cloud Advertising Market