
 China Packaging Primers Market | 2026-2036
China Packaging Primers Market Size, Share, and Industry Trends Forecast 2026-2036
China Packaging Primers Market Outlook
The split between premium performance primers and commodity-grade alternatives is shifting as food and pharmaceutical converters demand migration-compliant, low-VOC formulations while cost-driven beverage packers retain solvent-based alkyd systems. Henkel leverages its European regulatory expertise to position high-purity epoxy primers for pharmaceutical blister packs. Jiangsu Yangrui New Materials anchors domestic supply through integrated resin-to-primer manufacturing in Taizhou. PPG Industries competes on automotive-adjacent coating technology transferred to rigid metal packaging applications.
Packaging primers constitute thin-film coating systems applied to metal, plastic, or paper substrates to promote adhesion of inks, lacquers, or barrier layers, typically formulated at 5–25 micron dry-film thickness with controlled surface energy between 38–48 dynes per centimeter for optimal overprint compatibility. Acrylic primers lead volume in flexible food packaging due to their balance of cost and heat-seal adhesion, while polyurethane primers capture margin pools in pharmaceutical cold-form foil where barrier integrity demands justify premium pricing. Epoxy primers sustain growth in metal beverage can interiors as SAMR migrates toward GB food-contact standards aligned with EU Regulation 10/2011 testing protocols.
China's national standards administration under SAMR enforces GB 4806 series food-contact material limits, while MEE implements VOC emission controls under the 14th Five-Year Plan that directly constrain solvent-based primer formulations in Yangtze River Delta manufacturing zones. The dual carbon policy pressures converters toward waterborne and UV-cure systems, reshaping supplier qualification requirements. Stakeholders must monitor provincial MEE enforcement intensity and GB standard revision timelines to align product portfolios with compliance windows.
Market Dynamics
Waterborne acrylic primer formulations are displacing solvent-based systems across China's eastern coastal manufacturing corridor as MEE enforces VOC emission controls under the 14th Five-Year Plan, compressing qualification timelines for converters in Shanghai and Jiangsu.
Growth Catalysts
- MEE VOC emission controls:Yangtze River Delta manufacturing zones face tightening solvent-based formulation limits, accelerating converter migration to compliant waterborne systems.
- Food-contact safety upgrades:SAMR's GB 4806 series revisions demand migration-compliant primers for flexible food packaging, expanding addressable premium formulation demand.
- Pharmaceutical cold-form foil:Barrier integrity requirements in blister pack applications pull polyurethane primer consumption as domestic pharmaceutical output scales.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and epoxy resin input costs fluctuate with naphtha cracking economics, compressing formulation margin pools for mid-tier suppliers.
- Taizhou supply concentration:Integrated resin-to-primer manufacturing clusters in Jiangsu province create geographic single-point vulnerability for domestic waterborne acrylic supply.
- Alkyd system persistence:Cost-driven beverage packers retain solvent-based alkyd primers where MEE enforcement intensity varies by provincial jurisdiction, fragmenting technology transition timelines.
Strategic Opportunities
- Guangdong converter expansion:Pearl River Delta food packaging manufacturers are expanding primer consumption as SAMR tightens food-contact material safety standards.
- UV-cure system convergence:Dual carbon policy pressures intersect with energy-cure technology maturation, opening qualification windows for low-energy curing architectures in metal can interiors.
- Pharmaceutical blister pack premiumization:High-purity epoxy primer demand for cold-form foil applications expands as domestic pharmaceutical packaging aligns with EU Regulation 10/2011 testing protocols.
Industry Challenges
- Formulation chemist scarcity:Waterborne acrylic and UV-cure expertise pools concentrate in Shanghai and Suzhou, constraining converter technical service bandwidth in interior provinces.
- Dual certification timelines:GB 4806 compliance testing plus provincial MEE emission permitting creates extended qualification cycles for new primer introductions.
- Legacy solvent system retrofit:Existing coating line drying infrastructure requires capital-intensive modification to handle waterborne film formation kinetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Packaging Primers Market |
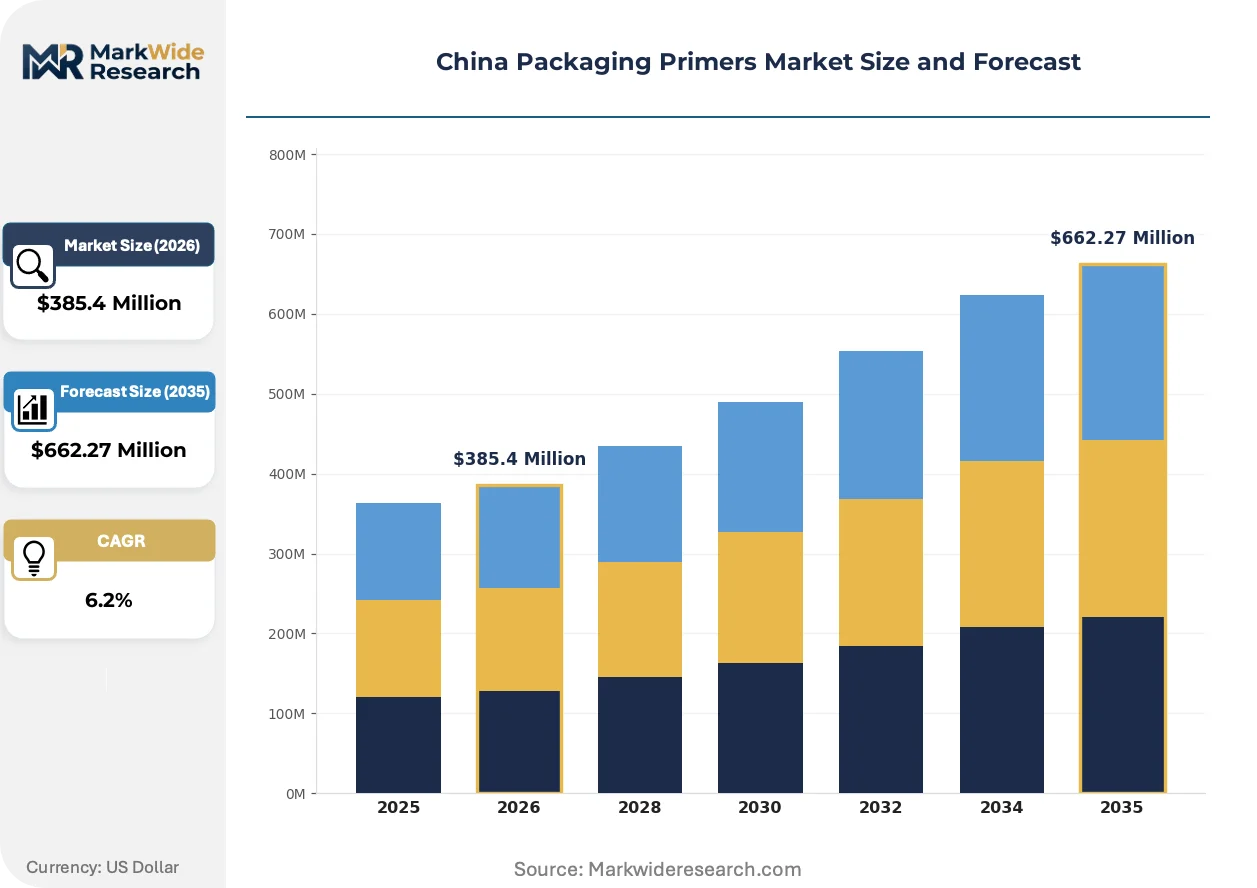
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Primers, Alkyd Primers, Polyurethane Primers, Epoxy Primers Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Cosmetic Packaging Form: Liquid, Powder, Paste, Spray End User: Manufacturers, Retailers, Distributors, Converters |
| Companies Covered | Henkel, Sherwin-Williams, PPG Industries, DIC Corporation, Flint Group, BASF SE, Axalta Coating Systems, Sun Chemical Group, Jiangsu Yangrui New Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Packaging Primers Market Strategic Shifts
Active reformulation across substrate categories is compressing technology transition windows as regulatory compliance deadlines harden and converter qualification protocols tighten.
Waterborne acrylic primer technology is rewriting adhesion performance benchmarks in flexible food packaging. Shanghai-based advanced converters are adopting these systems at accelerated pace as SAMR compliance deadlines approach. The shift is compressing solvent-based supplier margins while elevating formulation purity requirements across the eastern coastal corridor.
SAMR's GB 4806 series alignment with EU food-contact testing protocols is restructuring pharmaceutical packaging primer specifications. Domestic blister pack manufacturers must now demonstrate migration compliance previously reserved for export-oriented production. Metal can interior coating operations face the steepest reformulation curves as epoxy primer purity thresholds tighten.
Converter procurement patterns are compressing supplier qualification cycles from historical 18-month windows toward 8-12 month timelines. Large food packers in Jiangsu are unbundling technical service from material supply, forcing primer vendors to demonstrate standalone formulation support capability. This behavioral shift is most visible among multinational-affiliated converters in Suzhou and Wuxi industrial zones.
China Packaging Primers Market Segmentation
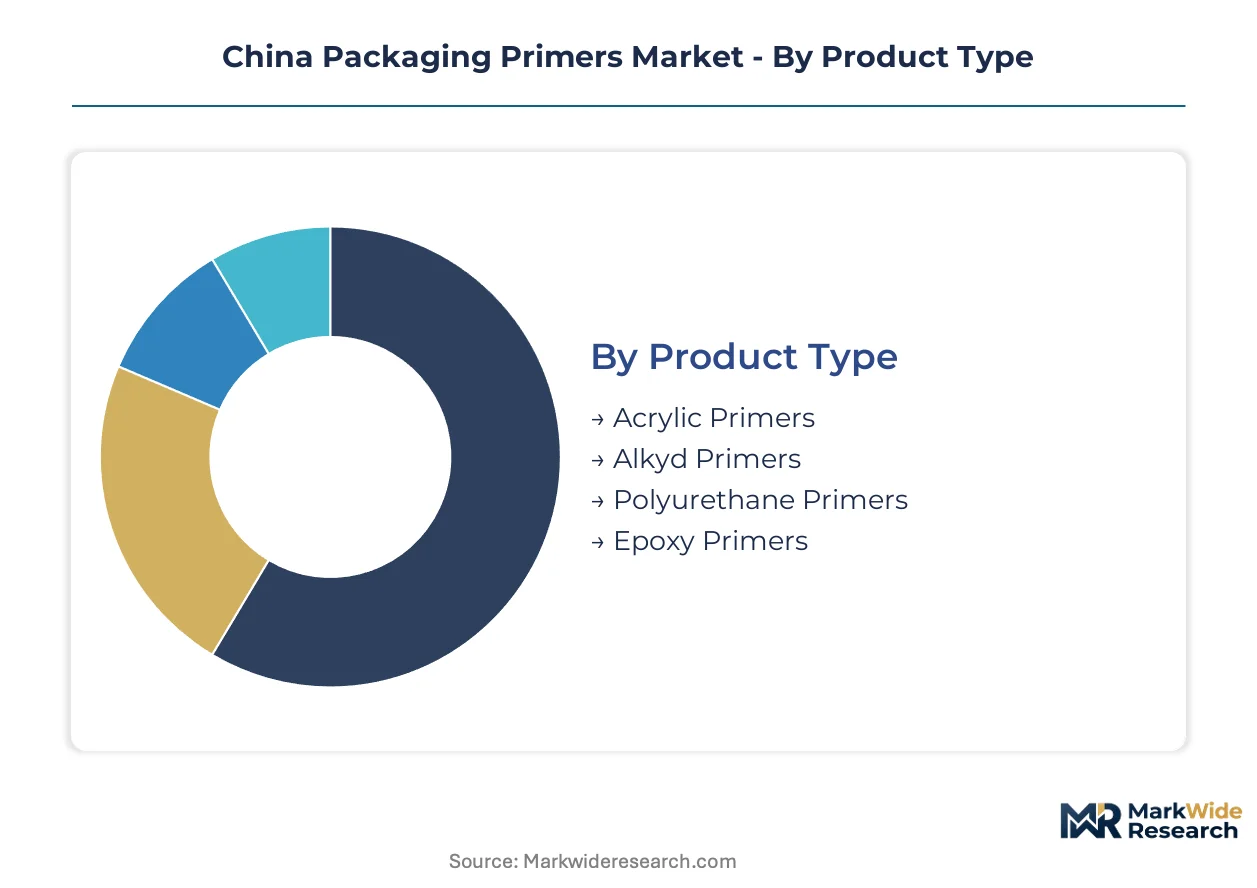
Primer selection in China hinges on substrate compatibility, curing infrastructure, and migration compliance under SAMR's GB 4806 series. Segmentation reveals divergent technology adoption curves between coastal converters with advanced coating lines and interior packers running legacy solvent systems.
Product Type:
Volume concentration favors commodity acrylics, while premium pricing attaches to specialized barrier-grade formulations.
- Acrylic Primers:Waterborne formulations dominate flexible food packaging with balanced adhesion and heat-seal performance. Jiangsu converters in Taizhou and Suzhou industrial zones are expanding procurement as MEE VOC deadlines compress qualification timelines.
- Epoxy Primers:High-purity systems command pharmaceutical blister pack specifications where barrier integrity demands justify elevated pricing. Metal can interior applications in Shanghai are migrating toward these formulations as SAMR aligns testing protocols with EU Regulation 10/2011.
- Polyurethane Primers:Cold-form foil applications in pharmaceutical packaging leverage these systems for superior moisture barrier adhesion.
- Alkyd Primers:Solvent-based persistence among cost-driven beverage packers in provincial jurisdictions with variable MEE enforcement intensity.
Mature deployment sits with alkyd systems in legacy beverage can lines. Newer deployment is concentrated in waterborne acrylic and high-purity epoxy formulations across Yangtze River Delta manufacturing zones.
Application:
Regulatory stringency varies sharply across end-use categories, creating tiered compliance investment requirements.
- Food Packaging:Flexible film converters face the steepest GB 4806 migration compliance curves. Shanghai-based advanced packers are unbundling technical service from material supply, forcing primer vendors to demonstrate standalone formulation support.
- Pharmaceutical Packaging:Blister pack and cold-form foil specifications demand the highest formulation purity tiers. Domestic pharmaceutical output scaling is pulling polyurethane and epoxy primer consumption as manufacturers align with EU-equivalent testing protocols.
- Beverage Packaging:Metal can interior coatings face reformulation pressure, though alkyd system retention persists where provincial MEE enforcement lags.
- Cosmetic Packaging:Aesthetic finish requirements drive specialized primer specifications with shorter qualification cycles than food or pharmaceutical grades.
Regulatory pressure concentrates in food and pharmaceutical applications. Cosmetic and select beverage segments retain formulation flexibility.
Form:
Coating line infrastructure and curing energy availability dictate form selection across China's manufacturing corridor.
- Liquid:Dominant form factor across all substrate categories with established spray and roll-coat application infrastructure. Waterborne liquid formulations are displacing solvent systems in Shanghai and Jiangsu as MEE emission controls tighten.
- Spray:Precision application for metal can interiors and complex cosmetic packaging geometries. UV-cure spray systems are gaining traction under dual carbon policy pressures.
- Powder:Limited penetration constrained by substrate heat tolerance requirements in flexible packaging applications.
- Paste:Niche deployment in specialty cosmetic and high-build industrial packaging with manual or semi-automated application.
Liquid systems anchor installed capacity. Spray configurations are climbing the fastest among converters retrofitting for energy-cure technologies.
End User:
Procurement sophistication diverges sharply between multinational-affiliated converters and domestic independent packers.
- Converters:Technical gatekeepers who specify primer formulations and control supplier qualification. Large food packers in Jiangsu are compressing vendor approval cycles from historical 18-month windows toward 8-12 month timelines.
- Manufacturers:Brand-owning packers with direct SAMR compliance liability are consolidating primer procurement at corporate level. Pharmaceutical manufacturers in Guangdong are expanding primer consumption as safety standards tighten.
- Distributors:Channel intermediaries serving fragmented interior province packers with limited technical service capability.
- Retailers:Minimal direct procurement; specification influence operates through private-label packaging requirements.
Specification authority concentrates with converters and brand-owning manufacturers. Distributor and retailer channels serve price-sensitive volume tiers with reduced technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial corridor dominates China's packaging primers activity, with Shanghai and Jiangsu province hosting the densest concentration of advanced coating converters and waterborne formulation expertise.
Yangtze River Delta
Flexible food packaging manufacturers in Suzhou and Wuxi industrial zones are expanding waterborne acrylic primer procurement as MEE enforces VOC emission deadlines under the 14th Five-Year Plan. SAMR's GB 4806 series revisions demand migration-compliant formulations. Taizhou anchors domestic resin-to-primer manufacturing capacity with integrated production clusters serving eastern coastal demand.
Pearl River Delta
Guangdong province food packers are accelerating primer consumption as SAMR tightens food-contact material safety standards for export-oriented production. The dual carbon policy pressures converters toward low-VOC systems. Shenzhen and Dongguan manufacturing zones concentrate pharmaceutical blister pack capacity pulling high-purity epoxy primer demand.
Beijing-Tianjin-Hebei
Metal beverage can coating operations in Tianjin face the steepest reformulation curves as MEE emission controls tighten around the capital region. SAMR aligns testing protocols with EU Regulation 10/2011. Legacy solvent-based alkyd retention persists where provincial enforcement intensity lags coastal benchmarks.
Sichuan-Chongqing
Western China packaging converters are retrofitting coating lines for waterborne film formation kinetics as MEE extends VOC controls beyond coastal zones. Formulation chemist scarcity constrains technical service bandwidth. Chongqing's automotive-adjacent coating expertise transfers to rigid metal packaging applications.
Shandong Peninsula
Qingdao and Yantai industrial zones host specialty cosmetic packaging manufacturers driving shorter qualification cycles than food or pharmaceutical grades. Petrochemical feedstock volatility in acrylic acid and epoxy resin inputs compresses margin pools. Regional distributors serve fragmented interior province packers with limited technical support capability.
China Packaging Primers Market Competitive Environment
Capital-heavy integrated resin producers compete with asset-light formulation specialists across China's packaging primers sector. The market structure tilts toward consolidation among multinational coating conglomerates with European regulatory expertise, while domestic mid-tier suppliers fragment around commodity acrylic formulations. Three archetypes dominate: multinational technology licensors leveraging automotive coating transfer, integrated Chinese resin-to-primer manufacturers with captive raw material security, and regional distributors serving price-sensitive interior packers. Competitive intensity centers on MEE compliance qualification speed and SAMR migration testing certification.
Within the multinational technology tier, Henkel and PPG Industries occupy positions anchored by European regulatory expertise and automotive-adjacent coating technology respectively. Jiangsu Yangrui New Materials exemplifies the integrated domestic archetype with its Taizhou-based resin-to-primer manufacturing cluster. These three entities represent the strategic poles around which qualification timelines, formulation purity thresholds, and technical service capabilities reorganize competitive positioning across China's eastern coastal manufacturing corridor.
| Leading Market Players |
|---|
| Henkel |
| Sherwin-Williams |
| PPG Industries |
| DIC Corporation |
| Flint Group |
| BASF SE |
| Axalta Coating Systems |
| Sun Chemical Group |
| Jiangsu Yangrui New Materials |
| Others |
Value Chain & Pricing Dynamics
Acrylic acid spot pricing in Asian petrochemical benchmarks cascades through China's packaging primers supply chain, compressing margin pools for mid-tier waterborne formulation suppliers while concentrating pricing power among integrated resin-to-primer manufacturers in Taizhou and captive epoxy producers serving pharmaceutical blister pack specifications.
Pricing Analysis
Yield-based pricing anchors premium tiers in pharmaceutical cold-form foil applications where barrier integrity failures carry batch-rejection costs. Three-tier pricing structure across migration-certified, standard-grade, and commodity alkyd levels separates SAMR-compliant epoxy systems from solvent-based alternatives. Cost compression in waterborne acrylic tiers is intensifying because Jiangsu converters are unbundling technical service from material supply. Beverage packers in provincial jurisdictions with variable MEE enforcement intensity exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premium pricing for EU Regulation 10/2011-aligned testing protocols.
Supply Chain Analysis
Formulation chemist availability constraints in Shanghai and Suzhou are forcing converters to source technical service from distant qualified suppliers, extending lead times for waterborne system qualification. Raw material supply concentrates in China, South Korea, and Japan for acrylic acid, epoxy resins, and polyurethane intermediates. Naphtha cracking economics and petrochemical feedstock volatility create margin instability for non-integrated suppliers. Distribution runs through converter-direct contracts for large Yangtze River Delta packers, with regional distributors serving fragmented interior province demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's packaging primers sector is consolidating around backward integration into captive resin production, with SAMR compliance certification and MEE emission permitting emerging as the decisive upstream levers separating viable scale players from margin-compressed commodity suppliers.
For Market Incumbents: Lock in converter relationships by embedding technical service teams within Suzhou and Wuxi industrial zones, compressing qualification cycles from historical 18-month windows toward 8-12 month benchmarks. Secure captive acrylic acid supply through offtake agreements with Taizhou petrochemical complexes to defend against naphtha volatility eroding waterborne formulation margins.
For New Entrants and Emerging Players: Launch via UV-cure system specialization targeting metal can interior retrofits in Tianjin and Beijing-Tianjin-Hebei manufacturing zones where dual carbon policy pressures intersect with legacy solvent line replacement cycles. Pharmaceutical cold-form foil applications in Shenzhen and Dongguan offer the most penetrable premium segment given barrier integrity requirements that justify elevated pricing and technical service investment.
For Investors and Strategic Acquirers: The window for entry favors integrated resin-to-primer manufacturers with SAMR migration testing certification and established MEE permitting relationships in Jiangsu or Guangdong provinces. Long-term viability across the analysis window hinges on waterborne and UV-cure technology portfolios aligned with 14th Five-Year Plan emission trajectories. Watch provincial MEE enforcement intensity dispersion as the inflection signal separating coastal compliance acceleration from interior alkyd system persistence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive resin supply insulates Taizhou manufacturers from naphtha cracking volatility compressing mid-tier margins. |
| SAMR Migration Testing Certification | GB 4806 series compliance opens pharmaceutical blister pack specifications previously reserved for export-oriented production. |
| UV-Cure System Qualification | Energy-cure technology captures dual carbon policy-driven retrofit demand in Tianjin metal can coating operations. |
| Technical Service Embedding | On-site formulation support in Suzhou industrial zones accelerates converter procurement decisions and locks out distant competitors. |
| Provincial MEE Permitting Expansion | Early emission control compliance in Guangdong positions suppliers ahead of SAMR's tightening food-contact material safety standards. |
Study Parameters
Multi-period observation of MEE enforcement intensity dispersion, SAMR GB standard revision timelines, and acrylic acid spot pricing volatility anchored the trend analysis, supplemented by interviews with coating line engineers at Jiangsu flexible film converters, procurement directors at Guangdong pharmaceutical packers, formulation chemists in Shanghai technical service centers, and resin plant managers in Taizhou petrochemical complexes. Secondary validation drew from customs export data, SAMR regulatory filings, ACC regional petrochemical reports, and SEC disclosures from multinational coating conglomerates. Bottom-up primer consumption estimates triangulated against top-down packaging output projections.
Segment-weighting across product type, application, form, and end-user dimensions calibrated value and volume distributions throughout the forecast period. CAGRs derived from regression analysis of historical primer intensity ratios against packaging substrate output, with explicit modeling of waterborne displacement rates in Yangtze River Delta zones and UV-cure adoption curves under dual carbon policy pressure. Industry-specific inputs included SAMR migration testing protocol alignment schedules and provincial MEE VOC deadline enforcement variance.
Feedstock price volatility, regulatory enforcement intensity dispersion, and technology transition timing are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about SAMR-EU testing protocol convergence and MEE 14th Five-Year Plan implementation consistency. Material deviation in naphtha cracking economics or provincial permitting timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Tester Market
Others
Mobile Computing Devices Market
Others
Global Compact Wheel Loaders Market
Others
Kuwait Retail Market
Others
Wood Stoves Market
Others
Computer on Module Market
Others
Storage Dewars Market
Others
Europe Street Lighting Market
Others
Cremation Furnace Market
Others
Global Bio-Based Chemicals Market
Others
Rope Market
Others
North America Machine Vision Systems Market
Others
5G Devices Market
Others
Dried Egg Market
Others
Next Gen Video Codecs Market
Others
UK Automotive LED Lighting Market