
 Air Separation Plant Market | 2026-2036
Air Separation Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Air Separation Plant Market Intelligence
Compliance with the ASME Boiler and Pressure Vessel Code (BPVC) is redrawing the competitive landscape for plant engineering and construction, setting a high barrier for new entrants. Global leaders like Linde plc leverage their extensive engineering capabilities and operational scale to secure large-volume contracts. Air Liquide SA differentiates through its focus on high-purity gas solutions for the electronics and healthcare sectors. Meanwhile, Air Products and Chemicals, Inc. sustains its market position through long-term, on-site supply agreements with major industrial clients in key geographies.
An air separation plant is an industrial facility designed to separate atmospheric air into its primary components. The core process often involves cryogenic fractional distillation, where air is cooled to temperatures below -180°C to liquefy and then separate gases based on their different boiling points. This process yields high-purity nitrogen, oxygen, and argon for industrial and medical applications. Cryogenic Air Separation Units constitute the largest product segment, serving high-volume end users like steel mills and chemical manufacturers. Conversely, non-cryogenic technologies such as Pressure Swing Adsorption (PSA) are gaining traction for smaller, on-site requirements in food & beverage and electronics production.
The market operates within a stringent regulatory framework that influences both plant design and operational standards. In the United States, EPA rules governing industrial emissions drive demand for oxygen in cleaner combustion processes. European Union regulations like REACH and the F-Gas Regulation impact the choice of refrigerants and solvents used in separation cycles. Concurrently, WHO guidelines on medical oxygen quality create a distinct standard for plants supplying the healthcare sector. The key strategic decision for end-users now pivots on choosing between large-scale, third-party supply contracts and investing in captive, on-site generation assets.
Market Dynamics
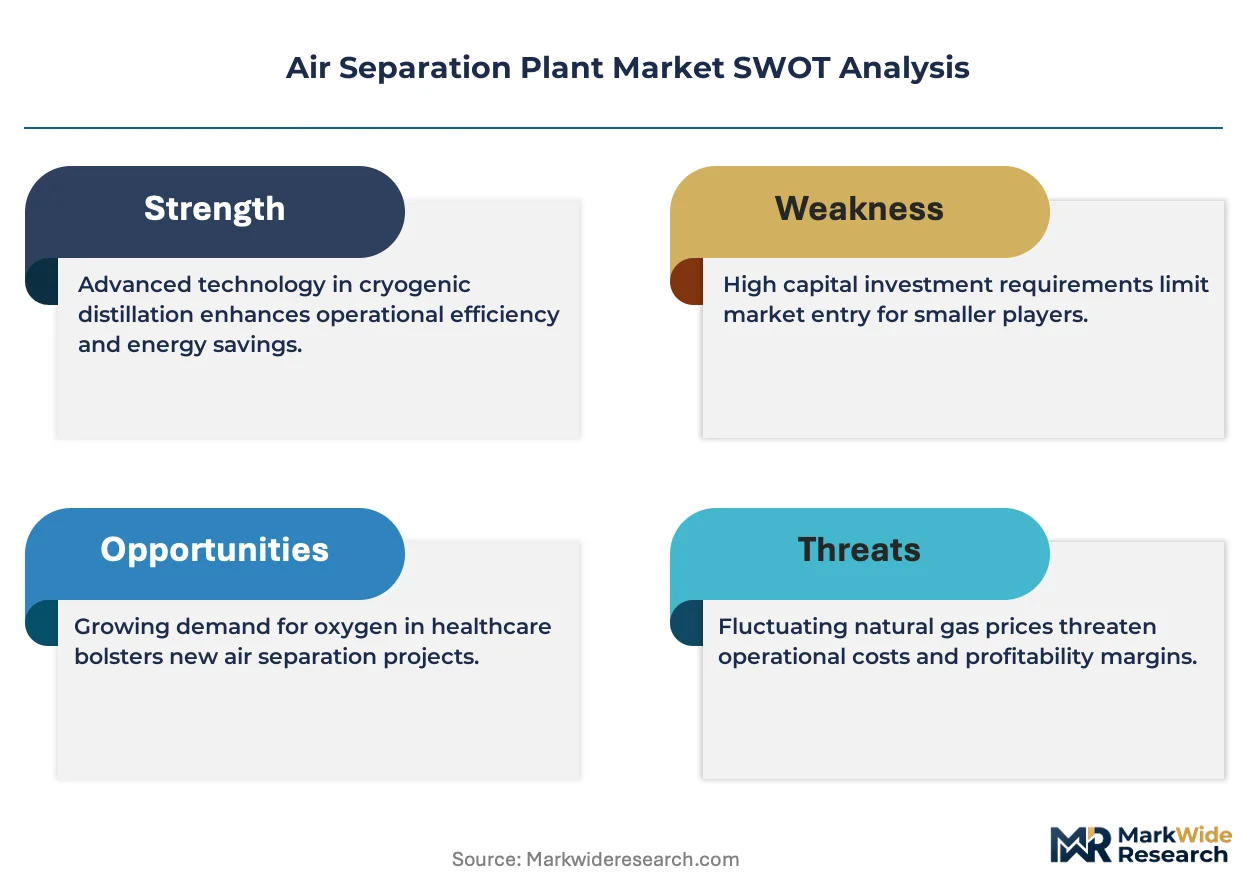
The central tension shaping the air separation plant market is the bifurcation between large-scale cryogenic facilities serving bulk industrial users and the rise of smaller, on-site non-cryogenic systems catering to specialized, lower-volume applications.
Growth Catalysts
- Regulatory Mandates:Stricter environmental standards, such as the EU Green Deal, are compelling heavy industries to adopt cleaner combustion and processing techniques, directly increasing the need for industrial oxygen and nitrogen from advanced separation units.
- Rapid Industrialization:Infrastructure development and manufacturing expansion in geographies like India create sustained demand for new, large-scale air separation plants to supply steel mills, refineries, and chemical complexes with essential gases.
- Electronics Sector Expansion:The relentless growth of semiconductor fabrication requires a consistent supply of ultra-high-purity nitrogen and argon, driving investment in specialized air separation units tailored for the electronics industry.
Market Restraints
- High Energy Consumption:Cryogenic air separation is an energy-intensive process, exposing plant operators to volatile electricity prices and making operational costs a significant structural barrier, particularly in regions with high energy tariffs.
- Capital Expenditure Barriers:The substantial upfront investment required to engineer and construct large-scale air separation units, often running into hundreds of millions of dollars, limits market entry to a few large, well-capitalized firms.
- Technical Purity Limits:Non-cryogenic technologies like Pressure Swing Adsorption (PSA), while cost-effective for smaller scales, cannot achieve the ultra-high purity levels required for medical or electronics applications, limiting their addressable market.
Strategic Opportunities
- Green Hydrogen Production:The development of a global green hydrogen economy presents a major opportunity, as large-scale electrolyzers require a co-located source of high-purity oxygen, which can be efficiently supplied by dedicated air separation units.
- Medical Gas Infrastructure:Expanding healthcare infrastructure in developing economies across Africa and Southeast Asia creates an opportunity to build and operate smaller, localized plants for producing medical-grade oxygen compliant with WHO guidelines.
- Digitalization and AI Integration:Applying artificial intelligence and machine learning algorithms to ASU operations offers a path to optimize energy consumption, predict component failures, and automate process controls, creating significant value through efficiency gains.
Industry Challenges
- Component Lead Times:Long lead times for critical, large-format equipment such as main air compressors and specialized cryogenic heat exchangers can introduce significant delays and cost overruns into plant construction projects.
- Skilled Labor Scarcity:A persistent shortage of experienced cryogenic engineers and certified plant operators presents an ongoing operational challenge, impacting plant efficiency, safety, and the ability to execute complex maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Separation Plant Market |
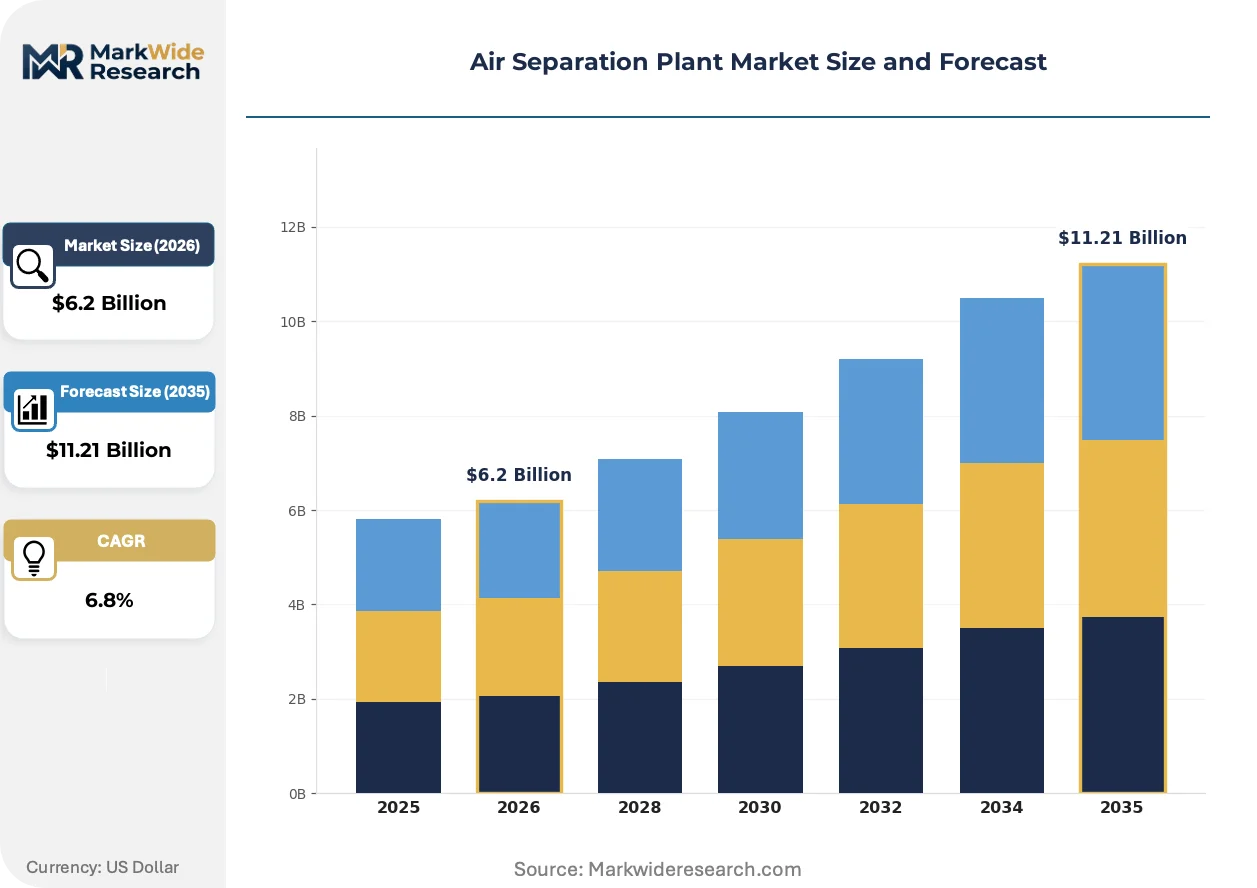
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
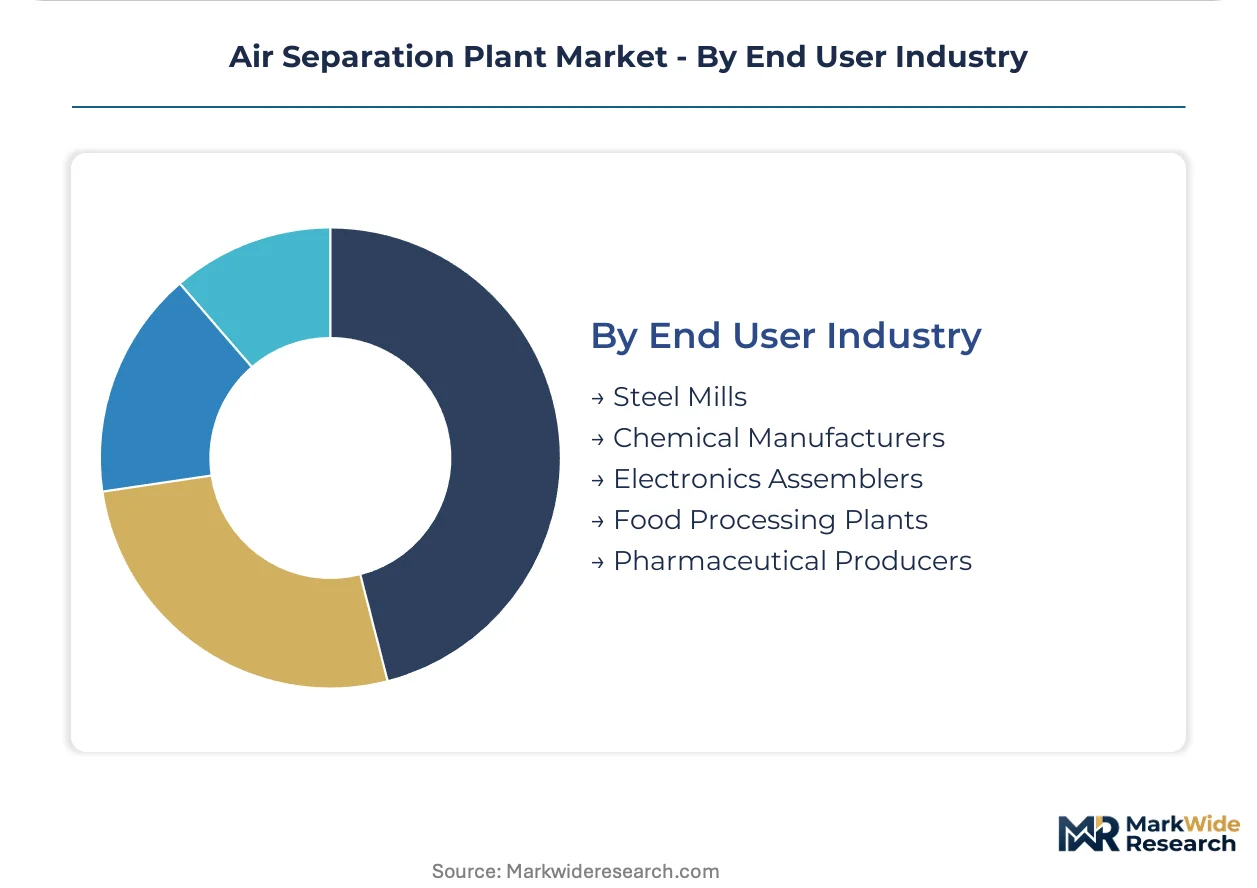
| Segmentation | Product Type: Cryogenic Air Separation Unit, Pressure Swing Adsorption, Membrane Separation, Hybrid Systems Technology: Distillation, Absorption, Adsorption, Cryogenic Liquefaction, Fractional Distillation Application: Metal Fabrication, Chemical Processing, Glass Manufacturing, Electronics Production, Food & Beverage Packaging End User Industry: Steel Mills, Chemical Manufacturers, Electronics Assemblers, Food Processing Plants, Pharmaceutical Producers |
| Companies Covered | Linde plc, Air Liquide SA, Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, Praxair, Inc., Oxyplants, AMCS Corporation, Technex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Separation Plant Market Strategic Shifts & Innovations
Decentralization of gas supply is reshaping the traditional industrial gas business model. The market is pivoting from a purely centralized production and distribution network toward a hybrid approach that incorporates on-site generation for greater efficiency and supply security.
Modular, non-cryogenic technologies like Pressure Swing Adsorption (PSA) and membrane separation provide on-demand gas generation directly at the point of use. Small and medium-sized enterprises in sectors such as food packaging, beverage production, and electronics assembly are adopting these systems for their nitrogen requirements. This adoption is fragmenting the historical reliance on bulk liquid gas deliveries from large, centralized cryogenic plants.
United States EPA regulations governing emissions from industrial furnaces and boilers are a significant driver of technology choice. These rules incentivize the use of oxygen-enhanced or oxy-fuel combustion, which burns fuel in a pure oxygen environment to increase efficiency and reduce nitrogen oxide (NOx) emissions. Consequently, end-users in glass, cement, and steel manufacturing are increasingly investing in on-site oxygen VPSA or small cryogenic plants.
A fundamental shift in procurement is occurring as large gas consumers move away from transactional purchases of liquid gas. They now favor long-term, on-site supply agreements where a gas company builds, owns, and operates a dedicated plant on or near the customer's facility. This over-the-fence model is most visible in major industrial corridors in China and the U.S. Gulf Coast, particularly within the chemical and steel sectors.
Air Separation Plant Market Segmentation
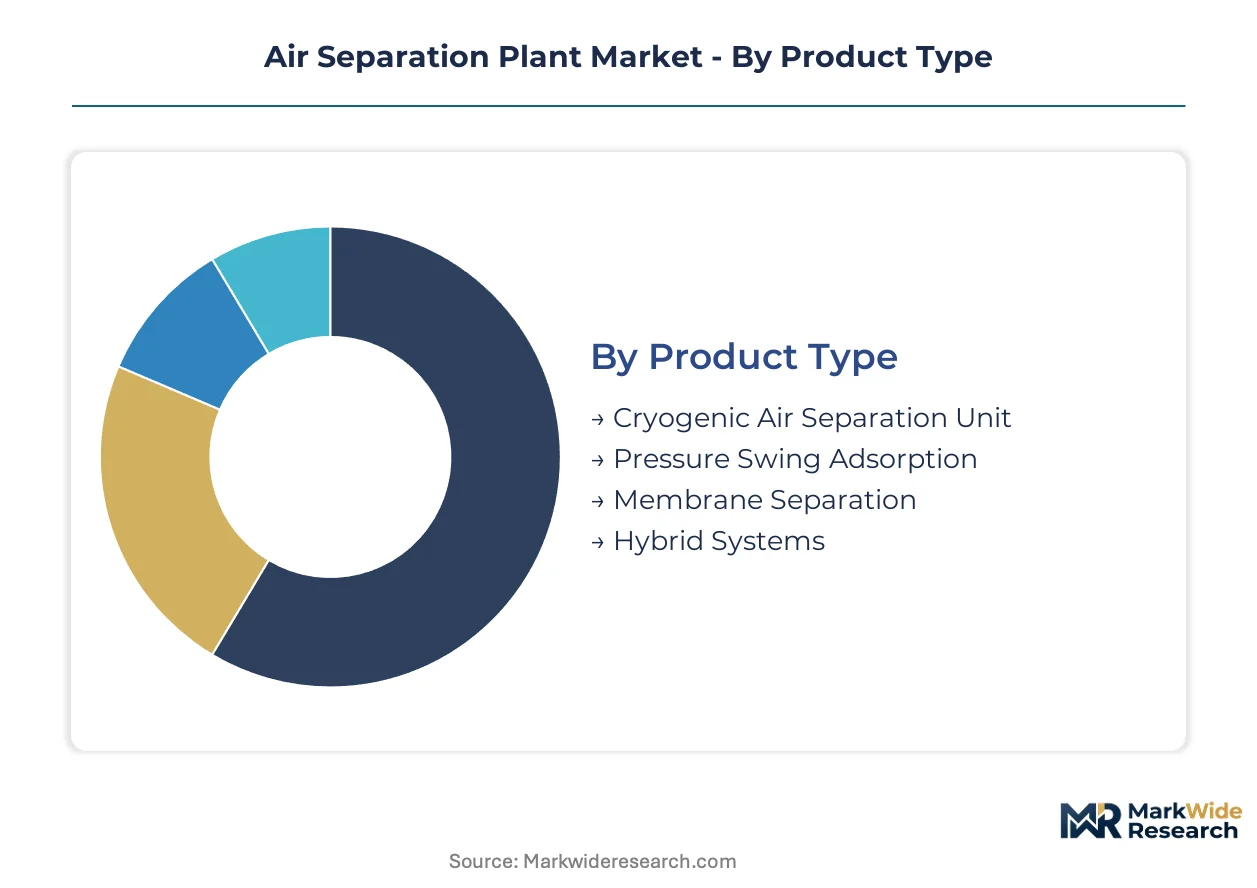
Understanding the air separation plant market through its diverse segments reveals distinct operational models and customer priorities. Segmentation highlights varied technological approaches and end-user demands driving investment across industrial, medical, and specialized gas applications.
Product Type:
Margin pools within product type often correlate with gas purity complexity and installation scale.
- Cryogenic Air Separation Unit:Facilities separate atmospheric air into high-purity nitrogen, oxygen, and argon via fractional distillation. Demand concentrates in large industrial operations like steel mills, driven by bulk gas needs.
- Pressure Swing Adsorption:PSA systems separate gases using adsorbent materials to capture and release target gases under pressure changes. This technology gains traction for smaller, on-site requirements in food & beverage and electronics.
- Membrane Separation:Uses selective permeable membranes for nitrogen generation, suitable for moderate purity and lower volume applications.
- Hybrid Systems:Combine cryogenic and PSA technologies to optimize purity or gas mixtures for complex industrial processes.
The dominant share belongs to Cryogenic Air Separation Unit, while Pressure Swing Adsorption is closing the gap fastest.
Technology:
Air separation technology choice dictates capital expenditure and operational cost tiers.
- Distillation:This process separates liquefied air components based on boiling points within cryogenic columns, producing high-purity oxygen, nitrogen, and argon. It forms the core of large-scale air separation, essential for bulk gas supply to chemical processing.
- Adsorption:Adsorption technologies, like Pressure Swing Adsorption (PSA), utilize porous materials to selectively remove specific gases from air. This is crucial for on-site, smaller-scale nitrogen and oxygen generation in food & beverage and electronics production.
- Absorption:Uses a liquid solvent to selectively absorb components from a gas mixture, primarily for impurity removal.
- Cryogenic Liquefaction:Cooling air to extremely low temperatures converts it to liquid, a preparatory step for fractional distillation.
- Fractional Distillation:Key in cryogenic ASUs, it separates liquid air into component gases based on distinct boiling points.
High-volume industrial gas production primarily relies on Distillation, while Adsorption technologies are gaining significant traction for decentralized supply.
Application:
Air separation plants serve diverse applications, each demanding specific gas purities and volumes tailored to process requirements.
- Chemical Processing:This application uses industrial gases like oxygen and nitrogen for oxidation reactions, inerting, and feedstock preparation in chemical manufacturing. Its expansion in India drives significant demand for large-scale oxygen and nitrogen supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for air separation plants centers on heavy industries and specialized sectors requiring high-purity gases. Chemical processors, steel manufacturers, and electronics fabricators drive significant demand across key global regions. These end-users prioritize both bulk supply and specialized on-site generation.
India
Rapid industrialization and extensive infrastructure development in India fuel substantial demand for large-scale air separation plants. The PLI scheme for manufacturing incentivizes new industrial setups, increasing gas requirements. Industrial corridors like the Delhi-Mumbai Industrial Corridor are seeing new plant installations to supply steel mills and chemical complexes.
United States
The United States' robust chemical processing and electronics sectors require consistent high-purity oxygen and nitrogen. EPA rules governing industrial emissions drive demand for oxygen in cleaner combustion processes. The U.S. Gulf Coast, a hub for chemical manufacturing, attracts investment in large-scale air separation units.
Germany
Germany's advanced manufacturing base and green initiatives create strong demand for industrial gases. The EU Green Deal mandates cleaner industrial processes, increasing the need for oxygen in steel and chemical plants. Industrial regions like North Rhine-Westphalia focus on optimizing gas supply for heavy industries and specialized manufacturing.
China
China's vast industrial expansion, particularly in steel and petrochemicals, drives immense demand for bulk industrial gases. The country's dual carbon goals promote efficiency and cleaner production, necessitating advanced gas separation technologies. Major industrial zones, such as the Yangtze River Delta, feature numerous long-term, on-site supply agreements for air separation plants.
Japan
Japan's high-tech electronics and automotive industries require ultra-high-purity nitrogen and argon for fabrication processes. METI initiatives supporting advanced manufacturing contribute to sustained investment in specialized air separation units. Industrial clusters in Kanto, including Tokyo, focus on precision manufacturing that relies on consistent gas quality.
Air Separation Plant Market Key Industry Players
Player mix skews toward large, integrated industrial gas suppliers with extensive global footprints. The market structure is moderately consolidated, with a few major participants controlling significant shares. Strategic archetypes include global giants offering full-service solutions and specialized engineering firms focused on niche applications. Geographic expansion and long-term supply agreements represent primary competitive moves.
Within the global integrated supplier archetype, Linde plc and Air Liquide SA exemplify extensive engineering capabilities and operational scale. These European-based industrial gas companies secure large-volume contracts across diverse industries, leveraging their established distribution networks and technological leadership. Air Products and Chemicals, Inc., a US-based entity, occupies a position anchored by its focus on long-term, on-site supply agreements with major industrial clients. This approach allows it to sustain a strong market presence in key geographies, differentiating its service model.
Leading Market Players Linde plc Air Liquide SA Air Products and Chemicals, Inc. Taiyo Nippon Sanso Corporation Messer Group GmbH Praxair, Inc. Oxyplants AMCS Corporation Technex Ltd. Others Please note: The company list above is for reference and is subject to change. The final study will cover 15–20 leading companies in this market, and the final selection can be tailored to the client’s specific requirements.Cost & Logistics Intelligence
Extended lead times for critical air separation plant components, such as specialized cryogenic heat exchangers, directly influence both project timelines and the negotiation leverage in long-term supply agreements.
Pricing Analysis
Cost-plus contracts, often indexed to energy prices and raw material costs, define the dominant pricing model for large-scale air separation plant installations. Price differentiation stems from the ultra-high purity required for electronics and healthcare applications, alongside comprehensive after-sales service packages. Pricing softness reflects intense competition for major industrial contracts and volatile electricity prices in regions like Germany. Smaller enterprises using non-cryogenic systems for food & beverage production exhibit the highest price sensitivity, while semiconductor manufacturers prioritize gas purity over cost.
Supply Chain Analysis
Rising inbound logistics costs, particularly due to port congestion in the U.S. Gulf Coast and the Yangtze River Delta, impact the delivery schedules and overall project costs for air separation plants. Supply concentration centers on Germany for engineering, China for manufacturing, and Japan for specialized cryogenic heat exchangers. The market draws from steel for structural components and advanced compressors. Single-source vulnerability for highly specialized equipment poses a structural risk. Distribution runs through long-term, over-the-fence supply agreements with major industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air separation plant market represents a defensive-moat story, primarily due to significant regulatory entrenchment and high switching costs for industrial clients.
For Market Incumbents: Consolidate core market share by securing more long-term, on-site supply agreements with chemical processors and steel mills. Invest in capacity addition in rapidly industrializing regions like India to counter emerging entrants. Reinforce technological leadership in ultra-high purity gas solutions to mitigate the threat from non-cryogenic systems. Prioritize compliance with ASME BPVC standards, which acts as a significant barrier for smaller competitors.
For New Entrants and Emerging Players: Unaddressed service-layer gaps in localized medical oxygen supply in developing economies present a clear entry point for new players. Focus on providing modular, non-cryogenic solutions for smaller-scale applications in food & beverage and healthcare. The most penetrable segment lies in underserved regional markets across Africa and Southeast Asia. Offer flexible, cost-effective on-site generation models to compete with bulk liquid gas deliveries.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-heavy utility play because of the essential nature of industrial gases and the high capital intensity required. Target acquisition archetypes include specialized engineering firms with niche cryogenic expertise or agile providers of non-cryogenic technologies. Evaluate companies with strong intellectual property in digitalization and AI integration for operational efficiency gains. A significant signal to watch is the sustained uptick in green hydrogen project announcements requiring co-located high-purity oxygen supply.
Strategic Initiative Industry Significance Capacity Expansion Securing bulk supply for rapidly industrializing regions like India meets sustained demand from steel mills. Green Manufacturing Transition Adopting cleaner production methods aligns with EU Green Deal mandates for chemical processing. Long-term Supply Agreement This over-the-fence model guarantees stable revenue streams from major industrial clients in China. Digitalization Investment Integrating AI and machine learning optimizes energy consumption for cryogenic Air Separation Units. Modular Plant Development Catering to smaller, on-site requirements expands market reach in food & beverage production. Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence reports anchors the qualitative findings of this study. This involved conversations with plant managers, procurement leads at chemical manufacturers, R&D directors in gas technology firms, and regulatory affairs specialists. Secondary data sources included EPA rules, WHO guidelines, company 10-K filings, and industry association reports. Bottom-up and top-down triangulation ensured robust data synthesis.
Sensitivity analysis informed the quantitative modeling, assessing potential impacts of varying market conditions on growth projections across the analysis window. The analytical framework segmented the market by product type, technology, application, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included industrialization rates in India and regional energy price volatility.
Forecasts assume regulatory continuity in the EU and US; material policy shifts would require re-modeling of market dynamics. This analysis reflects current economic conditions and technological trajectories, acknowledging potential impacts from geopolitical instability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Plug Market
Others
AI in Precision Medicine Market
Others
Fabric Based Computing Market
Others
Global Mobile Gambling Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Global Aircraft Lighting Systems Market
Others
Data Center CPU Market
Others
Quadrant Scale Market
Others
Coconut Activated Carbon Market
Others
United States Air Furnaces Market
Others
Powder Coating Equipment Market
Others
Liquid-Cooled Heat Sink Market
Others
Global Computer Graphics Market
Others
Lined Tank Market
Others
Global Maritime Freight Transport Market
Others
Buchner Funnels Market