
 India 3D Printing Construction Market | 2026-2036
India 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India 3D Printing Construction Market Insights
Concrete is consolidating its position as the dominant material in India 3D Printing Construction, displacing conventional brick-and-mortar economics through reduced labor intensity and faster curing cycles. L&T Construction leverages its project execution scale to anchor large infrastructure deployments. Tvasta specializes in indigenous concrete mix formulations optimized for gantry-based deposition. COBOD International A/S competes through technology transfer partnerships with Indian system integrators.
India 3D Printing Construction deploys layer-by-layer material deposition using computer-controlled extrusion or binding processes, typically achieving compressive strengths of 30-60 MPa in concrete formulations within 24-48 hours. The technology serves primarily to compress construction timelines and reduce material waste in housing and infrastructure delivery. Concrete dominates material segmentation due to its compatibility with existing supply chains and regulatory familiarity. Residential application leads current deployment volumes, though infrastructure is recording the fastest project pipeline growth. Government end users command the largest committed spend pools through public housing mandates.
BIS and CEA shape product standards and electrical safety compliance for automated construction equipment entering Indian project sites. The PLI scheme for domestic manufacturing is redirecting procurement toward locally assembled printer systems. State-level smart city special purpose vehicles are becoming the decisive demand aggregators for technology validation and scale deployment. Stakeholders must monitor which state housing boards convert pilot approvals into multi-project mandates.
Market Dynamics
State housing boards in Maharashtra and Gujarat are converting pilot approvals into multi-project mandates, compressing procurement cycles for concrete-based additive manufacturing systems while BIS code development lags deployment velocity.
Growth Catalysts
- PLI scheme for domestic manufacturing:The production-linked incentive framework redirects procurement toward locally assembled gantry systems, reducing import dependency for core deposition hardware.
- Smart city special purpose vehicles:State-level SPVs aggregate demand across tier-two urban centers, creating validated reference sites for technology scale-up.
- Concrete mix optimization:Indigenous formulations achieving 30-60 MPa compressive strength within 24-48 hours accelerate curing cycles versus conventional brick-and-mortar construction.
Market Restraints
- Portland cement price volatility:Input cost swings for the primary concrete binder compress project margins and deter fixed-price contracting.
- Equipment supply concentration:Core gantry and extrusion hardware originates from limited European and East Asian sources, exposing buyers to currency and lead-time risk.
- BIS code absence:The lack of finalized construction standards for additive manufacturing creates regulatory friction in building permit approvals.
Strategic Opportunities
- Affordable housing vertical:Government-mandated low-cost residential projects in Gujarat offer volume deployment pathways for validated system integrators.
- Infrastructure application pivot:Bridge components, culverts, and boundary walls represent underpenetrated use cases with faster approval timelines than vertical housing.
- CEA electrical safety compliance:Automated construction equipment certification creates a regulatory tailwind for system integrators achieving centralized electrical clearance.
Industry Challenges
- Structural engineer certification gap:Licensed professionals with additive manufacturing design competency remain scarce, delaying project sign-off.
- Legacy ERP integration:Construction management software stacks lack native modules for layer-wise build sequencing and real-time deposition monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India 3D Printing Construction Market |
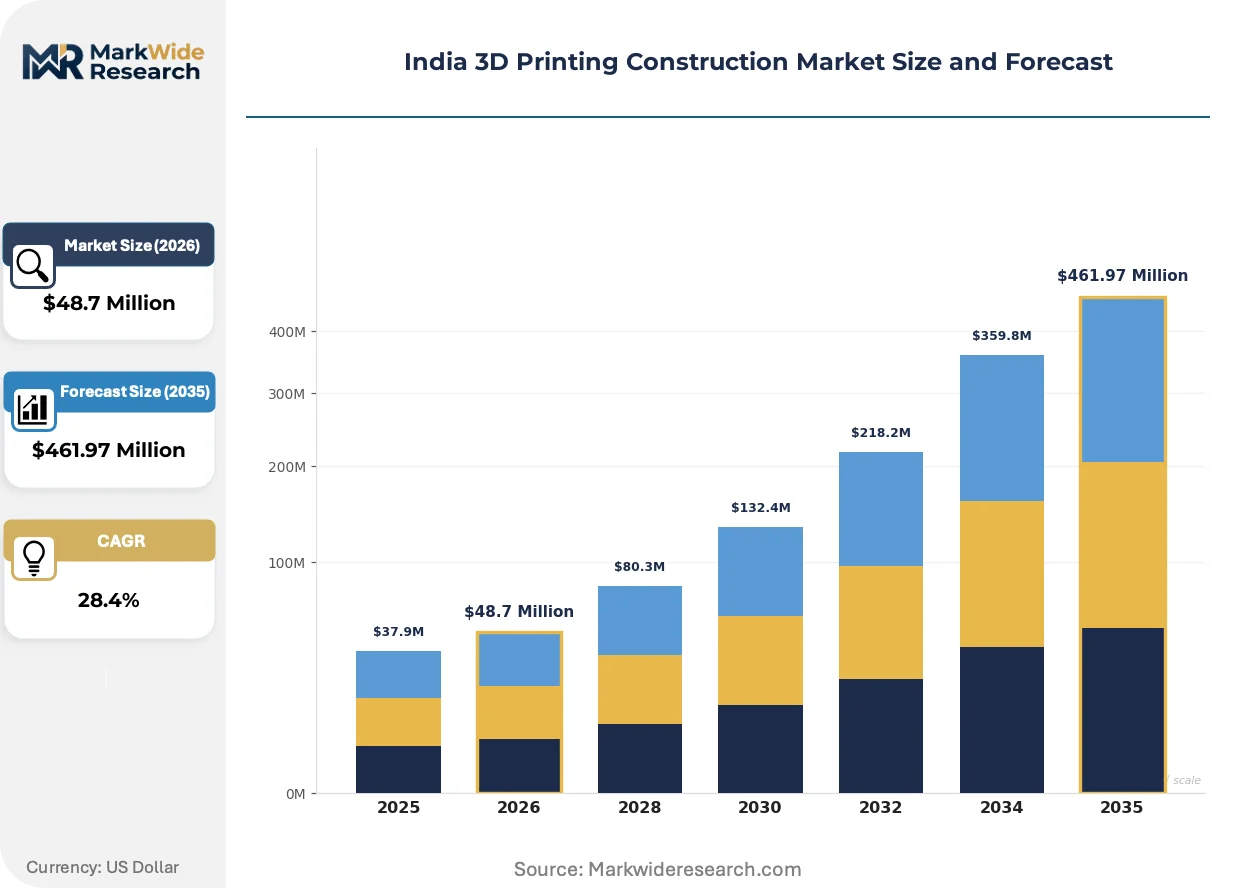
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $461.97 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FDM, SLS, DLP, Inkjet Material: Concrete, Plastic, Composite, Steel Application: Residential, Commercial, Infrastructure, Rehabilitation End User: Construction Firms, Architects, Developers, Government |
| Companies Covered | COBOD International A/S, L&T Construction, Kelvin6k, AJAX Engineering, Tvasta, INTECH Additive Solutions, Ace Micromatic Group, Godrej Construction, Wipro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India 3D Printing Construction Market Trends and Innovations
Gantry-based concrete deposition is absorbing capital and talent from conventional precast operations as state governments harden procurement preference for automated construction methods.
Geopolymer concrete formulations are absorbing interest from infrastructure developers seeking reduced carbon intensity in public works. State public works departments in Maharashtra are piloting these mixes for non-structural elements. The shift is compressing the addressable market for ordinary Portland cement-based systems in environmentally weighted tenders.
BIS is developing dedicated codes for additive manufacturing in construction, creating a compliance pathway for equipment certification. The framework mandates third-party validation of compressive strength and dimensional accuracy. Housing boards in Gujarat are pre-qualifying vendors against draft standards to accelerate post-ratification deployment.
Design-build contracting is displacing traditional lump-sum tendering for complex geometry structures. Municipal corporations in tier-two cities are bundling architectural design with construction execution to reduce interface risk. The model concentrates accountability with system integrators capable of computational design and robotic deposition.
India 3D Printing Construction Market Segmentation
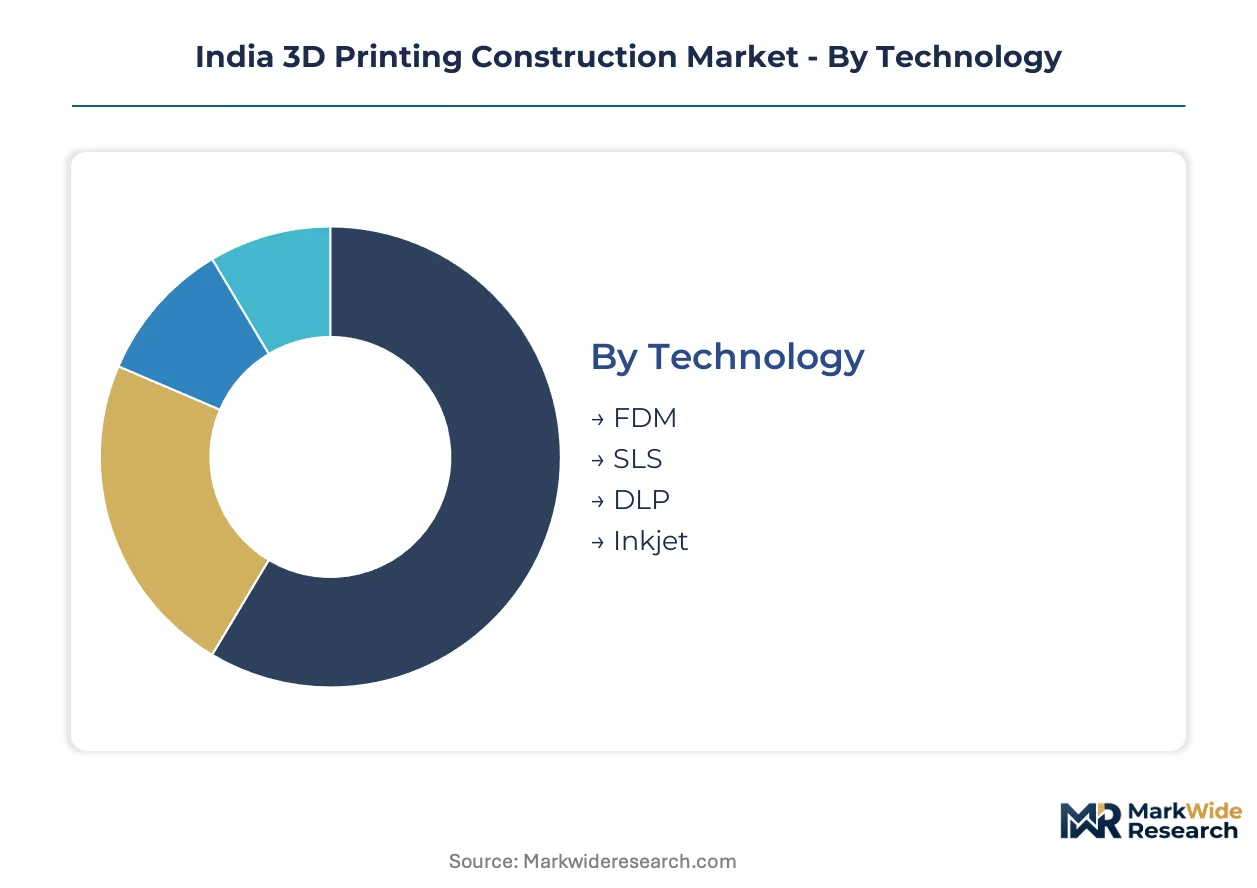
Technology, material, application, and end-user dimensions each reshape procurement patterns and margin structures for additive manufacturing in Indian construction. Segment boundaries are blurring as gantry-based concrete systems absorb functions from conventional precast and cast-in-place operations.
Technology:
Standalone deposition systems dominate current deployments, while hybrid configurations embedding sensing and real-time adjustment modules capture capital inflows from quality-sensitive infrastructure tenders.
- FDM:Fused deposition modeling extrudes thermoplastic filaments through heated nozzles, achieving layer resolutions of 0.1-0.3mm in polymer-based formwork and architectural mock-ups. Demand concentrates in architectural practices in Bengaluru and Mumbai producing rapid prototyping services for design validation, constrained by limited structural load-bearing capacity in finished components.
- SLS:Selective laser sintering fuses powdered polymers or metals using directed thermal energy, enabling complex internal geometries without support structures. Gujarat-based industrial design studios are absorbing capacity for customized facade elements and intricate interior fixtures, driven by the state's concentration of chemical processing infrastructure supplying polymer feedstock.
- DLP:Digital light processing cures photopolymer resins using projected ultraviolet patterns, delivering surface finishes superior to filament-based methods.
- Inkjet:Binder jetting deposits liquid binding agents onto powder beds, enabling multi-material gradients in single builds.
Volume placements concentrate in FDM for early-stage design visualization; the faster expansion belongs to SLS as functional load-bearing applications mature.
Material:
Cost tiers separate commodity feedstocks from performance-graded formulations, with procurement committees in Maharashtra and Gujarat weighting compressive strength certificates over unit price in structural applications.
- Concrete:Portland cement-based mixes with optimized rheology achieve 30-60 MPa compressive strength within 24-48 hours through accelerated curing protocols. Smart city special purpose vehicles in tier-two urban centers aggregate demand for affordable housing walls and boundary structures, compressing procurement cycles as BIS draft standards gain pre-qualification traction.
- Plastic:Recycled polyethylene and polypropylene formulations reduce embodied carbon in non-structural elements and temporary formwork. Kerala and Tamil Nadu municipalities are piloting ocean plastic-derived feedstocks for coastal infrastructure components, responding to marine waste mandates from state pollution control boards.
- Composite:Fiber-reinforced polymer matrices combining glass or carbon with thermoset binders deliver strength-to-weight ratios exceeding conventional materials.
- Steel:Powder metallurgy and wire-arc additive manufacturing produce structural connections and reinforcement cages with topology-optimized geometries.
Concrete commands the dominant procurement volume; composite formulations are climbing the fastest as infrastructure developers seek weight reduction in bridge and elevated corridor components.
Application:
Customer maturity varies sharply across use cases, with government end users demanding validated reference sites before committing to vertical housing while accepting higher technical risk in horizontal infrastructure.
- Residential:Single and multi-family dwelling construction using load-bearing printed walls and prefabricated printed components. Affordable housing boards in Maharashtra have converted pilot approvals into multi-project mandates for 500+ unit developments, anchoring demand for gantry systems with build envelopes exceeding 10 meters in width.
- Infrastructure:Bridge culverts, drainage channels, sound barriers, and utility enclosures requiring standardized geometries at volume. State public works departments in Gujarat are deploying these elements for highway expansion projects, attracted by faster approval timelines compared to vertical construction and reduced labor camp requirements in remote locations.
- Commercial:Office facades, retail kiosks, and hospitality interiors emphasizing aesthetic differentiation through parametric design.
- Rehabilitation:Structural repair and seismic retrofit using printed reinforcement jackets and replacement components.
Residential absorbs the largest committed capital; infrastructure is gaining share fastest as horizontal asset classes bypass structural engineer certification bottlenecks.
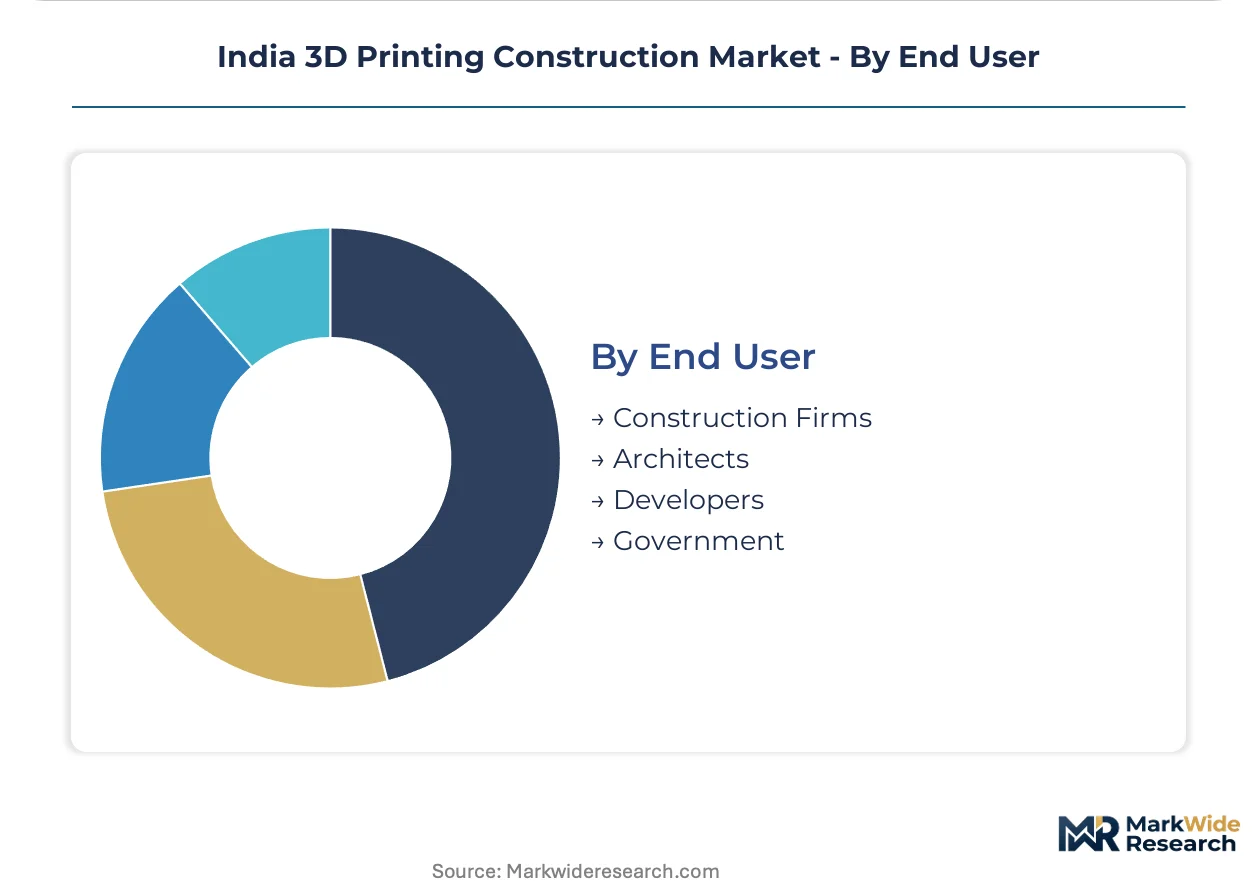
End User:
Procurement authority concentrates with entities controlling land banks and project finance, while design professionals influence technology selection through specification authority in design-build contracts.
- Construction Firms:Large integrated contractors with in-house equipment fleets and trained gantry operators. L&T Construction and similar executors anchor demand through direct system ownership, capturing margin from compressed timelines in government housing mandates.
- Government:Central and state housing boards, smart city SPVs, and public works departments with mandated low-cost delivery targets. These entities command the largest committed spend pools through multi-year affordable housing programs, though payment cycles and bid security requirements filter vendor participation.
- Architects:Design practices specifying additive manufacturing for complex geometry structures and computational design workflows.
- Developers:Private real estate promoters seeking differentiation in premium residential and commercial segments.
Construction firms place the heaviest equipment orders; government entities are expanding their share fastest as state housing boards convert pilot approvals into recurring procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's smart city special purpose vehicles anchor demand concentration through multi-project mandates for affordable housing developments exceeding 500 units.
Maharashtra
State housing boards in Mumbai and Pune are converting pilot approvals into recurring procurement frameworks for gantry-based concrete deposition systems. The Maharashtra State Road Development Corporation is integrating 3D-printed culverts into highway expansion projects, bypassing vertical construction certification bottlenecks. Thane and Nashik industrial corridors are attracting system integrators establishing regional equipment depots.
Gujarat
Affordable housing mandates in Ahmedabad and Surat are compressing procurement cycles for validated concrete printing vendors. The Gujarat State Road and Buildings Department is deploying boundary walls and utility enclosures through faster approval pathways than residential verticals. Vadodara's chemical processing infrastructure is supplying polymer feedstock for SLS-based facade element production.
Karnataka
Bengaluru's architectural practices are absorbing FDM capacity for rapid prototyping services and design validation workflows. The Karnataka Industrial Areas Development Board is allocating land parcels for construction technology clusters in the state's aerospace and precision manufacturing corridors. Mysuru's emerging industrial zones are piloting recycled plastic feedstocks for non-structural coastal infrastructure components.
Telangana
Hyderabad's municipal corporations are bundling design-build contracts for complex geometry structures in tier-two satellite cities. The Telangana State Industrial Infrastructure Corporation is establishing reference sites for technology validation through state-backed smart city deployments. Warangal and Karimnagar are emerging as testbeds for geopolymer concrete formulations in public works pilot programs.
Tamil Nadu
Chennai's construction equipment manufacturing base is pivoting toward gantry system assembly under PLI scheme incentives for domestic production. The Tamil Nadu Urban Habitat Development Board is aggregating demand across tier-two centers for affordable housing wall systems. Coimbatore's precision engineering cluster is supplying motion control hardware for indigenous printer system integration.
India 3D Printing Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated construction firms owning equipment fleets directly while technology licensors partner with regional system integrators for market access. The vendor base organizes around three archetypes: multinational technology transfer specialists, domestic construction conglomerates with in-house automation capabilities, and indigenous equipment fabricators serving state-level housing mandates. Dominant competitive moves include strategic partnerships for gantry hardware localization and portfolio diversification into geopolymer formulations for carbon-weighted tenders.
Within the multinational technology transfer tier, COBOD International A/S occupies a position as a European licensor enabling Indian system integrators to access gantry deposition hardware. Among domestic construction conglomerates, L&T Construction exemplifies scale-driven equipment ownership and direct project execution capacity. In the indigenous formulation specialist tier, Tvasta represents the archetype of companies optimizing concrete rheology for locally sourced materials and accelerated curing protocols.
| Leading Market Players |
|---|
| COBOD International A/S |
| L&T Construction |
| Kelvin6k |
| AJAX Engineering |
| Tvasta |
| INTECH Additive Solutions |
| Ace Micromatic Group |
| Godrej Construction |
| Wipro |
| Others |
Pricing and Supply Chain Analysis
State housing boards and smart city special purpose vehicles concentrate procurement authority, anchoring project-based pricing models where volume commitments unlock preferential rates for gantry system deployment. This buyer concentration compresses margins for equipment vendors while rewarding system integrators with validated reference sites and multi-year frameworks.
Pricing Analysis
Lead-time premiums command substantial markups for European-sourced gantry hardware facing extended delivery windows, while spot inventory from domestic assemblers under PLI incentives trades at discounted rates. Project-based contracting dominates, with price differentiation resting on BIS pre-qualification status and after-sales service bundling. Pricing pressure stems from Portland cement input volatility eroding fixed-price margins. Government end users exhibit highest price sensitivity, prioritizing unit cost per square meter over performance tiers; infrastructure developers show lowest sensitivity, weighting accelerated curing protocols and compressive strength certification.
Supply Chain Analysis
Domestic content mandates under the PLI scheme redirect sourcing toward locally assembled motion control systems and extrusion hardware, reducing import dependency. Core supply draws from Germany, Denmark, and China for precision linear drives and deposition nozzles. Raw material dependencies center on Portland cement, geopolymer activators, and polymer feedstock from Vadodara's chemical processing corridor. Single-source vulnerability concentrates in European gantry controller firmware. Distribution runs through state-level equipment depots in Thane and Coimbatore, feeding project sites directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures intensify as BIS code finalization filters uncertified vendors, forcing weaker players toward exit or acquisition. Scale advantages concentrate with system integrators achieving pre-qualification against draft standards.
For Market Incumbents: Deploy backward integration into indigenous concrete formulation capabilities to capture margin from geopolymer mix optimization. Anchor capacity in Maharashtra and Gujarat industrial corridors to secure state housing board frameworks. Counter emerging indigenous equipment fabricators through accelerated BIS certification investment and reference site density. For New Entrants and Emerging Players: Tier-two municipal corporations in Telangana and Karnataka represent underserved buyer archetypes with bundled design-build contracting appetite. Infrastructure applications—bridge culverts, drainage channels, boundary walls—offer fastest approval pathways bypassing structural engineer bottlenecks. Pursue technology licensing partnerships with European gantry specialists to compress development timelines. For Investors and Strategic Acquirers: The window for entry favors indigenous formulation specialists with validated compressive strength protocols and state-level procurement relationships. Long-term viability hinges on carbon-weighted tender participation as geopolymer adoption accelerates. Monitor BIS code ratification as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Geopolymer Formulation Development | Positions vendors for carbon-weighted tenders from Maharashtra Public Works Department pilots. |
| BIS Pre-Qualification Investment | Creates regulatory moat as draft standards convert to mandatory certification requirements. |
| State Equipment Depot Expansion | Compresses response times for Gujarat and Telangana smart city SPV procurement cycles. |
| Design-Build Contracting Capability | Captures bundled accountability in tier-two municipal corporation infrastructure projects. |
| PLI Scheme Localization Partnership | Reduces import dependency for core gantry hardware through domestic assembly incentives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with state housing board procurement officers, smart city SPV project directors, gantry system operators, concrete formulation specialists, and BIS technical committee members. Secondary sources encompassed BIS draft standard disclosures, PLI scheme administrative records, state public works department tender documents, and construction equipment import manifests. Bottom-up project pipeline aggregation reconciled against top-down state budget allocation analysis.
Data-stream reconciliation across equipment shipment records, state housing mandate announcements, and vendor qualification registries informed the analytical framework. Segmentation dimensions spanned technology type, material formulation, application vertical, and end-user procurement authority across the projection horizon. CAGRs derived from project-level deployment timelines and state budget trajectory modeling. Industry-specific inputs included geopolymer mix adoption curves and BIS code development velocity.
Revisions become necessary when BIS code ratification delays extend beyond anticipated administrative windows, Portland cement price volatility exceeds historical bands, or state housing board procurement frameworks stall at pilot phase. Forecasts reflect documented assumptions regarding regulatory progression and state fiscal commitment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Reusable Wine Bags Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Video Conferencing Hardware Market
Others
Electric Chainsaw Market
Others
Tripod Market
Others
Printing Machines Market
Others
Global Hydraulics Market
Others
Japan Automotive LED Lighting Market
Others
Europe Refrigerated Display Cases Market
Others
Badminton Apparel Market
Others
Smart Home Technologies Market
Others
US Camping and Caravanning Market
Others
Palatants Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Griffin Beaker Market
Others
Bird Food Market