
 Germany Smart Office Market | 2026-2036
Germany Smart Office Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Smart Office Market Foresight
German sensor and actuator manufacturing is rebalancing toward software-integrated building systems. Siemens leverages its domestic industrial automation heritage to anchor smart HVAC and lighting control portfolios. Schneider Electric sustains competitive pressure through deep energy management specialization. Bosch Building Technologies differentiates via native integration of fire safety, access control, and environmental monitoring into unified office platforms.
Germany Smart Office encompasses networked building infrastructure that automates climate, lighting, security, and collaboration tools through centralized digital control, typically operating via BACnet or KNX protocols with sub-100ms response thresholds for occupancy-driven environmental adjustment. Energy Management applications dominate current procurement cycles as landlords face stricter carbon disclosure requirements, while Workspace Optimization segments attract faster growth from hybrid-workplace reconfiguration mandates. Deployment gravitates toward Hybrid Cloud architectures that balance real-time edge processing for critical building functions with cloud analytics for portfolio-level efficiency benchmarking.
KBA energy efficiency standards, Germany's Building Energy Act (GEG), and EU Green Deal carbon reporting frameworks collectively elevate minimum performance thresholds for commercial retrofits. CSRD sustainability disclosure rules now require large office landlords to publish granular building-level emissions data, directly stimulating sensor and analytics procurement. Stakeholders must weigh interoperability commitments against vendor lock-in risks as KNX, BACnet, and emerging Matter protocols compete for dominance in next-generation German commercial properties.
Market Dynamics
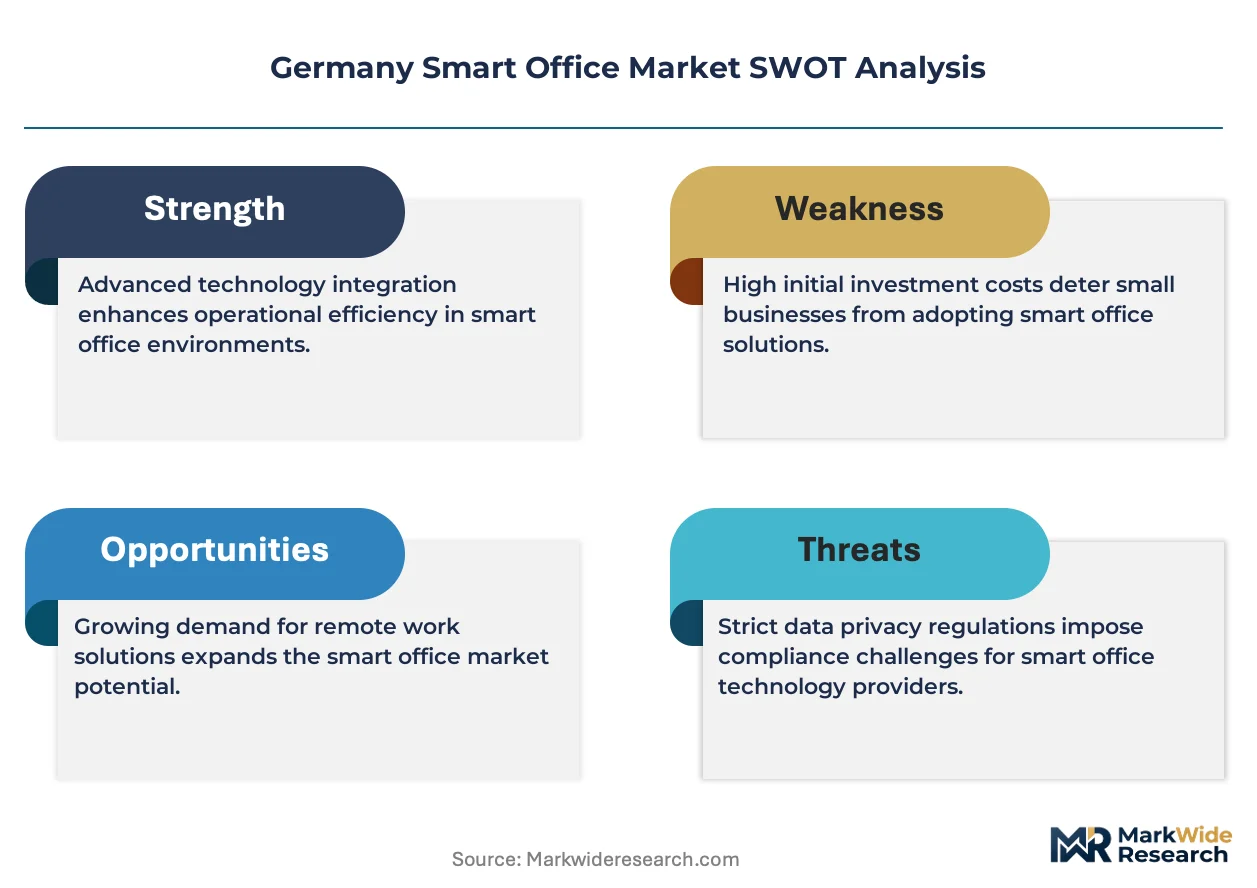
The Building Energy Act (GEG) and CSRD disclosure mandates are compressing procurement cycles for sensor networks and centralized building management platforms across German commercial real estate portfolios.
Growth Catalysts
- GEG retrofit mandates:Commercial landlords in Frankfurt and Munich face binding efficiency thresholds that require automated HVAC and lighting controls. Facility managers are prioritizing BACnet-compatible sensor deployments to meet compliance deadlines.
- Automotive headquarters clustering:Baden-Württemberg's engineering corridors concentrate modernization budgets exceeding other German Länder, with corporate real estate teams specifying unified workplace platforms.
- Hybrid cloud architectures:Edge processing for sub-100ms occupancy response is converging with cloud analytics for portfolio benchmarking, enabling real-time environmental adjustment at scale.
Market Restraints
- KNX-BACnet protocol fragmentation:Competing interoperability standards create vendor lock-in risks that delay procurement decisions and inflate integration costs for multi-site deployments.
- Specialized systems integration labor:Shortages of certified technicians for KNX and BACnet commissioning extend project timelines and compress margins for systems integrators.
- Legacy building infrastructure:Pre-2010 commercial stock in eastern Länder requires extensive electrical retrofitting before smart sensor networks can achieve full functionality.
Strategic Opportunities
- Saxony and Thuringia commercial zones:Underpenetrated eastern German markets present first-mover advantages for integrated workplace platform vendors as CSRD disclosure requirements expand to mid-cap landlords.
- Matter protocol emergence:Convergence of IP-based connectivity with established building automation standards is opening interoperability pathways that reduce proprietary system dependency.
- Workspace Optimization applications:Hybrid-workplace reconfiguration mandates are accelerating faster than Energy Management procurement, creating white space for occupancy analytics and collaboration tool integration.
Industry Challenges
- CSRD carbon disclosure granularity:Large office landlords must publish building-level emissions data with audit-ready sensor traceability, forcing upgrades to calibration and data governance infrastructure.
- Multi-protocol integration complexity:Facility teams struggle to harmonize BACnet HVAC controllers with KNX lighting systems and emerging Matter endpoints within unified management dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Smart Office Market |
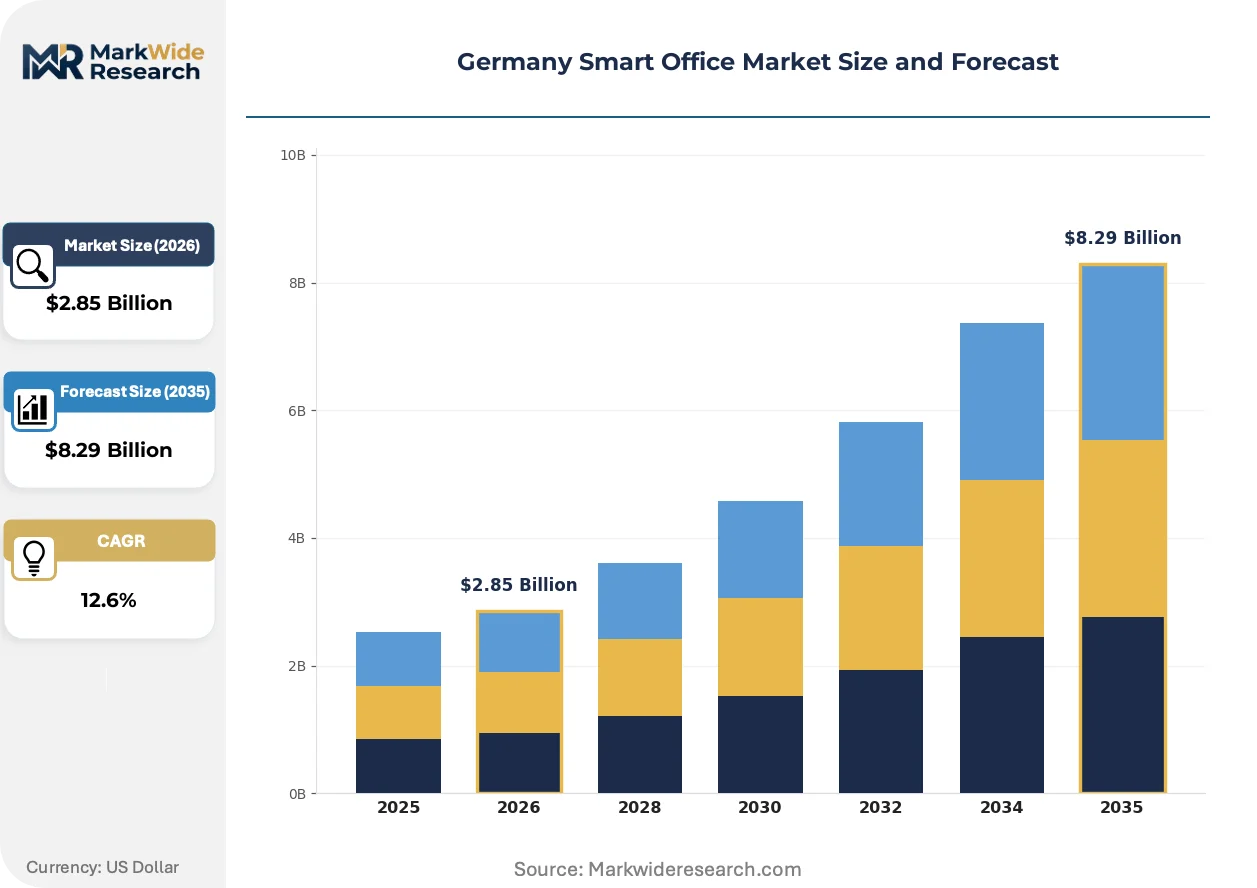
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $8.29 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Cloud Computing, Artificial Intelligence, Voice Recognition, Automation Systems, Augmented Reality Application: Energy Management, Security Monitoring, Workspace Optimization, Collaboration, Visitor Management, Asset Tracking End User Industry: Information Technology, Financial Services, Educational Institutions, Legal Firms, Marketing Agencies, Consulting Firms Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Edge Deployment |
| Companies Covered | Siemens, Schneider Electric, ABB, Honeywell, Johnson Controls, Cisco Systems, Bosch Building Technologies, Philips Lighting, Crestron Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Smart Office Market Shifts & Advancements
Software-defined building automation is displacing hardware-centric control architectures, with German facility managers prioritizing API-first platforms that enable third-party analytics integration and future protocol migration.
Digital twin technology for commercial buildings is unifying sensor telemetry from HVAC, lighting, and access control into single-pane visualization environments. Property operators in Munich and Frankfurt are piloting these platforms for predictive maintenance and energy scenario modeling. This convergence is compressing the traditional separation between facilities management and IT infrastructure oversight.
CSRD sustainability disclosure rules now require granular building-level emissions reporting with audit trails. German commercial landlords are deploying sub-metering sensor networks to capture scope 1 and 2 data with sufficient resolution for third-party verification. The Energy Management application segment is absorbing the bulk of this compliance-driven procurement as disclosure deadlines approach.
Corporate real estate teams are consolidating vendor relationships around full-stack workplace platform providers rather than point-solution specialists. Large tenants in Baden-Württemberg automotive headquarters are specifying single-contract responsibility for climate, security, and collaboration infrastructure. This concentration is marginalizing standalone sensor manufacturers without software integration capabilities.
Germany Smart Office Market Segmentation
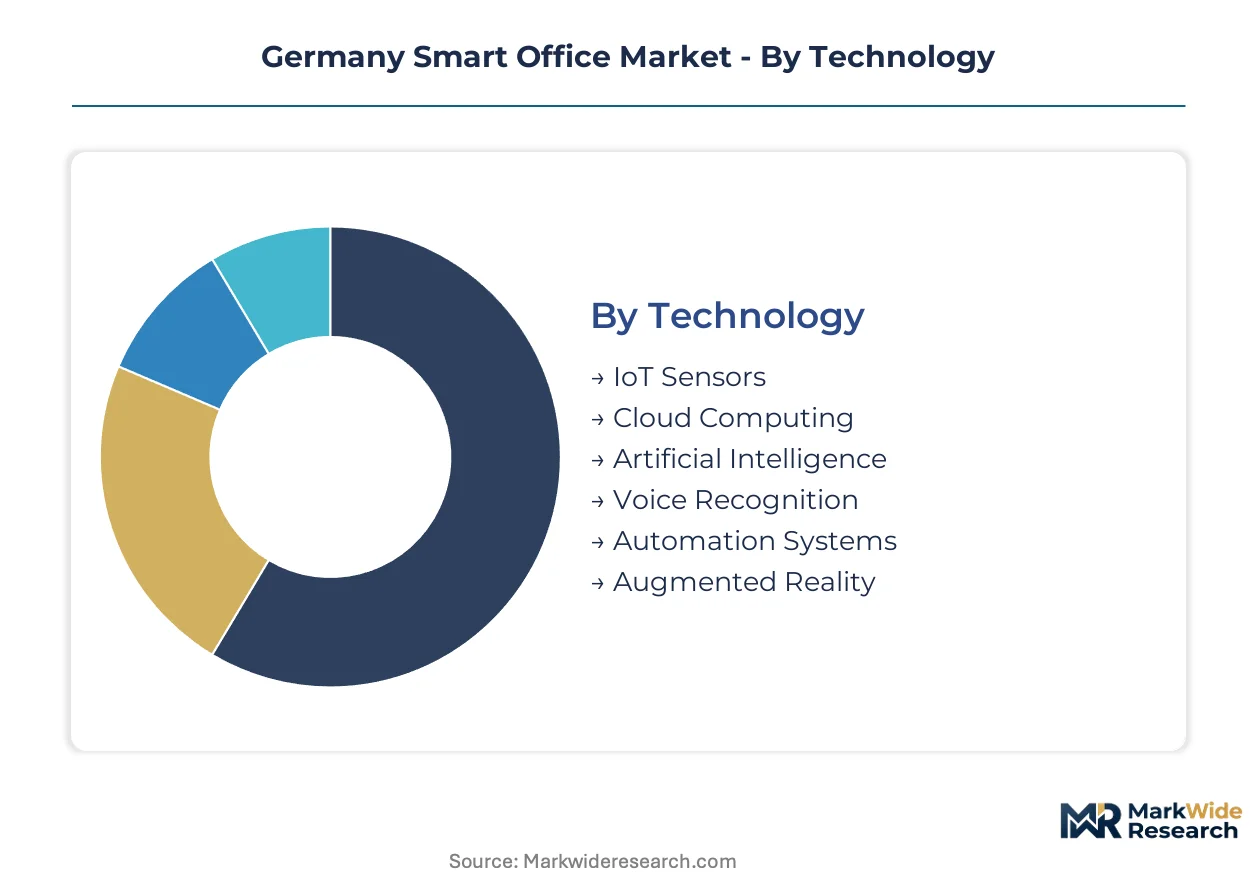
German smart office procurement patterns diverge sharply across technology maturity and regulatory exposure. Procurement teams in Frankfurt and Munich weight certification requirements differently depending on whether deployments handle critical building infrastructure or occupant-facing services.
Technology:
IoT Sensors and Automation Systems face mandatory KNX and BACnet compliance under Germany's Building Energy Act, while AI and Cloud Computing navigate GDPR data governance and EU AI Act risk classifications.
- IoT Sensors:Temperature, occupancy, and air quality monitors with sub-100ms response thresholds for HVAC integration. Demand clusters in Baden-Württemberg automotive headquarters where facility teams specify unified sensor networks for CSRD carbon disclosure compliance.
- Automation Systems:Programmable logic controllers and building management gateways that orchestrate HVAC, lighting, and access control. Frankfurt corporate real estate teams prioritize BACnet-compatible platforms to meet GEG retrofit mandates without vendor lock-in.
- Cloud Computing:Centralized analytics infrastructure for portfolio-level energy benchmarking across multi-site office holdings.
- Artificial Intelligence:Predictive algorithms for occupancy pattern recognition and energy demand forecasting.
- Voice Recognition:Natural language interfaces for conference room booking and environmental control commands.
- Augmented Reality:Spatial computing overlays for facility maintenance training and workspace reconfiguration planning.
IoT Sensors sits at the top of the volume ranking, with Artificial Intelligence climbing the fastest.
Application:
Cost tier separation drives procurement bifurcation between compliance-mandated infrastructure and productivity-focused occupant services.
- Energy Management:Automated HVAC scheduling, sub-metering networks, and carbon reporting dashboards. CSRD disclosure rules force large landlords to deploy building-level emissions tracking with audit-ready sensor traceability.
- Security Monitoring:Integrated video analytics, access control, and intrusion detection with native fire safety system coupling. Munich financial services tenants specify unified platforms that merge physical security with IT infrastructure oversight.
- Workspace Optimization:Occupancy analytics and desk-booking systems for hybrid workplace reconfiguration.
- Collaboration:Video conferencing infrastructure and digital whiteboard ecosystems for meeting room environments.
- Visitor Management:Digital check-in workflows and temporary access credentialing for guest reception areas.
- Asset Tracking:Real-time location systems for high-value equipment and mobile workstation inventory.
Energy Management commands the largest procurement budgets, while Workspace Optimization gains share fastest among corporate real estate teams.
End User Industry:
Customer type determines platform complexity requirements, with financial and legal sectors demanding higher security certification tiers than marketing or education verticals.
- Financial Services:Frankfurt banking headquarters drive demand for hybrid cloud architectures that segregate trading floor environmental data from portfolio analytics. BaFin supervisory expectations elevate cybersecurity requirements for building system networks.
- Information Technology:Munich software campuses prioritize API-first platforms enabling third-party analytics integration and rapid protocol migration.
- Legal Firms:Client confidentiality mandates shape access control and visitor management specifications.
- Educational Institutions:Budget-constrained procurement favors modular sensor deployments with phased automation expansion.
- Marketing Agencies:Creative workspace reconfiguration needs accelerate occupancy analytics adoption.
- Consulting Firms:Client-facing meeting infrastructure drives collaboration tool investment.
Financial Services leads absolute spending, with Information Technology showing the steepest expansion trajectory.
Deployment Model:
Margin structures vary dramatically between capital-intensive on-premises infrastructure and recurring-revenue cloud service arrangements.
- Hybrid Cloud:Architectures balancing edge processing for sub-100ms occupancy response with cloud analytics for portfolio benchmarking. Baden-Württemberg automotive headquarters specify this model to maintain real-time environmental control while enabling enterprise-wide efficiency comparisons.
- Edge Deployment:Localized compute nodes for latency-critical building functions without persistent cloud connectivity. Eastern Länder commercial zones with unreliable broadband favor this approach for standalone facility automation.
- On-Premises:Fully localized building management servers for data sovereignty requirements.
- Public Cloud:Multi-tenant SaaS platforms for standardized workplace analytics across distributed office portfolios.
- Private Cloud:Single-tenant hosted infrastructure for security-isolated building system operations.
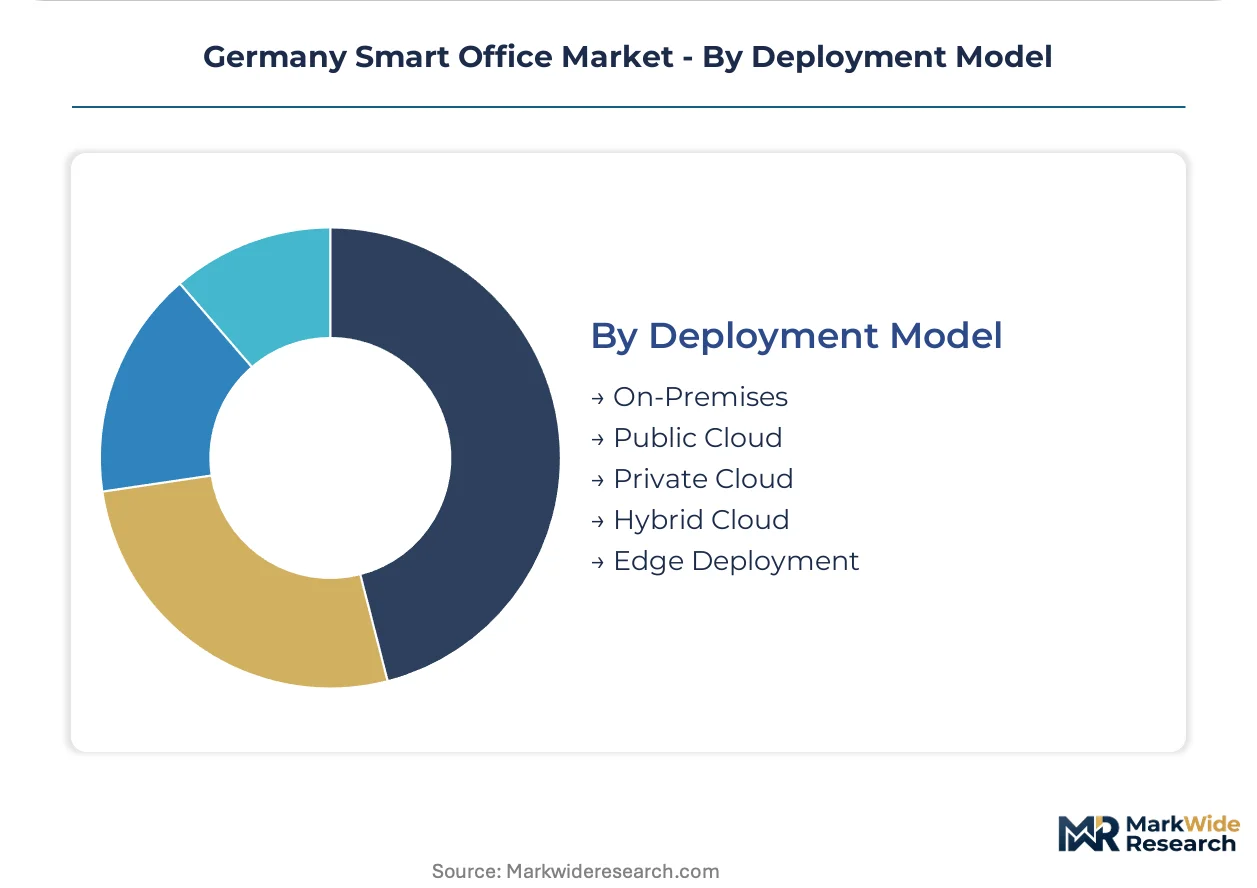
Hybrid Cloud dominates new procurement decisions, with Edge Deployment expanding most quickly in underpenetrated Saxony and Thuringia markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in smart office deployment favors western German Länder where GEG compliance infrastructure already exists, while eastern markets present retrofit cost gaps that delay procurement cycles. Facility managers in high-mandate regions absorb upfront sensor network investments faster than counterparts navigating legacy building constraints.
Baden-Württemberg
Automotive headquarters clusters in Stuttgart and surrounding engineering corridors concentrate the highest facility modernization budgets among German states. Corporate real estate teams at Bosch, Daimler, and Porsche specify unified workplace platforms integrating climate, security, and collaboration infrastructure. KBA energy efficiency standards bind these deployments to BACnet-compatible sensor networks with sub-100ms response thresholds for occupancy-driven HVAC adjustment.
Bavaria
Munich's financial services and technology campuses drive hybrid cloud architecture procurement balancing edge processing latency with portfolio-level analytics. CSRD disclosure mandates force large landlords to deploy building-level emissions tracking with audit-ready sensor traceability. The metropolitan region's software engineering density prioritizes API-first platforms enabling rapid protocol migration and third-party analytics integration.
Hesse
Frankfurt's banking headquarters elevate cybersecurity requirements for building system networks under BaFin supervisory expectations. Corporate real estate teams specify BACnet-compatible automation systems to meet GEG retrofit deadlines without vendor lock-in. The city's concentration of international financial institutions demands segregated data architectures that separate trading floor environmental controls from cloud-based portfolio benchmarking.
North Rhine-Westphalia
Ruhr Valley industrial conversion projects and Düsseldorf corporate headquarters create mixed-demand environments for smart office retrofitting. Legacy manufacturing buildings require extensive electrical infrastructure upgrades before KNX and BACnet sensor networks achieve full functionality. The state's building energy regulator enforces GEG compliance timelines that compress procurement cycles for centralized building management platforms.
Saxony
Underpenetrated commercial zones in Leipzig and Dresden present first-mover advantages for integrated workplace platform vendors as CSRD requirements expand to mid-cap landlords. Pre-2010 commercial stock dominates the regional inventory, demanding extensive electrical retrofitting before smart sensor deployment. Edge deployment architectures with localized compute nodes address unreliable broadband infrastructure while enabling standalone facility automation.
Germany Smart Office Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined building automation and AI-integrated workplace analytics. The vendor base stratifies across three maturity tiers: industrial automation heritage players with domestic manufacturing roots, European energy management specialists with deep compliance expertise, and North American building technology conglomerates with scale advantages. Competitive positioning hinges on M&A activity consolidating point-solution vendors into full-stack platforms, alongside strategic partnerships between sensor manufacturers and cloud analytics providers.
Among industrial automation heritage players, Siemens anchors the domestic tier with inherited strengths in programmable logic controllers and building management gateways. Schneider Electric exemplifies the European energy management specialist archetype, occupying a position defined by deep GEG compliance integration and carbon disclosure tooling. Bosch Building Technologies represents the converged safety-environmental platform model, sitting within a tier that merges fire safety, access control, and environmental monitoring into unified office infrastructure.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| ABB |
| Honeywell |
| Johnson Controls |
| Cisco Systems |
| Bosch Building Technologies |
| Philips Lighting |
| Crestron Electronics |
| Others |
Supply & Pricing Matrix
GEG retrofit mandates gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant component vendors while elevating BACnet-certified system integrators. Facility managers in Frankfurt and Munich absorb cost premiums for KNX-compatible sensor networks that satisfy audit-ready carbon disclosure requirements under CSRD rules.
Pricing Analysis
Distributor margins for building automation hardware compress as direct-to-OEM procurement channels expand among Baden-Württemberg automotive headquarters. Three-tier pricing structure across premium BACnet-certified, standard KNX-compatible, and economy non-integrated levels reflects certification grade and volume scale differentiation. Pricing pressure stems from certified technician shortages extending project timelines and inflating commissioning costs. Mid-cap landlords in eastern Länder exhibit highest price sensitivity, while financial services tenants in Frankfurt prioritize cybersecurity certification over unit economics.
Supply Chain Analysis
Germany's Building Energy Act local-content provisions reshape sourcing toward domestic KNX and BACnet gateway manufacturers. Component supply concentrates in Germany, China, and Taiwan for programmable logic controllers, occupancy sensors, and edge computing nodes. Raw material dependencies span semiconductor wafers, rare earth magnets for actuator motors, and copper wiring for building infrastructure. Single-source vulnerability in specialized sensor ASICs creates procurement risk for multi-site deployments. Distribution runs through authorized systems integrators with certified commissioning capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany Smart Office Market opportunity concentrates in geographic arbitrage between western Länder with GEG compliance infrastructure and underpenetrated eastern markets where CSRD expansion lags 18-24 months.
For Market Incumbents: Extend software-defined automation portfolios through API-first platform acquisitions that neutralize emerging cloud-native entrants. Siemens and Schneider Electric should deepen BACnet-KNX protocol bridging capabilities to reduce integration cost barriers that delay procurement decisions. Vertical integration into edge computing hardware secures supply continuity against semiconductor allocation volatility. For New Entrants and Emerging Players: Mid-cap landlords in Saxony and Thuringia commercial zones represent the most penetrable buyer archetype as CSRD disclosure requirements expand beyond large-cap portfolios. First-mover positioning in underpenetrated eastern Länder with edge deployment architectures bypasses legacy broadband constraints. Channel partnerships with regional systems integrators accelerate commissioning credibility without certified technician buildout. For Investors and Strategic Acquirers: Roll-up economics work for software-integrated workplace platform specialists because corporate real estate teams are consolidating vendor relationships around full-stack providers. Target acquisition archetypes include occupancy analytics startups with GDPR-compliant data governance and KNX-certified sensor manufacturers lacking cloud integration. Watch for Matter protocol adoption inflection as interoperability standardization triggers vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Bridging Investment | KNX-BACnet integration capabilities reduce procurement friction for multi-site facility managers. |
| Edge Computing Hardware Acquisition | Localized compute nodes address broadband reliability gaps in eastern German commercial zones. |
| CSRD Compliance Tooling Development | Audit-ready sensor traceability commands pricing premiums from Frankfurt and Munich landlords. |
| Certified Technician Training Programs | Commissioning labor shortages compress margins for systems integrators across German Länder. |
| Hybrid Cloud Platform Integration | Real-time edge processing with portfolio analytics satisfies Baden-Württemberg automotive requirements. |
Research Methodology
Multiple input streams — primary interviews with facility managers, corporate real estate executives, and building automation engineers, alongside secondary validation through EU regulatory filings and German federal construction statistics — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed systems integrators, KNX/BACnet certification bodies, and commercial property developers. Secondary sources included GEG implementation guidance, CSRD technical standards, and federal building energy audit databases.
Data-stream reconciliation across technology deployment models, application segments, and regional regulatory clusters shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed IoT sensor categories, automation system architectures, deployment models, and end-user industry verticals. CAGRs were derived from installation base expansion rates, retrofit cycle timing, and compliance-driven replacement demand. Industry-specific inputs incorporated GEG enforcement timelines, CSRD disclosure phase-in schedules, and KNX/BACnet protocol adoption trajectories.
Underlying measurement precision varies by segment; Energy Management and Hybrid Cloud deployment carry tighter precision than emerging Workspace Optimization applications. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology interoperability convergence. Supply chain disruption, protocol standardization delays, or CSRD timeline modifications could revise trajectory estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Video Management System Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
US Digital Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Barcode Software Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Australia ICT Market