
 Industrial Tablet PC Market | 2026-2036
Industrial Tablet PC Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Tablet PC Market Foresight
Manufacturing floor digitization is restructuring procurement priorities across heavy industry. Zebra Technologies Corporation dominates enterprise mobility with deep channel control across North American distribution networks. Getac Technology Corporation specializes in military-grade enclosures that sustain premium positioning in defense and oilfield applications. Panasonic Corporation anchors Japanese industrial automation through decades of Toughbook brand equity and direct OEM relationships.
An industrial tablet PC is a hardened computing device engineered with reinforced chassis materials, extended temperature tolerance, and ingress protection ratings to operate reliably in dusty, wet, or vibration-intensive environments. These units typically integrate resistive or capacitive touchscreens readable under direct sunlight, sealed ports, and hot-swappable battery architectures to maintain continuous workflow in field service, warehouse management, and plant-floor supervision. Rugged tablets lead unit shipments due to replacement cycles in logistics fleets, while Windows operating systems command the installed base through backward compatibility with legacy SCADA and ERP clients. Android is displacing legacy platforms in last-mile delivery and retail inventory where custom app ecosystems compete on total cost of ownership.
OSHA workplace safety mandates and FCC emissions certifications shape baseline product requirements for US market entry, while REACH substance restrictions and CE marking directives govern European material compliance and recyclability obligations. The EU AI Act will soon impose algorithmic transparency requirements on tablets running predictive maintenance or computer-vision quality control software. Stakeholders must weigh certification stacking costs against the margin premium of multi-standard platforms that qualify for defense, healthcare, and hazardous location tenders without hardware redesign.
Market Dynamics
Manufacturing floor digitization is restructuring procurement priorities across heavy industry, compressing replacement cycles for consumer-grade devices and elevating MIL-STD-810H certification to a baseline requirement for automotive and chemical processing tenders.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is forcing refrigerant-dependent cooling systems out of hazardous environment tablets, accelerating demand for passive thermal management designs in German chemical corridors.
- Automotive OEM digitization:Volkswagen, BMW, and Mercedes-Benz assembly plants are replacing paper work instructions with rugged tablets, driving volume concentration in Stuttgart, Munich, and Wolfsburg industrial clusters.
- Resistive-to-capacitive touchscreen migration:PCAP technology with wet-finger and glove operation is displacing legacy resistive panels in food processing and cold storage logistics, enabling UI modernization without workflow disruption.
Market Restraints
- Indium tin oxide supply concentration:Over 80% of refined indium originates from Chinese smelters, exposing PCAP manufacturers to export quota volatility and price spikes for transparent conductive oxide layers.
- REACH substance restrictions:ECHA's evolving SVHC candidate list forces iterative material requalification, extending product development timelines by 8-14 months for chassis alloys and conformal coatings.
- Consumer tablet substitution:Samsung Galaxy Tab Active and Apple iPad Pro with third-party rugged cases capture price-sensitive field service segments, compressing margins for purpose-built industrial units below $800.
Strategic Opportunities
- EU AI Act compliance services:Algorithmic transparency mandates for predictive maintenance tablets create adjacent revenue streams in documentation, audit trails, and explainability toolkits for computer-vision quality control deployments.
- Edge AI accelerator integration:Convergence of ARM-based SOCs with dedicated NPU cores enables on-device inference for defect detection, opening pharmaceutical packaging and semiconductor wafer inspection applications previously served by fixed industrial PCs.
- Direct OEM contracting:BYD, CATL, and Northvolt battery gigafactories are bypassing distribution channels for volume tablet procurement, rewarding vendors with configure-to-order capabilities and embedded engineering support.
Industry Challenges
- Embedded Linux firmware talent scarcity:Android and Windows dominance has thinned the developer pool for Yocto and Buildroot customization, complicating long-term support commitments for 10-year lifecycle defense contracts.
- ATEX/IECEx certification backlog:Notified body capacity constraints in Germany and the UK extend hazardous location approval timelines to 14-18 months, delaying product launches for oilfield and mining segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Tablet PC Market |
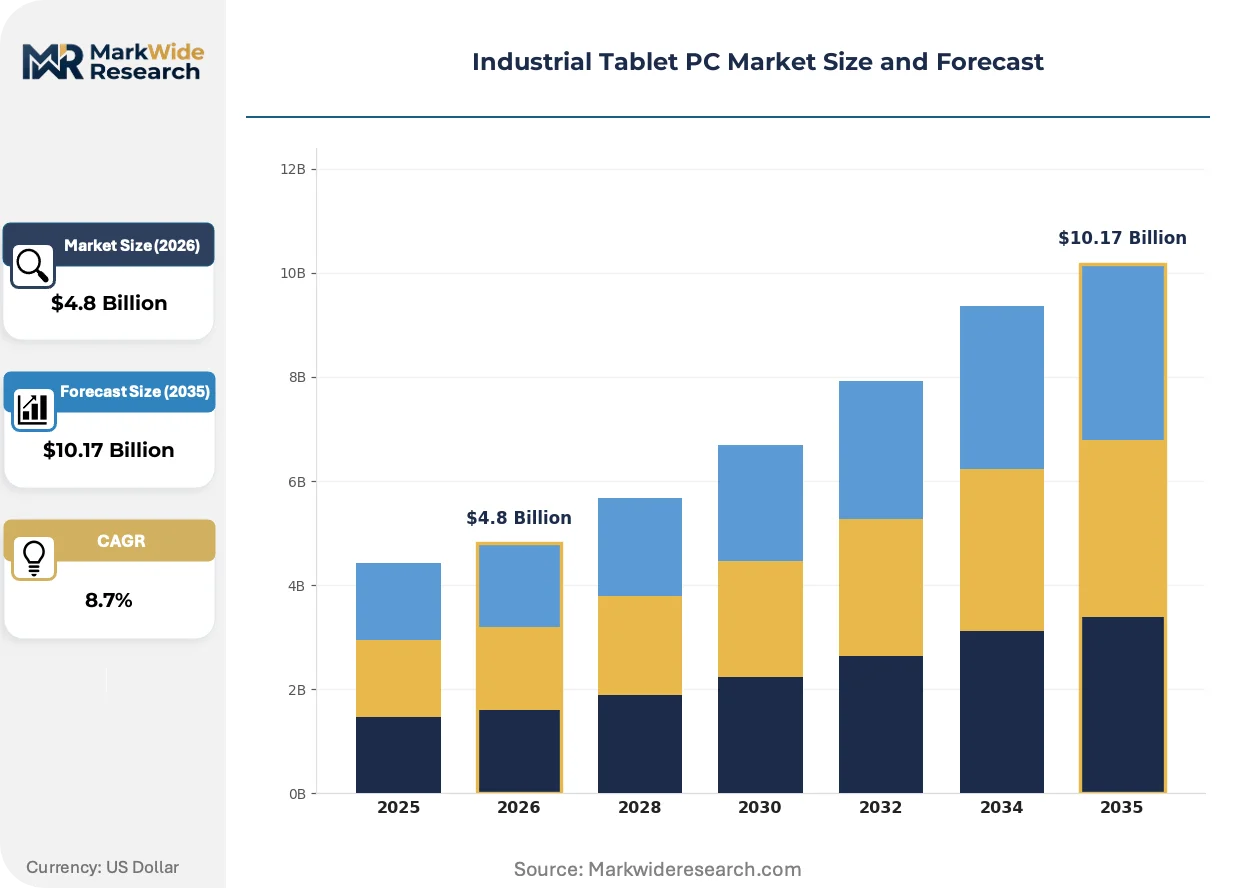
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rugged Tablet, Fixed Tablet, Convertible Tablet, Handheld Tablet End User: Manufacturing, Logistics, Healthcare, Construction Connectivity: Wi-Fi, Bluetooth, Cellular, NFC Operating System: Windows, Android, Linux, iOS |
| Companies Covered | Lenovo Group Limited, Zebra Technologies Corporation, Samsung Electronics Co Ltd, Handheld Group, Getac Technology Corporation, Dell Technologies, Panasonic Corporation, MobileDemand, Advantech Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Tablet PC Market Shifts & Advancements
Active thermal management architectures, algorithmic compliance frameworks, and procurement centralization are converging to redefine how industrial tablets are specified, certified, and deployed across heavy industry verticals.
Phase-change materials and vapor chamber assemblies are displacing fan-based cooling in MIL-STD-810H tablets, enabling sealed enclosures that sustain 60°C operational ceilings without particulate ingress. Automotive paint shop and foundry operators in Germany's industrial corridor are adopting these designs fastest, compressing the performance gap between fanless rugged units and traditional actively-cooled industrial PCs. Fanless thermal design is consolidating the mid-range segment, forcing incumbent vendors to retool chassis architectures or retreat to premium defense-only positioning.
The EU AI Act's risk-classification framework for machine-learning-enabled devices imposes documentation burdens on tablets running predictive maintenance or automated optical inspection software. Industrial OEMs must now maintain technical files demonstrating algorithmic robustness, data governance, and human oversight protocols for quality control deployments. German automotive and French pharmaceutical manufacturers are most affected, with compliance costs driving consolidation toward vendors offering pre-certified software stacks.
Consolidated procurement through corporate fleet management platforms is displacing site-level purchasing autonomy in logistics and field service organizations. DHL, DB Schenker, and Kuehne+Nagel are centralizing tablet standardization across European distribution networks, favoring vendors with pan-European service depot coverage and unified endpoint management APIs. This concentration is most visible in the Netherlands and Germany, where 3PL procurement teams now mandate 5-year total cost of ownership guarantees including damage replacement and firmware lifecycle commitment.
Industrial Tablet PC Market Segmentation
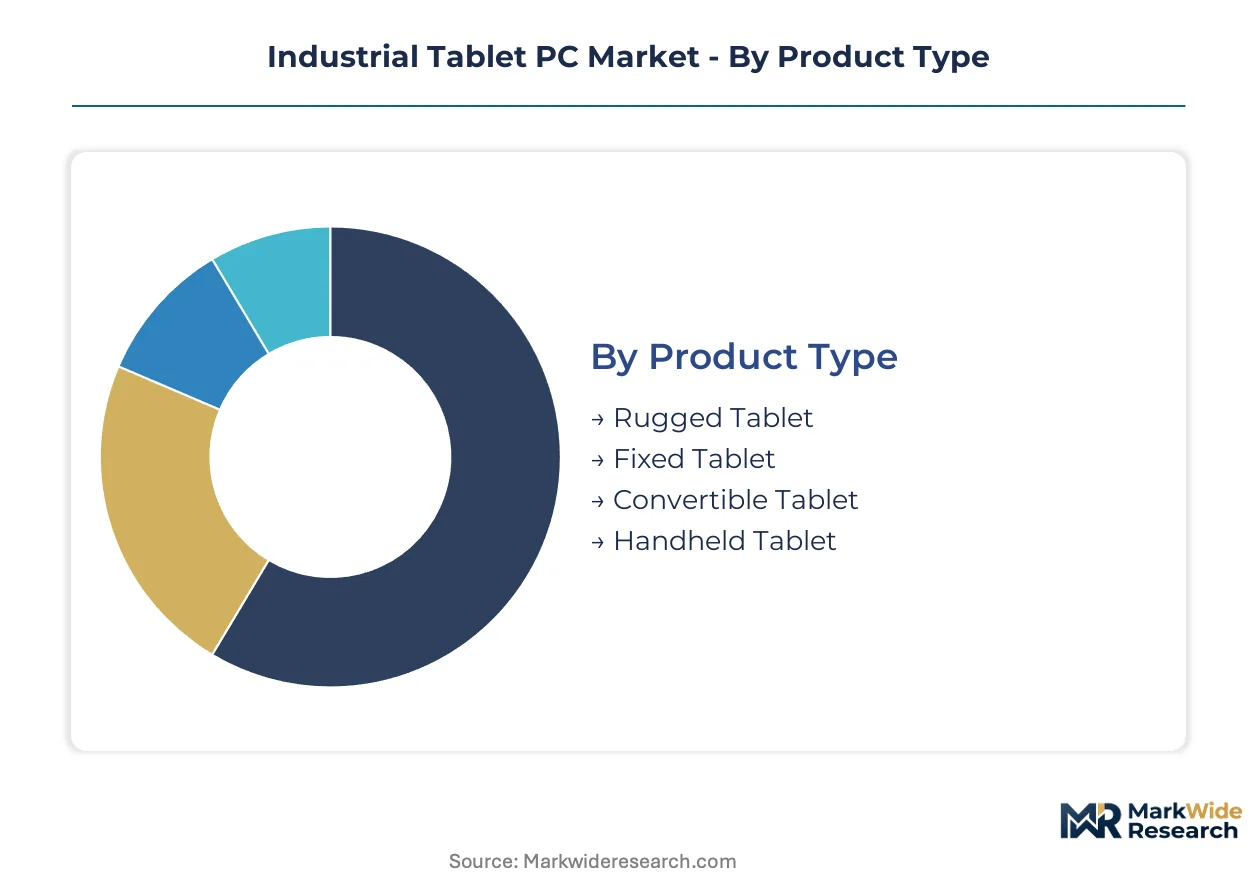
Industrial tablet procurement patterns diverge sharply across product architecture, end-use environment, and integration requirements. Certification stacking costs and legacy system compatibility create distinct buyer cohorts with non-overlapping specification priorities.
Product Type:
Form factor selection tracks environmental exposure severity and mobility requirements across buyer organizations.
- Rugged Tablet:Reinforced chassis assemblies with MIL-STD-810H shock ratings and IP65+ ingress protection sustain drops from 1.2 meters onto concrete. Demand concentrates in German automotive assembly plants where paint shop humidity and welding floor particulates destroy consumer-grade hardware within months.
- Fixed Tablet:Panel-mount enclosures with VESA bracketing and passive thermal management anchor machine HMI stations and production line dashboards. Procurement clusters in Japanese semiconductor fabs and South Korean battery gigafactories requiring 24/7 operational continuity without battery maintenance cycles.
- Convertible Tablet:Detachable keyboard docks with stylus digitizers serve field engineering and inspection workflows.
- Handheld Tablet:Single-hand grip designs with integrated barcode scanners dominate warehouse picking operations.
Volume sits with Rugged Tablet; growth tilts toward Fixed Tablet.
End User:
Vertical-specific compliance regimes and workflow integration depth shape procurement decision criteria.
- Manufacturing:SCADA integration requirements and ATEX/IECEx hazardous location certifications dominate specification sheets. German chemical processors and French pharmaceutical packagers drive premium-tier demand for tablets running predictive maintenance algorithms under the EU AI Act framework.
- Logistics:Cold chain tolerance, glove-compatible touchscreens, and fleet management API compatibility determine vendor selection. Dutch and German 3PL operators centralize procurement across European distribution networks, mandating unified endpoint management and 5-year total cost of ownership guarantees.
- Healthcare:FDA 510(k) clearance and HIPAA-compliant encryption architectures filter vendor pools.
- Construction:Sunlight-readable displays and dust-sealed port covers address outdoor site conditions.
Procurement scale clusters in Logistics; margin expansion favors Manufacturing.
Connectivity:
Real-time data transmission requirements and infrastructure availability determine radio module configuration.
- Cellular:LTE and 5G modems with dual-SIM failover enable fleet tracking and remote diagnostics where Wi-Fi infrastructure is absent. Last-mile delivery operators in rural Germany and construction sites across Spain and Italy drive module attach rates above 70% in field-service deployments.
- Wi-Fi:Wi-Fi 6E and emerging Wi-Fi 7 support high-density warehouse environments with roaming handoff requirements. Automated storage and retrieval systems in Belgian and Dutch distribution centers demand sub-20ms latency for pick-to-light coordination.
- Bluetooth:Low-energy pairing with peripheral sensors and wearable devices.
- NFC:Contactless authentication and payment processing in retail and healthcare access control.
Deployment breadth favors Wi-Fi; attach rate growth steepest in Cellular.
Operating System:
Legacy application compatibility and developer ecosystem maturity divide procurement between enterprise IT standards and mobile-native workflows.
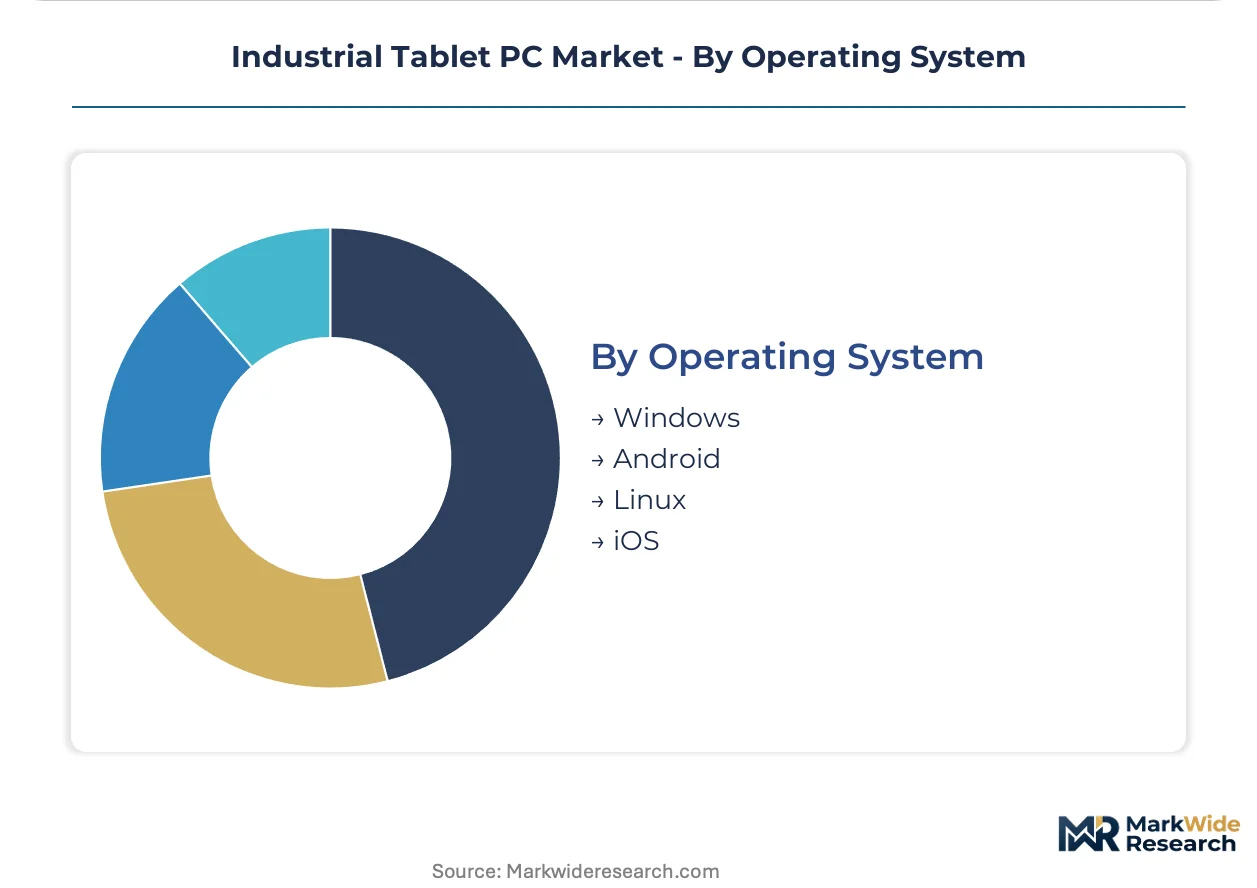
- Windows:Full x86 application compatibility preserves investments in legacy SCADA clients, ERP terminals, and engineering workstations. German automotive OEMs and Japanese industrial automation providers specify Windows IoT Enterprise for 10-year lifecycle commitments and direct Microsoft long-term servicing channel access.
- Android:Custom app ecosystem flexibility and lower total cost of ownership attract logistics and retail inventory operators. Last-mile delivery fleets in France and grocery chains in Spain deploy Android Enterprise with zero-touch provisioning for rapid device replacement.
- Linux:Yocto and Buildroot customization for defense and aerospace applications requiring source code auditability.
- iOS:Consumer-grade hardware with third-party rugged cases captures price-sensitive field service segments below $800 price points.
Installed base dominance rests with Windows; share expansion runs through Android.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial tablet PC production concentrates in East Asian electronics manufacturing hubs, while consumption gravity pulls toward German automotive corridors and North American logistics networks. This geographic asymmetry shapes certification requirements and supply chain configurations across vendor portfolios.
Germany
Automotive OEM digitization at Volkswagen, BMW, and Mercedes-Benz assembly plants drives MIL-STD-810H procurement volumes. The EU F-Gas Regulation accelerates passive thermal design adoption for chemical processing environments. Stuttgart, Munich, and Wolfsburg industrial clusters standardize on rugged tablets for paint shop and welding floor deployments.
United States
OSHA workplace safety mandates and FCC emissions certifications establish baseline entry requirements for field service and warehouse management segments. Three logistics operators centralize procurement across distribution networks, mandating unified endpoint management APIs. Midwest automotive plants and Southeast battery gigafactories bypass distribution channels for direct vendor contracting.
China
Indium tin oxide supply concentration from domestic smelters exposes PCAP manufacturers to export quota volatility. MIIT industrial digitization directives accelerate replacement cycles in state-owned heavy industry. Yangtze River Delta electronics fabricators and Pearl River Delta battery producers drive fixed tablet demand for panel-mount HMI stations.
Japan
METI industrial automation standards preserve Windows IoT Enterprise dominance through decade-long lifecycle commitments. Semiconductor fabrication facilities in Kyushu and Chubu specify fixed tablets for cleanroom environments. Kanto region automotive suppliers maintain direct OEM relationships with established vendor ecosystems.
Netherlands
CE marking directives and REACH substance restrictions govern material compliance for pan-European distribution. Rotterdam and Venlo logistics hubs centralize tablet standardization across 3PL networks, requiring five-year total cost of ownership guarantees. Dutch procurement teams mandate damage replacement and firmware lifecycle commitments in fleet contracts.
Industrial Tablet PC Market Competitive Landscape
Top-tier vendors anchor premium defense and automotive certifications, while mid-tier specialists compete on configure-to-order flexibility and regional service depot coverage. The vendor base stratifies across three functional tiers: full-stack platform providers with direct OEM relationships, component-integrated specialists serving vertical applications, and regional fabricators competing on price-sensitive field service segments. Consolidation pressure runs through M&A activity targeting edge AI capabilities and strategic partnerships for pan-European service networks.
Within the defense-grade enclosure tier, Getac Technology Corporation and Panasonic Corporation exemplify premium positioning through MIL-STD-810H certification depth. Zebra Technologies Corporation occupies a position in enterprise mobility through North American distribution channel control. These three anchors represent divergent strategic postures: military-grade specialization, brand equity in industrial automation, and logistics fleet standardization.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| Zebra Technologies Corporation |
| Samsung Electronics Co Ltd |
| Handheld Group |
| Getac Technology Corporation |
| Dell Technologies |
| Panasonic Corporation |
| MobileDemand |
| Advantech Co Ltd |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply for passive thermal management designs while compressing premium-tier pricing access for vendors serving German chemical processors and automotive paint shops. Buyers without certified chassis architectures face extended requalification timelines that inflate total cost of ownership and disqualify them from hazardous environment tenders.
Pricing Analysis
Margin tightening in the mid-range segment reflects consumer-grade tablet substitution with third-party rugged cases. Three-tier pricing structure across MIL-STD-810H certified, IP65 industrial-grade, and economy field-service tiers separates automotive OEM procurement from logistics fleet standardization. Price differentiation rests on certification depth and pan-European service depot coverage. Cost-down pressure on economy tiers accelerates because Samsung and Apple capture price-sensitive segments below eight hundred dollars. Logistics operators demonstrate highest price sensitivity through centralized procurement mandates, while defense contractors exhibit lowest sensitivity due to decade-long lifecycle commitments.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and Japan's precision manufacturing corridors concentrate high-reliability component fabrication. Raw material dependencies include indium tin oxide from Chinese smelters, lithium-polymer cells from Yangtze River Delta producers, and ARM-based SOC wafers from TSMC foundries. Supply chain risk centers on export quota volatility for transparent conductive oxide layers that feed PCAP touchscreen production. Distribution runs through North American value-added resellers, German industrial automation distributors, and direct OEM contracting with battery gigafactories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive touchscreen migration with wet-finger and glove operation is displacing legacy resistive panels, creating a technology-transition phase where UI modernization reshapes vendor competitive position.
For Market Incumbents: Hedge against consumer-grade substitution by deepening MIL-STD-810H certification portfolios and securing direct OEM relationships with automotive and battery manufacturers. Channel control through pan-European service depot networks defends margin position against mid-tier configure-to-order specialists. Investment in edge AI accelerator integration addresses the threat of fixed industrial PC vendors encroaching on quality control applications. For New Entrants and Emerging Players: Launch via direct contracting with gigafactory operators in the US Midwest and European battery corridors, bypassing entrenched distribution relationships. BYD, CATL, and Northvolt procurement teams represent the most penetrable buyer cohort due to their volume concentration and engineering support requirements. Target EU AI Act compliance services as an adjacent revenue stream, offering documentation and audit trail toolkits for predictive maintenance deployments. For Investors and Strategic Acquirers: ATEX/IECEx certification backlog extension to fourteen-to-eighteen months is the leading indicator that notified body capacity constraints will consolidate vendor tiers through acquisition. Long-term viability favors platforms with multi-standard certification stacking that qualifies for defense, healthcare, and hazardous location tenders without hardware redesign. Acquisition target archetype: mid-tier specialists with configure-to-order capabilities and embedded Linux firmware talent for ten-year lifecycle defense contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Passive Thermal Design Investment | EU F-Gas Regulation compliance unlocks German chemical corridor procurement without refrigerant-dependent cooling systems. |
| Edge AI Accelerator Integration | ARM-based SOCs with NPU cores enable pharmaceutical packaging defect detection previously served by fixed industrial PCs. |
| Direct OEM Contracting Capability | Configure-to-order engineering support captures volume procurement from battery gigafactories bypassing distribution channels. |
| Pan-European Service Depot Expansion | Unified endpoint management APIs satisfy DHL and DB Schenker centralized fleet standardization mandates. |
| EU AI Act Compliance Pre-Certification | Algorithmic transparency documentation reduces German automotive OEM technical file preparation burdens. |
Research Methodology
SEC filings, ECHA substance restriction updates, and MIIT industrial digitization directives formed the secondary backbone, supplemented by customs trade data and OEM procurement database tracking. Primary interviews with plant engineers at German automotive assembly facilities, maintenance directors in Dutch logistics hubs, procurement leads at battery manufacturers, and aftermarket service heads at industrial distributors validated demand assumptions. Bottom-up unit shipment modeling and top-down value aggregation triangulated market size across rugged, fixed, convertible, and handheld form factors.
Historical trendline analysis of replacement cycle compression and certification stacking cost trajectories informed projection methodology. Segmentation dimensions modeled include product architecture, end-use vertical, connectivity configuration, and operating system ecosystem across the projection horizon. CAGRs derived from regression analysis of procurement volume concentration in automotive digitization and logistics fleet standardization. Forecast inputs incorporated F-Gas Regulation phase-down timelines and ATEX/IECEx approval capacity constraints.
Regulatory enforcement variance, indium export quota disruption, and consumer-grade substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding OEM digitization commitment durability and hazardous location certification backlog resolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Halal Food & Beverage Market
Others
Printed Leather Market
Others
France Location-Based Services Market
Others
Hopper Dryers Market
Others
North America Smart Homes Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Coalescing Filter Market
Others
Magnesite Market
Others
Workbench Tanks Market
Others
Europe Battery Packaging Market
Others
Foldable Smartphone Market
Others
Social Media Engagement Applications Market
Others
Europe Astrology Market
Others
Pet Care Packaging Market
Others
Agitator Bead Mill Market
Others
Canada Laser Hair Removal Market