
 Snus Market | 2026-2036
Snus Market Size, Share, and Industry Trends Forecast 2026-2036
Snus Market Intelligence
The migration of consumer spending from combustible cigarettes to smokeless alternatives is rewriting the profit landscape for tobacco companies. Swedish Match AB sustains market leadership through deep-rooted brand loyalty in Scandinavia. British American Tobacco competes aggressively with its expanding portfolio of white snus products. Separately, Philip Morris International positions itself within the broader reduced-risk category through strategic product development.
Snus is a moist, pasteurized smokeless tobacco product, typically placed under the upper lip for nicotine absorption. Its composition includes finely ground tobacco, water, and salt, with a unique heat-treatment process distinguishing it from fermented dipping tobaccos. The White Snus product type is rapidly gaining preference over traditional formats, driven by its non-staining characteristic. Portion Snus continues to dominate sales volumes for its pre-packaged convenience, with Mint flavors leading the Flavor Profile segment.
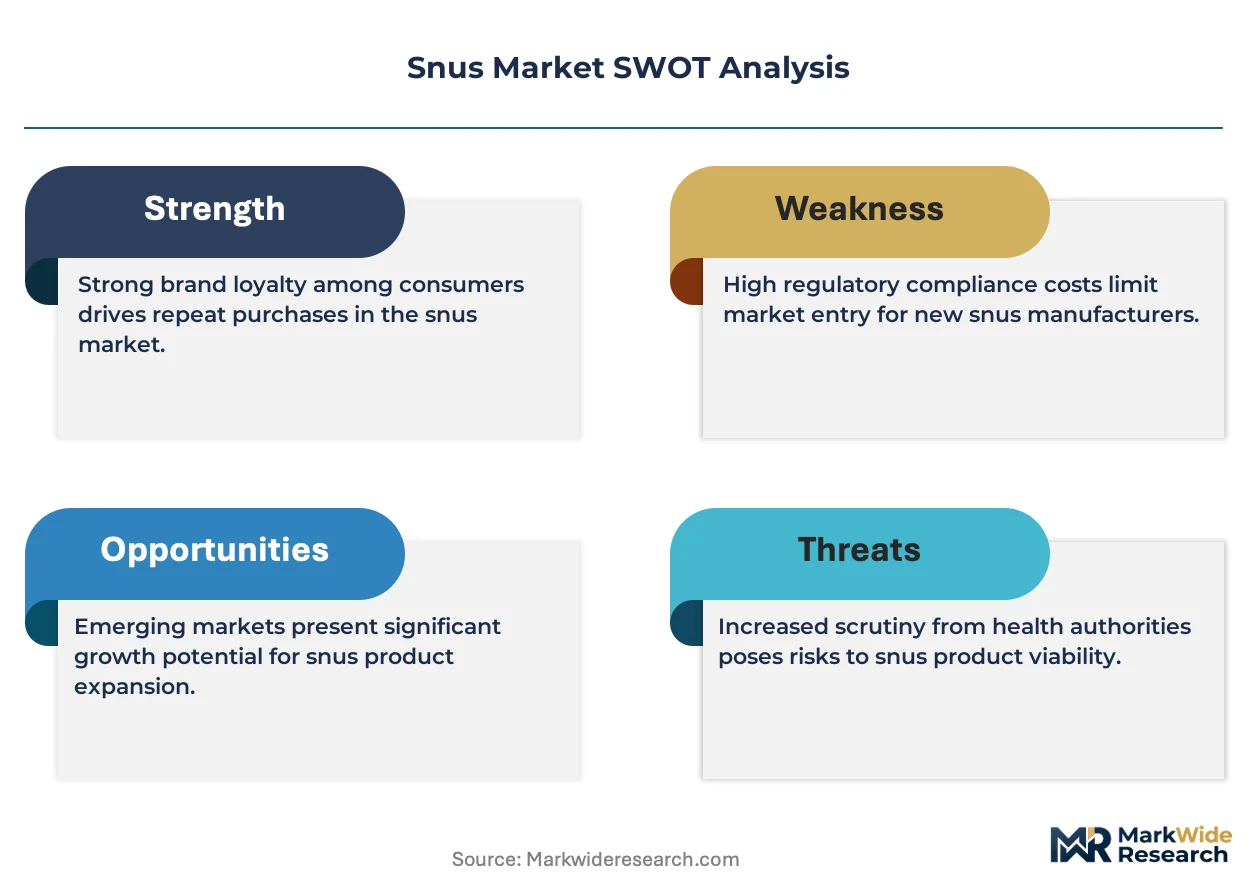
Regulatory approaches vary significantly, with Sweden's Livsmedelsverket classifying snus as a food product, imposing distinct quality controls. In contrast, the US FDA regulates it as a tobacco product, utilizing a Modified Risk Tobacco Product pathway for certain items. The European Union's general ban on sales outside Sweden further complicates market access. Navigating these divergent regulatory landscapes remains the central strategic challenge for all market participants.
Market Dynamics
The market's core dynamic is the stark divergence in regulatory frameworks. This spans from Sweden's food-product classification under Livsmedelsverket to the EU's ban and the US FDA's risk-modification pathway, creating fragmented global access.
Growth Catalysts
- Modified Risk Pathways:The US FDA's Modified Risk Tobacco Product (MRTP) framework provides a scientifically-vetted route to market, legitimizing certain snus products as less harmful alternatives to cigarettes for adult smokers.
- Harm Reduction Demand:Adult smokers in countries like Norway and the United States are actively seeking non-combustible nicotine products, driven by health concerns and restrictive public smoking laws.
- Product Innovation:The development of white snus, which does not stain teeth, directly addresses a key aesthetic concern for consumers, broadening the product's appeal beyond traditional user bases.
Market Restraints
- EU Sales Prohibition:The European Union's comprehensive ban on the sale of snus in all member states except Sweden represents the single largest structural barrier to market expansion in the region.
- Public Health Stigma:In many countries, snus is incorrectly conflated with other smokeless tobacco products like dipping tobacco, leading to negative public perception and restrictive local policies.
- Alternative Nicotine Products:Intense competition from nicotine pouches, which are often tobacco-free and subject to different, sometimes less stringent, regulations, presents a significant substitution threat.
Strategic Opportunities
- New Market Entry:Exploring markets in Asia, such as Japan, where there is a high prevalence of smoking and an evolving regulatory stance on reduced-risk products, offers significant long-term growth potential.
- Digital Channel Expansion:Utilizing direct-to-consumer e-commerce platforms in legally permissive markets like the United States allows for greater brand control and direct engagement with adult consumers.
- Flavor Profile Diversification:Creating sophisticated flavor profiles beyond mint, such as botanical or fruit infusions, can attract a wider demographic of adult users seeking novel sensory experiences.
Industry Challenges
- Regulatory Navigation:Managing compliance across disparate legal frameworks, from Sweden's food safety laws to the US FDA's tobacco-specific premarket applications, demands significant legal and scientific expertise.
- Taxation Volatility:Abrupt changes in excise tax structures for smokeless tobacco products in key markets can severely impact pricing strategies and consumer demand with little warning.
- Quality Control at Scale:Ensuring uniform pasteurization and moisture content to meet stringent standards like those imposed by Livsmedelsverket becomes more complex as production footprints expand globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snus Market |
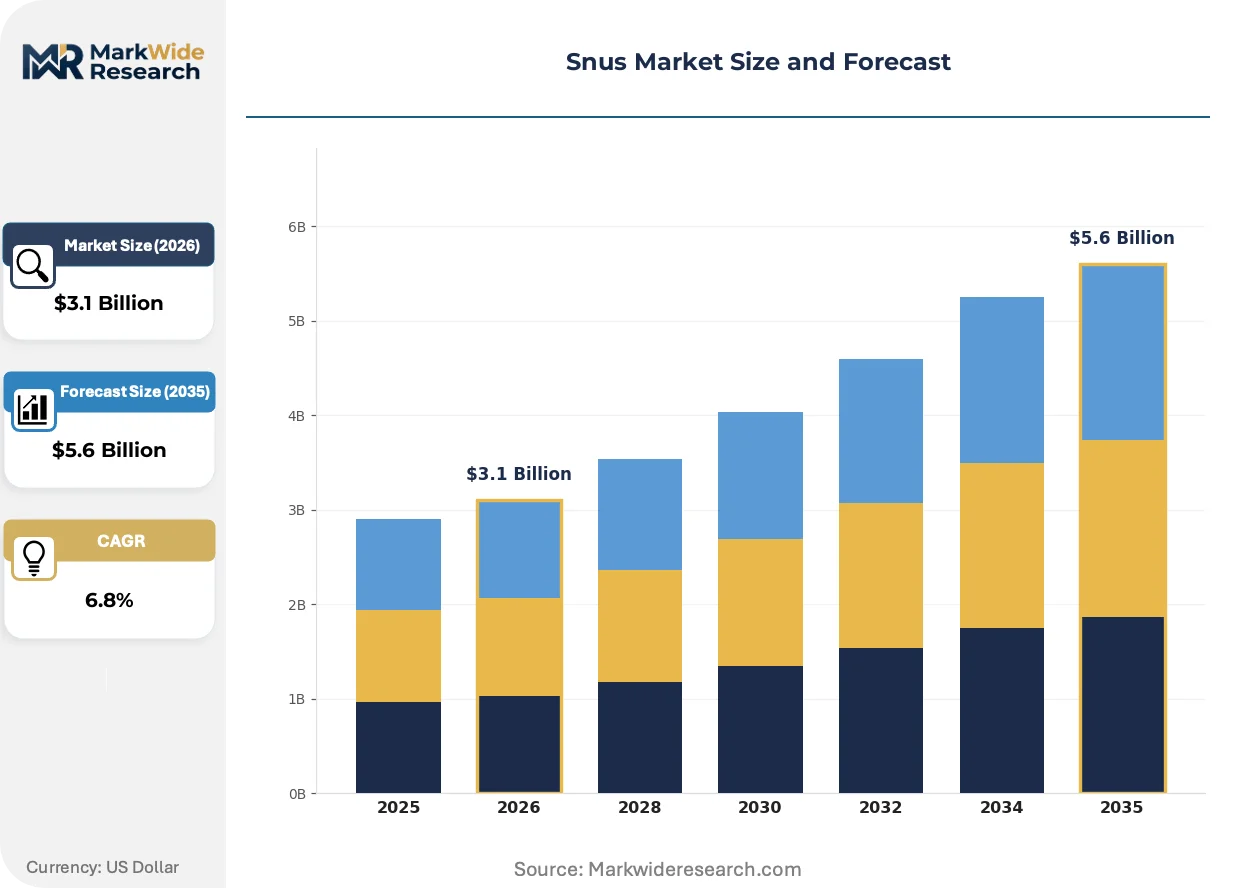
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Snus, White Snus, Portion Snus, Loose Snus Flavor Profile: Mint, Berry, Citrus, Coffee Packaging Type: Flexible Packs, Cans, Pouches, Bulk Packaging End User: Adult Smokers, Former Smokers, Nicotine Users, Others |
| Companies Covered | GN Tobacco Sweden AB, British American Tobacco, Swedish Match AB, Skruf Snus AB, Philip Morris International, Altria Group Inc., Japan Tobacco, Mac Baren, Imperial Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snus Market Strategic Shifts & Innovations
Product formulation and scientific substantiation are converging to redefine market boundaries. The evolution from traditional tobacco leaf to novel base materials and flavor systems is creating new categories and challenging established regulatory definitions.
Tobacco-free base materials infused with nicotine are gaining traction. Adult consumers aiming to lower or cease their tobacco consumption are the primary adopters. This development is hybridizing the category, creating a new segment that blurs the line between traditional snus and modern oral nicotine pouches.
The US FDA's Modified Risk Tobacco Product (MRTP) pathway has altered industry research priorities. This framework incentivizes investment in clinical studies to support reduced harm claims. Portion snus manufacturers are most affected, reorienting development to generate the evidence required for an MRTP application.
A pronounced consumer shift toward discrete, spitless oral products is accelerating. This change diminishes the relevance of traditional loose snus, particularly among new users. The trend is most visible in the United States, where consumers lack attachment to legacy formats and prioritize convenience.
Snus Market Segmentation
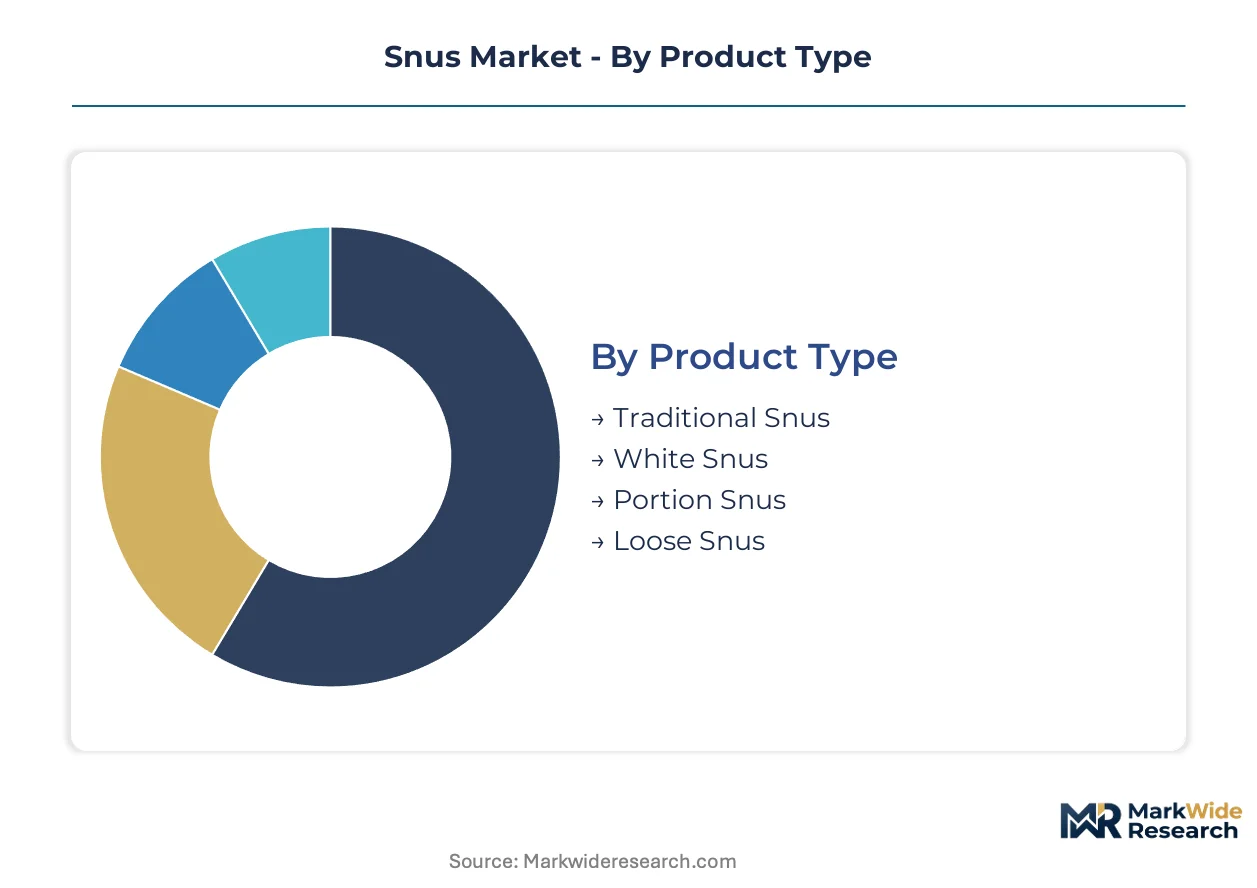
The Snus market’s structure reflects diverse product formats, consumer preferences, and packaging innovations. Understanding these granular divisions provides clarity on demand drivers and competitive dynamics. Each segment caters to specific user needs and regulatory environments across different geographies.
Product Type:
Product type segmentation highlights the primary forms of snus available to consumers.
- Portion Snus:This format consists of pre-portioned, often moist, tobacco enclosed in small pouches, designed for discreet placement under the lip. Its convenience and reduced mess drive high sales volumes, particularly in Scandinavian markets like Sweden.
- White Snus:Characterized by its tobacco-free or low-tobacco content and white appearance, this product aims to prevent teeth staining. It attracts new users in markets such as the United States, who prioritize aesthetic considerations and a cleaner experience.
- Traditional Snus:This category encompasses classic snus products, typically darker in color and made with heat-treated tobacco.
- Loose Snus:Unpackaged, moist tobacco that users manually form into a portion before placing it under the lip.
Portion Snus holds significant installed capacity. White Snus is rotating up the share rankings.
Flavor Profile:
Consumer preference for specific flavor profiles significantly influences product development and market penetration.
- Mint:This profile offers a refreshing and often cooling sensation, appealing to a broad user base seeking a clean taste. Mint flavors lead the overall Flavor Profile segment, particularly among new users in countries like the United States.
- Berry:Berry-infused snus products deliver a sweet and fruity experience, attracting users who prefer less traditional tobacco notes. This flavor category finds a strong reception among younger adult consumers in various European markets.
- Citrus:Offering a tangy and zesty taste, citrus flavors provide an alternative for users desiring a sharp, refreshing experience.
- Coffee:Coffee-flavored snus appeals to consumers seeking a robust, aromatic experience often associated with traditional tobacco.
Mint flavors dominate the market. Berry profiles are steadily expanding their consumer base.
Packaging Type:
Packaging type dictates the convenience and discreetness of snus consumption for the end-user.
- Pouches:These small, permeable bags contain pre-portioned snus, offering a mess-free and discreet method of use. Their design directly supports the popularity of portion snus, especially in markets where hygiene and convenience are priorities.
- Cans:Traditional round or rectangular containers house both loose and portion snus, providing protection and easy access for daily users. Cans remain a standard packaging choice, particularly for established brands in Scandinavian countries.
- Flexible Packs:Lightweight and often resealable packaging options offer portability and reduced material usage for certain snus varieties.
- Bulk Packaging:Larger quantities of loose snus are sold in bulk, typically catering to long-term users or specific retail models.
Pouches represent the most common delivery format. Cans maintain a strong presence for traditional products.
End User:
End-user segmentation reflects the primary motivations and demographics driving snus adoption.
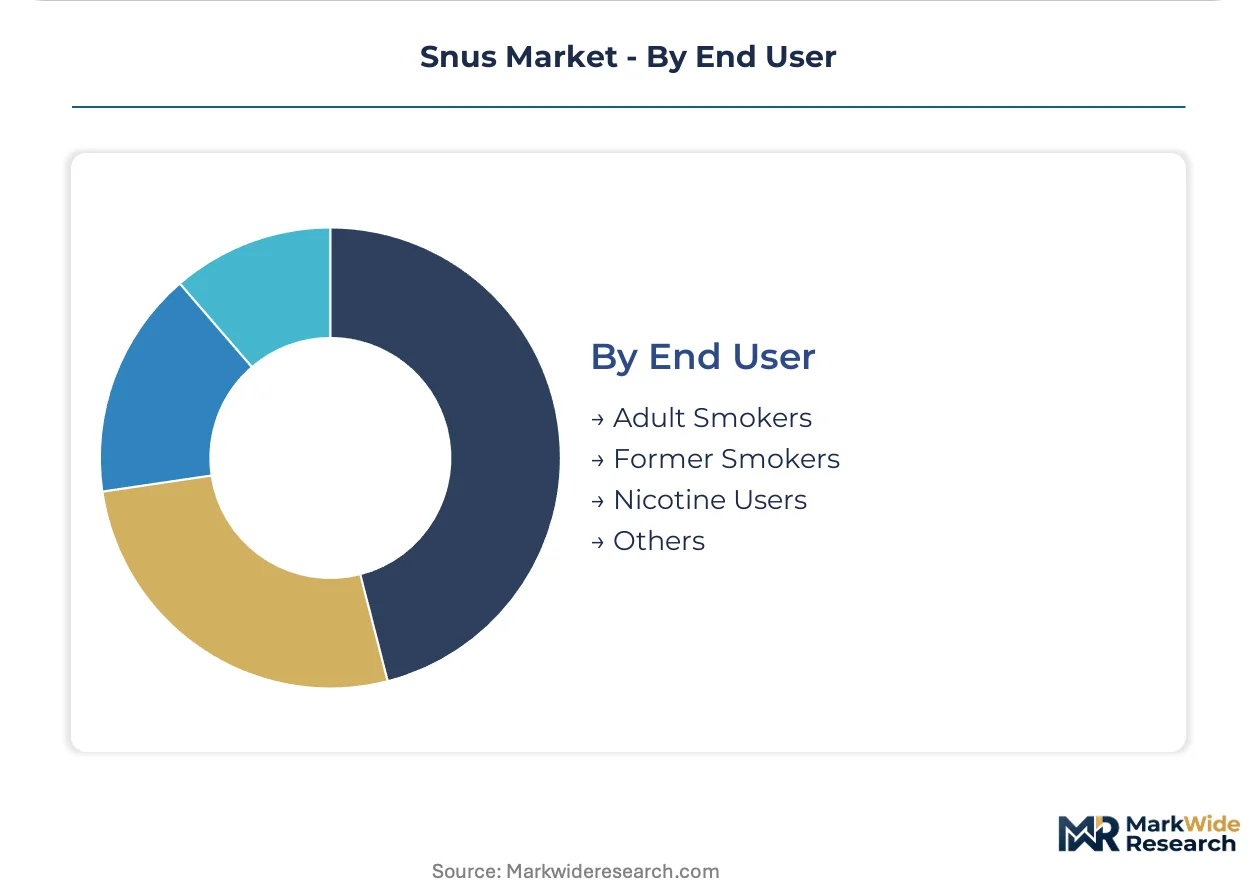
- Adult Smokers:This group comprises individuals actively seeking reduced-risk alternatives to combustible cigarettes, often driven by health concerns or public smoking restrictions. Demand from adult smokers is particularly high in the United States and Norway.
- Former Smokers:Individuals who have ceased smoking but continue to seek nicotine through less harmful oral products fall into this category. Their transition often involves products like snus as a bridge from traditional tobacco.
- Nicotine Users:This broad category includes individuals who consume nicotine through various products, seeking its effects regardless of tobacco content.
- Others:This segment encompasses occasional users or those experimenting with snus for recreational purposes outside the primary cessation or harm reduction motivations.
Adult Smokers are the largest consumer group. Former Smokers represent the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for snus products varies significantly across mature and emerging markets. Consumers in established Scandinavian markets often exhibit lower elasticity due to deep-rooted cultural acceptance and brand loyalty. Conversely, new users in expansion markets, such as the United States, are more responsive to pricing strategies and product innovation.
Sweden
Demand for snus in Sweden is driven by strong cultural acceptance and a preference for traditional smokeless tobacco. Sweden's Livsmedelsverket classifies snus as a food product, imposing distinct quality controls on its production. Stockholm remains a hub for product development, with Swedish Match AB sustaining market leadership through established brand loyalty.
Norway
Adult smokers in Norway actively seek non-combustible nicotine products, driven by health concerns and restrictive public smoking laws. Health authorities in Norway have supported harm reduction strategies, allowing snus as an alternative to combustible products. Oslo's urban centers show high consumption rates, with consumers adopting white snus for its aesthetic benefits.
United States
The US market experiences significant expansion, with adult smokers seeking alternatives to combustible cigarettes. The US FDA regulates snus as a tobacco product, utilizing the Modified Risk Tobacco Product (MRTP) pathway for certain items. Demand concentrates in states like California and New York, where product innovation targets new user demographics.
Japan
Japan presents a strategic opportunity due to its high prevalence of smoking and evolving regulatory stance on reduced-risk products. The Ministry of Health, Labour and Welfare (MHLW) monitors novel tobacco products, influencing market entry for smokeless alternatives. Tokyo's urban consumers show interest in discrete oral products, aligning with global trends in convenience.
Germany
The German market faces significant access challenges due to the European Union's comprehensive ban on snus sales. Despite the EU ban, some German consumers access snus through cross-border trade, highlighting underlying demand. Berlin's urban areas occasionally see niche distribution, though official market participation remains restricted by EU directives.
Snus Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, defining the snus market's competitive structure. The market exhibits a tiered consolidation, with established tobacco giants maintaining strong positions alongside specialized snus producers. Strategic archetypes include traditional Scandinavian leaders, global tobacco diversifieds expanding their smokeless portfolios, and innovation-focused oral nicotine developers. Portfolio diversification into white snus products and geographic expansion into new markets like the United States are dominant competitive moves among these players.
Within the global tobacco diversifieds, British American Tobacco and Philip Morris International exemplify the strategy of expanding into reduced-risk products. British American Tobacco, a global entity, occupies a position focused on an expanding portfolio of white snus products across various geographies. Philip Morris International, another international player, anchors its presence within the broader reduced-risk category through significant strategic product development. Swedish Match AB, a Swedish company, represents the traditional market leader, sustaining its position through deep-rooted brand loyalty, particularly in Scandinavian markets. These entities collectively drive market evolution and shape competitive dynamics.
| Leading Market Players |
|---|
| GN Tobacco Sweden AB |
| British American Tobacco |
| Swedish Match AB |
| Skruf Snus AB |
| Philip Morris International |
| Altria Group Inc. |
| Japan Tobacco |
| Mac Baren |
| Imperial Brands |
Cost & Logistics Intelligence
Undercapacity in specialized heat-treatment facilities for snus production drives both supplier behavior and pricing posture across the industry. This constraint particularly impacts manufacturers seeking to meet stringent quality controls like those imposed by Sweden's Livsmedelsverket.
Pricing Analysis
The recurring consumption revenue tier, derived from continuous customer engagement with established snus brands, drives product lifetime value. Per-unit transactional pricing dominates the market, with brand premium and quality grade serving as primary differentiation drivers. Pricing pressure stems from the high cost of regulatory compliance, particularly for US FDA Modified Risk Tobacco Product applications. New users in expansion markets like the United States exhibit higher price sensitivity compared to brand-loyal consumers in Scandinavia.
Supply Chain Analysis
Regulatory restriction, specifically the EU's ban on snus sales outside Sweden, dominates the supply chain risk profile. Geographic supply concentrates in Sweden and, for specific product formulations, the United States. Raw material dependencies include finely ground tobacco leaf, water, salt, and various flavorings. Distribution runs through traditional retail channels in permissive markets, increasingly supplemented by direct-to-consumer e-commerce platforms in legally compliant regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snus market represents an early-cycle expansion story, with harm reduction demand serving as a significant tailwind in consumer adoption. This shift creates distinct strategic imperatives for different market participants.
For Market Incumbents:Build regulatory compliance moats by investing heavily in US FDA Modified Risk Tobacco Product applications for existing and new product lines. Diversify the product portfolio aggressively into white snus formats to counter competition from tobacco-free nicotine pouches. Leverage deep-rooted brand loyalty in Scandinavian markets against emerging threats from alternative nicotine products. Expand manufacturing capacity in geographies with favorable regulatory frameworks, such as the United States, to scale production efficiently.
For New Entrants and Emerging Players:Establish a beachhead in underserved or rapidly evolving segments, such as the US market's adult smoker demographic seeking non-combustible alternatives. Target Asia, particularly Japan, where an evolving regulatory stance on reduced-risk products presents long-term growth potential. Focus on product innovation, including advanced flavor profiles beyond mint and novel tobacco-free base materials. Utilize direct-to-consumer digital channels as a primary go-to-market angle in legally permissive markets to build brand recognition and bypass traditional distribution barriers.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across the specialized manufacturing and regulatory compliance segments of the snus market. The long-term viability of this market hinges on its sustained role as a less harmful alternative to combustible tobacco, offering consistent growth. Acquisition targets should include innovation-focused oral nicotine developers with strong intellectual property in product formulation or regulatory approvals. FDA MRTP approvals for snus products serve as a key signal to watch for market legitimization and expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| MRTP Application Investment | Secures market access and consumer trust by legitimizing snus as a reduced-risk alternative. |
| White Snus Portfolio Expansion | Addresses aesthetic concerns and attracts new users, broadening the product's overall market appeal. |
| Digital Channel Development | Enhances direct consumer engagement and brand control in legally permissive e-commerce environments. |
| Flavor Profile Diversification | Attracts a wider adult demographic by offering novel sensory experiences beyond traditional mint. |
| Geographic Market Entry (Asia) | Unlocks significant long-term growth potential in regions with high smoking prevalence and evolving regulations. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through a structured primary interview program, complemented by extensive secondary validation. Interviews included tobacco executives, regulatory affairs specialists, product development scientists, and retail buyers across key markets. Secondary data sources encompassed FDA filings, Livsmedelsverket reports, industry trade publications, and company annual reports. This approach facilitated a robust bottom-up and top-down triangulation of market data.
The forecast framework employed a multi-factor analytical approach across the analysis window to project market trajectories. Segmentation dimensions modeled included product type, flavor profile, packaging type, end user, and regional regulatory cluster. Compound annual growth rates were derived through a proprietary quantitative model, integrating historical trends with forward-looking market dynamics. Public health guidelines and consumer smoking cessation rates served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global consumer discretionary spending or public health policy would shift the trajectory. Forecasts reflect assumptions documented through primary and secondary research, acknowledging potential risk factors such as abrupt regulatory changes or intensified public health campaigns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Qatar Smartphone Market
Others
Global Military Wearable Sensors Market
Others
Depth Gauge Market
Others
Hypersensitivity Market
Others
Global Sportswear Market
Others
Rotary Union Market
Others
APAC Machine Vision Systems Market
Others
Digital Media Adaptor (DMA) Market
Others
Asia-Pacific Camping and Caravanning Market
Others
US Automotive LED Lighting Market
Others
Fluid Bed Systems Market
Others
Spain Smart Home Market
Others
Egg Market
Others
Europe Transportation Management Systems Market
Others
3D Printing Construction Market
Others
Lepidolite Market