
 Thermoformed Plastics Market | 2026-2036
Thermoformed Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Plastics Market Intelligence
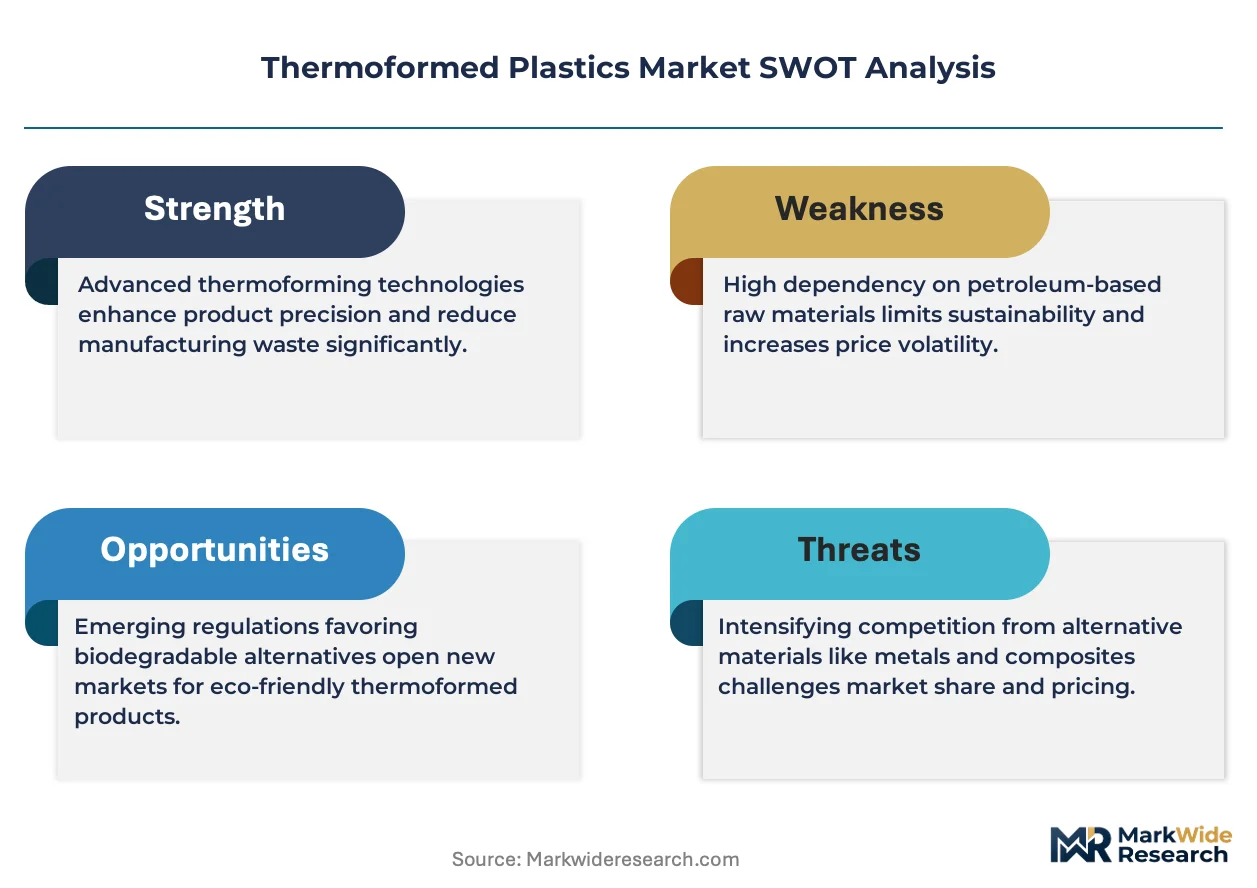
Germany is fragmenting thermoformed plastics capacity as automotive suppliers and packaging converters expand parallel sheet extrusion and forming lines. Pactiv LLC anchors North American foodservice tray production through integrated resin-to-package operations. Sonoco Products Company specializes in rigid paper-plastic hybrid formats for protein packaging. Greiner Packaging GmbH dominates European dairy and fresh-food container markets with in-house PET sheet capacity.
Thermoformed plastics are thermoplastic sheets heated above glass-transition temperature, vacuum- or pressure-formed over molds, then trimmed into finished shapes with typical gauge ranges from 0.005 to 0.500 inches; they serve primarily as lightweight, cost-efficient barriers for perishable goods and structural components. Polyethylene Terephthalate leads rigid food packaging due to clarity and recyclability alignment with EU Green Deal targets. Polystyrene occupies mature disposable foodservice applications where regulatory phase-outs are accelerating substitution. Clamshells and trays concentrate margin pools in medical and electronics protective formats where cleanliness protocols command premium positioning.
EPA guidelines on recycled content thresholds and FDA food-contact substance notifications shape resin selection and migration testing burdens for domestic suppliers. REACH and RoHS compliance in Europe restricts certain additives in consumer-facing thermoformed articles, redirecting formulation R&D toward bio-based and post-consumer feedstocks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or partner with specialized reclaimers.
Market Dynamics
The EU F-Gas Regulation and Green Deal recyclability mandates are forcing simultaneous reformulation of resin feedstocks and reconfiguration of sheet extrusion capacity across European thermoforming operations.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforcement of CO2 reduction targets drives thermoformed interior panel adoption near Stuttgart production clusters.
- Food-contact migration testing harmonization:FDA notification pathways streamline approval timelines for post-consumer recycled PET in retail packaging applications.
- Medical device cleanliness protocols:ISO 14644-1 cleanroom certification requirements expand addressable market for sterile barrier clamshells in surgical kit packaging.
Market Restraints
- Feedstock cost volatility:Virgin PET pricing tracks paraxylene and ethylene glycol spot markets, compressing converter margins during upstream petrochemical tightness.
- Polystyrene substitution pressure:EU single-use plastics directives accelerate phase-outs of expanded PS foodservice items before viable cost-parity alternatives achieve scale.
- Sheet extrusion capacity concentration:In-house PET sheet production at major dairy packagers limits independent converter access to resin supply.
Strategic Opportunities
- Bio-based feedstock integration:PLA and bio-PET formulations aligned with EU Green Deal carbon intensity targets open premium positioning in fresh-food retail channels.
- Direct-to-factory digital channels:B2B platform procurement of custom thermoformed dunnage displaces distributor-mediated sourcing in automotive tier-one supply chains.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz mandates drive converter investment in closed-loop collection infrastructure for rigid food containers.
Industry Challenges
- Thermoforming die design specialization:Shortage of mold engineers capable of multi-cavity aluminum tool optimization for thin-gauge high-speed lines constrains capacity expansion timelines.
- Migration testing backlog:FDA food-contact substance notification review queues extend commercialization timelines for novel barrier coating formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Plastics Market |
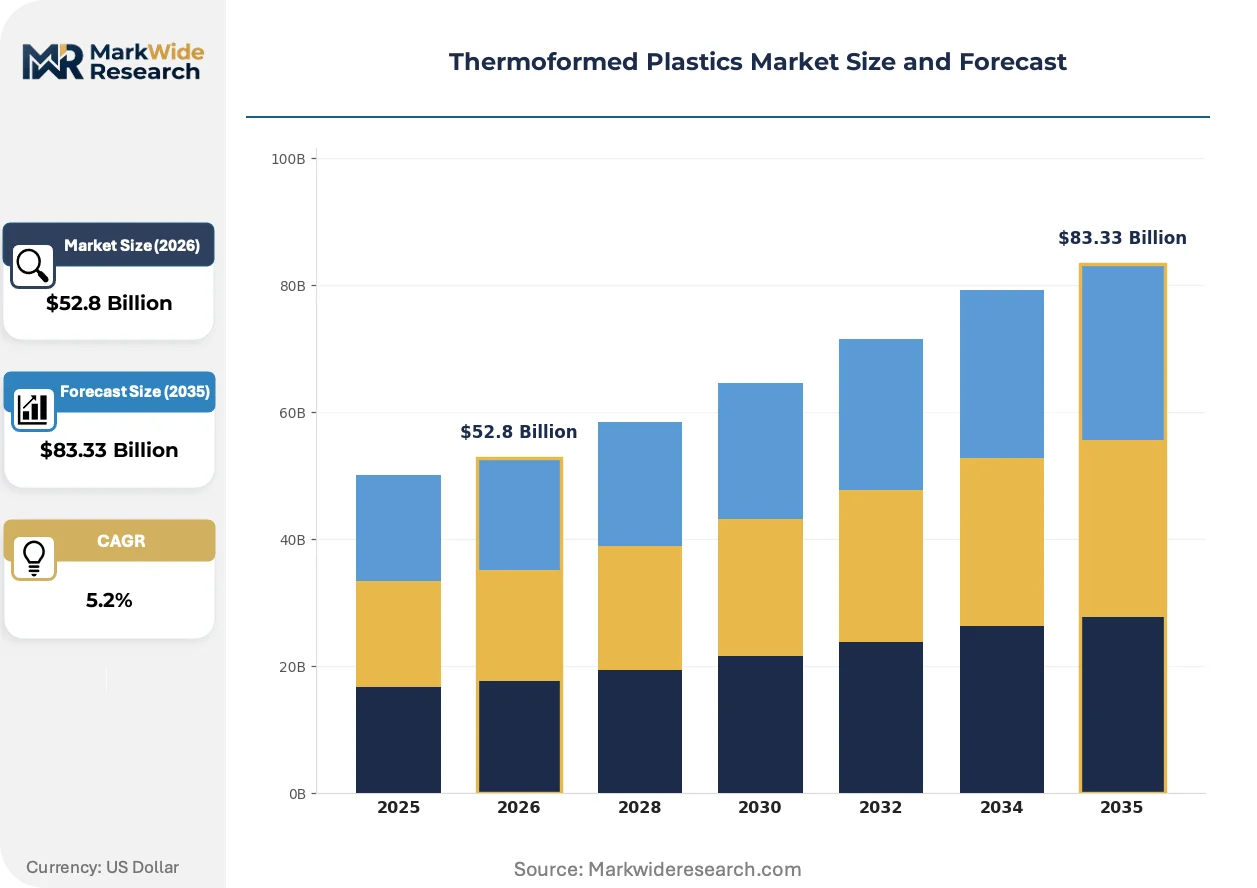
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $83.33 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Polystyrene, Polyethylene Terephthalate, Acrylonitrile Butadiene Styrene, Polycarbonate Form: Sheets, Films, Containers, Clamshells, Trays Application: Packaging, Automotive Components, Consumer Electronics, Agriculture Equipment, Construction Panels End User Industry: Food & Beverage, Electronics Manufacturing, Agricultural Equipment Suppliers, Building & Construction, Household Goods |
| Companies Covered | Pactiv LLC, Sonoco Products Company, Genpak LLC, Placon Corporation, Anchor Packaging LLC, Brentwood Industries, Greiner Packaging GmbH, CM Packaging, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Plastics Market Strategic Shifts & Innovations
Active barrier coatings and digital forming controls are compressing cycle times while enabling thinner-gauge specifications that reduce per-unit resin consumption.
Multi-layer coextrusion with oxygen-scavenging EVOH cores is collapsing the performance gap between thermoformed containers and glass or metal alternatives for shelf-stable protein packaging. Retail meat and prepared meal brands in Germany and France are specifying these structures for modified-atmosphere applications. The technology is collapsing traditional material hierarchies in refrigerated distribution chains.
REACH authorization requirements for phthalate plasticizers in food-contact applications are redirecting formulation R&D toward bio-based adipate and citrate alternatives. Compounders serving European dairy packaging converters face substance inventory deadlines that compress development cycles. Medical device and electronics protective formats bear the heaviest compliance documentation burdens.
Centralized procurement of thermoformed dunnage by automotive OEMs is consolidating supplier relationships and demanding real-time production data integration. Tier-one seating and interior component manufacturers near Munich and Wolfsburg now require EDI-linked inventory visibility. This concentration is most pronounced in German automotive supply chains.
Thermoformed Plastics Market Segmentation
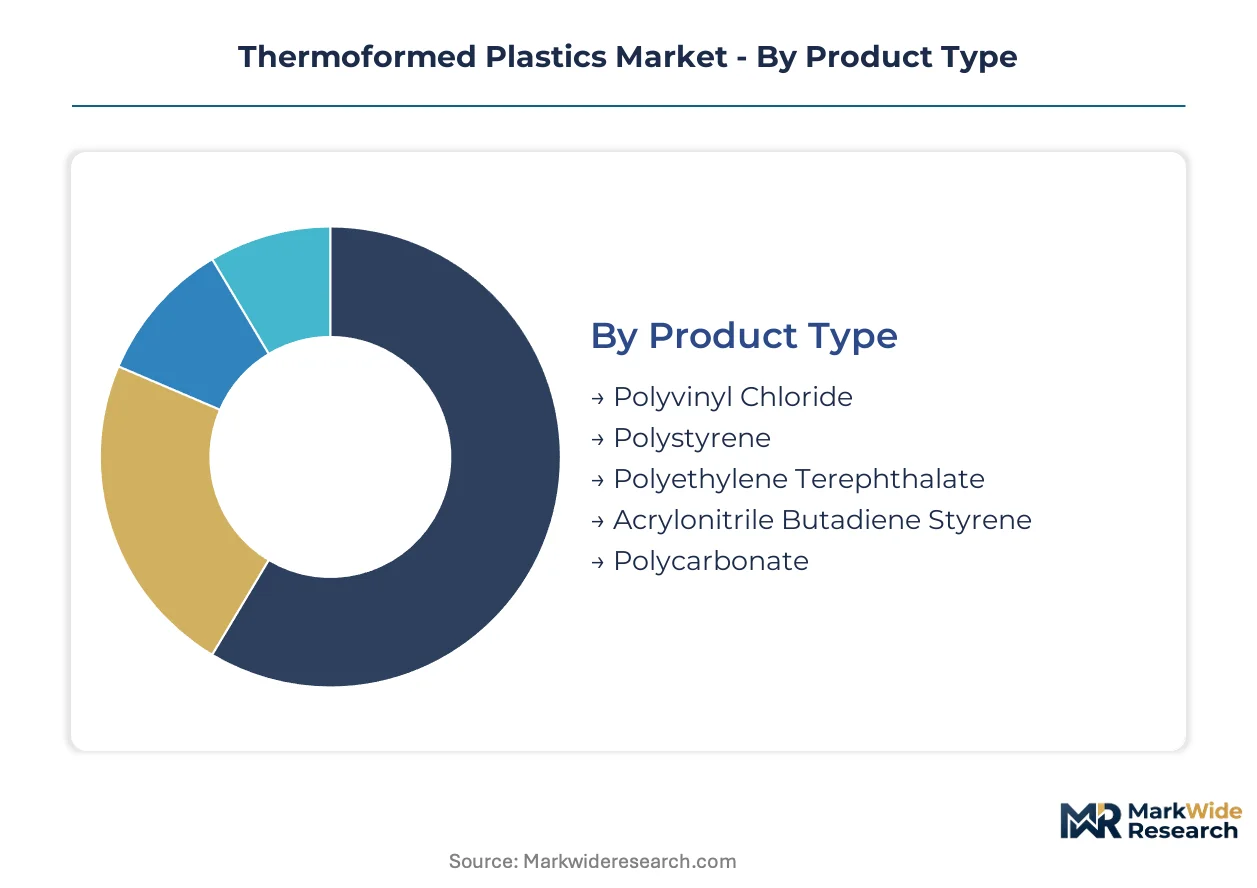
Thermoformed plastics demand fragments across material chemistries, physical formats, and end-use specifications that each carry distinct tooling investments and regulatory compliance burdens. Understanding these segment boundaries clarifies where margin pools concentrate and where capacity expansion faces technical barriers.
Product Type:
Use-case spectrum spans disposable foodservice items through engineering-grade automotive interior panels, with material selection dictated by clarity requirements, temperature resistance, and recyclability mandates.
- Polyethylene Terephthalate:Amorphous thermoplastic offering optical clarity and barrier properties suited to modified-atmosphere food packaging. Germany's dairy and fresh-protein packagers specify PET for its alignment with EU Green Deal recyclability targets and existing collection infrastructure.
- Polystyrene:Crystal and expanded grades dominate cost-sensitive disposable foodservice applications despite accelerating regulatory phase-outs. EU single-use plastics directives are compressing addressable volume for PS trays and hinged containers ahead of cost-parity bio-based alternatives.
- Polyvinyl Chloride:Rigid formulations serve medical blister packs and pharmaceutical trays where sterilization compatibility matters. REACH restrictions on phthalate plasticizers are redirecting formulation work toward bio-based adipate alternatives.
- Acrylonitrile Butadiene Styrene:Engineering-grade toughness supports automotive interior panels and consumer electronics housings. KBA enforcement of CO2 reduction targets drives ABS adoption for lightweight dashboard and door trim components near Stuttgart production clusters.
- Polycarbonate:High-impact transparency suits medical device housings and aircraft interior components where flame-retardant specifications apply. ECHA substance evaluation processes extend qualification timelines for food-contact polycarbonate applications.
The dominant share belongs to Polyethylene Terephthalate, while Acrylonitrile Butadiene Styrene is closing the gap fastest.
Form:
Physical format selection hinges on downstream automation compatibility, nesting efficiency in distribution, and the degree of product protection required through supply chain handling.
- Trays:Shallow-drawn formats with formed pockets for unitized product presentation. Foodservice and retail meat channels specify thermoformed trays for automated filling line compatibility and modified-atmosphere sealing.
- Clamshells:Hinged two-cavity designs providing 360-degree product visibility and tamper evidence. Electronics and medical device manufacturers specify clamshells for sterile barrier properties and retail theft deterrence.
- Sheets:Unformed extruded substrates supplied to captive thermoforming operations or independent converters. In-house sheet production at major dairy packagers limits independent converter access to resin supply.
- Films:Thin-gauge flexible formats for lidding and flow-wrap applications where conformability to irregular shapes matters. Barrier-coated PET films compete with aluminum laminates in pharmaceutical blister applications.
- Containers:Deep-drawn rigid formats with defined rim geometries for stacking and lidding. Fresh-protein and prepared meal brands in France and Germany specify multi-layer containers with oxygen-scavenging cores.
Trays command the largest volume position, though Clamshells are expanding most quickly in medical and electronics protective applications.
Application:
Functional requirements diverge sharply between barrier-driven packaging segments and structural load-bearing applications where dimensional stability under thermal cycling matters.
- Packaging:Primary and secondary containment for perishable and durable goods across retail and institutional channels. FDA food-contact substance notification pathways streamline approval timelines for post-consumer recycled PET in retail packaging.
- Automotive Components:Interior panels, trunk liners, and HVAC ducting where weight reduction supports CO2 compliance. German OEM procurement consolidation demands EDI-linked inventory visibility from tier-one seating suppliers near Munich and Wolfsburg.
- Consumer Electronics:Protective dunnage and retail display formats for smartphones, laptops, and accessories. Cleanliness protocols and anti-static specifications command premium positioning in semiconductor shipping trays.
- Agriculture Equipment:Cab interior panels and component housings for tractors and harvesters. Equipment manufacturers specify UV-stabilized formulations for prolonged outdoor exposure.
- Construction Panels:Temporary protection and permanent architectural applications where cost efficiency outweighs premium aesthetics. Building codes in multiple jurisdictions restrict combustible plastic panel use in high-occupancy structures.
Packaging absorbs the dominant share of thermoformed volume, while Automotive Components are gaining share fastest under lightweighting mandates.
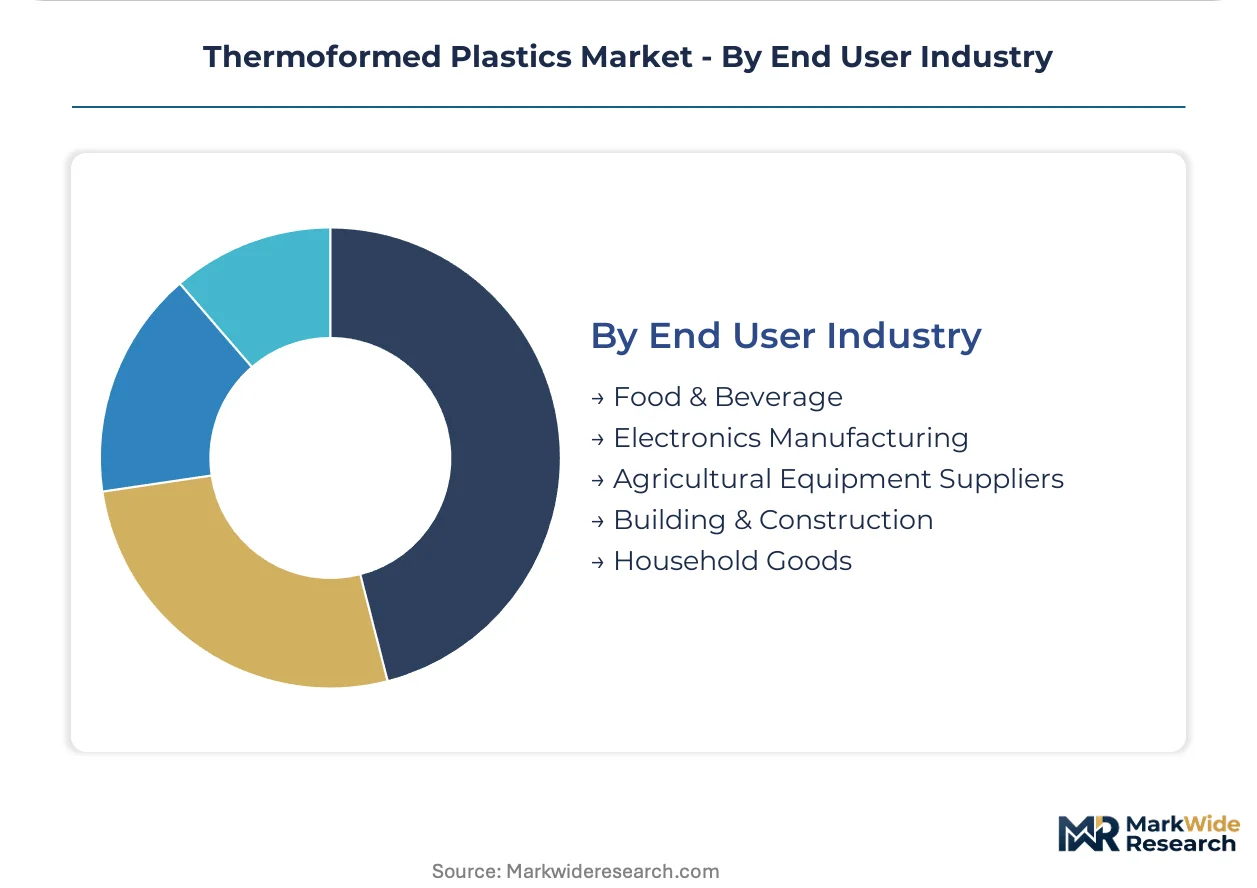
End User Industry:
Customer concentration patterns vary from fragmented retail channels through consolidated OEM procurement structures that reshape supplier relationship economics.
- Food & Beverage:Dairy, meat, prepared meals, and beverage packaging across retail and foodservice channels. Germany's Verpackungsgesetz mandates drive converter investment in closed-loop collection infrastructure for rigid food containers.
- Electronics Manufacturing:OEM and contract manufacturers requiring protective formats for component shipping and retail presentation. ISO 14644-1 cleanroom certification requirements expand addressable market for sterile barrier clamshells in surgical kit packaging.
- Building & Construction:Residential and commercial contractors specifying temporary surface protection and permanent architectural elements. Green building certification programs increasingly credit recycled content thresholds.
- Agricultural Equipment Suppliers:OEM and aftermarket channels for tractor and harvester component supply. Seasonal demand patterns create capacity utilization challenges for dedicated thermoforming lines.
- Household Goods:Retail channels for storage, organization, and disposable foodservice items. Private-label concentration in mass retail channels compresses margin structures for commodity formats.
Food & Beverage holds the established volume lead, though Electronics Manufacturing is climbing the fastest on medical device and semiconductor packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sheet extrusion capacity clusters heavily in Germany, where automotive and dairy packaging demand drives parallel expansion of captive and merchant supply. Converter operations in the United States and China follow distinct regulatory pathways for food-contact approval, while Mexico and India build thermoforming capacity to serve nearshored automotive and consumer goods manufacturing.
Germany
Automotive lightweighting mandates from the KBA accelerate thermoformed interior panel adoption across Baden-Württemberg production corridors. The EU F-Gas Regulation and Verpackungsgesetz recyclability requirements force simultaneous resin reformulation and closed-loop infrastructure investment. Stuttgart and Munich industrial zones host expanding sheet extrusion and forming lines as tier-one seating suppliers demand EDI-linked inventory visibility.
United States
FDA food-contact substance notification pathways streamline approval timelines for post-consumer recycled PET in retail packaging applications. EPA guidelines on recycled content thresholds shape resin selection and migration testing burdens for domestic suppliers. Integrated resin-to-package operations in the Midwest and Southeast anchor North American foodservice tray production.
China
Dual carbon goals and evolving GB standards for food-contact materials redirect formulation R&D toward bio-based feedstocks. NMPA notification requirements for novel barrier coatings extend commercialization timelines for modified-atmosphere packaging structures. Yangtze River Delta manufacturing clusters concentrate thin-gauge high-speed thermoforming capacity for electronics protective formats.
Mexico
Nearshoring of automotive component manufacturing drives demand for thermoformed dunnage and interior panels serving US OEM supply chains. SAMR-aligned import standards for food-contact plastics create compliance documentation requirements for cross-border packaging shipments. Nuevo León and Bajío Region industrial parks attract converter investment from multinational dairy and protein packagers.
India
FSSAI food-contact regulations and BIS standards for recycled content accelerate substitution of polystyrene foodservice items. PLI scheme incentives for packaging machinery support domestic thermoforming equipment manufacturing. Maharashtra and Gujarat industrial corridors build sheet extrusion capacity to serve fragmented retail and institutional food channels.
Thermoformed Plastics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with mold engineering and barrier coating capabilities. The vendor base separates into three strata: multinational converters with captive resin supply, regional specialists in dairy and medical packaging niches, and automotive-focused dunnage fabricators with OEM-direct relationships. Strategic moves concentrate on backward integration into sheet extrusion and geographic expansion through distributor acquisition.
Among North American integrated converters, Pactiv LLC and Sonoco Products Company exemplify the resin-to-package archetype with foodservice and protein packaging positioning. Greiner Packaging GmbH anchors the European dairy and fresh-food container segment through in-house PET sheet capacity. These three entities represent distinct geographic footprints and end-use specializations without overlapping core markets.
| Leading Market Players |
|---|
| Pactiv LLC |
| Sonoco Products Company |
| Genpak LLC |
| Placon Corporation |
| Anchor Packaging LLC |
| Brentwood Industries |
| Greiner Packaging GmbH |
| CM Packaging |
| Amcor plc |
| Others |
Cost & Logistics Intelligence
Feedstock cost volatility in virgin PET and paraxylene spot markets compresses converter margins unevenly across tiers, forcing a three-tier pricing structure across premium, standard, and economy levels while simultaneously driving geographic consolidation of sheet extrusion capacity near demand clusters.
Pricing Analysis
The EU F-Gas Regulation and Green Deal recyclability mandates dictate the pricing tier structure across European thermoforming operations. Pricing stratifies across premium, standard, and economy tiers based on post-consumer recycled content thresholds and FDA food-contact certification status. Cost compression in standard-grade foodservice formats is intensifying because polystyrene substitution pressure outpaces bio-based alternative scale-up. Institutional buyers in foodservice channels exhibit highest price sensitivity, while medical device manufacturers with ISO 14644-1 cleanliness requirements show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for electronics protective formats. Manufacturing gravity centers on Germany, the United States, and China, with resin supply drawing from paraxylene and ethylene glycol feedstocks anchored in Gulf Coast and Asian petrochemical complexes. Single-source vulnerability concentrates in specialized aluminum mold engineering for multi-cavity thin-gauge lines. Distribution runs through tier-one automotive OEM procurement portals and dairy packager captive operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cavity aluminum tool engineering for thin-gauge high-speed lines represents the critical chokepoint constraining capacity expansion timelines, with mold designer scarcity widening competitive moats for incumbents possessing in-house capabilities.
For Market Incumbents: Pre-empt polystyrene substitution pressure by accelerating bio-based PLA and bio-PET formulation scale-up ahead of EU single-use plastics directive deadlines. Backward integration into PET sheet extrusion secures resin supply against in-house dairy packager concentration while capturing margin pools in modified-atmosphere barrier structures. For New Entrants and Emerging Players: Indian foodservice tray markets present underpenetration relative to per capita consumption benchmarks, with FSSAI regulatory alignment creating lower barrier entry than EU or US pathways. Target Maharashtra and Gujarat industrial corridors with polystyrene-alternative formats leveraging PLI scheme machinery incentives. Direct-to-factory digital procurement platforms displace distributor-mediated sourcing in automotive dunnage. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with captive sheet supply and EDI-linked OEM relationships. Long-term viability hinges on closed-loop collection infrastructure ownership under extended producer responsibility frameworks. Monitor FDA food-contact substance notification queue lengths as inflection indicator for novel barrier coating commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet Extrusion | Captive PET supply insulates Greiner Packaging GmbH from resin allocation constraints in dairy channels. |
| Bio-Based Feedstock Scale-Up | PLA formulation investment aligns with EU Green Deal carbon intensity thresholds for fresh-food retail. |
| Digital Procurement Platform Launch | B2B dunnage sourcing displaces distributor margins in Stuttgart automotive tier-one supply chains. |
| Closed-Loop Collection Infrastructure | Germany's Verpackungsgesetz mandates drive converter investment in rigid food container reclaim systems. |
| Multi-Layer Coextrusion Capacity Addition | EVOH oxygen-scavenging cores collapse performance gaps with glass and metal for protein packaging. |
Research Approach
Desk research of trade association filings, customs records, and SEC 10-K disclosures preceded structured interviews with thermoforming plant managers, automotive tier-one procurement leads, dairy packaging technical directors, and FDA regulatory consultants. Bottom-up capacity modeling triangulated against top-down demand segmentation across material chemistry, physical format, and end-use specifications.
Assumptions held regulatory timelines and feedstock cost structures fixed while varying automotive lightweighting mandate enforcement intensity and bio-based resin cost-parity achievement rates. The analytical framework modeled volume and value across the projection horizon by material type, form factor, application segment, and regional production cluster. CAGRs derived from segment-level demand elasticity coefficients and capacity utilization trajectories, with specific inputs including KBA CO2 enforcement schedules and EU Green Deal recyclability threshold implementations.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, currency volatility, or trade policy would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Animal Feed Protein Ingredients Market
Others
Fresh Durian Market
Others
Global Electroshock Weapons Market
Others
Global Cryogenic Tanks Market
Others
Wearable Translator Market
Others
China 3D Printing Construction Market
Others
Canada Feed Additives Market
Others
Saudi Arabia Laser Hair Removal Market
Others
China Smart Home Market
Others
Mobile Computer Cart Market
Others
Smart Home Platforms Market
Others
Smart Home Gateways Market
Others
Europe Smart Homes Market
Others
US Camping and Caravanning Market
Others
Japan Smart Home Market
Others
Global Electronic Filters Market