
 Voice Controlled Devices Market | 2026-2036
Voice Controlled Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Controlled Devices Market Outlook
Platform licensing revenue is rewriting profit allocation across the voice controlled devices value chain. Amazon.com, Inc. leverages its Alexa developer ecosystem to capture recurring service income beyond hardware margins. Apple Inc. anchors its position through tight integration between Siri and its proprietary device portfolio. Samsung Electronics Co., Ltd. competes by extending Bixby across its appliance and mobile product lines.
Voice controlled devices are electronic systems that process spoken commands through embedded microphones, digital signal processors, and cloud-connected natural language processing engines, converting acoustic patterns into executable instructions with latency thresholds typically below 500 milliseconds. These systems serve commercial and industrial purposes ranging from hands-free home automation to enterprise workflow automation and patient care documentation. Smart speakers represent the most mature hardware category, while wearable devices demonstrate the fastest growth trajectory as miniaturization improves battery efficiency and on-device inference capability. Enterprise end users command premium pricing due to compliance requirements and custom vocabulary training, whereas consumer segments drive volume through standardized speech recognition platforms.
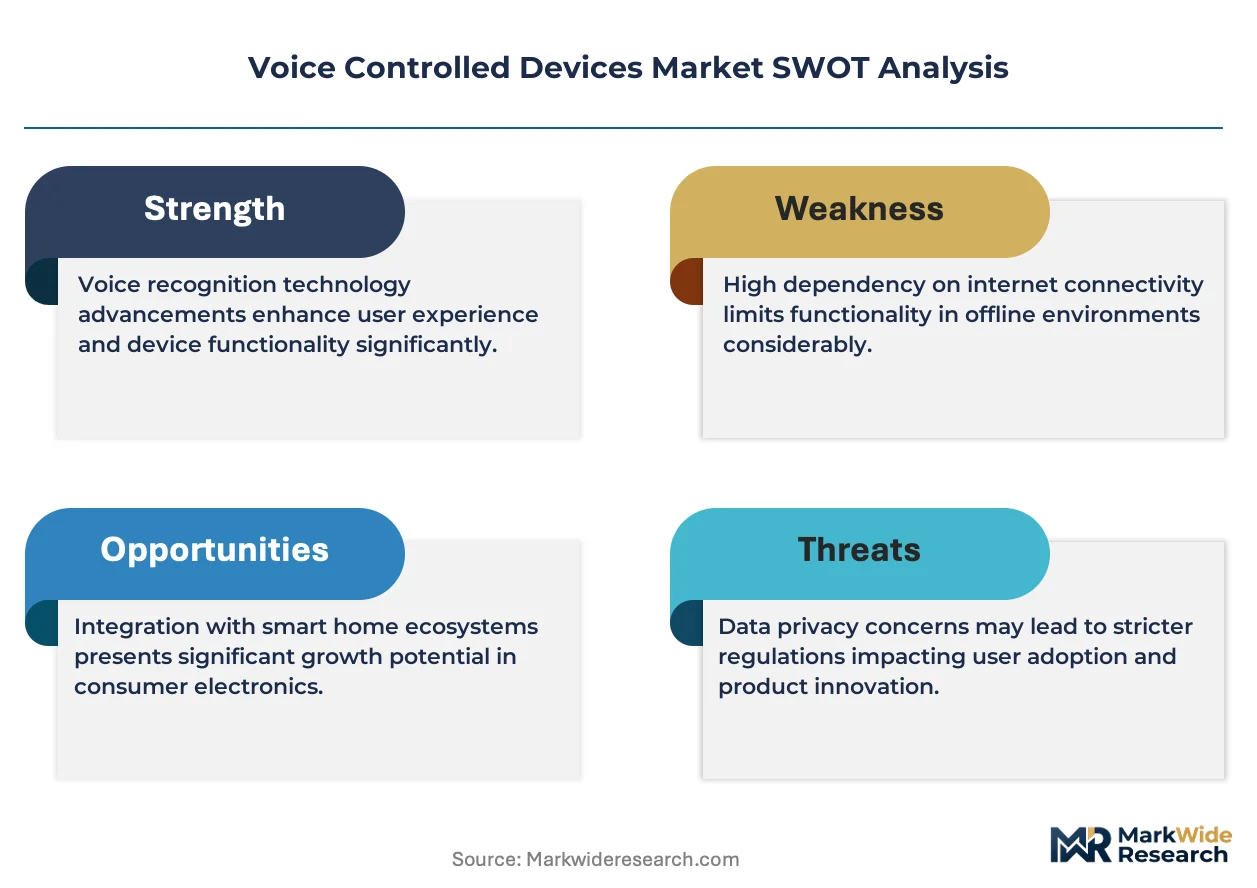
The Federal Communications Commission governs radio frequency emissions from wireless voice devices in the United States, while the EU AI Act imposes risk-classification requirements on conversational AI systems marketed in Europe. The National Institute of Standards and Technology publishes biometric performance standards that shape procurement criteria for government and healthcare voice authentication deployments. Stakeholders must monitor evolving interoperability mandates and on-device privacy architectures as regulatory fragmentation between jurisdictions intensifies compliance complexity.
Market Dynamics
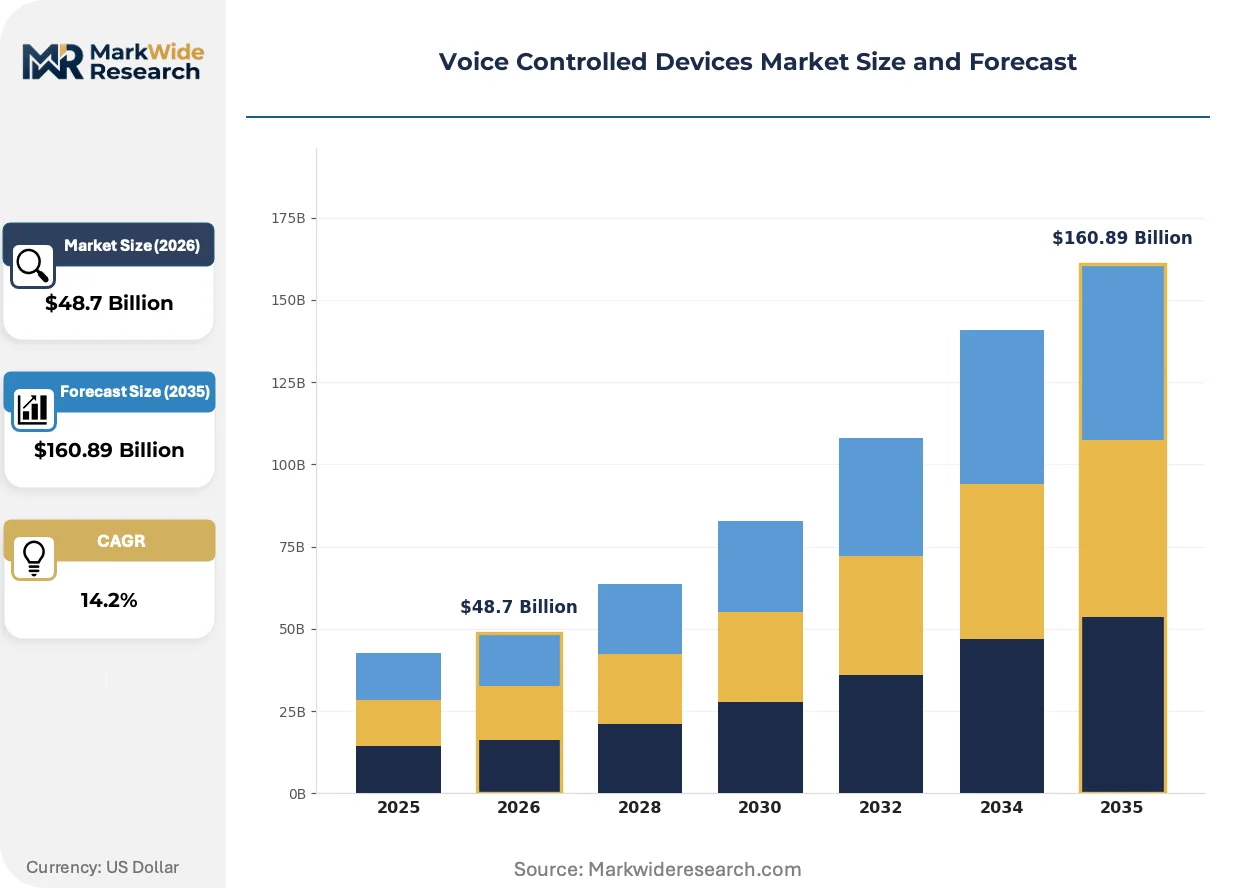
Platform licensing revenue is restructuring profit allocation across the voice controlled devices value chain, as hardware margins compress and recurring service income becomes the dominant value capture mechanism.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for conversational AI systems are accelerating enterprise procurement of certified voice platforms in healthcare and financial services.
- Smart home hub integration:Residential IoT ecosystem convergence is pulling voice interfaces into thermostat, lighting, and security control systems.
- On-device inference capability:Edge AI chip miniaturization is reducing latency below 200 milliseconds for wearable voice devices.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control over 70 percent of NLP backend capacity, creating single-point-of-failure risk for device manufacturers.
- Microphone array cost volatility:MEMS sensor supply depends on Taiwanese foundry capacity subject to geopolitical disruption.
- GDPR voice data retention limits:European storage restrictions complicate model training and personalization service delivery.
Strategic Opportunities
- Industrial workflow automation:Voice-directed picking and assembly instructions in warehousing and manufacturing remain underpenetrated relative to consumer saturation.
- US IRA healthcare digitization incentives:Medicare reimbursement for clinical documentation automation is expanding hospital voice technology budgets.
- Automotive cabin integration:Multizone voice recognition for driver-passenger differentiation represents a greenfield application with premium pricing tolerance.
Industry Challenges
- Acoustic model training specialist scarcity:Phonetic linguists with domain expertise in low-resource languages command compensation premiums that inflate R&D budgets.
- Legacy enterprise system API fragmentation:Voice platform vendors face integration complexity with decades-old ERP and clinical record architectures.
- FCC equipment authorization timelines:Radio frequency certification delays for new wireless voice hardware average 14 weeks, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Controlled Devices Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Voice Assistants, Wearable Devices, Smart Home Hubs Technology: NLP, Machine Learning, IoT Connectivity, Speech Recognition End User: Consumers, Enterprises, Healthcare Providers, Educational Institutions Application: Home Automation, Voice Search, Smart Appliances, Customer Service |
| Companies Covered | Amazon.com, Inc., Apple Inc., Alphabet Inc., Microsoft Corporation, Google LLC, IBM Corporation, Baidu, Inc., Samsung Electronics Co., Ltd., iFLYTEK Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Controlled Devices Market Strategic Shifts
Edge AI inference is redistributing computational load from cloud data centers to device-local silicon, altering power architecture, privacy architecture, and platform economics simultaneously.
Neural processing units with dedicated tensor cores are rendering obsolete the cloud-dependent voice pipelines that previously required persistent connectivity. Automotive OEMs and medical device manufacturers are adopting these chips fastest, driven by functional safety and HIPAA compliance requirements. This shift is compressing recurring cloud service revenue models while expanding upfront hardware bill-of-materials costs.
The EU AI Act's risk-tier classification system is forcing conversational AI vendors to restructure product documentation and quality management systems. High-risk applications in healthcare and transportation now require conformity assessment by notified bodies before market placement. German automotive suppliers and French healthcare technology firms are investing most heavily in compliance infrastructure to maintain European market access.
Enterprise buyers are unbundling voice platform procurement from hardware acquisition, separating software licensing from device supply contracts. Healthcare systems and warehouse operators are driving this shift, demanding API-accessible voice services compatible with multi-vendor device fleets. This pattern is most pronounced in the United States, where large hospital networks and third-party logistics providers possess procurement scale to enforce vendor-agnostic standards.
Voice Controlled Devices Market Segmentation
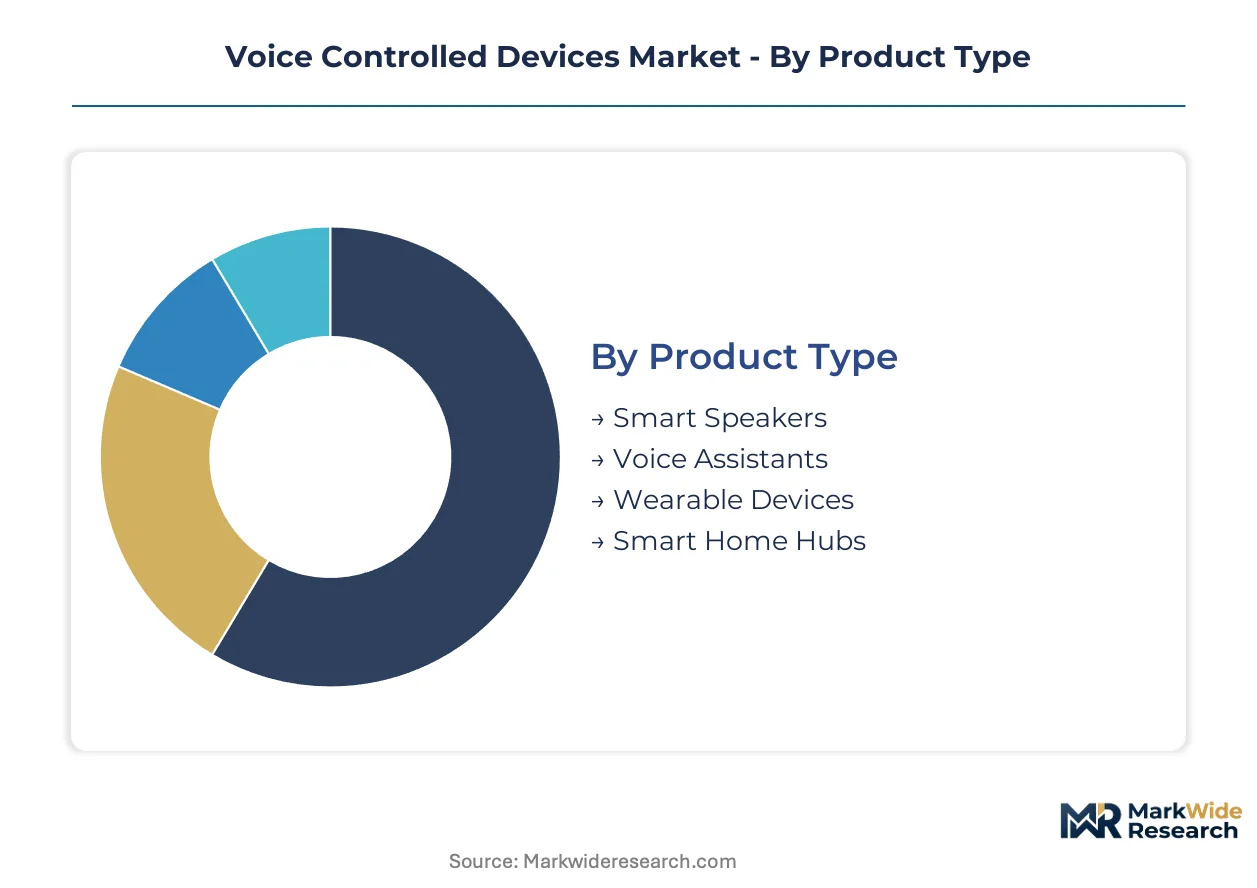
Voice controlled devices fragment across hardware form factors, underlying AI technologies, buyer sophistication, and deployment contexts. Each segmentation axis reveals distinct margin profiles, regulatory exposure, and competitive intensity that reshape vendor strategy.
Product Type:
Mature hardware categories coexist with emerging form factors at vastly different points in the technology adoption curve.
- Smart Speakers:Cylindrical or spherical enclosures housing microphone arrays, full-range drivers, and Wi-Fi connectivity modules. Household penetration in the United States concentrates among Amazon Echo and Google Nest ecosystems, though saturation is compressing replacement cycles and average selling prices.
- Wearable Devices:Earbuds, smartwatches, and fitness bands embedding ultra-low-power voice processors with wake-word detection. Battery efficiency gains and on-device inference capability are pulling demand toward hearables in fitness and enterprise hands-free workflows.
- Voice Assistants:Software-only platforms deployed through mobile applications, automotive infotainment systems, and third-party hardware integrations.
- Smart Home Hubs:Centralized controllers bridging Zigbee, Z-Wave, Matter, and Wi-Fi protocols with integrated voice interfaces for lighting, climate, and security orchestration.
Smart speakers retain volume leadership; wearable devices hold the steepest expansion curve.
Technology:
Cost tier separation distinguishes commoditized connectivity layers from premium AI processing stacks.
- Natural Language Processing:Transformer-based models parsing semantic intent, entity extraction, and dialogue state management. Healthcare documentation and financial services compliance in the United States are concentrating procurement around HIPAA-ready NLP pipelines with audit logging.
- Machine Learning:Edge training frameworks enabling personalized acoustic models without cloud data transmission. On-device personalization is gaining traction in European deployments constrained by GDPR voice data retention limits.
- IoT Connectivity:Protocol stacks for device discovery, pairing, and command routing across heterogeneous smart home ecosystems.
- Speech Recognition:Acoustic modeling converting phoneme sequences to text with speaker diarization and noise suppression for far-field capture.
NLP commands premium licensing economics; machine learning is climbing the fastest as edge silicon penetration deepens.
End User:
Customer type determines procurement sophistication, contract structure, and support intensity.
- Consumers:Individual purchasers acquiring devices through retail channels with minimal integration requirements and high price elasticity.
- Enterprises:Warehouse operators, hospitality chains, and corporate facilities deploying voice-directed workflows with centralized fleet management and custom vocabulary training.
- Healthcare Providers:Hospitals and clinics purchasing FDA-registered voice documentation systems with clinical decision support integration and malpractice liability coverage. Medicare reimbursement for clinical documentation automation in the United States is expanding procurement budgets.
- Educational Institutions:K-12 districts and universities deploying accessibility tools and language learning applications with COPPA and FERPA compliance mandates.
Consumers dominate unit shipments; healthcare providers deliver the highest revenue per seat.
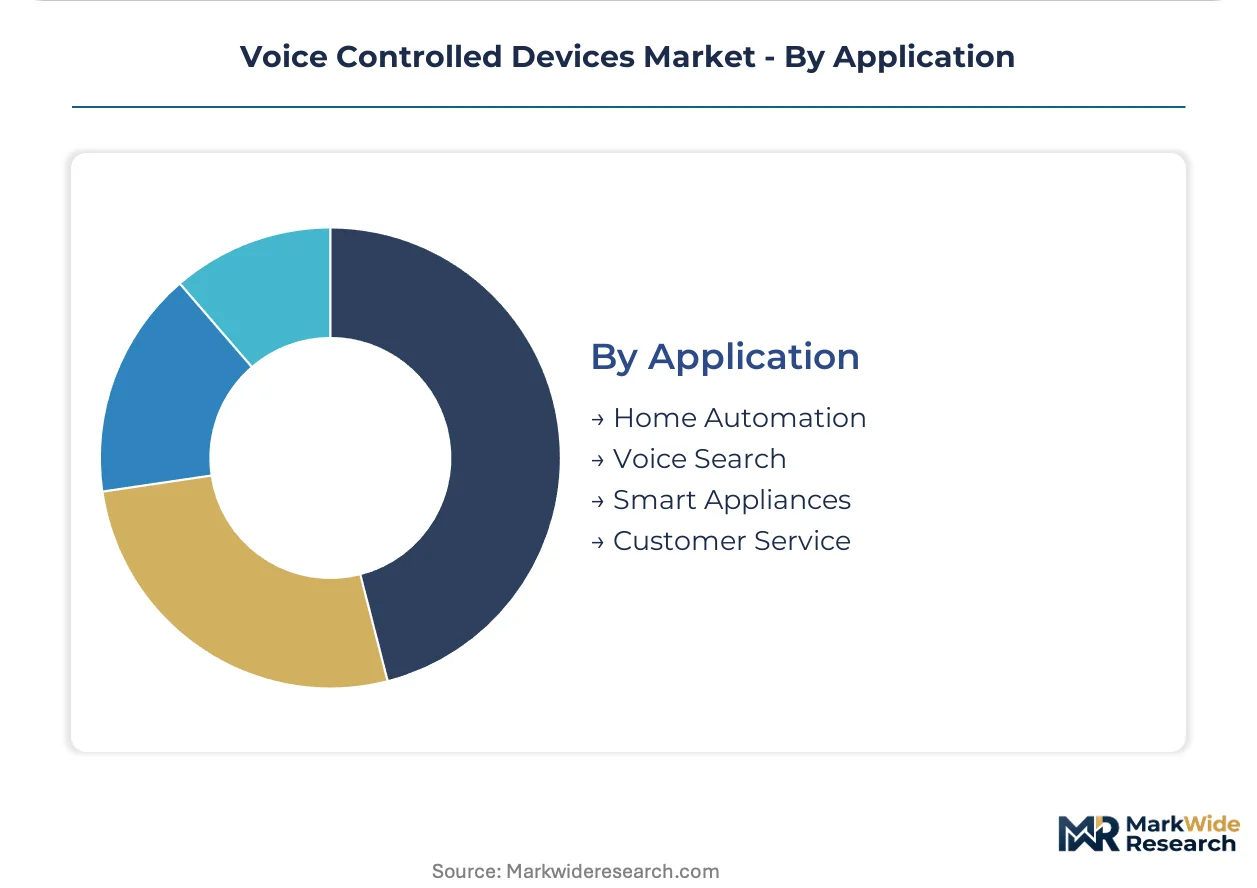
Application:
Application context shapes latency requirements, safety criticality, and integration architecture.
- Home Automation:Voice-activated control of lighting, thermostats, locks, and entertainment systems through unified smart home platforms.
- Voice Search:Hands-free information retrieval and transaction initiation displacing typed queries in mobile and automotive contexts.
- Smart Appliances:Refrigerators, ovens, washing machines, and HVAC units embedding voice interfaces for cycle control and maintenance alerts.
- Customer Service:Interactive voice response systems and agent assist tools automating routing, authentication, and post-call summarization in contact centers.
Home automation anchors installed base; customer service is gaining share fastest as conversational AI matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Consumer segments in India and Southeast Asia resist premium hardware pricing, while healthcare procurement in Germany and the United States absorbs substantial per-seat licensing costs for HIPAA-ready and MDR-certified voice documentation systems.
United States
Hospital networks and third-party logistics providers drive enterprise voice platform procurement with substantial fleet-scale purchasing power. Medicare reimbursement for clinical documentation automation under the IRA expands hospital technology budgets beyond hardware into recurring software licensing. Seattle and San Francisco Bay Area clusters concentrate NLP engineering talent and cloud infrastructure investment.
Germany
Automotive OEMs and industrial equipment manufacturers demand voice interfaces with ISO 26262 functional safety certification for cabin and factory-floor deployment. The EU AI Act's high-risk system classification forces German suppliers to restructure quality management systems for conversational AI conformity assessment. Stuttgart and Munich engineering centers lead investment in edge AI silicon for automotive voice recognition.
China
Smart home ecosystem integration accelerates through MIIT-backed Matter protocol adoption, pulling voice interfaces into appliance and HVAC control systems. GB standards for voice data security and cross-border transmission shape domestic platform architecture and limit foreign cloud dependency. Shenzhen hardware manufacturing clusters and Beijing AI research centers concentrate B2C device production and NLP model development.
Japan
Aging demographics and labor shortage pressures push healthcare and hospitality sectors toward voice-directed workflow automation with premium support service requirements. METI guidelines for AI utilization in medical devices shape procurement criteria for clinical voice documentation systems. Tokyo-Osaka corridor concentration of precision electronics manufacturers supplies MEMS microphone arrays and ultra-low-power voice processors.
United Kingdom
Financial services compliance mandates and contact center modernization drive enterprise voice platform adoption with strict audit logging requirements. GDPR voice data retention limits complicate model training for personalization services, favoring on-device inference architectures. London fintech and insurance clusters represent concentrated demand for secure voice authentication and conversational AI customer service tools.
Voice Controlled Devices Market Competitive Environment
Capability concentration sits with hyperscale cloud platforms possessing proprietary NLP training infrastructure; scale advantage sits with consumer electronics conglomerates commanding global distribution and captive silicon supply. The market structures around three tiers: cloud-native voice service platforms, integrated hardware-software ecosystems, and specialized enterprise solution vendors. Dominant competitive moves include strategic API licensing partnerships with automotive and healthcare OEMs, and vertical integration into edge AI semiconductor design to reduce cloud dependency and latency.
Within the hyperscale platform tier, Amazon.com, Inc. and Alphabet Inc. exemplify the cloud-native archetype through developer ecosystem cultivation and recurring service revenue models. Apple Inc. anchors the integrated ecosystem position through proprietary silicon and tight hardware-software coupling. Samsung Electronics Co., Ltd. occupies the diversified electronics conglomerate position with cross-category voice interface deployment spanning mobile, appliance, and automotive product lines.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Alphabet Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Baidu, Inc. |
| Samsung Electronics Co., Ltd. |
| iFLYTEK Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Taiwanese MEMS foundry concentration creates simultaneous vulnerability in microphone array supply and pricing power compression for device manufacturers. This single-source dependency for acoustic sensors widens spreads between premium certified tiers and economy unbranded alternatives while forcing vendors toward multi-sourcing strategies.
Pricing Analysis
Platform licensing revenue drives lifetime value beyond hardware margins. Three-tier pricing structure across premium HIPAA-certified, standard enterprise, and economy consumer levels separates healthcare procurement from retail channels. Cost compression in consumer smart speakers intensifies as Amazon and Google subsidize hardware to capture recurring service income. Enterprise buyers show lowest price sensitivity due to compliance requirements and custom vocabulary training needs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for voice controlled device assembly. Taiwan, South Korea, and China concentrate MEMS microphone and neural processing unit fabrication. Bill-of-materials draws from silicon wafers, rare earth magnets for speaker drivers, and lithium-ion cells for portable devices. Distribution runs through direct-to-consumer e-commerce, enterprise VAR channels, and automotive OEM tier-1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice controlled devices sit in early-cycle expansion as Medicare reimbursement for clinical documentation automation unlocks hospital procurement budgets previously constrained by capital expenditure limits.
For Market Incumbents: Entrench platform dominance by deepening API integration with automotive and healthcare OEMs before regulatory certification requirements harden. Amazon and Google must defend against edge AI chip vendors eroding cloud dependency by accelerating proprietary silicon roadmaps. HIPAA-ready NLP pipeline investment preserves healthcare pricing premiums. For New Entrants and Emerging Players: Establish a beachhead in industrial workflow automation where voice-directed picking and assembly instructions remain underpenetrated relative to consumer saturation. Warehouse operators and manufacturing facilities lack vendor-agnostic voice platforms, creating procurement leverage for specialized entrants. Target FDA-registered clinical documentation systems as Medicare reimbursement expands addressable budgets. For Investors and Strategic Acquirers: EU AI Act high-risk system classification reshapes the acquisition landscape toward compliance-ready voice platform vendors with notified body relationships. Five-to-ten year viability favors edge AI semiconductor designers reducing cloud latency for automotive and medical applications. Watch FDA 510(k) clearance velocity for clinical voice documentation as inflection signal for healthcare segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Development | Neural processing units with tensor cores reduce cloud dependency for HIPAA-compliant medical devices. |
| Healthcare API Integration | FDA-registered voice documentation systems capture Medicare reimbursement expansion under IRA incentives. |
| EU AI Act Certification | Notified body conformity assessment unlocks high-risk healthcare and transportation market access. |
| Automotive Multizone Recognition | Driver-passenger differentiation commands premium pricing in cabin voice interface procurement. |
| Industrial Workflow Deployment | Voice-directed picking systems penetrate warehousing automation faster than saturated consumer segments. |
Study Parameters
A standing panel of NLP engineering directors, healthcare CIOs, automotive platform architects, and smart home ecosystem product managers provided ongoing calibration across the analysis window. Primary interviews with FDA regulatory consultants and EU notified body assessors combined with secondary validation from FCC equipment authorization databases, SEC hyperscaler capex disclosures, and hospital GPO contract repositories. Bottom-up device shipment modeling and top-down platform revenue triangulation anchored segmentation outputs.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated edge AI adoption paths. Segmentation dimensions spanned hardware form factor, NLP deployment architecture, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical smart speaker penetration patterns and healthcare digitization incentive trajectories. Medicare reimbursement elasticity and automotive safety certification timelines served as industry-specific forecast inputs throughout the modeling period.
Stress conditions across MEMS supply disruption, EU AI Act enforcement intensity, and cloud infrastructure concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding voice data privacy regulation evolution and edge silicon cost reduction trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Edible Insects for Animal Feed Market
Others
Coalescing Filter Market
Others
Aircraft Exterior Lighting Market
Others
Global Cosmetovigilance Market
Others
Middle East and Africa Surface Analysis Market
Others
Healthcare Bioconvergence Market
Others
Synthetic Leather Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Digital Signage Media Player Market
Others
Italy 3D Printing Construction Market
Others
Surgical Simulation Market
Others
Smart Home Service Market
Others
Eye Balm Market
Others
Video-As-A-Service (Vaas) Market
Others
Education and Learning Analytics Market
Others
North America Printed Signage Market