
 Badminton Apparel Market | 2026-2036
Badminton Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Badminton Apparel Market Analysis
Badminton-specific textile engineering talent is rotating toward Southeast Asian manufacturing hubs, tightening design capacity in traditional Japanese and Korean centers. Yonex Co., Ltd. leverages vertical integration across yarn-to-garment operations in domestic facilities. Li-Ning Company Limited anchors its competitive stance through deep distribution control across China's provincial sports bureaus. Victor Rackets Industrial Corp. specializes in thermoregulation technology for tropical tournament circuits.
Badminton apparel denotes performance-oriented garments engineered for rapid directional changes, overhead arm extension, and sustained anaerobic exertion in indoor court environments. Polyester-dominant knit constructions with elastane content between 8% and 15% deliver the tensile recovery and moisture vapor transmission rates required for rally-intensive play. Shirts command the largest revenue pool within product type segmentation, though skirts and compression socks post higher unit margins in professional channels. Material segmentation shows polyester displacing cotton across all end-user tiers except recreational entry-level buyers. End-user segmentation reveals coaches and trainers as an overlooked procurement node, with bulk orders tied to national federation supply contracts.
ISO 20740 sportswear durability standards and China's GB 18401 national textile safety framework govern fiber content labeling and azo dye restrictions across major production bases. Japan's METI enforces energy efficiency benchmarks for textile dyeing operations that raise compliance costs for synthetic fabric processors. Stakeholders must track how emerging chemical disclosure requirements in multiple Asian markets reshape material sourcing decisions and supplier qualification timelines.
Market Dynamics
Polyester-dominant knit constructions with 8-15% elastane content are systematically replacing cotton blends across competitive and club-tier segments, driven by moisture vapor transmission requirements for rally-intensive play and tightening athletic wear safety standards in major Asian production bases.
Growth Catalysts
- GB 18401 compliance mandates:China's national textile safety framework pushes brands toward certified synthetic materials, accelerating polyester adoption in domestic supply chains.
- Junior academy enrollment surges:Indonesia's club-level training segment drives compressed replacement cycles for performance shirts and shorts.
- ISO 20740 durability standards:International sportswear certification requirements elevate fiber content labeling rigor, favoring engineered knits over commodity fabrics.
Market Restraints
- Petrochemical input volatility:Polyester feedstock costs fluctuate with crude oil derivatives, squeezing margin structures for mid-tier manufacturers.
- Design capacity concentration:Textile engineering talent rotation toward Southeast Asian manufacturing hubs tightens technical development resources in traditional Japanese and Korean centers.
- Energy efficiency compliance:Japan's METI dyeing operation benchmarks raise synthetic fabric processor costs, compressing regional competitiveness.
Strategic Opportunities
- Thermoregulation technology convergence:Integration of phase-change materials with moisture-wicking knits opens premium positioning for tropical tournament circuits.
- Coach and trainer procurement nodes:Bulk orders tied to national federation supply contracts represent an overlooked B2B channel with volume concentration.
- Compression sock category expansion:Higher unit margins in professional channels support vertical brand extension beyond core shirt and short offerings.
Industry Challenges
- Azo dye restriction timelines:Chemical disclosure requirements across multiple Asian markets reshape supplier qualification processes, extending go-to-market lead times.
- Specialized pattern-making expertise gaps:Rapid directional change and overhead arm extension biomechanics demand sport-specific garment engineering talent that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Badminton Apparel Market |
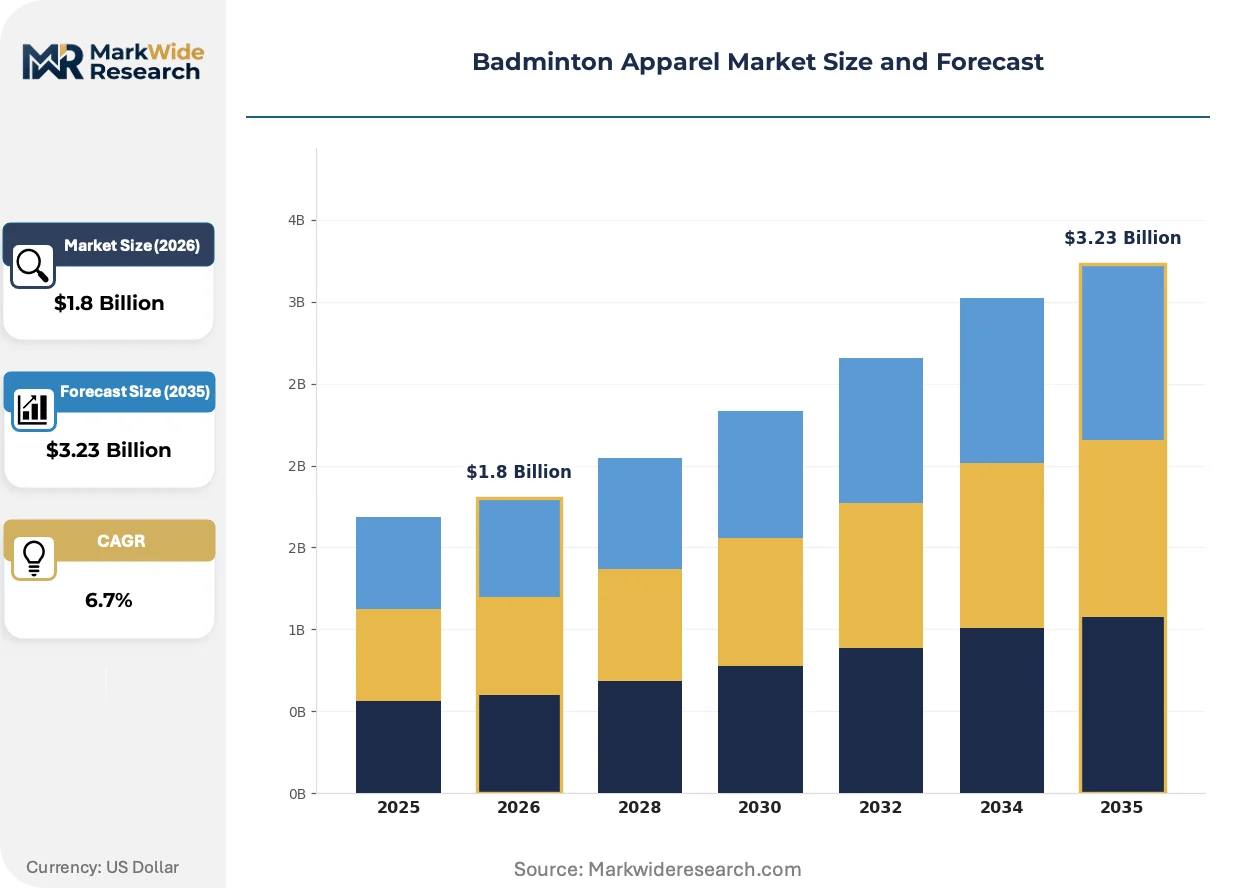
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Shorts, Skirts, Socks Material: Polyester, Nylon, Cotton, Spandex End User: Professional Players, Recreational Players, Trainers, Coaches Distribution Channel: Retail Stores, Online Marketplaces, Specialty Stores, Sports Outlets |
| Companies Covered | Yonex Co., Ltd., Li-Ning Company Limited, Victor Rackets Industrial Corp., ASICS Corporation, adidas AG, Nike, Inc., PUMA SE, Under Armour, Inc., Apacs Sports (M) Sdn Bhd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Badminton Apparel Market Emerging Trajectories
Material science advances and regulatory tightening are converging to reshape how performance badminton apparel is engineered, certified, and procured across competitive tiers.
Seamless knitting technology with integrated ventilation zones is displacing traditional cut-and-sew construction in high-performance tournament wear. National team suppliers and elite club programs are adopting these constructions at accelerating pace to reduce chafe points during extended rally sequences. This shift is displacing conventional panel-based assembly methods and compressing supplier bases toward technical knit specialists with capital-intensive machinery.
China's GB standards evolution and emerging chemical disclosure frameworks across Southeast Asian markets are tightening fiber content verification requirements. The industrial consequence is forced supplier consolidation as smaller mills lack testing infrastructure for azo dye and heavy metal compliance. Junior academy and recreational entry-level segments face the steepest cost pass-through pressures as they lack scale to absorb certification overhead.
Bulk procurement tied to national federation supply contracts is consolidating purchasing power among coaches and trainers. Traditional retail and direct-to-consumer channels face margin compression as institutional buyers negotiate multi-year performance agreements with volume guarantees. This pattern concentrates most visibly in China's provincial sports bureau distribution networks and Indonesia's national badminton association equipment programs.
Badminton Apparel Market Segmentation
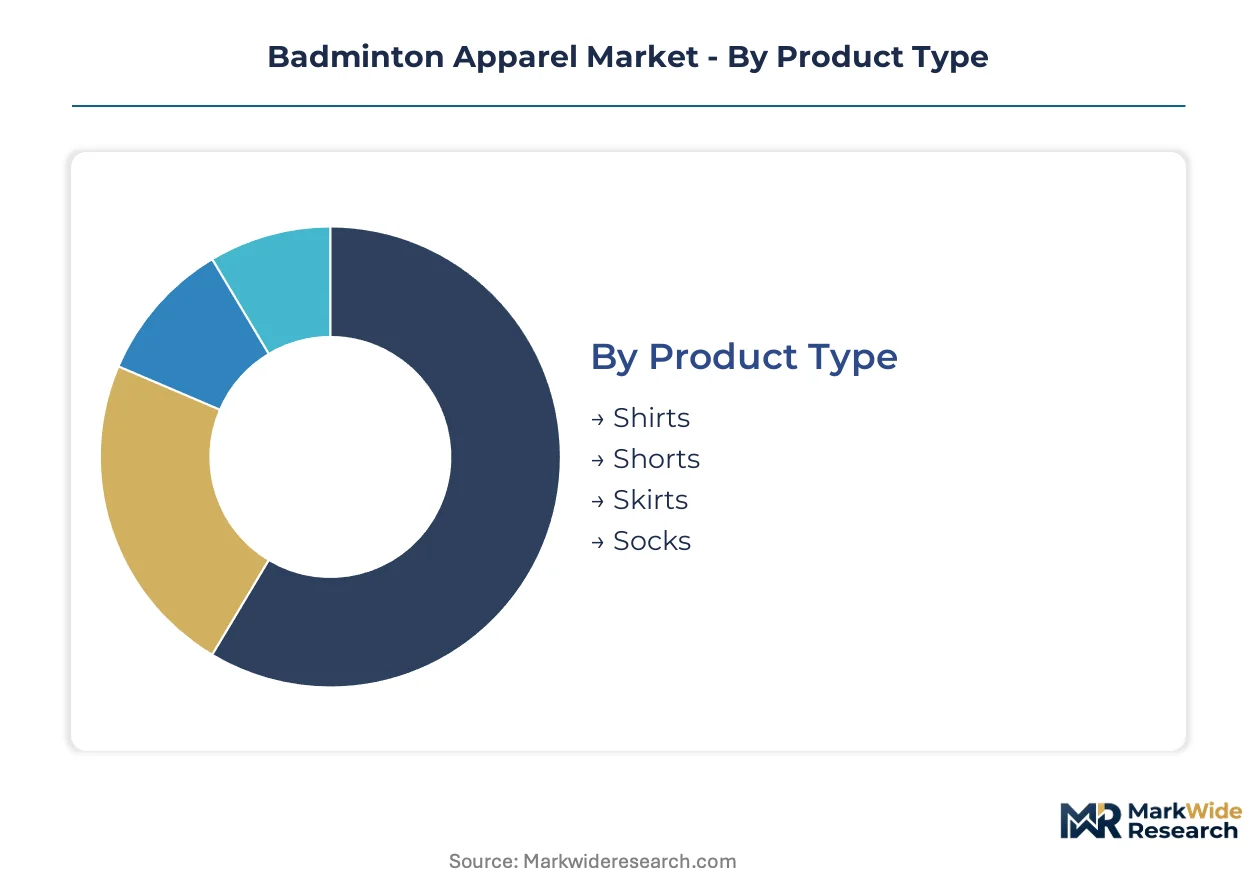
Badminton apparel segmentation reveals how performance requirements, procurement patterns, and material science intersect across player tiers. Understanding where margin pools concentrate helps stakeholders prioritize design investment and channel strategy.
Product Type:
Margin pools concentrate in garments with the highest technical specification requirements and replacement frequency.
- Shirts:Polyester-dominant knit constructions with 8-15% elastane content deliver tensile recovery for overhead arm extension. Demand clusters in Indonesia's junior academy segment, where compressed replacement cycles coincide with seasonal enrollment surges. GB 18401 compliance mandates elevate certified synthetic adoption, squeezing cotton-blend alternatives.
- Shorts:Rapid directional change biomechanics demand gusseted crotch construction and moisture vapor transmission rates above standard athletic benchmarks. China's provincial sports bureaus drive bulk procurement through national federation supply contracts, concentrating volume in institutional channels.
- Skirts:Higher unit margins in professional channels support premium positioning for tropical tournament circuits.
- Socks:Compression variants post elevated margins through specialized knitting machinery requirements.
The dominant share belongs to Shirts, while Socks is closing the gap fastest on margin contribution per unit.
Material:
Cost tier stratification separates certified performance synthetics from commodity alternatives.
- Polyester:Moisture-wicking knit constructions with engineered filament cross-sections dominate competitive and club-tier segments. China's national sports regulator tightened athletic wear safety standards, accelerating displacement of cotton blends across domestic supply chains.
- Nylon:Superior abrasion resistance positions this material in high-friction zones of elite tournament wear.
- Cotton:Recreational entry-level buyers sustain residual demand despite vapor transmission limitations.
- Spandex:Elastane content between 8% and 15% enables rally-intensive play recovery characteristics.
Polyester commands institutional procurement volumes, while Nylon gains share fastest in premium tournament-grade applications.
End User:
Customer type determines whether procurement flows through retail, institutional, or direct channels.
- Professional Players:Thermoregulation technology integration opens premium positioning for tropical circuits. Asia-Pacific demand accelerates as polyester-based moisture-wicking fabrics replace cotton blends in national team supplier relationships.
- Trainers:Bulk orders tied to national federation supply contracts represent an overlooked B2B channel with volume concentration.
- Coaches:Procurement nodes consolidate purchasing power through multi-year performance agreements with volume guarantees.
- Recreational Players:Price-sensitive segment faces steepest certification cost pass-through pressures.
Professional Players anchor premium revenue pools, though Trainers is expanding most quickly through institutional contract consolidation.
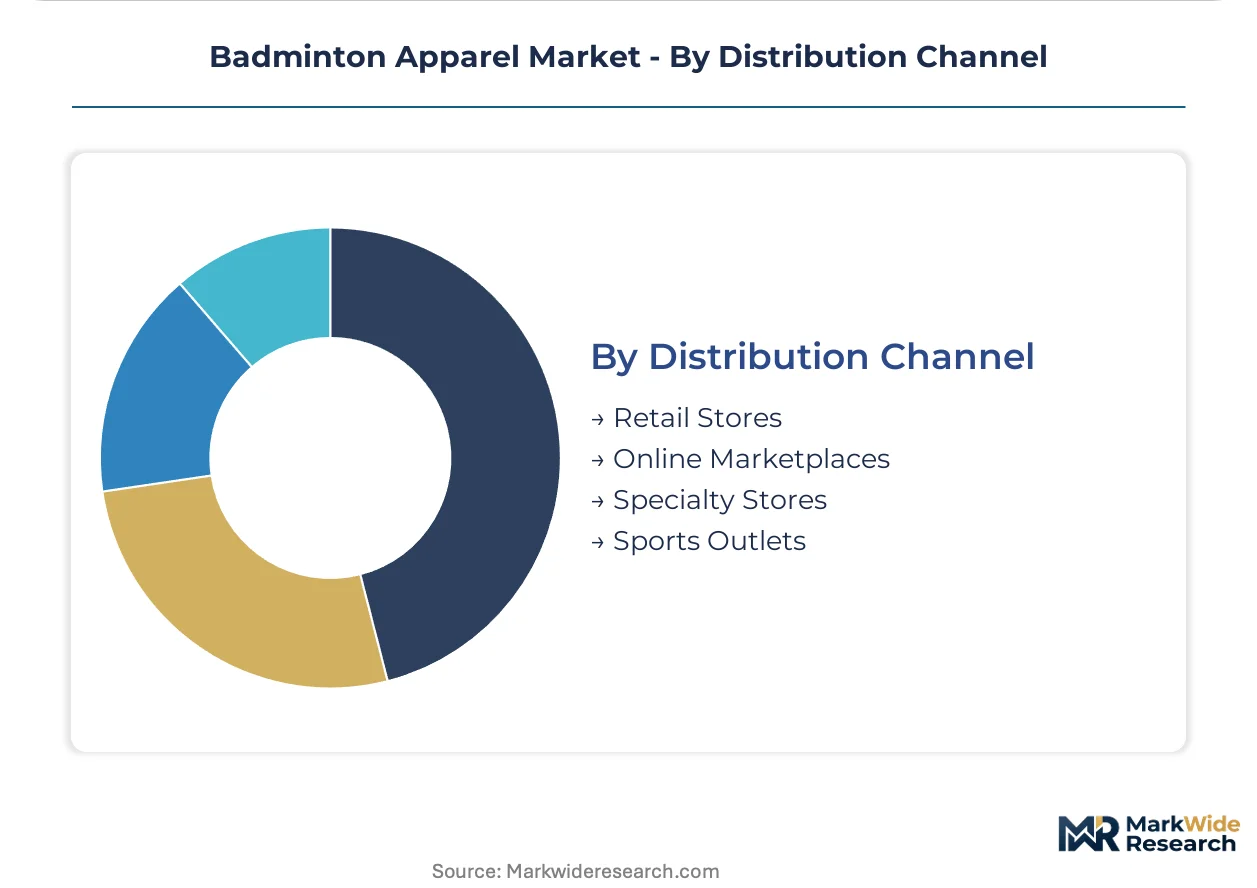
Distribution Channel:
Supply concentration varies by channel capital requirements and technical service intensity.
- Specialty Stores:Technical fitting expertise and sport-specific inventory depth support premium positioning.
- Online Marketplaces:Direct-to-consumer channels face margin compression as institutional buyers negotiate volume guarantees.
- Sports Outlets:Multi-sport retailers lack badminton-specific technical knowledge for performance garment selection.
- Retail Stores:Geographic coverage advantages compete with inventory depth limitations.
Specialty Stores retain the highest margin capture, while Online Marketplaces is climbing the fastest on volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in China commands a 15-20% premium over Indonesian wholesale benchmarks, reflecting tighter GB standards compliance costs and provincial sports bureau procurement concentration. Southeast Asian manufacturing hubs absorb design talent migration while Japanese technical centers face capacity constraints. Regional differentiation stems from regulatory stringency, federation procurement scale, and tropical climate adaptation requirements.
China
Provincial sports bureaus drive institutional procurement volume through multi-year federation supply contracts. GB 18401 textile safety mandates accelerate certified synthetic adoption while squeezing cotton-blend alternatives from competitive segments. Yangtze River Delta manufacturing clusters concentrate yarn-to-garment vertical operations serving domestic tournament-grade demand.
Indonesia
Junior academy enrollment surges compress replacement cycles for performance shirts and shorts across club-level training networks. National badminton association equipment programs consolidate bulk purchasing power among institutional buyers. Jakarta and Surabaya metropolitan areas anchor distribution infrastructure for tropical tournament circuit supply.
Japan
METI energy efficiency benchmarks for textile dyeing operations raise synthetic fabric processor costs and compress regional manufacturing competitiveness. Technical knit specialists with capital-intensive seamless machinery retain premium positioning for national team supplier relationships. Osaka-Kobe industrial corridor maintains design engineering density despite talent rotation pressures.
South Korea
Domestic badminton federation procurement standards emphasize ISO 20740 durability certification for competitive apparel. Seoul Capital Area concentration of elite training academies sustains replacement demand for moisture-wicking tournament wear. Busan-Ulsan textile processing hubs face margin pressure from Japanese and Chinese synthetic fiber competition.
India
BIS textile labeling requirements intersect with state-level sports department procurement consolidation in Maharashtra and Karnataka. Mumbai and Bangalore metropolitan clusters develop technical knit capacity for domestic tournament circuit supply. Price-sensitive recreational segments face steepest certification cost pass-through pressures.
Badminton Apparel Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Specialist badminton equipment manufacturers with captive textile operations command premium positioning through sport-specific biomechanical engineering, while diversified athletic apparel conglomerates leverage scale economies across multi-sport portfolios. Three archetypes dominate: vertically integrated specialists, multi-sport athletic brands, and regional procurement-anchored suppliers. Competitive moves concentrate on federation supply contract capture, thermoregulation technology licensing, and Southeast Asian manufacturing capacity expansion.
Among vertically integrated specialists, Yonex Co., Ltd. and Li-Ning Company Limited exemplify contrasting geographic anchoring strategies, with the former representing Japanese domestic production continuity and the latter occupying a position within China's provincial sports bureau distribution networks. Victor Rackets Industrial Corp. sits within the thermoregulation technology specialist tier, exemplifying tropical climate adaptation focus. These three companies anchor the competitive landscape without exhausting its structural diversity.
| Leading Market Players |
|---|
| Yonex Co., Ltd. |
| Li-Ning Company Limited |
| Victor Rackets Industrial Corp. |
| ASICS Corporation |
| adidas AG |
| Nike, Inc. |
| PUMA SE |
| Under Armour, Inc. |
| Apacs Sports (M) Sdn Bhd. |
| Others |
Supply Flow & Price Mechanics
Polyester filament substitution for cotton blends is simultaneously redrawing manufacturing geography toward Southeast Asian spinning hubs and compressing margin structures for mills lacking certified synthetic processing capabilities. This input shift concentrates pricing power among vertically integrated producers while fragmenting procurement options for mid-tier brands.
Pricing Analysis
The customization-premium spread separates federation-configured tournament kits from standard retail assortments, with institutional buyers capturing volume discounts that compress direct-to-consumer channel viability. Three-tier pricing structure across premium, standard, and economy levels stratifies by GB 18401 certification grade and moisture vapor transmission performance. Pricing pressure stems from petrochemical feedstock volatility, which squeezes mid-tier manufacturers without backward integration into yarn production. Recreational entry-level buyers exhibit highest price sensitivity, while national team suppliers accept premium positioning for thermoregulation-enhanced constructions.
Supply Chain Analysis
China and Vietnam anchor polyester knit fabrication, with Indonesia and Bangladesh absorbing cut-and-sew assembly for price-sensitive segments. Raw material flows draw from Zhejiang Province petrochemical complexes for filament supply, while elastane content sources from South Korean spandex specialists. Single-source vulnerability concentrates in seamless knitting machinery, where European and Japanese equipment suppliers dominate technical specifications. Distribution runs through provincial sports bureau procurement networks in China and national federation equipment programs in Indonesia, bypassing traditional retail intermediaries for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Badminton apparel traces a cyclical recovery pattern keyed to junior academy enrollment waves, which compress replacement cycles and concentrate procurement timing. Federation contract renewal windows create predictable demand spikes that favor prepared suppliers.
For Market Incumbents: Shield margin position by deepening backward integration into certified yarn production ahead of GB 18401 enforcement tightening. Secure exclusive thermoregulation technology licensing to differentiate tropical tournament offerings against multi-sport athletic brands encroaching from adjacent categories. Prioritize federation supply contract renewal timing to lock volume commitments before procurement consolidation accelerates.
For New Entrants and Emerging Players: Compression sock technical manufacturing represents an underserved white-space where specialized knitting machinery requirements deter commodity apparel entrants. Target Indonesia's club-level training segment through direct academy relationships, bypassing consolidated provincial sports bureau channels that favor incumbent distributors. Lead with biomechanical fitting services that multi-sport retailers cannot replicate, converting technical expertise into recurring procurement relationships.
For Investors and Strategic Acquirers: China's evolving GB standards enforcement reshapes the acquisition landscape by devaluing uncertified mill assets while premiumizing testing-capable operations. Five-to-ten year viability favors targets with captive synthetic fiber processing and established federation supplier status. Monitor junior academy enrollment trajectories in Indonesia and India as the demand inflection signal that precedes procurement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Federation Supply Contract Capture | Multi-year performance agreements with China's provincial sports bureaus lock volume and reduce channel conflict. |
| Thermoregulation Technology Licensing | Phase-change material integration opens premium positioning for tropical tournament circuits in Southeast Asia. |
| Seamless Knitting Capacity Expansion | Capital-intensive machinery acquisition displaces cut-and-sew competitors in high-performance national team supply. |
| Backward Integration into Yarn Production | In-house polyester filament processing insulates margin from petrochemical feedstock volatility and GB 18401 compliance costs. |
| Junior Academy Direct Distribution | Bypassing retail intermediaries in Indonesia's club-level segment captures replacement cycle timing and reduces price transparency. |
Methodological Framework
Desk research of customs trade databases, federation procurement records, and textile certification registries preceded structured interviews with brand product development directors, mill operations managers, and national association equipment officers. Primary fieldwork with provincial sports bureau procurement specialists and specialty retail buyers validated demand segmentation assumptions. Secondary sources included GB standards documentation, METI energy efficiency filings, and ISO 20740 test protocols. Bottom-up volume modeling and top-down market sizing triangulated through synthetic fiber consumption trends and tournament participation statistics.
Variance decomposition across product type, material grade, end-user tier, and distribution channel anchored the analytical framework over the projection horizon. Segmentation dimensions spanned garment construction complexity, fiber content certification level, player competitive tier, and procurement channel structure. CAGRs derived from replacement cycle frequency modeling and enrollment-driven demand elasticity. Industry-specific forecast inputs incorporated junior academy capacity expansion plans and federation equipment budget allocations.
Forecasts assume regulatory continuity in China's GB standards enforcement and Indonesia's national association procurement centralization; material policy shifts would require re-modeling. Specific risks include azo dye restriction timeline acceleration, petrochemical price spike persistence, and federation contract award delays. Recalibration cycles align with material shifts in junior academy enrollment data and synthetic fiber import volume trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Tablet Market
Others
Europe Aircraft Lighting Systems Market
Others
HPHT Diamond Cubic Press Market
Others
Fiberglass Storage Tanks Market
Others
Industrial Hooters Market
Others
Calcined Petroleum Coke Market
Others
LAMEA Astrology Market
Others
Pickup Truck Market
Others
Global Computer Peripherals Market
Others
Digital Media Adaptor (DMA) Market
Others
Fresh Durian Market
Others
Global Food Fiber Market
Others
Fiber to the X (Fttx) Tester Market
Others
Gas Radiators Market
Others
Mini Personal Computer Market
Others
Ultrasonic Flow Meter Market