
 Smart Finance Services Market | 2026-2036
Smart Finance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Finance Services Market Intelligence
ISO 27001 certification for information security management is reorganizing competitive access in smart finance services, raising compliance costs for smaller providers. Fujitsu Limited leverages its embedded systems heritage to sustain hardware-software integration across ATM networks. Diebold Nixdorf anchors self-service banking infrastructure in North America and Europe. Intel Corporation competes through edge-computing chipsets that power real-time fraud detection at transaction terminals.
Smart finance services encompass digitally enabled financial intermediation platforms that deploy algorithmic decision engines, API-driven data aggregation, and encrypted distributed ledgers to automate payments, credit scoring, portfolio allocation, and treasury operations. These systems process structured and unstructured financial data through machine learning pipelines operating at sub-second latency thresholds to reduce operational friction and counterparty risk. Robo-advisors and wealth management platforms capture margin pools among retail investors seeking low-cost portfolio automation. Payment processing and budgeting tools extend fastest among small businesses adopting cloud-native treasury workflows. Blockchain and AI segments attract R&D capital as institutions pilot programmable settlement infrastructure.
The SEC enforces disclosure standards for algorithmic trading systems, while the EU AI Act imposes risk-classification obligations on automated credit-decision engines, compressing deployment timelines for non-compliant vendors. GDPR and state-level privacy frameworks in California and New York fragment data governance costs across multi-jurisdictional operators. Stakeholders must track evolving central bank digital currency pilots and corresponding API standardization mandates that will reshape interoperability requirements.
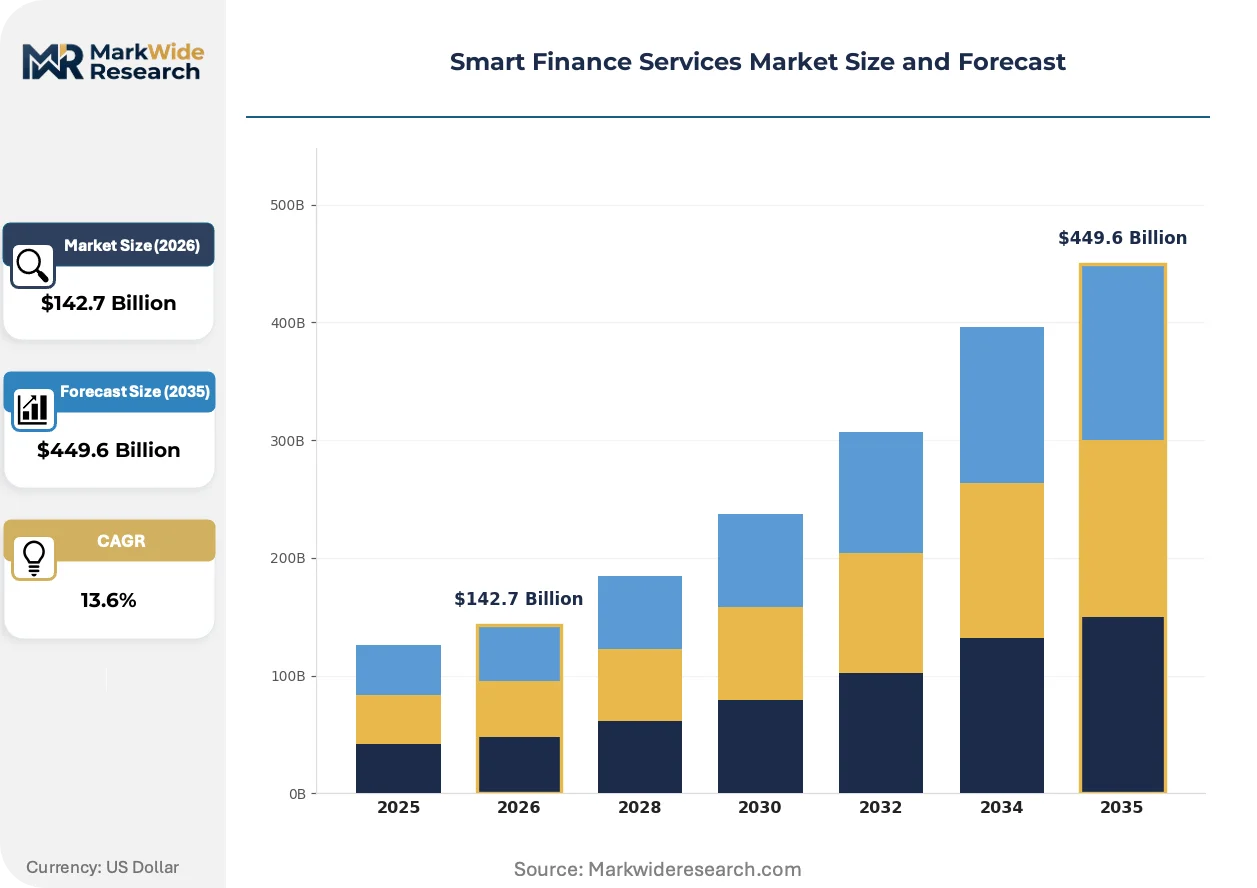
Market Dynamics
The EU AI Act's risk-classification framework for automated credit-decision engines is compressing deployment timelines and forcing algorithmic transparency investments across smart finance services. This regulatory pressure is reshaping competitive access as ISO 27001 certification costs concentrate vendor selection among well-capitalized providers.
Growth Catalysts
- Regulatory sandbox programs:The United States, China, and Germany have established controlled testing environments that accelerate fintech innovation cycles and reduce time-to-market for AI-powered budgeting tools.
- Small business cloud adoption:Payment processing and treasury workflow platforms extend fastest among SMBs adopting cloud-native infrastructure for automated reconciliation and cash forecasting.
- Edge computing architectures:Real-time fraud detection at transaction terminals now operates at sub-second latency thresholds, reducing counterparty exposure for retail banking networks.
Market Restraints
- GDPR and state privacy fragmentation:California's CCPA and New York's SHIELD Act impose multi-jurisdictional compliance costs that scale disproportionately for mid-tier operators.
- Algorithmic audit requirements:The SEC's disclosure standards for automated trading systems demand specialized legal and technical expertise that inflates operational overhead.
- Legacy core banking integration:Mainframe-dependent institutions face technical debt barriers when embedding API-driven data aggregation into existing infrastructure.
Strategic Opportunities
- Central bank digital currency pilots:API standardization mandates accompanying CBDC rollouts in Germany and China will reshape interoperability requirements for payment infrastructure providers.
- Wealth management automation:Robo-advisory platforms capture margin pools among retail investors seeking low-cost portfolio allocation, particularly in the United States.
- Blockchain settlement infrastructure:Programmable ledger pilots attract R&D capital as institutions experiment with atomic settlement for cross-border treasury operations.
Industry Challenges
- Machine learning pipeline talent scarcity:Sub-second latency engineering and encrypted distributed ledger architecture require specialized skill sets that command premium compensation in competitive labor markets.
- ISO 27001 certification timelines:Information security management audits extend 6-18 months, delaying market access for emerging providers against established competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Finance Services Market |
| Market Size in 2026 | $142.7 Billion |
| Market Size in 2035 | $449.6 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Robo-Advisors, Payment Processing, Wealth Management, Budgeting Tools Technology: Blockchain, AI, Machine Learning, Data Analytics End User: Retail Investors, Institutional Clients, Small Businesses, Large Corporations Deployment: Cloud-Based, On-Premises, Hybrid Models, Mobile Applications |
| Companies Covered | Diebold Nixdorf, Intel Corporation, Fujitsu Limited, IMS Evolve, GRGBanking Equipment Co., Ltd., Miles Technologies, Inc., Zicom SaaS Pvt. Ltd., Dialog Axiata PLC, Virtusa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Finance Services Market Strategic Shifts & Innovations
Machine learning pipelines for credit scoring and fraud detection are bifurcating into high-latency batch processing versus real-time inference architectures. This technical divergence is forcing vendors to specialize rather than generalize.
Real-time inference engines process structured and unstructured financial data at transaction terminals. Retail banking networks in Germany and the United States deploy these systems for instantaneous fraud flagging. The technology is bifurcating vendor strategies between edge-computing hardware specialists and cloud-native software providers.
The EU AI Act imposes conformity assessment obligations on automated credit-decision systems classified as high-risk. Financial institutions must maintain technical documentation and human oversight protocols. European retail banks are responding by establishing algorithmic governance committees and third-party audit relationships.
Small businesses are consolidating treasury workflows onto unified platforms that combine payment processing, budgeting, and cash forecasting. Traditional bank-provided cash management services face displacement from fintech-native alternatives. This pattern concentrates in the United States where SMB cloud software penetration exceeds other developed markets.
Smart Finance Services Market Segmentation
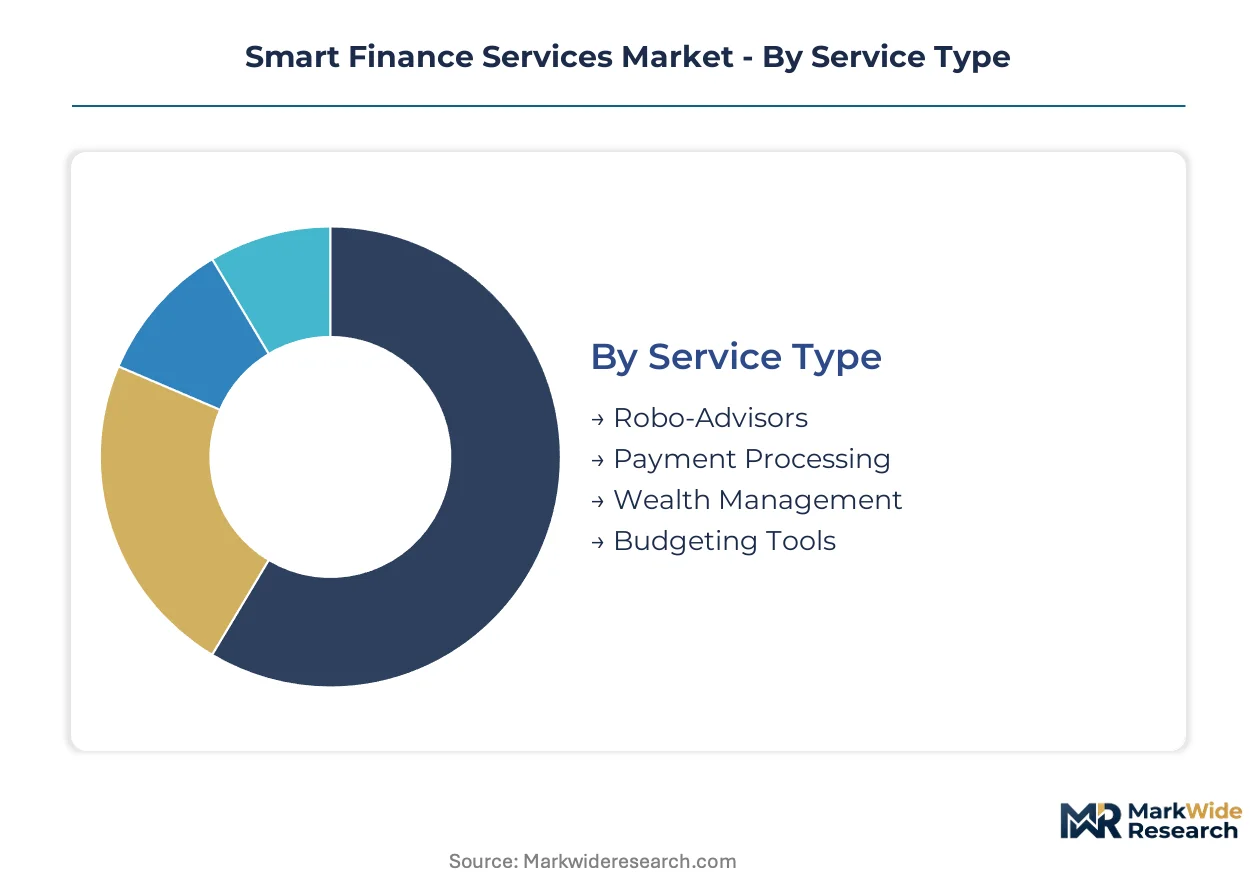
Smart finance services fragment across service delivery models, underlying technology stacks, and client sophistication levels. Each segmentation axis carries distinct regulatory exposure and margin architecture that shapes provider strategy.
Service Type:
Domestic demand concentrates in payment processing and budgeting tools, while wealth management and robo-advisory services draw cross-border platform competition from US and European operators.
- Robo-Advisors:Algorithmic portfolio allocation engines operate through automated risk-profiling questionnaires and ETF-based construction. Retail investors in Germany and the United States drive adoption as SEC disclosure requirements and EU AI Act conformity assessments elevate compliance costs for automated advice platforms.
- Payment Processing:Real-time transaction clearing infrastructure handles structured payment data through API-driven aggregation layers. Small businesses in the United States adopt cloud-native treasury workflows fastest, displacing traditional bank-provided cash management services with fintech-native alternatives.
- Wealth Management:Human-advisor hybrid platforms serve high-net-worth segmentation with bespoke portfolio construction.
- Budgeting Tools:AI-powered expense categorization and cash-flow forecasting applications target retail banking customers seeking automated financial discipline.
Payment processing holds the largest share; momentum sits with robo-advisors as regulatory sandboxes accelerate algorithmic transparency investments.
Technology:
Cost tier separation distinguishes capital-intensive blockchain infrastructure from lightweight data analytics deployments accessible to mid-tier providers.
- Blockchain:Distributed ledger architectures enable programmable settlement and atomic cross-border transactions. Large corporations piloting treasury automation in China and Germany attract R&D capital as central bank digital currency rollouts reshape interoperability requirements for payment infrastructure providers.
- AI:Neural network-driven credit scoring and fraud detection operate at sub-second latency thresholds. The EU AI Act's high-risk classification for automated credit-decision engines compresses deployment timelines and forces algorithmic transparency investments across European retail banking networks.
- Machine Learning:Supervised learning pipelines process structured and unstructured financial data for predictive risk modeling.
- Data Analytics:Descriptive and diagnostic visualization tools support treasury reporting and regulatory disclosure workflows.
Data analytics commands the broadest installed base; blockchain is climbing the fastest as institutions experiment with programmable settlement infrastructure.
End User:
Volume concentration follows business size, with small businesses driving fastest expansion and institutional clients demanding bespoke integration.
- Retail Investors:Mass-market individuals access low-cost portfolio automation through mobile-native platforms. United States households lead penetration as robo-advisory margins compress traditional wealth management fee structures and democratize access to algorithmic allocation.
- Institutional Clients:Pension funds, insurers, and asset managers require customized risk analytics and regulatory reporting integration. Large corporations in Germany demand ISO 27001-certified providers as information security management audits reorganize competitive access and raise compliance barriers for emerging vendors.
- Small Businesses:SMBs consolidate payment processing, budgeting, and cash forecasting onto unified cloud platforms.
- Large Corporations:Enterprise treasuries operate multi-entity liquidity management across jurisdictional boundaries.
Retail investors represent the deepest volume pool; institutional clients are gaining share fastest as algorithmic audit requirements elevate procurement thresholds.
Deployment:
Maturity differentiation separates established on-premises core banking from rapidly scaling cloud-native alternatives.
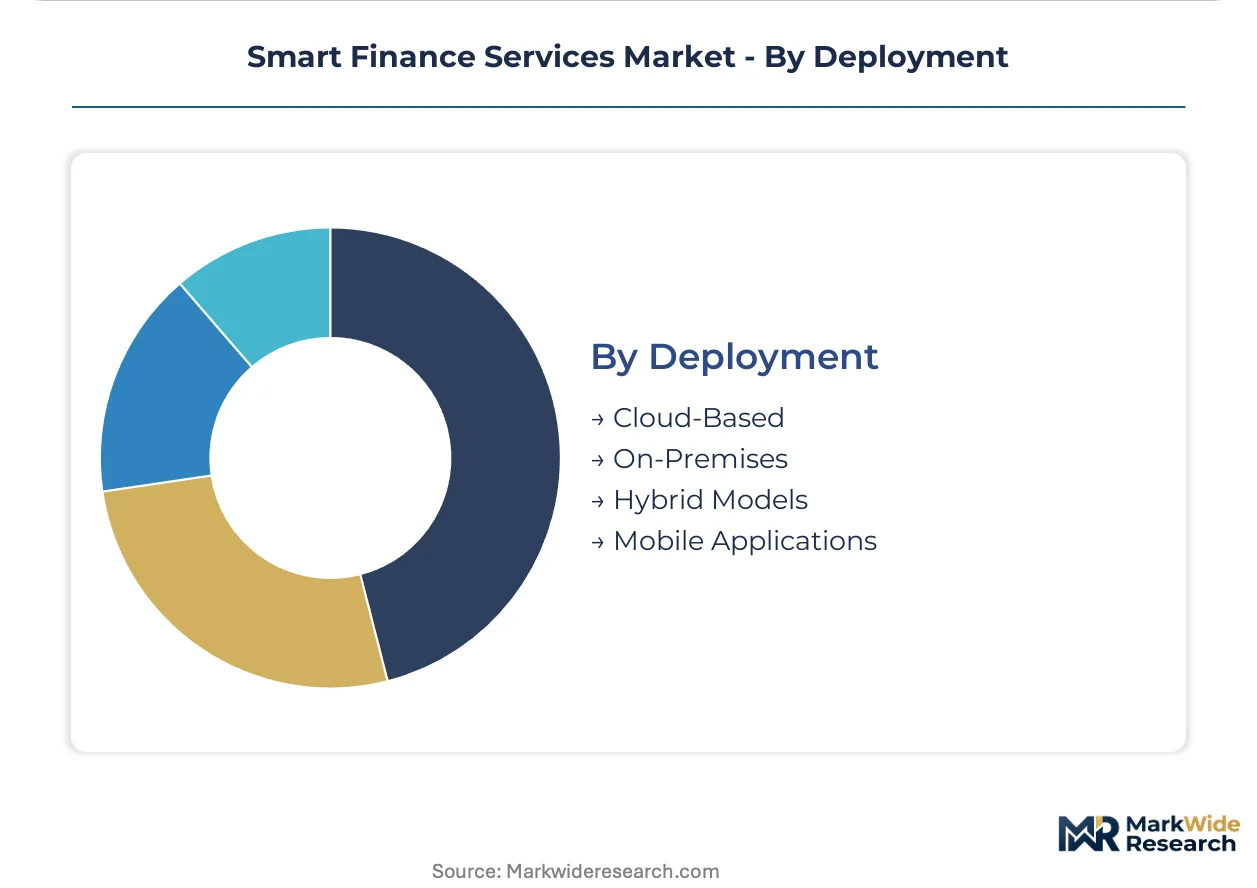
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for machine learning inference and real-time fraud detection. Small businesses in the United States adopt cloud-native treasury workflows fastest, extending payment processing and automated reconciliation capabilities without legacy core banking integration debt.
- Mobile Applications:Native iOS and Android interfaces dominate retail investor engagement with biometric authentication and push-notification alerting. China's regulatory sandbox environment accelerates fintech innovation cycles for mobile-first budgeting tools and wealth management access.
- On-Premises:Dedicated hardware installations serve institutions with data sovereignty requirements.
- Hybrid Models:Split architectures maintain sensitive operations locally while leveraging cloud elasticity for analytics.
Cloud-based deployment holds the largest share; mobile applications show the steepest expansion trajectory as retail banking customers accelerate adoption of AI-powered financial tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory sandbox programs in the United States, China, and Germany are accelerating fintech innovation cycles and compressing time-to-market for AI-powered financial tools. These controlled testing environments reduce compliance friction for algorithmic credit-decision engines and automated wealth management platforms.
United States
Retail banking customers are driving fastest adoption of AI-powered budgeting tools and robo-advisory platforms. The SEC enforces disclosure standards for algorithmic trading systems that inflate operational overhead for automated advice providers. New York and California state privacy frameworks fragment data governance costs, with fintech clusters in Silicon Valley and Manhattan bearing disproportionate compliance burdens.
China
Central bank digital currency pilots in major metropolitan areas are reshaping interoperability requirements for payment infrastructure providers. SAMR oversight of algorithmic recommendation systems imposes transparency obligations on automated credit platforms. The Yangtze River Delta and Pearl River Delta concentrate mobile-first wealth management innovation as regulatory sandboxes accelerate fintech deployment timelines.
Germany
Institutional clients demand ISO 27001-certified providers as information security audits reorganize competitive access. The EU AI Act's high-risk classification for automated credit-decision engines compresses deployment timelines across European retail banking networks. Frankfurt and Berlin anchor algorithmic governance committee formation and third-party audit relationship establishment.
United Kingdom
Wealth management automation captures margin pools among retail investors seeking low-cost portfolio allocation. FCA oversight of automated financial advice parallels EU AI Act risk-classification frameworks. London's fintech cluster concentrates robo-advisory platform development as GDPR compliance costs scale disproportionately for mid-tier operators.
Japan
Edge-computing architectures for real-time fraud detection at transaction terminals operate at sub-second latency thresholds. METI guidance on AI governance influences financial sector algorithmic transparency investments. Tokyo and Osaka anchor retail banking network upgrades as institutions pilot programmable settlement infrastructure.
Smart Finance Services Market Key Industry Players
Player mix skews toward diversified technology conglomerates with embedded systems heritage and specialized fintech infrastructure providers. Market structure concentrates around vendors with ISO 27001 certification capabilities and established hardware-software integration competencies. Two strategic archetypes dominate: edge-computing hardware specialists sustaining ATM network integration, and cloud-native software providers targeting SMB treasury workflow automation. Competitive moves center on strategic partnerships for regulatory sandbox access and portfolio diversification into blockchain settlement infrastructure.
Within the diversified technology tier, Intel Corporation and Fujitsu Limited occupy positions spanning hardware-software integration across financial infrastructure networks. Diebold Nixdorf anchors self-service banking equipment specialization in North American and European markets. These three exemplify the certification-heavy competitive dynamic where information security management audits delay market access for emerging providers against established competitors.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| Intel Corporation |
| Fujitsu Limited |
| IMS Evolve |
| GRGBanking Equipment Co., Ltd. |
| Miles Technologies, Inc. |
| Zicom SaaS Pvt. Ltd. |
| Dialog Axiata PLC |
| Virtusa Corporation |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification timelines spanning 6-18 months concentrate pricing power among established vendors while compressing margins for emerging providers seeking competitive access. This lead-time differential shapes supply chain sourcing decisions as procurement teams prioritize pre-certified partners over unverified alternatives, reinforcing incumbent advantages across ATM network integration and cloud-native treasury platforms.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate edge-computing hardware procurement, tethering transaction terminal pricing to foundry output cycles. Three-tier pricing structure across ISO 27001-certified premium, compliant-standard, and uncertified economy levels segments buyer access. Cost compression in the economy tier intensifies because mid-tier operators absorb disproportionate GDPR and state privacy compliance burdens. Small businesses exhibit highest price sensitivity, while institutional clients in Germany prioritize certification premiums over unit economics.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing chokepoints constrain edge-computing chipset availability for real-time fraud detection terminals, amplifying lead-time volatility across retail banking networks. Hardware-software integration draws from Taiwan, South Korea, and United States fabrication capacity, with specialized FPGA and ASIC architectures resting on concentrated foundry output. Single-source vulnerability in advanced node production threatens sub-second latency engineering pipelines. Distribution runs through direct OEM relationships with Diebold Nixdorf and Fujitsu Limited anchoring self-service banking equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart finance services are approaching a platform-economics inflection as central bank digital currency pilots in Germany and China force API standardization across previously siloed payment infrastructure. This interoperability shift will reorganize competitive access around certified providers capable of multi-jurisdictional compliance.
For Market Incumbents: Shield core ATM network relationships through accelerated ISO 27001 recertification and embedded firmware update cycles. Cloud-native entrants threaten self-service banking margins; vertical integration into edge-computing chipset sourcing secures supply continuity against Taiwan foundry constraints. Prioritize algorithmic governance committee establishment ahead of EU AI Act enforcement waves. For New Entrants and Emerging Players: Lead with SMB treasury workflow consolidation in United States regulatory sandboxes, where cloud-native penetration exceeds other developed markets. White-space concentrates in AI-powered budgeting tools for retail banking customers and blockchain settlement pilots for cross-border corporate treasuries. Partner with established hardware-software integrators to bypass certification timeline barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates seeking to divest non-core fintech infrastructure units. Long-term viability favors providers with demonstrated regulatory sandbox access and pre-established ISO 27001 certification. Monitor CBDC pilot expansion signals as inflection indicators for payment infrastructure valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Governance Investment | EU AI Act compliance committees in Frankfurt and Berlin reduce deployment timeline risk for automated credit engines. |
| Edge-Computing Partnership | Intel Corporation's fraud detection chipsets secure sub-second latency commitments from United States retail banks. |
| Regulatory Sandbox Access | China's SAMR-approved pilots accelerate mobile-first wealth management platform validation cycles. |
| ISO 27001 Certification Acceleration | Information security audits reorganize vendor selection criteria for German institutional procurement teams. |
| CBDC Interoperability Development | API standardization mandates accompanying German central bank pilots reshape payment infrastructure requirements. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with fintech product executives, bank CTOs, regulatory affairs specialists, and treasury platform engineers; and secondary validation against SEC disclosure filings, EU AI Act technical documentation, central bank digital currency pilot announcements, and ISO certification registry data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled deployment architecture, end-user sophistication tier, technology stack composition, and jurisdictional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion patterns. Forecast inputs incorporated edge-computing latency threshold evolution and algorithmic transparency investment trajectories specific to automated financial advice platforms.
The analysis sits within stated boundaries; outcomes outside sustained regulatory sandbox program expansion and ISO 27001 certification timeline stability would require recalibration. Forecasts reflect documented assumptions regarding CBDC pilot progression and EU AI Act enforcement intensity. Practitioners should keep alternative scenarios live as central bank digital currency interoperability mandates and algorithmic audit requirement scopes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Virtual Account Management Software Market
Financial Services
North America B2C Legal Services Market
Financial Services
Australia Online Trading Platform Market
Financial Services
BFSI A2P SMS Market
Financial Services
Credit Rating Software Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Debt Collection Software and Service Market
Financial Services
ATM Managed Services Market
Financial Services
Saas Escrow Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
Billing and Revenue Management Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
South Korea Financial Services Software Market
Financial Services
US Healthcare Finance Solutions Market