
 North America B2C Legal Services Market | 2026-2036
North America B2C Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America B2C Legal Services Market Insights
Paralegal workforce shortages across Ontario and the southwestern United States is reorganizing how legal platforms allocate human expertise versus automated workflows. LegalZoom leverages proprietary document engines to sustain volume leadership in standardized filings. Morgan & Morgan anchors its position through mass-tort advertising scale and plaintiff-side specialization. Rocket Lawyer competes via subscription pricing that locks in recurring consumer relationships.
North America B2C legal services encompass consumer-facing advisory, document preparation, and representation delivered outside corporate counsel structures, typically through flat-fee or contingency arrangements for matters under fifty thousand dollars in dispute value. Personal injury and divorce command the largest service-type revenue pools, though immigration and criminal defense segments face acute attorney supply constraints that push pricing upward. Subscription delivery models now capture recurring revenue from individuals and families seeking ongoing access to legal consultation, while hybrid online-in-person channels dominate in complex matters requiring court appearances.
The Federal Trade Commission monitors advertising claims in legal services, while state bar associations across California, New York, and Texas enforce unauthorized practice of law restrictions that shape platform operating boundaries. The American Bar Association's evolving guidance on lawyer-client relationships in digital environments influences how Clio and similar platforms structure attorney matching and document review protocols. Stakeholders must track state-level regulatory fragmentation as platforms expand across provincial and state lines with divergent fee-sharing and referral rules.
Market Dynamics
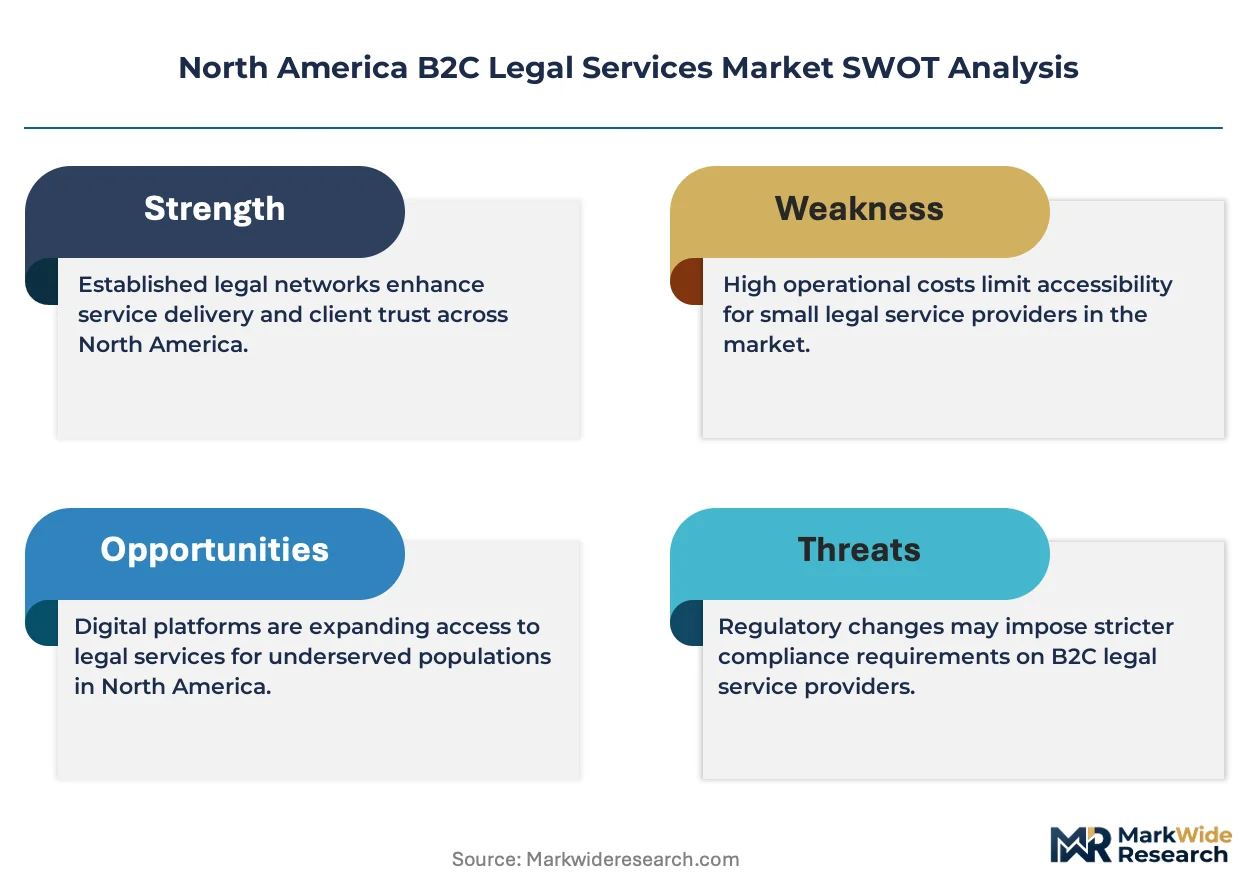
AI-powered document automation is compressing the cost structure for standardized legal filings across the United States and Canada, forcing traditional law firms to unbundle routine services from premium advisory work.
Growth Catalysts
- FTC advertising oversight:The Federal Trade Commission's enforcement against misleading legal service claims is elevating platform transparency and consumer trust in digital channels.
- Paralegal workforce gaps:Ontario and southwestern US jurisdictions face acute talent shortages that accelerate platform investment in automated document workflows.
- Subscription pricing models:Recurring revenue structures for family legal plans are locking in middle-income households seeking predictable access to consultation services.
Market Restraints
- State bar unauthorized practice restrictions:California, New York, and Texas bar associations enforce fee-sharing prohibitions that constrain platform expansion across jurisdictional lines.
- Attorney supply constraints:Immigration and criminal defense segments face acute licensed practitioner shortages that push service pricing beyond middle-income affordability thresholds.
- Regulatory fragmentation:Divergent provincial and state referral rules force platforms to maintain separate operational structures for each jurisdiction entered.
Strategic Opportunities
- Estate planning automation:Middle-income families in Florida and Texas represent underpenetrated demand for flat-fee will and trust preparation services.
- Hybrid channel development:Complex matters requiring court appearances are driving platform investment in integrated online-to-in-person service handoffs.
- American Bar Association digital guidance:Evolving standards on lawyer-client relationships in virtual environments create regulatory clarity for platform-based attorney matching protocols.
Industry Challenges
- Licensed attorney verification:Platforms face operational burden in validating active bar membership across multiple state jurisdictions in real-time.
- Legacy system integration:Court filing systems in older state jurisdictions resist API connectivity, forcing manual document submission workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America B2C Legal Services Market |
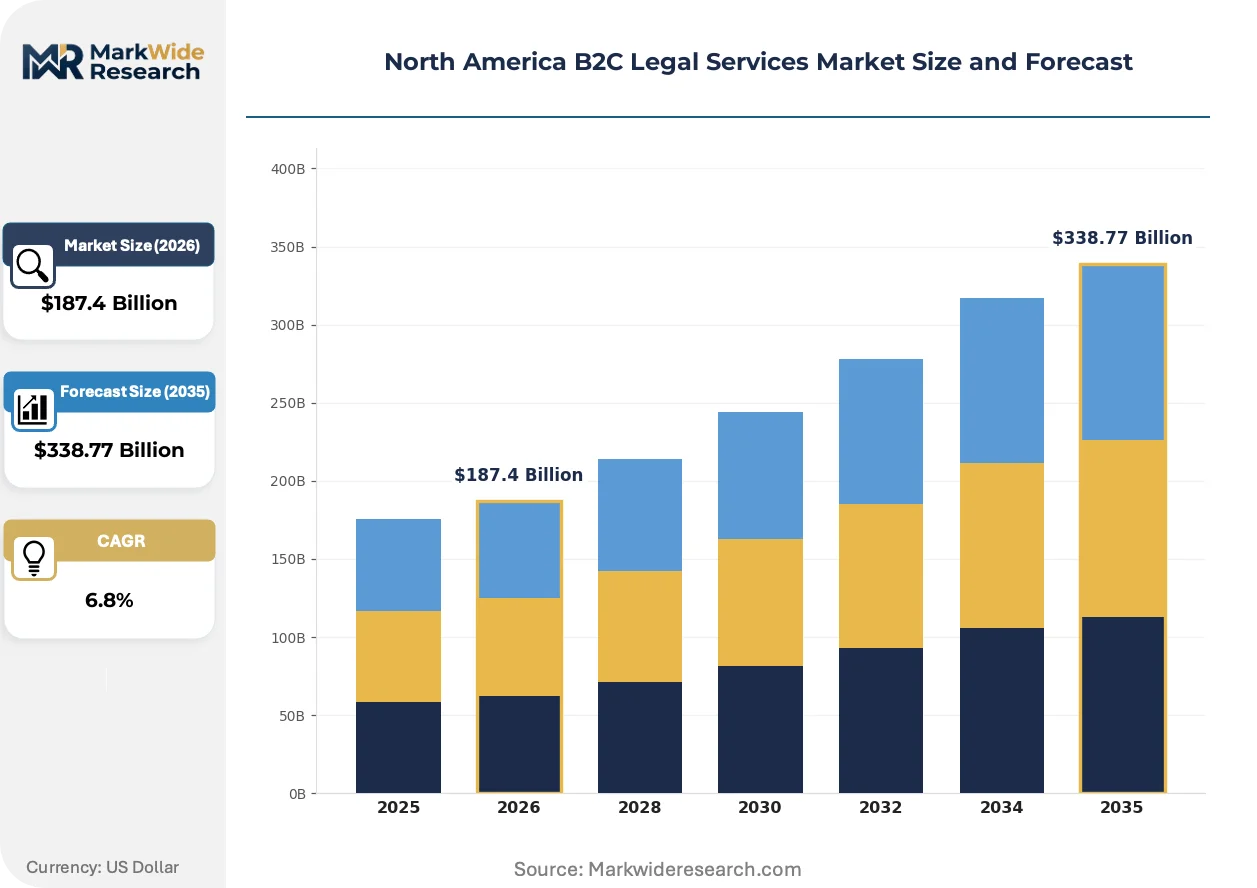
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Divorce, Personal Injury, Immigration, Criminal Defense Client Type: Individuals, Small Businesses, Non-profits, Families Delivery Model: In-person, Online, Hybrid, Subscription Pricing Model: Fixed Fee, Hourly Rate, Retainer, Contingency |
| Companies Covered | LegalShield, Clio, LegalZoom, Avvo, LawDepot, Rocket Lawyer, Hyatt Legal Plans, Nolo, Morgan & Morgan, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America B2C Legal Services Market Trends and Innovations
Document automation engines are redistributing legal work between human attorneys and algorithmic systems, compressing timelines for routine filings while elevating premium advisory services.
Natural language processing tools are fragmenting the traditional attorney-client relationship by enabling consumers to generate first-draft contracts, wills, and incorporation documents without initial lawyer consultation. Middle-income households in California and Texas are adopting these self-service pathways at accelerating rates. The technology is fragmenting revenue pools away from hourly-billing solo practitioners toward platform-mediated flat-fee structures.
The American Bar Association's evolving guidance on virtual lawyer-client relationships is reshaping platform compliance architectures across the United States. State bar associations in California, New York, and Texas are interpreting these standards through divergent enforcement lenses. Document review and attorney matching protocols on platforms like Clio are restructuring to satisfy the most restrictive jurisdictional interpretation.
Consumer purchasing patterns are compressing the traditional lawyer search cycle from weeks to hours through subscription-based legal plan adoption. Family households seeking ongoing access to consultation are displacing episodic, matter-based attorney retention. This behavioral shift concentrates most visibly in Florida and Texas metropolitan corridors where platform advertising density intersects with high population mobility.
North America B2C Legal Services Market Segmentation
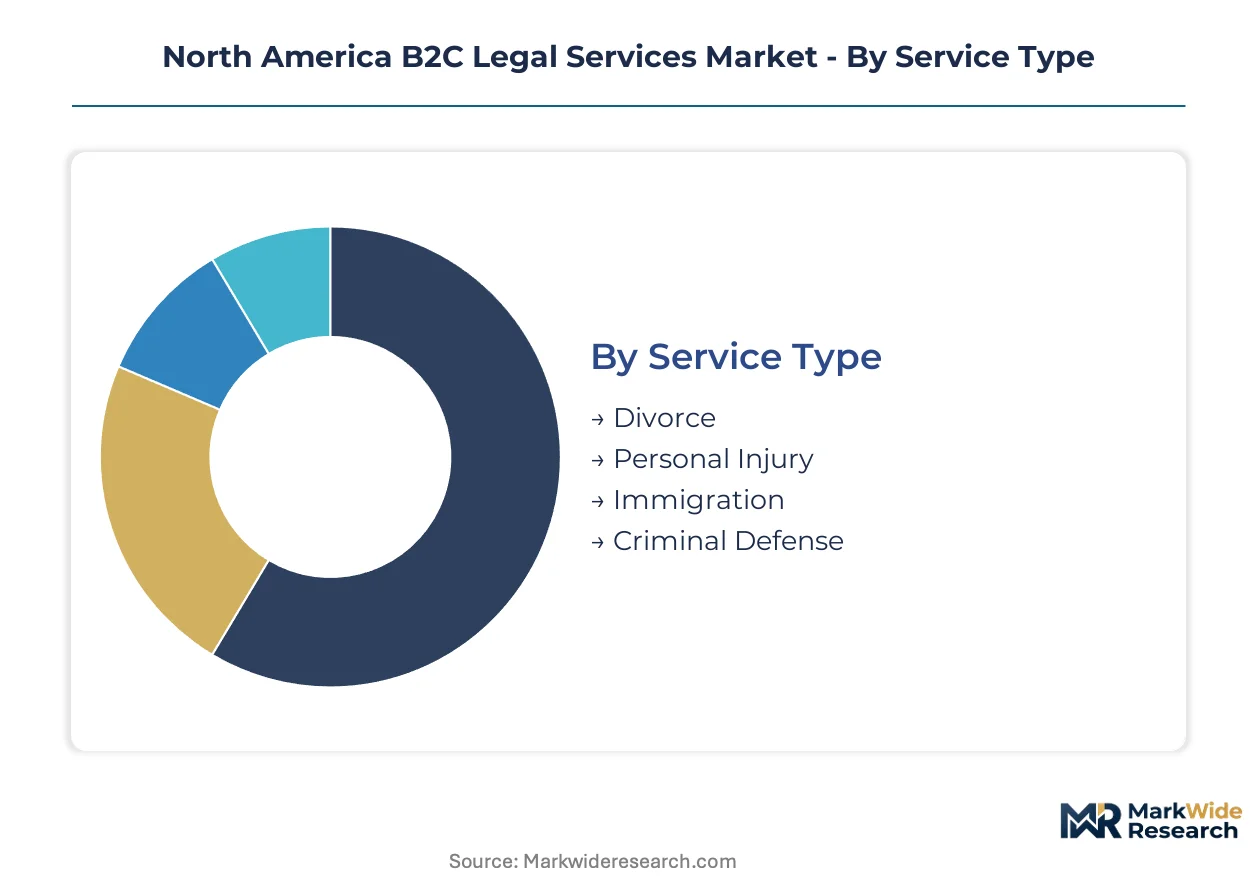
Segmentation in B2C legal services reveals how substitution pressure from document automation and platform intermediation concentrates differently across service categories. Understanding these fault lines exposes where traditional hourly billing retains pricing power versus where flat-fee automation captures volume.
Service Type:
Substitution pressure from AI document engines and self-service platforms varies sharply across service categories, with standardized filings facing the most intense displacement while courtroom representation maintains defensive moats.
- Divorce:Document automation engines now generate uncontested divorce petitions and property settlement agreements without attorney consultation. Demand concentrates in Texas and Florida metropolitan corridors where high population mobility elevates dissolution rates.
- Personal Injury:Contingency fee structures and mass-tort advertising scale sustain revenue concentration despite document standardization. California and Texas plaintiff bars anchor volume through class-action aggregation and television marketing density.
- Immigration:Licensed attorney supply constraints push pricing beyond middle-income affordability thresholds. Visa petition complexity and USCIS procedural volatility sustain premium advisory demand.
- Criminal Defense:Court appearance requirements and Sixth Amendment protections insulate this segment from platform substitution. Public defender capacity gaps in southwestern states drive private market expansion.
Personal Injury anchors the volume base while Immigration gains share at the steepest rate amid policy volatility and visa backlogs.
Client Type:
Cost tier differentiation separates episodic purchasers seeking one-time document preparation from recurring-revenue households locking in subscription access.
- Individuals:Single-matter consumers drive episodic revenue through traffic violations, landlord disputes, and simple will execution. Platform advertising density in California and Florida shapes acquisition costs.
- Families:Multi-generational households seeking estate planning continuity and ongoing custody modifications generate the highest lifetime value. Subscription pricing models lock in recurring relationships across Texas and Florida.
- Small Businesses:Contract drafting and employment policy updates concentrate demand among sub-fifty-employee enterprises. Ontario and California regulatory complexity elevates compliance advisory needs.
- Non-profits:Grant compliance and board governance requirements sustain modest but stable advisory demand. Pro bono program gaps in southwestern states push paid service utilization.
Families anchor the volume base while Small Businesses expand most quickly through regulatory complexity and platform self-service adoption.
Delivery Model:
Application context determines channel selection, with complexity thresholds dictating where pure digital suffices versus where physical presence becomes mandatory.
- Hybrid:Integrated online-to-in-person handoffs capture complex matters requiring court appearances. Platform investment concentrates in California and Texas where metropolitan density supports attorney network scale.
- Subscription:Recurring legal plan access locks in middle-income households seeking predictable consultation availability. Florida and Texas metropolitan corridors show the highest adoption density.
- Online:Pure digital delivery dominates standardized document generation and initial attorney matching. Natural language processing tools fragment traditional attorney-client relationship formation.
- In-person:Traditional office consultation retains dominance in criminal defense and contested litigation. State bar unauthorized practice restrictions constrain platform expansion into this channel.
Hybrid delivery anchors the volume base while Subscription climbs the fastest through recurring revenue capture and household retention mechanics.
Pricing Model:
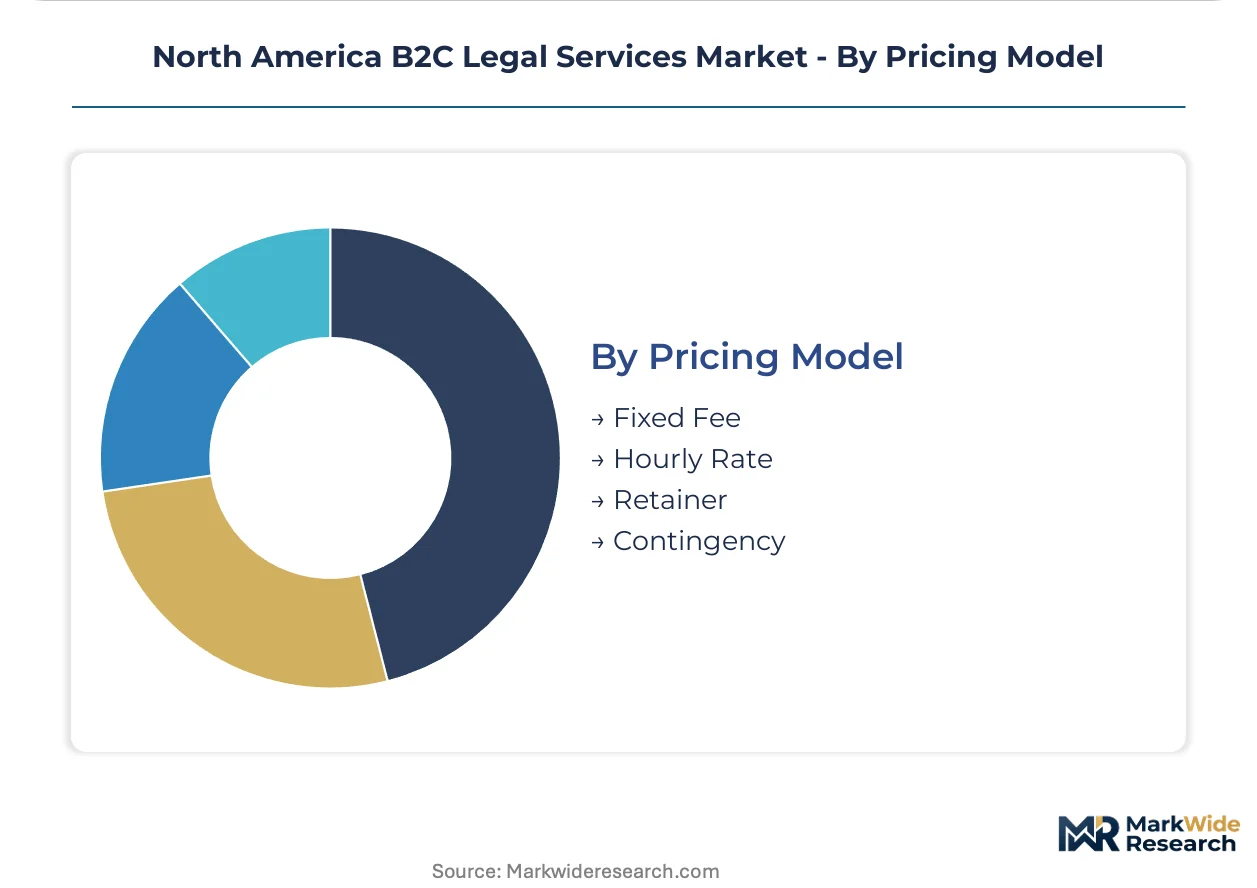
Margin structure separates fixed-fee platform mediation from contingency-scale plaintiff operations and hourly billing defense practices.
- Contingency:Plaintiff-side personal injury and mass-tort operations sustain the highest revenue per matter. Morgan & Morgan advertising scale demonstrates the capital intensity required for market presence.
- Fixed Fee:Flat-rate document preparation and unbundled advisory services compress margins while capturing volume. Middle-income affordability thresholds in Texas and Florida shape pricing bands.
- Hourly Rate:Traditional time-based billing retains dominance in complex litigation and white-collar defense. Criminal defense attorney supply constraints in immigration-heavy jurisdictions push rates upward.
- Retainer:Prepaid advisory relationships sustain solo practitioners and small partnerships. Estate planning and family law continuity generate predictable cash flow in high-mobility markets.
Fixed Fee anchors the volume base while Contingency shows the steepest expansion trajectory through mass-tort aggregation and advertising scale economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Trade Commission anchors the regulatory environment across the United States, where consumer protection enforcement shapes how legal platforms structure advertising and service delivery. State bar associations in California, New York, and Texas impose divergent fee-sharing restrictions that fragment operational architectures. Demand concentrates in metropolitan corridors where population density intersects with regulatory complexity.
United States
California, Texas, and Florida generate the highest B2C legal service volumes through population scale and mobility-driven demand for family law and estate planning. The State Bar of California enforces strict unauthorized practice of law restrictions that constrain platform expansion across county lines. Los Angeles and Houston metropolitan areas anchor the highest platform advertising density and subscription plan adoption rates.
Canada
Ontario and Quebec drive Canadian demand through immigration advisory needs and small business formation in Toronto and Montreal corridors. The Law Society of Ontario regulates paralegal scope of practice, creating workforce constraints that accelerate automation investment. Toronto's technology corridor hosts the highest concentration of legal tech platform development activity outside the United States.
Mexico
Mexico City and Guadalajara metropolitan areas concentrate demand for consumer legal services amid foreign investment-driven contract complexity. The Federal Consumer Protection Agency monitors legal service advertising claims, though enforcement remains less stringent than US counterparts. Cross-border legal needs in northern border states generate specialized advisory demand for immigration and trade documentation.
North America B2C Legal Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America B2C legal services market. Document automation platforms compete on scale economics while plaintiff-side litigation firms compete on advertising intensity and case aggregation capacity. Three strategic archetypes dominate: subscription-based legal plan providers, automated document generation platforms, and mass-tort litigation aggregators. Competitive positioning depends on M&A-driven technology acquisition and geographic expansion through attorney network scaling.
Within the subscription-based tier, LegalShield and Rocket Lawyer exemplify recurring revenue models that lock in household relationships through predictable consultation access. LegalZoom occupies a position bridging automated document preparation with attorney matching services. Morgan & Morgan represents the mass-tort aggregation archetype, where advertising scale and plaintiff-side specialization create defensive moats against platform commoditization. These three entities anchor distinct competitive vectors that shape how middle-income consumers access legal assistance across state and provincial boundaries.
| Leading Market Players |
|---|
| LegalShield |
| Clio |
| LegalZoom |
| Avvo |
| LawDepot |
| Rocket Lawyer |
| Hyatt Legal Plans |
| Nolo |
| Morgan & Morgan |
| Others |
Pricing and Supply Chain Analysis
State bar unauthorized practice restrictions across California, New York, and Texas simultaneously gate attorney network qualification and enforce fee-sharing prohibitions that segment pricing power by jurisdiction. This regulatory fragmentation forces platforms to maintain separate operational structures, elevating compliance costs that concentrate in premium advisory tiers while automated document workflows compress entry-level pricing.
Pricing Analysis
California commands the widest price spreads between Los Angeles metropolitan premiums and inland flat-fee markets. Three-tier pricing structure across premium, standard, and economy levels separates white-glove attorney matching from self-service document generation and basic template access. Price differentiation rests on customization depth and attorney review intensity. Cost compression in standardized filings is intensifying because AI document engines displace routine paralegal hours. Small businesses show the highest price sensitivity, while family estate planning subscribers accept recurring premiums for relationship continuity.
Supply Chain Analysis
The United States and Canada anchor legal platform development, with Ontario and California hosting the densest concentrations of document automation engineering and attorney network infrastructure. Raw material dependencies include natural language processing licenses, cloud compute capacity, and state bar membership verification databases. Single-source vulnerability concentrates in legacy court filing systems that resist API connectivity, forcing manual submission chokepoints. Distribution runs through direct-to-consumer digital channels, employer-sponsored legal benefit plans, and hybrid online-to-in-person handoffs for complex matters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle-income household consolidation around subscription legal plans has shifted buyer power toward recurring-revenue platforms and away from episodic hourly practitioners. This concentration elevates platform negotiating leverage with attorney networks.
For Market Incumbents: Fortify subscription retention mechanics through estate planning continuity features that lock in multi-generational household relationships. Deepen attorney network control in Texas and Florida through exclusive matching agreements that constrain competitor access. Document automation substitution and emerging AI-native entrants threaten margin compression in standardized filings. For New Entrants and Emerging Players: Immigration advisory gaps in southwestern states present white-space entry where licensed attorney supply constraints push pricing beyond platform saturation. Target uncontested divorce automation in high-mobility Texas metropolitan corridors where demand outpaces incumbent capacity. Employer-sponsored legal benefit channel partnerships offer the most penetrable B2B2C acquisition angle with predictable contract values. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-digital document preparation as AI inference costs decline and engineering leverage compounds. Long-term viability favors hybrid platform-architects that blend automated workflows with attorney network scale rather than pure-software or pure-service models. Watch attorney licensing reciprocity agreements as the signal indicating regulatory arbitrage opportunities for geographic expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Attorney Network Scaling | Platform coverage density in California and Texas metropolitan corridors determines consumer acquisition cost efficiency. |
| AI Document Engine Development | Proprietary natural language processing capabilities compress marginal cost for standardized filings below competitor reach. |
| Subscription Pricing Lock-in | Recurring household relationships in Florida and Texas generate predictable cash flows that fund geographic expansion. |
| Hybrid Channel Integration | Online-to-in-person handoff protocols capture complex matters requiring court appearances that pure-digital platforms forfeit. |
| Regulatory Arbitrage Positioning | Multi-jurisdictional compliance architectures exploit divergent state bar interpretations to accelerate cross-border expansion. |
Research Methodology
The analysis maps document automation platforms, subscription legal plan providers, and mass-tort litigation aggregators, each validated through platform executives, state bar regulatory counsel, legal tech engineers, and family law practitioners. Primary interviews combined with secondary validation from state bar disciplinary records, court filing system documentation, FTC advertising enforcement actions, and legal tech venture financing disclosures. Bottom-up attorney network sizing triangulates against top-down household legal spend estimates from consumer expenditure surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type complexity, client household structure, delivery channel integration, and pricing model mechanics. CAGRs derived from trend extrapolation of document automation adoption curves, subscription renewal rate trajectories, and attorney supply-demand imbalances in immigration and criminal defense segments.
Material uncertainties — regulatory reinterpretation of unauthorized practice boundaries, AI liability frameworks, and court system modernization timelines — sit outside the modeled envelope. Forecasts reflect assumptions about technology diffusion rates and bar association enforcement continuity that specific events could revise. Recalibration cycles align with material shifts in state bar guidance, FTC enforcement priorities, and platform M&A activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Canada Credit Cards Market
Financial Services
South Korea Factoring Services Market
Financial Services
Virtual Account Management Software Market
Financial Services
Digital Account Opening Market
Financial Services
ATM Managed Services Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Banknote Counters Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Global Automated Algo Trading Market
Financial Services
Germany E-Brokerage Market
Financial Services
Credit Rating Software Market
Financial Services
Solar Powered ATM Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Australia Online Gambling Market