
 Global Executive Search (Headhunting) Market | 2026-2036
Global Executive Search (Headhunting) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Executive Search (Headhunting) Market Foresight
ISO 10667 assessment certification for executive evaluation is collapsing as a universal gatekeeper, with boutique and technology-enabled search firms bypassing legacy credentialing through proprietary analytics platforms. Korn Ferry leverages its integrated organizational consulting backbone to anchor premium retained engagements across Fortune 500 board placements. Heidrick & Struggles differentiates through its Velocity leadership assessment engine, while Spencer Stuart sustains dominance in private equity-backed CEO succession mandates.
Executive search denotes a specialized professional service wherein retained consultants identify, evaluate, and recruit senior leadership candidates through confidential direct outreach, structured competency interviews, and psychometric validation against board-defined success criteria. The practice operates on exclusive fee structures tied to candidate first-year compensation, with typical retainers spanning one-third upfront, one-third at shortlist, and one-third at placement completion. Retained search commands the dominant margin pool due to exclusivity premiums and multi-year client relationships, while contract staffing captures volume growth as enterprises flex leadership capacity during transformation programs. Talent mapping gains traction among multinational corporations seeking proactive succession pipelines across emerging market subsidiaries.
The U.S. SEC climate disclosure rules and EU CSRD mandate new board-level sustainability expertise, forcing search firms to develop ESG-competent candidate pools or forfeit regulated-industry mandates. Japan's METI governance code revisions similarly reshape director independence requirements across listed enterprises. Stakeholders must monitor how generative AI tools for candidate sourcing and predictive performance modeling reshape fee structures and consultant productivity benchmarks.
Market Dynamics
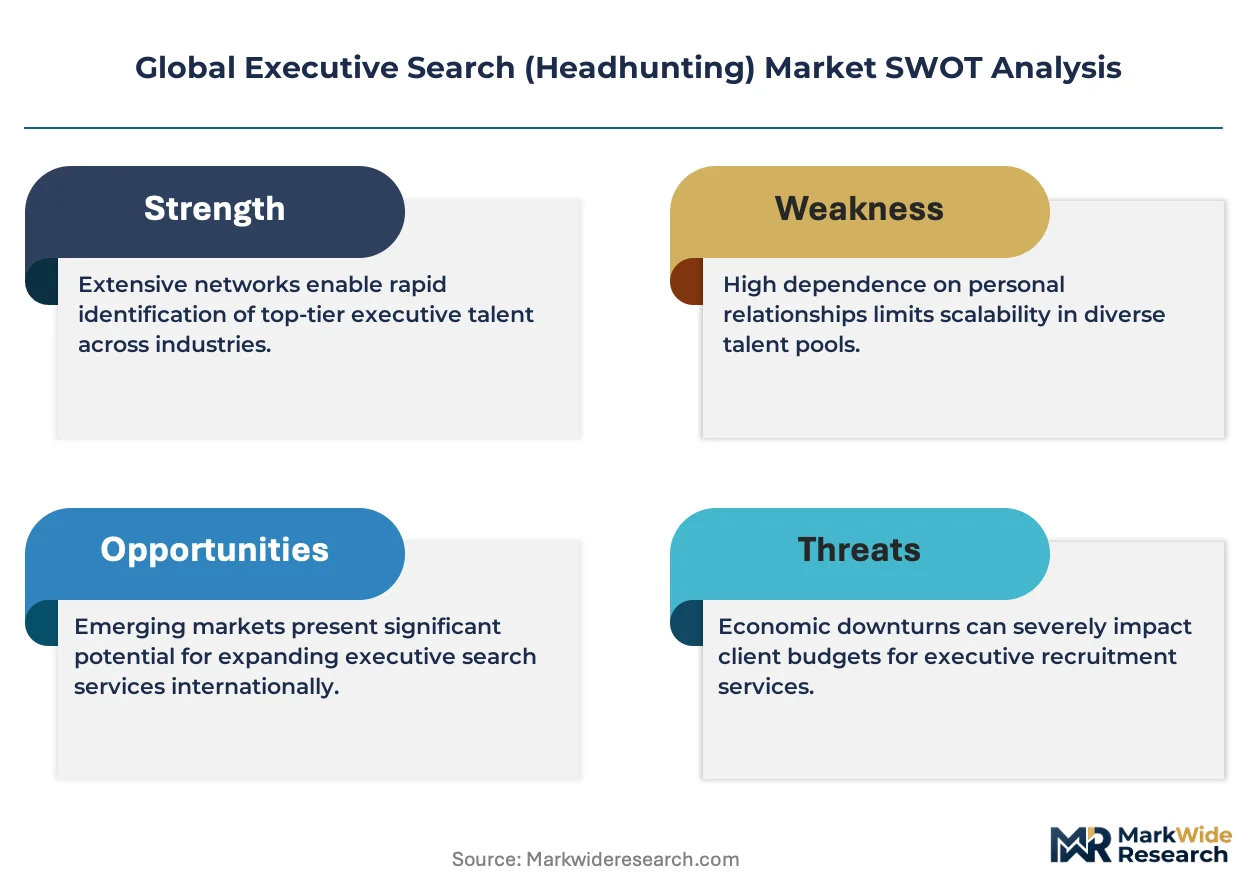
The executive search market is bifurcating around digital credentialing infrastructure, as proprietary assessment platforms from technology-enabled challengers erode the dominance of legacy certification frameworks that once governed partner selection at multinational enterprises.
Growth Catalysts
- EU AI Act compliance mandates:Regulated industries across the European Union now require board-level AI governance expertise, generating retained search mandates for chief technology officers with algorithmic accountability credentials.
- Private equity portfolio velocity:North American buyout firms are compressing CEO succession timelines to 90-day cycles, sustaining premium fee structures for search firms with dedicated financial sponsor practices.
- Digital transformation leadership gaps:Industrial conglomerates in Germany and Japan are recruiting chief digital officers with manufacturing IoT deployment experience, expanding addressable demand beyond traditional technology sector boundaries.
Market Restraints
- Fee compression from contingent alternatives:Technology platforms offering fixed-fee executive sourcing are capturing mid-market mandates previously served by retained search incumbents.
- Talent pool concentration in Silicon Valley:Venture-backed technology executives cluster geographically, creating supply bottlenecks for searches requiring relocation to secondary headquarters locations.
- ISO 10667 assessment fragmentation:The collapse of universal credentialing standards forces search firms to invest in proprietary validation tools, raising fixed cost structures without commensurate pricing power.
Strategic Opportunities
- India's manufacturing leadership pipeline:Multinational corporations are building proactive succession benches for subsidiary chief executives as production shifts accelerate under the country's PLI scheme incentives.
- Climate disclosure expertise demand:The US SEC climate rules and EU CSRD are creating new board competency requirements that search firms can monetize through specialized sustainability officer practices.
- Generative AI sourcing convergence:Firms integrating large language models into candidate identification workflows are compressing research phases, enabling higher consultant utilization rates against fixed retainer structures.
Industry Challenges
- Psychometric validation skill scarcity:Consultant pipelines lack depth in industrial-organizational psychology, forcing reliance on external vendors and margin dilution.
- Client data integration complexity:Search firms must reconcile proprietary candidate databases with client applicant tracking systems, creating implementation friction and project delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Executive Search (Headhunting) Market |
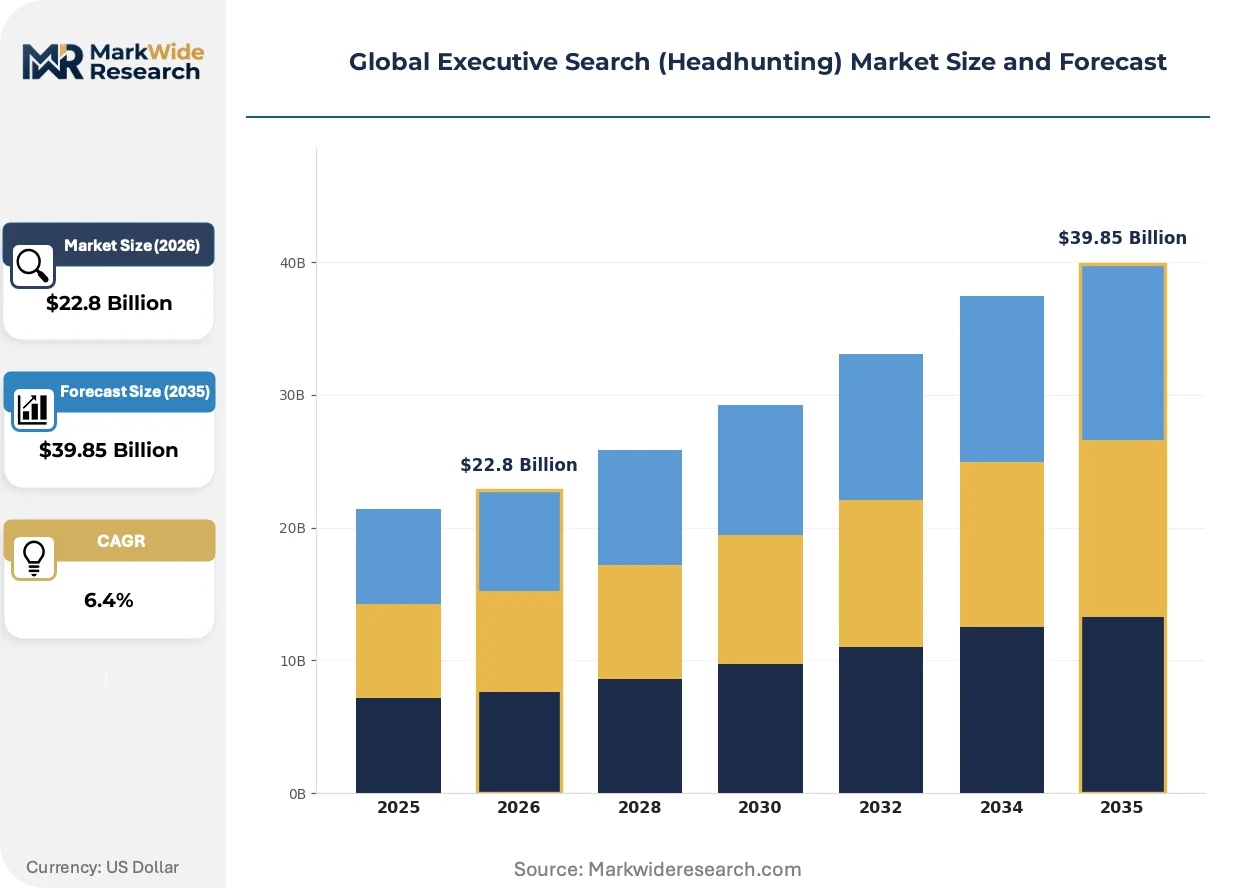
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retained Search, Contingency Search, Contract Staffing, Talent Mapping, Advisory Services Industry Focus: Information Technology, Consumer Goods, Financial Services, Pharmaceuticals, Telecommunications Client Type: Multinational Corporations, SMEs, Startups, Non-Profit Organizations, Government Agencies Engagement Model: Exclusive Mandate, Multiple Mandate, Project-Based, On-Demand, Recruitment Process Outsourcing |
| Companies Covered | Korn Ferry, Heidrick & Struggles, Spencer Stuart, Russell Reynolds Associates, Egon Zehnder, Odgers Berndtson, DHR Global, Amrop Partnership, NGS Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Executive Search (Headhunting) Market Shifts & Advancements
Generative artificial intelligence is restructuring how executive candidates are identified, evaluated, and presented, compressing traditional research timelines while raising new questions about assessment validity and client acceptance.
Predictive analytics platforms are displacing manual candidate sourcing workflows across retained search practices. Large language models now parse unstructured professional histories to identify leadership potential markers invisible to keyword-based screening. Fortune 500 technology and financial services divisions are piloting these tools for board-level mandates, though adoption remains cautious among industrial incumbents with conservative governance cultures.
The EU AI Act's risk-based classification system is mandating algorithmic transparency in automated hiring tools used by search firms serving regulated industries. European financial institutions and healthcare conglomerates must now document how AI-driven candidate ranking systems avoid discriminatory outcomes. Search firms operating across Germany, France, and the Netherlands are investing in compliance infrastructure or exiting regulated-sector mandates entirely.
Outcome-based fee structures are gaining traction among private equity sponsors seeking to align search firm incentives with candidate performance. Retainers now increasingly tie final payments to 12-month retention milestones rather than placement completion alone. This model is most visible in North American buyout markets, where sponsor relationships command pricing experimentation unavailable to corporate human resources departments with rigid procurement policies.
Global Executive Search (Headhunting) Market Segmentation
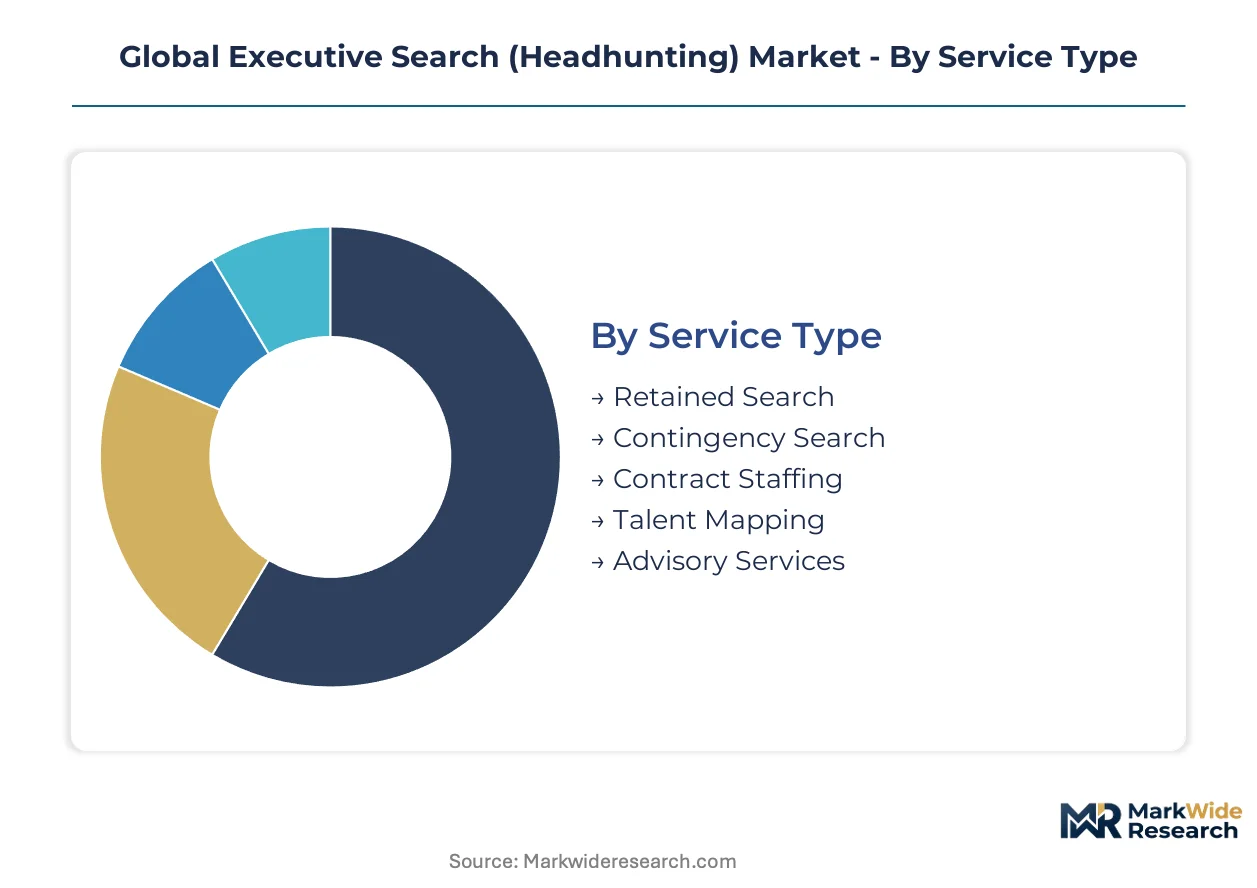
Executive search segmentation reveals how fee structures, client scale, and service intensity map to distinct operational models. Each category exposes different margin profiles and consultant productivity benchmarks across the industry.
Service Type:
Retained search engagements concentrate in domestic board placements across the United States and Germany, while contract staffing and talent mapping increasingly serve export-led multinational expansion into India and Southeast Asian manufacturing hubs.
- Retained Search:Exclusive mandates with three-phase fee structures tied to first-year compensation. Demand clusters in Fortune 500 CEO succession and private equity-backed leadership refreshes across New York, London, and Frankfurt financial centers. The EU AI Act is forcing search firms to document algorithmic transparency in candidate ranking systems used for regulated-industry placements.
- Contingency Search:Non-exclusive, success-fee arrangements typically capturing 15-25% of placed candidate compensation. Volume concentrates in mid-market technology and professional services sectors where hiring velocity outweighs confidentiality requirements. Fee compression from technology-enabled platforms is eroding margins in this segment.
- Contract Staffing:Temporary executive placement for transformation programs and interim leadership gaps. German industrial conglomerates and Japanese automotive groups deploy this model during digital restructuring.
- Talent Mapping:Proactive succession bench development without immediate placement mandate. Multinationals building India subsidiary leadership pipelines under the country's PLI scheme incentives drive adoption.
- Advisory Services:Organizational design and compensation benchmarking bundled with search relationships. Sustains consultant utilization during slow placement cycles.
Retained search holds the largest share; momentum sits with contract staffing as enterprises flex leadership capacity through economic uncertainty.
Industry Focus:
Technology sector mandates generate the highest fee premiums due to scarce digital transformation leadership, while pharmaceutical and financial services searches face escalating compliance complexity from sector-specific regulators.
- Information Technology:Chief technology officer and chief digital officer placements dominating retained search volume. Silicon Valley talent concentration creates supply bottlenecks for searches requiring relocation to secondary headquarters in Austin, Toronto, or Berlin.
- Financial Services:Board-level risk and compliance expertise mandated by SEC climate disclosure rules and EU CSRD sustainability requirements. European financial institutions must now document AI governance credentials in automated hiring tools.
- Consumer Goods:Supply chain and e-commerce leadership for omnichannel transformation. Demand spreads across developed and emerging markets.
- Pharmaceuticals:R&D leadership and regulatory affairs expertise for FDA and EMA compliance. Patent cliff pressures accelerate CEO succession cycles.
- Telecommunications:Infrastructure and 5G deployment leadership for network modernization programs.
Information technology commands premium pricing; financial services is climbing the fastest as regulatory mandates expand board competency requirements.
Client Type:
Multinational corporations sustain the longest consultant relationships through multi-year retained agreements, while startup demand concentrates in venture-growth chief revenue officer and chief financial officer searches.
- Multinational Corporations:Complex matrix organizations requiring subsidiary CEO succession across 10+ country operations. Proactive talent mapping investments exceed $500,000 annually for largest accounts.
- SMEs:Owner-founder transitions and first professional CEO placements. Price sensitivity drives contingent search adoption.
- Startups:Venture-backed scaling leadership with compressed 30-day placement timelines. Geographic clustering in San Francisco, Boston, and Tel Aviv.
- Non-Profit Organizations:Board-governed searches with mission-alignment screening beyond commercial metrics.
- Government Agencies:Public sector executive recruitment with procurement-compliant RFP processes.
Multinational corporations anchor revenue concentration; startups are expanding most quickly as venture deployment sustains aggressive hiring.
Engagement Model:
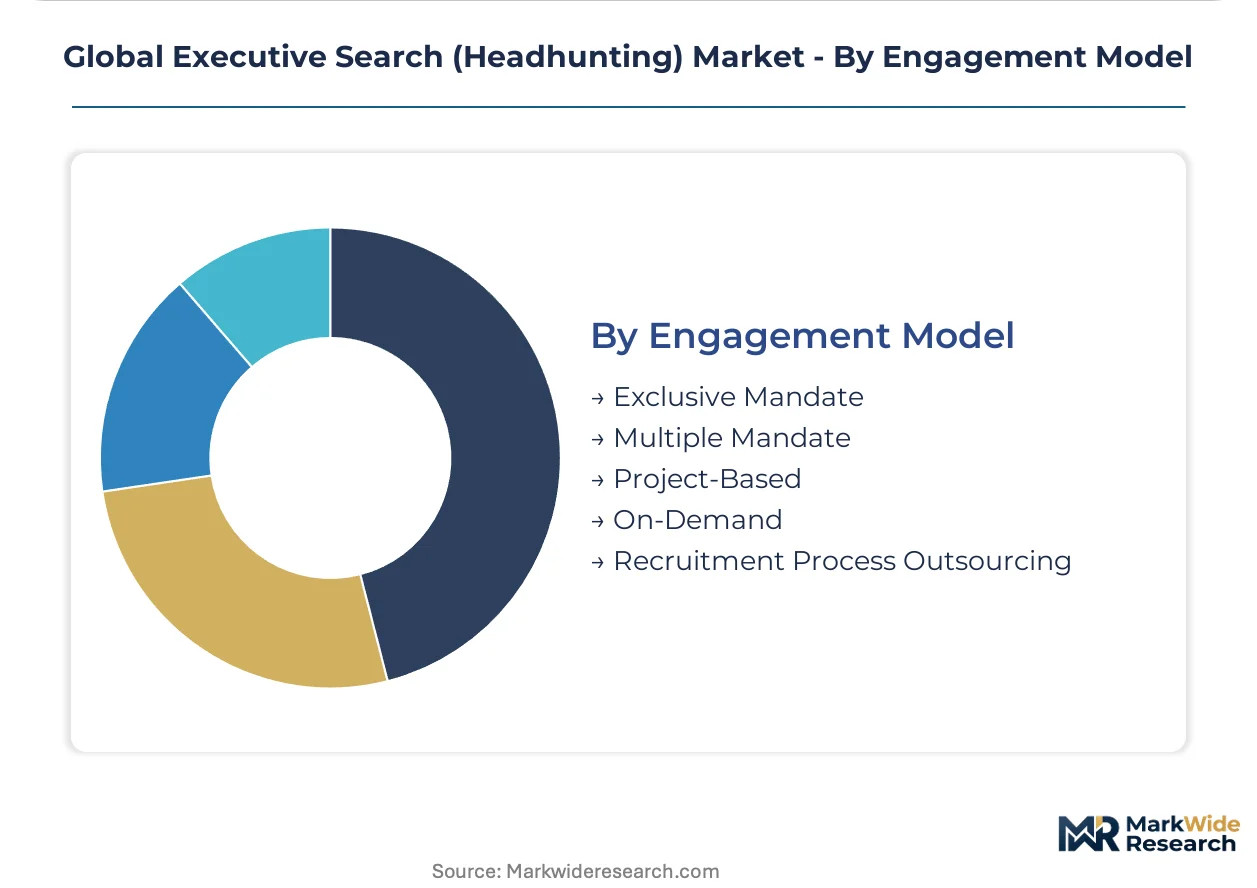
Exclusive mandates dominate C-suite placements where confidentiality and candidate quality outweigh cost considerations, while project-based and on-demand models capture volume in functional leadership tiers.
- Exclusive Mandate:Single-firm retention with dedicated consultant team and off-limits protections. Standard for board director and CEO searches across S&P 500 and DAX-listed enterprises.
- Multiple Mandate:Competitive engagement with 2-3 search firms for non-confidential roles. Contingency fee structures predominate.
- Project-Based:Fixed-scope engagements for specific leadership cohort builds or geographic expansions.
- On-Demand:Subscription access to search firm research and candidate databases without placement commitment.
- Recruitment Process Outsourcing:End-to-end executive hiring function transfer for high-volume leadership needs.
Exclusive mandate retains the dominant margin pool; on-demand models are gaining share fastest as procurement departments seek budget predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private equity sponsors and Fortune 500 boards concentrate retained search spending in financial centers with deep leadership talent pools and regulatory complexity. Geographic demand patterns track private capital deployment cycles and corporate headquarters density rather than population or GDP alone.
United States
Buyout firms in New York and Boston compress CEO succession timelines to 90-day cycles, sustaining premium fee structures for dedicated financial sponsor practices. SEC climate disclosure rules mandate new board-level sustainability expertise, forcing search firms to develop ESG-competent candidate pools. Silicon Valley talent concentration creates supply bottlenecks for searches requiring relocation to secondary headquarters in Austin or Denver.
Germany
Industrial conglomerates in Baden-Württemberg and Bavaria recruit chief digital officers with manufacturing IoT deployment experience, expanding addressable demand beyond traditional technology boundaries. The EU AI Act mandates algorithmic transparency in automated hiring tools, forcing compliance infrastructure investments. Frankfurt's financial center drives board-level risk and compliance expertise mandates tied to CSRD sustainability requirements.
United Kingdom
London's status as a private equity hub sustains aggressive leadership refresh cycles across portfolio companies. The Financial Conduct Authority's evolving governance codes reshape director independence requirements for listed enterprises. Fintech and professional services clusters in the City and Canary Wharf generate concentrated demand for CFO and chief revenue officer placements.
Japan
METI governance code revisions reshape director independence requirements across Tokyo Stock Exchange-listed enterprises. Automotive and electronics groups in Nagoya and Osaka deploy contract staffing models during digital restructuring programs. Aging demographic pressures accelerate proactive succession bench development for subsidiary chief executives.
India
Multinational corporations build proactive succession pipelines for subsidiary CEOs as production shifts accelerate under the PLI scheme incentives. Mumbai and Bangalore clusters concentrate venture-backed scaling leadership demand with compressed 30-day placement timelines. SEBI's evolving corporate governance standards elevate board competency requirements for listed entities.
Global Executive Search (Headhunting) Market Competitive Landscape
Player mix skews toward integrated consulting-search hybrids and technology-enabled boutiques, with legacy pure-play retainers defending position through relationship depth and exclusivity premiums. The competitive terrain splits between scale-driven global networks with organizational consulting backbones and specialized practices serving financial sponsors or regulated industries. Strategic archetypes include integrated talent-management platforms, private equity-dedicated boutiques, and AI-augmented research challengers. Dominant competitive moves center on proprietary assessment technology development and outcome-based fee structure experimentation.
Within the integrated consulting tier, Korn Ferry leverages its organizational consulting backbone to anchor premium retained engagements. Heidrick & Struggles occupies a position as a technology-enabled pure-play through its Velocity leadership assessment engine. Spencer Stuart exemplifies the relationship-driven archetype sustaining dominance in private equity-backed CEO succession mandates.
| Leading Market Players |
|---|
| Korn Ferry |
| Heidrick & Struggles |
| Spencer Stuart |
| Russell Reynolds Associates |
| Egon Zehnder |
| Odgers Berndtson |
| DHR Global |
| Amrop Partnership |
| NGS Global |
| Others |
Supply & Pricing Matrix
Consultant utilization rates at scale-driven search firms anchor both cost structures and pricing floors, as fixed retainer economics require sustained billable-hour velocity to cover proprietary assessment platform investments. This scale dynamic concentrates supply among integrated consulting hybrids while compressing margins for boutiques lacking workflow automation.
Pricing Analysis
Retained search contracts indexed to first-year candidate compensation dominate the market, with three-phase payment structures spanning one-third upfront, one-third at shortlist, and one-third at placement. Price differentiation rests on exclusivity premiums and multi-year relationship tenure rather than service tiering. Cost compression in mid-market contingency search is intensifying because technology platforms capture volume mandates with fixed-fee sourcing. Corporate procurement departments exhibit highest price sensitivity, while private equity sponsors accept outcome-based premiums tied to 12-month retention milestones.
Supply Chain Analysis
The United States, United Kingdom, and Germany anchor the global supply of senior search consultants, with London and New York financial centers producing the deepest benches of financial sponsor-dedicated practices. Talent pipelines draw from industrial-organizational psychology programs, former C-suite executives, and strategy consulting alumni. Single-source vulnerability concentrates in Silicon Valley for technology leadership mandates, where geographic clustering creates supply bottlenecks for relocation searches. Distribution runs through partner-led relationship networks rather than centralized platforms, preserving premium pricing through information asymmetry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates the executive search market as regulatory mandates splinter demand into specialized competency pools that scale-driven incumbents cannot address uniformly. The EU AI Act and SEC climate disclosure rules create niche openings for boutiques with domain-specific validation tools.
For Market Incumbents: Secure algorithmic transparency documentation for regulated-industry mandates before the EU AI Act enforcement window closes. Invest in proprietary assessment infrastructure to offset ISO 10667 credential collapse, while consolidating financial sponsor relationships through dedicated partner coverage teams that compress placement timelines below 90-day benchmarks.
For New Entrants and Emerging Players: Differentiate on ESG-competent candidate pools for board sustainability mandates, where incumbent development lags regulatory velocity. Target India's manufacturing leadership pipeline under PLI scheme incentives, where proactive succession bench development exceeds $500,000 annually for multinational accounts. Pursue on-demand subscription models that procurement departments favor for budget predictability.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-augmented research challengers with generative sourcing workflows that compress research phases. Long-term viability hinges on outcome-based fee structure acceptance across private equity sponsor relationships. Watch for inflection when contingent technology platforms capture retained-search-caliber mandates in regulated industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Assessment Platform Development | Velocity leadership engines from Heidrick & Struggles demonstrate premium pricing power through validated psychometric differentiation. |
| Financial Sponsor Practice Buildout | Spencer Stuart's dedicated buyout coverage sustains exclusivity premiums through 90-day succession cycle compression. |
| ESG-Competent Candidate Pool Investment | Korn Ferry's integrated organizational consulting backbone anchors CSRD-mandated board sustainability expertise mandates. |
| Generative AI Sourcing Integration | Large language model deployment in candidate identification workflows raises consultant utilization against fixed retainer structures. |
| Outcome-Based Fee Structure Experimentation | North American private equity sponsors increasingly tie final payments to 12-month retention milestones rather than placement completion. |
Research Methodology
Desk research of SEC 10-K filings, EU regulatory submissions, and private equity placement databases preceded structured interviews with retained search partners, chief human resources officers at Fortune 500 enterprises, and private equity operating partners. Primary fieldwork with these stakeholders validated secondary findings on fee structure evolution and placement timeline compression. Bottom-up consultant productivity benchmarks triangulated against top-down market size estimates from industry association disclosures.
Variance decomposition across service type, industry focus, client scale, and geographic cluster shaped the analytical framework throughout the projection horizon. Segmentation modeling captured retained versus contingency engagement splits, technology versus industrial sector demand patterns, and multinational corporation versus financial sponsor client archetypes. CAGRs derived from consultant headcount expansion rates, average fee per placement trajectories, and regulatory mandate adoption curves.
Material uncertainties — private equity deployment cyclicality, generative AI tool adoption velocity, and EU AI Act enforcement stringency — sit outside the modeled envelope. Forecasts reflect assumptions about sustained exclusivity premium retention and algorithmic transparency compliance cost absorption. Recalibration cycles align with material shifts in regulatory mandate scope and financial sponsor liquidity conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Healthcare Finance Solutions Market
Financial Services
Trade Finance Market
Financial Services
Liquidation Service Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
ATM Management Service Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Pawn Shop Market
Financial Services
India Legal Services Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Treasury Management Market
Financial Services
Germany Factoring Services Market
Financial Services
ATM Software Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Reverse Factoring Market
Financial Services
Intermediary Service Market
Financial Services
Intellectual Property Rights and Royalty Management Market