
 ATM Managed Services Market | 2026-2036
ATM Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Managed Services Market Intelligence
Cloud-to-edge orchestration is narrowing the operational gap between centralized monitoring and field-level ATM uptime. Diebold Nixdorf Incorporated leverages its integrated hardware-software stack to dominate enterprise deployments across North America. NCR Atleos Corporation sustains competitive positioning through its extensive technician network and cash logistics integration. Fiserv Inc anchors its presence with cloud-native management platforms that streamline multi-vendor fleet oversight for mid-tier financial institutions.
ATM managed services encompass the full lifecycle operation of automated teller machines, including remote diagnostics, predictive maintenance, cash forecasting, and security patch management delivered under long-term service contracts. These services rely on ISO 8583 messaging protocols, encrypted VPN tunnels, and real-time telemetry feeds to maintain transaction availability above contractual thresholds. Monitoring and cash replenishment command the largest share of recurring revenue due to their labor-intensive nature and strict SLA penalties. Cloud-based deployment models represent the fastest-expanding segment as banks seek to reduce on-premise infrastructure capital. Security systems within the technology stack capture disproportionate margin pools given escalating PCI DSS compliance costs and fraud prevention investments.
The Federal Reserve's cash access policies, PCI Security Standards Council mandates, and state-level data privacy statutes collectively shape operational requirements for ATM service providers in the United States. India's RBI guidelines on cash management outsourcing and BIS certification standards for ATM hardware further tighten vendor qualification criteria. Stakeholders must weigh cloud migration timelines against residual latency constraints at rural and edge locations where hybrid architectures retain strategic value.
Market Dynamics
Cloud-to-edge orchestration is compressing the latency gap between centralized monitoring and field-level ATM uptime, forcing service providers to rearchitect their delivery models around hybrid infrastructure stacks.
Growth Catalysts
- PCI DSS 4.0 mandates:The updated Payment Card Industry Data Security Standard compels financial institutions to upgrade encryption protocols and real-time monitoring capabilities, expanding contract scopes for managed service providers.
- Community bank consolidation:Smaller institutions across the United States, India, and Brazil are outsourcing entire ATM fleets to reduce fixed operational overhead and access enterprise-grade security infrastructure.
- Predictive maintenance algorithms:Machine learning models analyzing ISO 8583 transaction telemetry now enable preemptive component replacement, cutting field service dispatches and extending hardware lifecycle value.
Market Restraints
- Semiconductor supply concentration:ATM controller boards and encryption modules depend on concentrated Asian foundry capacity, exposing service providers to lead-time volatility and inventory carrying costs.
- Last-mile cash logistics:Armored transport and vault cash management remain structurally expensive due to fuel, labor, and insurance cost escalations that resist automation.
- Rural connectivity limitations:Edge ATM locations in underserved geographies lack reliable fiber or 5G backhaul, constraining real-time monitoring SLA attainment and cloud-native feature deployment.
Strategic Opportunities
- India's ATM penetration gap:The country's ratio of machines per capita remains below emerging market benchmarks, creating whitespace for managed service contracts as RBI guidelines liberalize cash management outsourcing.
- Carbon-neutral cash logistics:Electric armored vehicle pilots and route optimization algorithms offer differentiation against incumbent diesel-based replenishment networks.
- API-first banking convergence:Managed service platforms integrating open banking interfaces can capture recurring revenue from fintechs deploying white-label ATM access points.
Industry Challenges
- ISO 20022 migration complexity:Financial institutions face multi-year timelines to replace legacy ISO 8583 messaging infrastructure, forcing service providers to maintain dual-protocol stacks and certification regimes.
- Cybersecurity talent scarcity:Qualified penetration testers and incident response specialists command premium compensation, compressing margins on security-heavy managed service tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Managed Services Market |
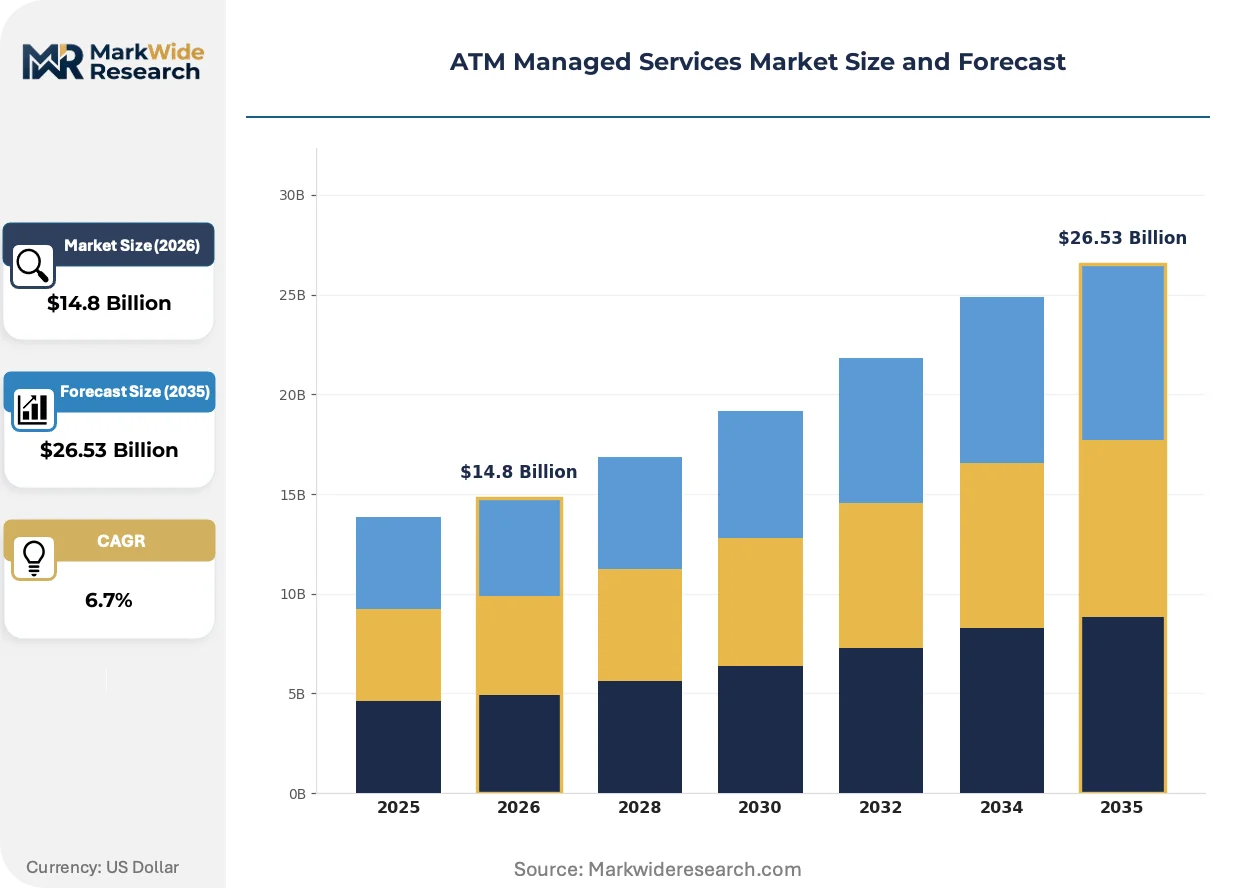
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Maintenance, Repair, Cash Replenishment Client Type: Banks, Credit Unions, Retailers, Payment Processors Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Software Solutions, Hardware Interfaces, Security Systems, Network Infrastructure |
| Companies Covered | AGS Transact Technologies Ltd, Fiserv Inc, Diebold Nixdorf Incorporated, Financial Software and Systems Pvt Ltd, Hitachi Payment Services Pvt Ltd, NCR Atleos Corporation, CMS Info Systems Ltd, Hyosung Corporation, Euronet Worldwide Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Managed Services Market Strategic Shifts & Innovations
Service delivery architectures are pivoting from reactive break-fix models toward predictive, software-defined operations that bind hardware uptime to algorithmic outcomes rather than technician dispatch metrics.
Edge-native telemetry platforms are digitizing ATM fleet management by embedding containerized analytics directly at the machine level. Regional banks in the United States and cooperative credit unions in Brazil are deploying these stacks fastest, driven by SLA penalty clauses that reward sub-minute fault detection. The shift is digitizing the traditional divide between remote monitoring capabilities and field service execution, collapsing response windows from hours to minutes.
India's RBI guidelines on cash management outsourcing are tightening vendor qualification criteria through mandatory BIS certification standards for ATM hardware and encrypted VPN architecture audits. The industrial consequence is a qualification bottleneck that favors incumbent service providers with existing certification infrastructure. Mid-tier banks are responding by consolidating vendor relationships rather than fragmenting across multiple regional specialists.
Community financial institutions are unbundling ATM operations from core banking procurement, separating hardware lifecycle management from software platform decisions. Credit unions in particular are disintermediating traditional bundled contracts, selecting best-of-breed managed service providers through competitive RFP processes. This pattern is most visible across the United States, where charter-specific regulatory requirements previously discouraged vendor switching.
ATM Managed Services Market Segmentation
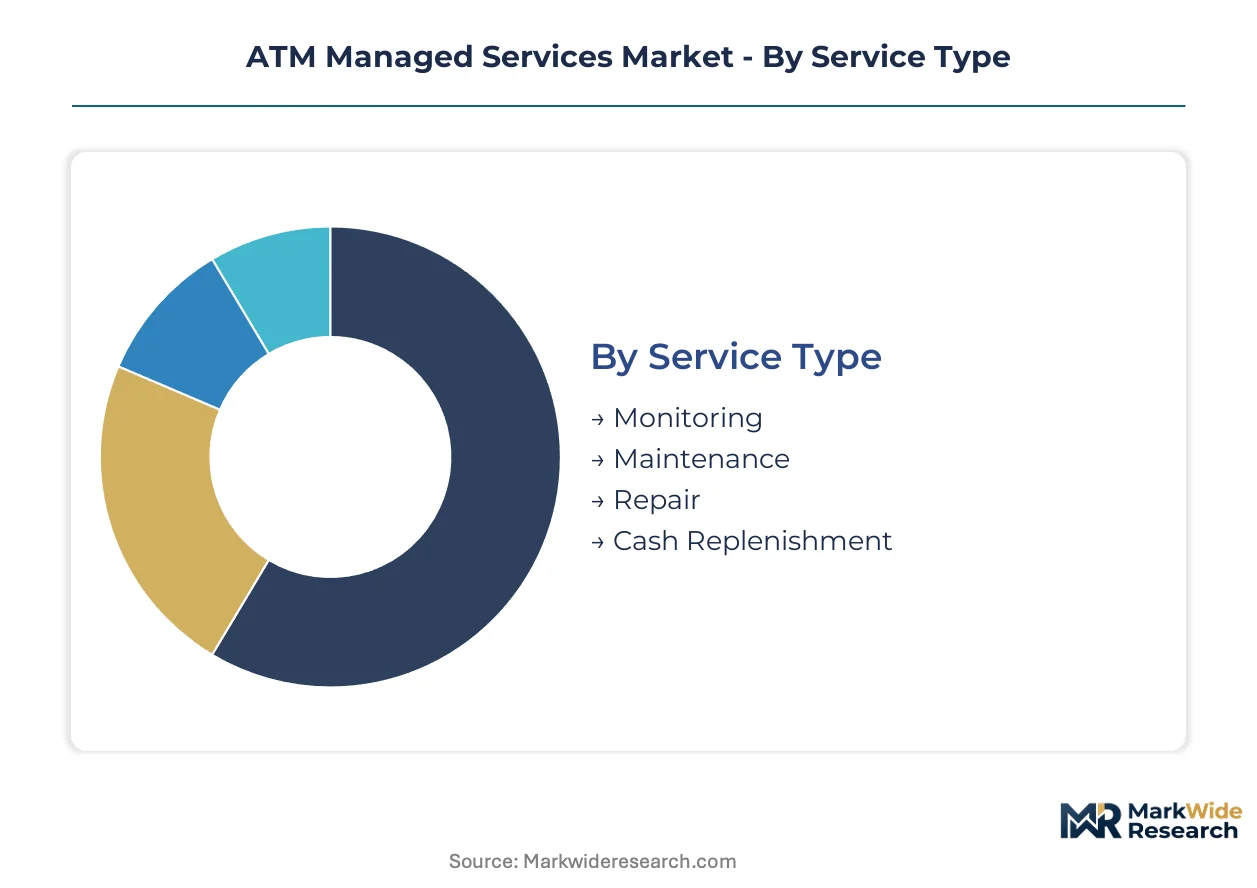
ATM managed services fragment across operational, technological, and client dimensions that determine contract scope, pricing architecture, and vendor selection criteria. Each segmentation axis carries distinct margin profiles and competitive dynamics that shape how service providers configure their delivery models.
Service Type:
Use-case spectrum spans reactive intervention to predictive orchestration, with labor intensity and SLA stringency defining commercial terms.
- Monitoring:Real-time telemetry ingestion via ISO 8583 messaging protocols enables fault detection before customer impact. United States community banks concentrate demand here as PCI DSS 4.0 mandates tighten uptime thresholds and penalty clauses.
- Maintenance:Scheduled preventive servicing and component lifecycle management preserve hardware availability. India's cooperative credit unions drive contract growth as RBI guidelines liberalize outsourcing while mandating BIS-certified technician networks.
- Repair:Break-fix dispatch for card readers, cash dispensers, and encryption modules. Brazil's regional banks favor tiered response SLAs balancing cost against rural accessibility constraints.
- Cash Replenishment:Vault cash forecasting, armored transport coordination, and settlement reconciliation. Fuel and insurance cost escalations compress margins despite high contract value.
Established volume favors Monitoring; emerging adoption favors Cash Replenishment as algorithmic forecasting displaces manual vault management.
Client Type:
Procurement sophistication varies sharply across institutional categories, dictating contract structure from transactional break-fix to integrated lifecycle partnerships.
- Banks:Multi-vendor fleet oversight with enterprise-grade security requirements and dedicated account management. Tier-1 institutions in the United States consolidate vendors to reduce procurement fragmentation.
- Credit Unions:Charter-specific compliance needs and member-service orientation drive preference for specialized providers with NCUA audit experience. Unbundling from core banking procurement accelerates competitive RFP activity.
- Retailers:White-label ATM deployment for customer foot traffic and ancillary revenue. India's convenience store chains represent expanding whitespace as cash access infrastructure penetrates tier-2 cities.
- Payment Processors:API-first integration requirements and fintech partnership ecosystems. Real-time settlement demands favor cloud-native service architectures with open banking interfaces.
Contract complexity concentrates with Banks; margin expansion opportunity sits with Payment Processors.
Deployment Model:
Infrastructure location determines latency, capital intensity, and feature accessibility across rural-to-urban location gradients.
- On-Premise:Legacy NOC architectures with dedicated hardware and private circuit backhaul. Mature installed base in Brazil's established urban corridors where fiber penetration supports centralized models.
- Cloud-Based:Containerized management platforms with elastic compute for predictive analytics. Expanding most quickly among United States mid-tier banks seeking to eliminate data center capital expenditure.
- Hybrid:Split architecture preserving sensitive transaction processing on-premise while offloading analytics to cloud. India's RBI-mandated encryption requirements sustain demand despite operational complexity.
- Edge Computing:Embedded telemetry and localized decisioning at the ATM itself. Rural connectivity limitations in Brazil's northern states and India's hinterland drive containerized edge deployment for sub-minute fault detection.
Hybrid configurations dominate current procurement; Edge Computing gains share fastest as 5G backhaul extends.
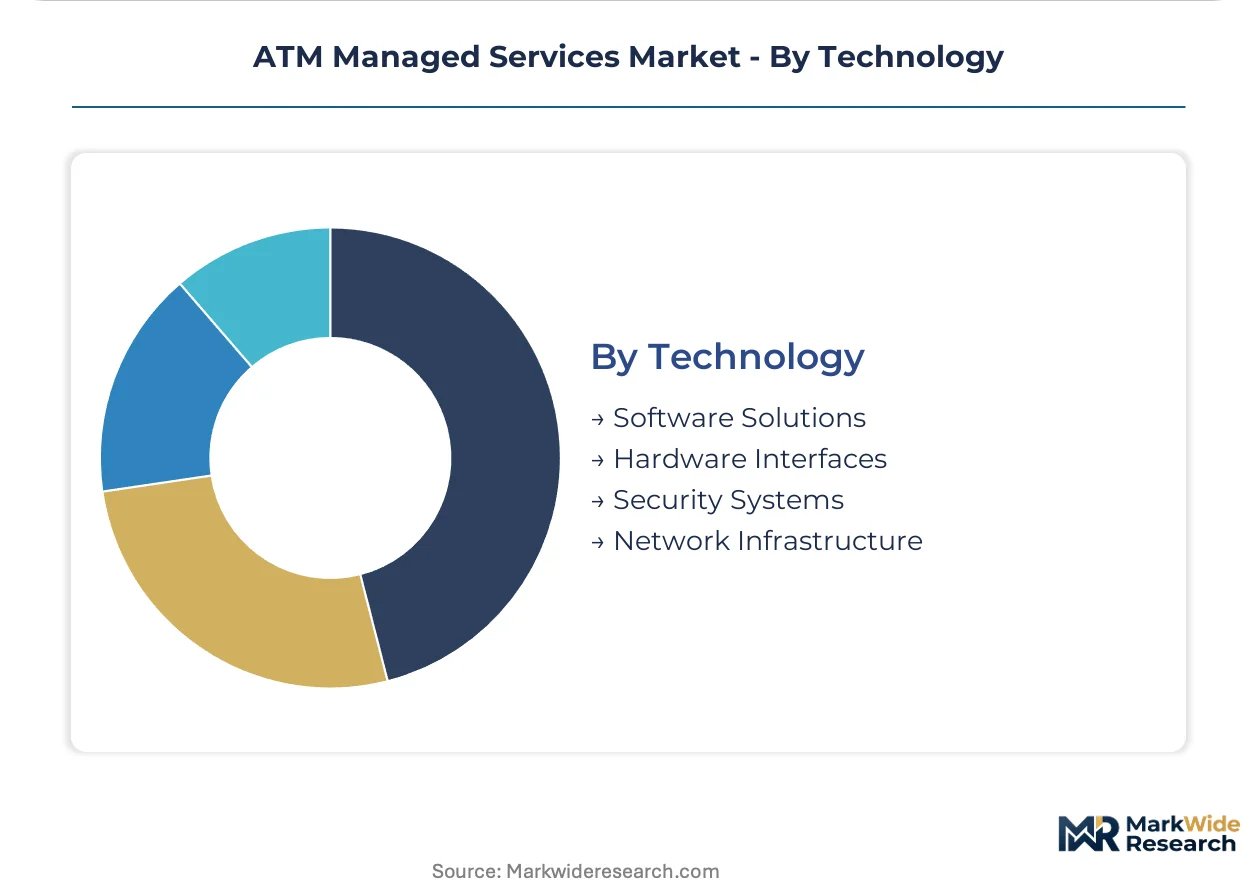
Technology:
Technology stack layers determine interoperability, security posture, and upgrade pathway flexibility across multi-vendor fleets.
- Software Solutions:Fleet management platforms, predictive maintenance algorithms, and cash forecasting engines. Machine learning model deployment concentrates in United States credit unions with SLA penalty structures rewarding preemptive intervention.
- Hardware Interfaces:Controller boards, card readers, and cash handling modules with embedded diagnostics. Semiconductor supply concentration in Asian foundries exposes inventory carrying costs and lead-time volatility.
- Security Systems:Encryption modules, PCI DSS compliance tooling, and fraud detection layers. Disproportionate margin capture given certification requirements and cybersecurity talent scarcity.
- Network Infrastructure:VPN tunnels, SD-WAN orchestration, and redundant backhaul provisioning. Rural coverage gaps in Brazil and India constrain real-time SLA attainment regardless of architecture sophistication.
Security Systems command premium pricing; Software Solutions scale fastest as API-first banking convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports ATM managed services expertise to banks across Southeast Asia and the Middle East, while the United States ships cloud-native management platforms to Canadian and Mexican financial institutions modernizing cross-border cash access infrastructure.
United States
Community banks and credit unions drive contract expansion as PCI DSS 4.0 mandates tighten encryption and monitoring requirements. The Federal Reserve's cash access policies shape operational standards for armored transport and vault cash management. Chicago and Dallas anchor major service delivery hubs where Diebold Nixdorf and NCR Atleos maintain technician networks for enterprise fleet oversight.
India
RBI guidelines liberalizing cash management outsourcing accelerate managed service adoption among cooperative credit unions and regional banks. BIS certification standards for ATM hardware and encrypted VPN architecture audits tighten vendor qualification criteria. Mumbai and Bengaluru concentrate fintech partnerships where white-label ATM deployments penetrate tier-2 cities through convenience store chains.
Brazil
Regional banks favor tiered response SLAs balancing cost against rural accessibility constraints in aging ATM fleet modernization. ANVISA-equivalent financial regulations and central bank cash logistics protocols govern armored transport licensing. São Paulo and Rio de Janeiro host established urban corridors with fiber penetration supporting centralized monitoring models, while northern states drive edge computing adoption for connectivity-limited locations.
Germany
Savings banks and cooperative financial institutions consolidate vendor relationships to reduce procurement fragmentation across multi-vendor fleets. BaFin supervision and GDPR data residency requirements sustain demand for hybrid cloud architectures with on-premise transaction processing. Frankfurt and Munich anchor compliance-heavy contracts where security system margins capture disproportionate value from PCI DSS certification costs.
United Kingdom
Open banking convergence and API-first fintech partnerships create recurring revenue opportunities for managed service platforms integrating white-label ATM access points. FCA conduct rules and PSR payment system oversight shape service-level agreements for real-time settlement. London's financial technology cluster drives cloud-native feature deployment, while regional banking networks in the Midlands and North England prioritize hybrid models for latency-sensitive rural locations.
ATM Managed Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where integrated hardware-software stacks anchor enterprise contracts and modular service providers capture mid-tier fragmentation. The vendor base separates into three strategic archetypes: full-stack incumbents with captive technician networks, cloud-native platform specialists, and regional cash logistics integrators. Dominant competitive moves include strategic partnerships with fintechs for white-label deployment and geographic expansion through RBI-certified technician networks in India.
Within the full-stack incumbent tier, Diebold Nixdorf Incorporated and NCR Atleos Corporation exemplify channel control through integrated hardware-software delivery and extensive field service infrastructure. Fiserv Inc occupies a position among cloud-native platform specialists, anchoring multi-vendor fleet oversight for mid-tier financial institutions through API-first architectures. These three companies represent the competitive poles around which regional specialists and logistics integrators orbit.
| Leading Market Players |
|---|
| AGS Transact Technologies Ltd |
| Fiserv Inc |
| Diebold Nixdorf Incorporated |
| Financial Software and Systems Pvt Ltd |
| Hitachi Payment Services Pvt Ltd |
| NCR Atleos Corporation |
| CMS Info Systems Ltd |
| Hyosung Corporation |
| Euronet Worldwide Inc |
| Others |
Cost & Logistics Intelligence
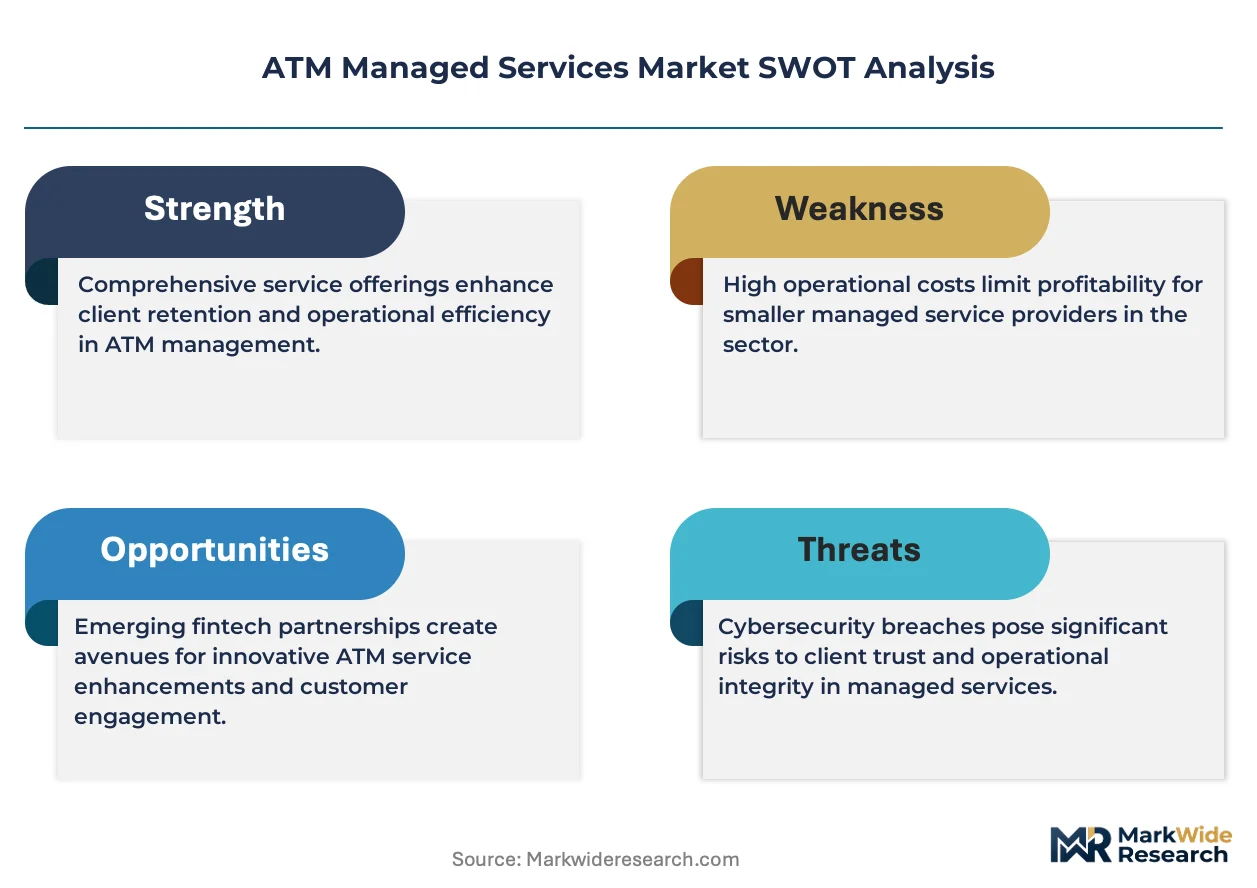
Semiconductor supply concentration in Asian foundries exposes ATM managed service providers to lead-time volatility that widens pricing spreads between premium-certified and standard-tier maintenance contracts while compressing margins on hardware-intensive engagements. This single-source dependency for controller boards and encryption modules forces buyers to accept longer procurement cycles or pay expedite premiums, reshaping contract structures toward software-heavy service bundles that reduce silicon exposure.
Pricing Analysis
Current-generation edge-native telemetry platforms command substantial premiums over prior-generation centralized NOC architectures and legacy break-fix models still prevalent in Brazil's northern states. Three-tier pricing structure across premium, standard, and economy levels separates PCI DSS 4.0-compliant predictive maintenance bundles from basic monitoring-only contracts and reactive repair dispatch. Pricing pressure stems from cybersecurity talent scarcity, where qualified penetration testers command premium compensation that compresses margins on security-heavy managed service tiers. Community banks and credit unions exhibit highest price sensitivity, while tier-1 institutions prioritize SLA stringency over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships with Taiwanese and South Korean semiconductor foundries, straining working capital for hardware procurement. Controller boards, encryption modules, and cash handling mechanisms draw from concentrated manufacturing capacity in Taiwan, South Korea, and mainland China. Single-source vulnerability for ATM-specific chipsets creates inventory carrying cost burdens that cascade into contract pricing. Distribution runs through authorized distributor networks and direct OEM relationships, with regional logistics integrators in India and Brazil managing last-mile field service inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cybersecurity specialists and BIS-certified technician networks constitute scarce assets that constrain service expansion velocity and inflate compensation costs across competitive tiers. This capability bottleneck favors incumbents with established certification infrastructure while raising barriers for mid-tier challengers.
For Market Incumbents: Entrench market position by deepening captive technician networks in India to exploit RBI-mandated certification requirements that disqualify unqualified competitors. Consolidate vendor relationships with community banks undergoing procurement unbundling from core banking platforms. Prioritize ISO 20022 migration readiness to capture multi-protocol maintenance contracts during the ISO 8583 transition window. For New Entrants and Emerging Players: India's tier-2 city convenience store chains represent underpenetrated whitespace where white-label ATM deployments for fintech partnerships bypass established banking procurement channels. Target credit union competitive RFP processes in the United States where charter-specific compliance experience creates differentiation against generalist providers. Lead with API-first platform architectures that integrate open banking interfaces for payment processor segments seeking modular service components. For Investors and Strategic Acquirers: Cloud-native platform specialists with multi-vendor fleet orchestration capabilities present attractive acquisition targets as mid-tier banks accelerate SaaS migration away from on-premise infrastructure. Long-term viability hinges on hybrid architecture expertise spanning edge computing deployment and centralized analytics across the projection horizon. Monitor 5G rural backhaul extension timelines as inflection indicators for edge-native service model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| RBI-Certified Technician Network Expansion | Mandatory BIS certification creates qualification moats against unqualified regional competitors in India. |
| PCI DSS 4.0 Compliance Platform Development | Encryption protocol upgrades expand contract scopes for security-heavy managed service tiers. |
| Edge-Native Telemetry Deployment | Containerized analytics at ATM level collapses fault detection windows below SLA penalty thresholds. |
| Carbon-Neutral Cash Logistics Pilot | Electric armored vehicle differentiation addresses fuel cost escalations and ESG procurement criteria. |
| API-First Fintech Integration | Open banking interfaces capture recurring revenue from white-label ATM access point deployments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, RBI regulatory circulars, and PCI Security Standards Council documentation to establish market sizing and competitive positioning. Interviews with ATM fleet operations directors, cybersecurity compliance officers, armored transport logistics managers, and cooperative credit union procurement leads provided operational validation. Bottom-up triangulation across service contract value analysis combined with top-down reconciliation against central bank cash access statistics and industry association membership data.
Forecast inputs incorporate service type segmentation by monitoring intensity, deployment model migration trajectories, and client type procurement sophistication across the analysis window. Modeled dimensions span reactive-to-predictive maintenance spectrum, cloud-native versus hybrid infrastructure adoption, and geographic regulatory cluster differentiation. CAGRs derive from contract renewal rate analysis, fleet modernization cycle timing, and technology substitution elasticity for edge computing architectures. Cash logistics cost escalations and semiconductor supply lead-time volatility inform margin compression assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cloud-native platform specialists or accelerated 5G rural deployment by telecommunications providers would shift outcomes. Macroeconomic deviation affecting community bank consolidation velocity, regulatory changes to PCI DSS enforcement timelines, or breakthrough edge AI capabilities reducing technician dispatch requirements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Pawn Shop Market
Financial Services
India Security Brokerage Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Global Temporary Labor Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Debt Collection Software and Service Market
Financial Services
E-Invoicing Market
Financial Services
Mobile Notary Service Market
Financial Services
Middle Office Outsourcing Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Intermediary Service Market
Financial Services
Commodity Trade Finance Market
Financial Services
Online Investment Platform Market
Financial Services
White Glove Services Market
Financial Services
Capital Restructuring Services Market