
 BFSI Contact Center Analytics Market | 2026-2036
BFSI Contact Center Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
BFSI Contact Center Analytics Market Intelligence
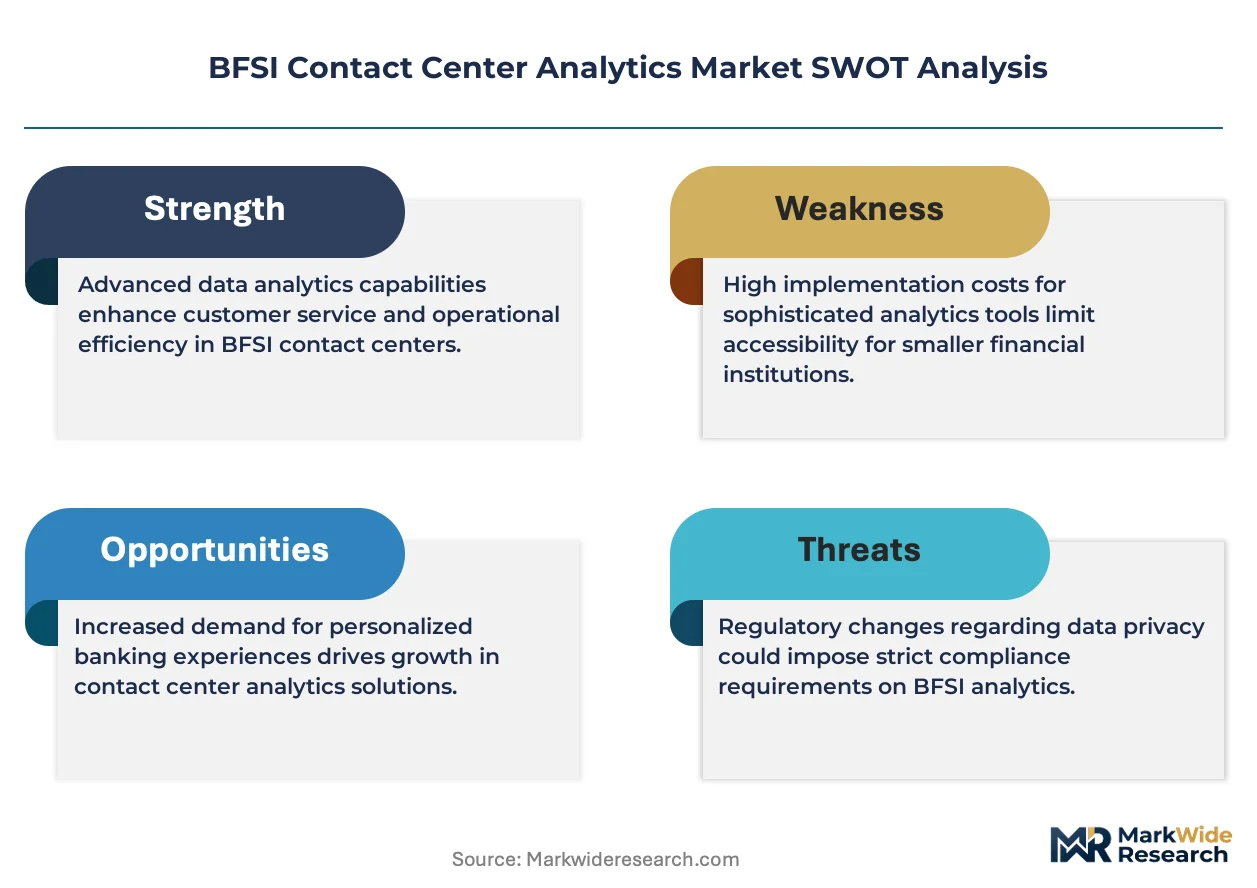
Cloud distribution channels is tilting toward hybrid architectures as BFSI institutions balance data sovereignty with elasticity. NICE Ltd dominates real-time speech analytics for compliance monitoring in North American banking. Genesys Telecommunications Laboratories Inc extends its cloud-native platform through API-first integrations with core banking systems. SAP SE anchors enterprise-grade deployments by embedding contact center analytics within its broader financial services cloud suite.
BFSI Contact Center Analytics encompasses software systems that capture, process, and interpret voice, text, and behavioral data from customer interactions across banking, insurance, and investment services channels, typically operating at sub-second latency for real-time agent guidance and post-interaction quality scoring. Speech analytics solutions lead current revenue contribution as regulatory transcription requirements expand, while predictive analytics segments accelerate fastest through AI-driven churn and fraud propensity models. Cloud-based deployment captures growing share among mid-tier banks shedding capital-intensive on-premises estates, though hybrid configurations retain primacy at systemic institutions with multi-jurisdictional data residency obligations.
US banking regulators including the OCC and CFPB mandate call recording retention and supervisory access, directly expanding analytics infrastructure scope for compliance documentation and dispute reconstruction. The EU AI Act and GDPR impose algorithmic transparency and automated decision-making constraints on predictive scoring deployed in European insurance contact centers. Stakeholders must evaluate how emerging sovereign AI requirements will fragment cloud deployment strategies across jurisdictional boundaries.
Market Dynamics
Cloud migration mandates from US banking regulators are forcing systemic institutions to overlay analytics on legacy contact center estates while preserving real-time compliance monitoring capabilities.
Growth Catalysts
- Speech Analytics:Regulatory transcription requirements from the OCC and CFPB are expanding infrastructure scope for call recording retention and dispute reconstruction in retail banking divisions.
- Real-time Agent Guidance:Sub-second latency systems are capturing behavioral data from customer interactions to enable immediate coaching during live calls.
- AI-driven Predictive Models:Churn and fraud propensity scoring is accelerating deployment of advanced analytics in insurance contact centers.
Market Restraints
- Data Residency Complexity:Multi-jurisdictional obligations at systemic institutions are fragmenting cloud deployment strategies and extending procurement cycles.
- Legacy Integration Costs:Capital-intensive on-premises estates at Tier 1 banks require expensive overlay architectures before analytics platforms can operate.
- Algorithmic Transparency Constraints:The EU AI Act is imposing automated decision-making limitations on predictive scoring deployed in European insurance operations.
Strategic Opportunities
- Mid-tier Banking Cloud Migration:Mid-tier banks shedding capital-intensive estates represent expanding addressable market for cloud-native analytics platforms.
- Hybrid Architecture Services:Balancing data sovereignty with elasticity is creating demand for configuration expertise across US and European banking operations.
- API-first Core Banking Integration:Cloud-native platforms embedding directly into financial services infrastructure are opening new deployment pathways.
Industry Challenges
- Specialized Talent Scarcity:Shortages of data scientists with domain expertise in both contact center operations and BFSI compliance are constraining implementation velocity.
- Cross-system Integration Complexity:Synchronizing real-time analytics with core banking databases and CRM platforms requires extensive custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BFSI Contact Center Analytics Market |
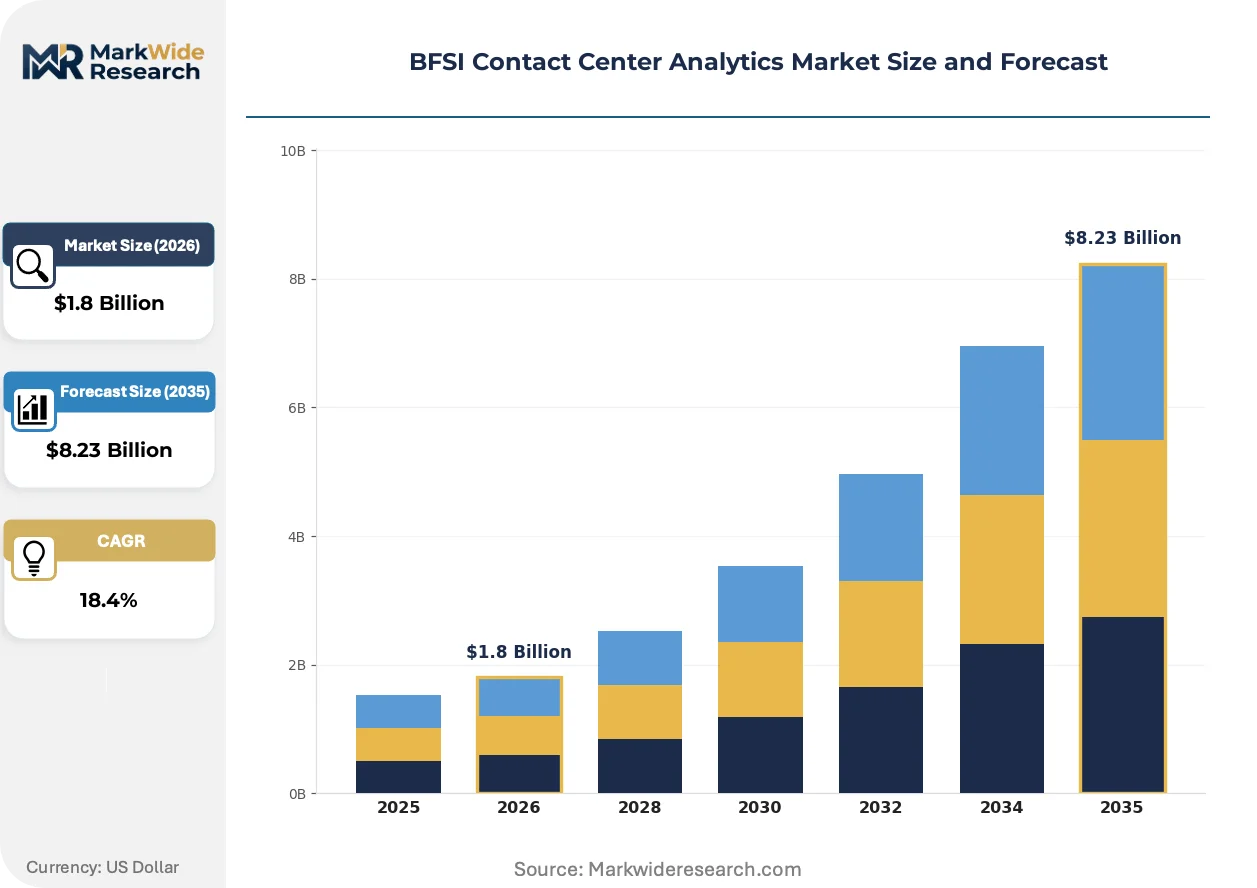
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Analytics, Predictive Analytics, Text Analytics, Descriptive Analytics Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Commercial Banks, Investment Firms, Insurance Companies, Payment Processors Solution: Customer Experience Management, Quality Management, Workforce Optimization, Performance Management |
| Companies Covered | Oracle Corp, Verint Systems Inc, NICE Ltd, Mitel Networks Corp, 8x8 Inc, Genesys Telecommunications Laboratories Inc, SAP SE, Enghouse Systems Ltd, Cisco Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BFSI Contact Center Analytics Market Strategic Shifts & Innovations
Real-time processing architectures and regulatory data mandates are compressing deployment timelines while expanding the functional scope of analytics platforms in banking and insurance channels.
Conversational AI platforms are virtualizing traditional agent scripting and quality assurance workflows. Tier 1 banks are deploying these systems across retail divisions to automate compliance documentation during live customer interactions. This technology is virtualizing the role of human supervisors in post-call review processes.
The EU AI Act is imposing algorithmic transparency requirements on automated decision-making in European insurance contact centers. Insurers must now maintain explainability logs for churn prediction models used during policy renewal conversations. French and German carriers are restructuring their analytics stacks to accommodate audit trails for CNIL and BfDI supervisory access.
Subscription-based platform access is displacing perpetual license models among mid-tier banks seeking to shed capital expenditure commitments. Channel partners are repositioning around managed service offerings that bundle implementation, training, and regulatory update management. This shift is most visible in US regional banking networks modernizing complaint resolution infrastructure.
BFSI Contact Center Analytics Market Segmentation
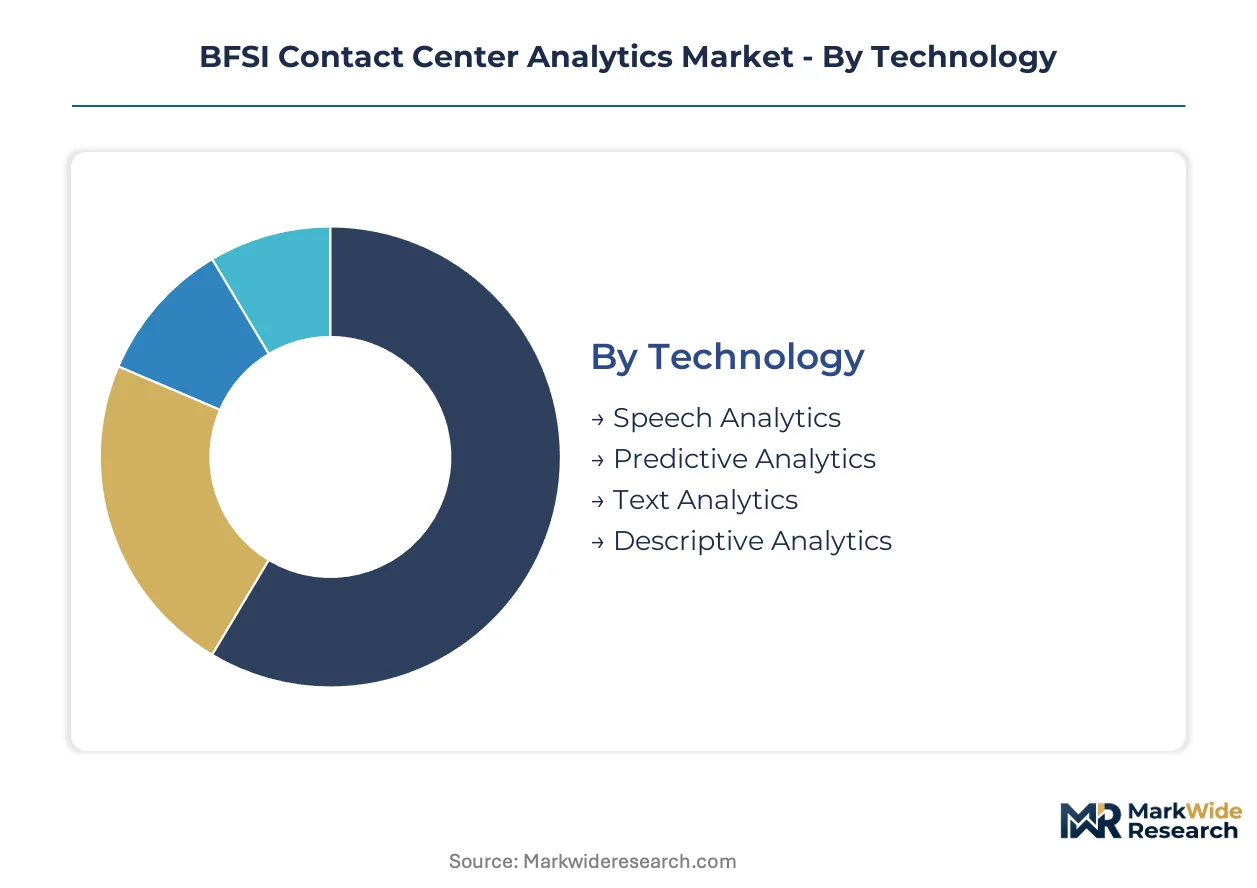
Technology choices in BFSI contact center analytics determine latency thresholds for real-time agent guidance and regulatory compliance architectures. Deployment models reflect institutional risk tolerance for data sovereignty versus operational elasticity. End-user segmentation tracks divergent priorities between retail banking complaint resolution and investment services surveillance requirements.
Technology:
Mature transcription engines anchor current infrastructure spending while emerging AI inference layers reshape competitive differentiation.
- Speech Analytics:Real-time phonetic indexing and emotion detection engines process voice streams at sub-second latency for live compliance flagging. US retail banking divisions deploy these systems to satisfy OCC call recording mandates and accelerate dispute reconstruction workflows.
- Predictive Analytics:Machine learning models score churn probability and fraud propensity from interaction metadata and account history. European insurance carriers are restructuring these stacks to accommodate EU AI Act explainability requirements for automated renewal pricing.
- Text Analytics:Natural language processing pipelines extract intent and sentiment from chat transcripts and email queues.
- Descriptive Analytics:Historical aggregation dashboards visualize agent performance distributions and channel volume patterns.
Speech analytics handles the majority of throughput; predictive analytics is the fastest mover on share.
Deployment:
Cost tier stratification separates capital-intensive legacy estates from subscription-native mid-tier migrations.
- Cloud-Based:Elastic compute architectures eliminate upfront infrastructure commitments and accelerate feature deployment cycles. Mid-tier US regional banks are shedding on-premises estates to redirect capital toward core banking modernization.
- Hybrid:Split configurations retain sensitive voice data on sovereign infrastructure while pushing analytics workloads to elastic cloud tiers. Systemic institutions with multi-jurisdictional operations deploy these architectures to satisfy divergent regulatory residency requirements.
- On-Premises:Dedicated hardware estates persist at Tier 1 banks with entrenched security protocols and custom integration layers.
- SaaS:Fully managed platform access bundles implementation, training, and regulatory update management into recurring contracts.
Hybrid configurations dominate at systemic institutions; cloud-based deployment is expanding most quickly among mid-tier banks.
End User:
Application intensity varies sharply between high-volume retail operations and surveillance-heavy investment services.
- Commercial Banks:Retail divisions drive analytics procurement for complaint resolution automation and cross-selling optimization. Branch networks and contact centers generate the highest interaction volumes requiring real-time quality scoring.
- Insurance Companies:Policy service centers deploy predictive models for renewal retention and claims fraud detection. European carriers face EU AI Act constraints on automated decision-making during customer conversations.
- Investment Firms:Trading floor surveillance and client advisory documentation require specialized compliance transcription with audit trail integrity.
- Payment Processors:Dispute resolution centers leverage interaction analytics to reconstruct transaction contexts and accelerate chargeback investigations.
Commercial banks absorb the largest deployment base; insurance companies are climbing the fastest on analytics intensity.
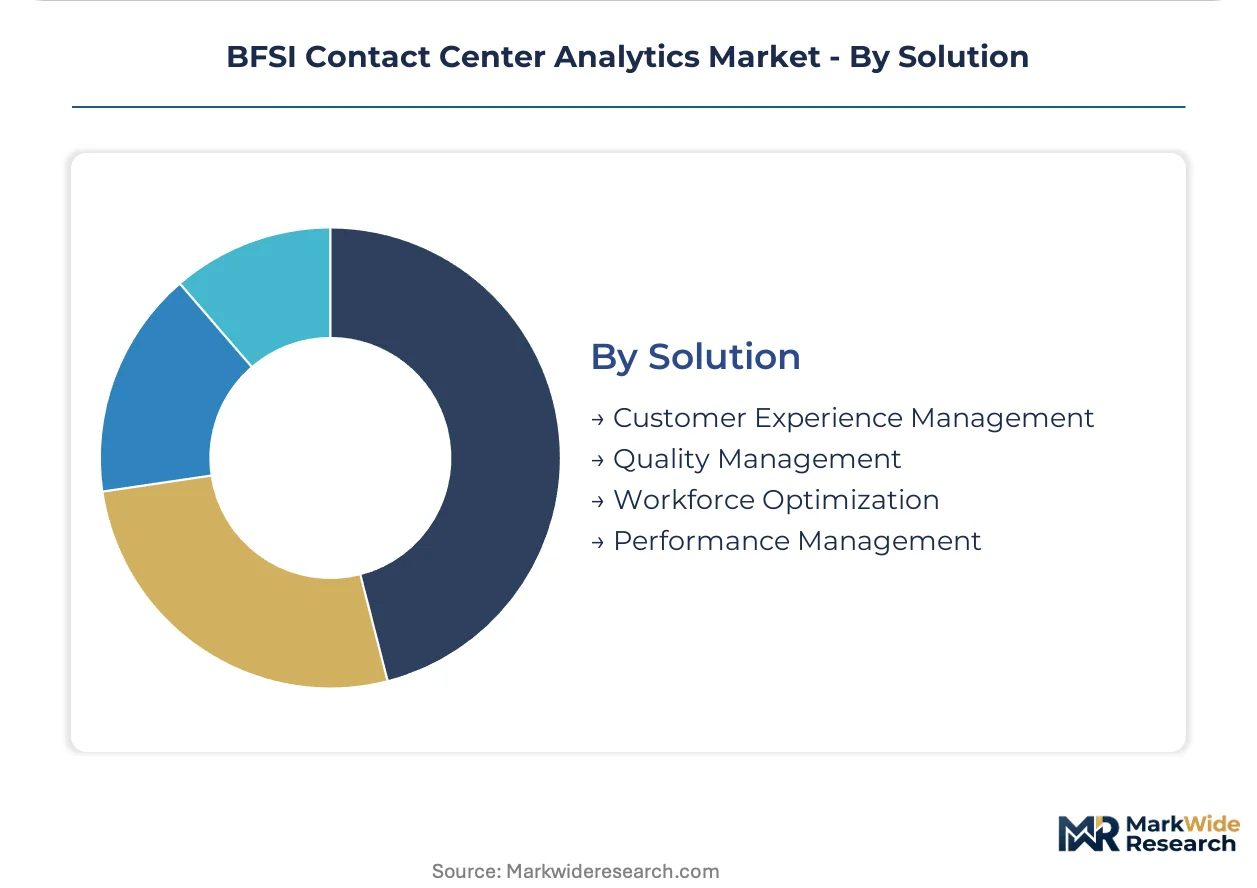
Solution:
Customer-facing functionality commands premium pricing while back-office optimization faces procurement compression.
- Customer Experience Management:Journey orchestration platforms unify voice, chat, and digital touchpoints into single interaction histories. Real-time sentiment triggers enable agent guidance and supervisor escalation during live conversations.
- Quality Management:Automated scoring engines replace manual call sampling with 100% interaction evaluation against compliance and service standards.
- Workforce Optimization:Forecasting and scheduling modules align agent capacity with predicted contact volumes across banking and insurance operations.
- Performance Management:Individual and team dashboards track KPI achievement against regulatory service level agreements and revenue targets.
Customer experience management captures the dominant share of solution spending; quality management is gaining share fastest through regulatory transcription mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in US banking operations where regulatory mandates accelerate analytics procurement, while European carriers absorb compliance cost premiums under algorithmic transparency rules. This asymmetry shapes deployment timelines and vendor selection criteria across major markets.
United States
Tier 1 banks operate the largest legacy contact center estates requiring analytics overlay, with retail divisions driving modernization budgets. OCC and CFPB call recording retention mandates directly expand infrastructure scope for dispute reconstruction. New York and Charlotte banking clusters deploy real-time speech analytics at sub-second latency for live compliance flagging.
Germany
Systemic insurers restructure predictive scoring stacks to accommodate BfDI audit trail requirements for automated renewal pricing. The EU AI Act imposes explainability constraints on churn models used during policy conversations. Frankfurt and Munich carrier headquarters anchor hybrid cloud configurations balancing data sovereignty with elastic compute.
United Kingdom
Commercial banking networks prioritize complaint resolution automation following FCA conduct supervision tightening. GDPR residency obligations fragment deployment architectures for institutions with EU-UK dual operations. London's fintech corridor incubates API-first analytics integrations with challenger banking platforms.
France
Insurance contact centers face CNIL supervisory access requirements for algorithmic decision logs in customer retention workflows. GDPR automated decision-making constraints limit predictive scoring deployment during live policy conversations. Parisian carrier operations lead restructuring efforts for EU AI Act compliance documentation.
India
Mid-tier banks accelerate cloud-native analytics adoption to shed capital-intensive on-premises estates. RBI guidelines on customer grievance redressal expand quality management infrastructure requirements. Mumbai and Bangalore financial services clusters drive subscription-based platform procurement for retail banking modernization.
BFSI Contact Center Analytics Market Key Industry Players
Specialized contact center vendors and enterprise software conglomerates split the market between domain-specific functionality and platform breadth. Consolidation pressures favor players with pre-built banking integrations over point-solution specialists. Three archetypes dominate: real-time speech analytics specialists, cloud-native platform providers, and enterprise suite embedders. Competitive moves center on API-first core banking partnerships and managed service bundling for mid-tier institutions.
Within the real-time compliance tier, NICE Ltd and Verint Systems Inc occupy positions anchored by phonetic indexing engines. Genesys Telecommunications Laboratories Inc exemplifies the cloud-native archetype through elastic platform architectures. SAP SE represents enterprise suite embedders by anchoring analytics within broader financial services cloud deployments.
| Leading Market Players |
|---|
| Oracle Corp |
| Verint Systems Inc |
| NICE Ltd |
| Mitel Networks Corp |
| 8x8 Inc |
| Genesys Telecommunications Laboratories Inc |
| SAP SE |
| Enghouse Systems Ltd |
| Cisco Systems Inc |
| Others |
Cost & Logistics Intelligence
Bangalore's analytics engineering clusters anchor global capacity for real-time speech processing engines, with elasticity in cloud-native talent pools translating directly into pricing leverage for subscription-based platform vendors targeting mid-tier banking migrations.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order deployments at systemic institutions. Subscription-based pricing dominates as mid-tier banks shed perpetual license commitments, while hybrid architecture premiums reflect data sovereignty engineering costs. Price differentiation rests on compliance certification depth and API integration complexity. Pricing pressure intensifies in the mid-market as cloud-native vendors compete for regional bank modernization budgets. Tier 1 institutions show lowest price sensitivity due to regulatory mandate urgency; mid-tier banks exhibit highest sensitivity, prioritizing opex reduction.
Supply Chain Analysis
Export-control regimes restricting advanced AI chip flows to Chinese hyperscalers are fragmenting compute infrastructure sourcing for analytics platforms. Supply concentrates in Taiwan for specialized inference processors, the United States for cloud orchestration software, and Ireland for EU data residency hosting. Component dependencies include NVIDIA GPU clusters, phonetic indexing libraries, and core banking API middleware. Single-source vulnerability in specialized AI accelerators threatens deployment timelines. Distribution runs through direct enterprise sales teams and channel partners bundling managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as regulatory divergence between US and EU jurisdictions creates specialized compliance niches that favor domain-specific vendors over generalized platforms.
For Market Incumbents: Build switching-cost moats through deeper core banking system integrations that embed analytics workflows into agent desktop environments. Deepen API-first partnerships with tier 1 core banking vendors to preempt displacement by cloud-native challengers. Invest in sovereign cloud certifications for EU data residency requirements before mid-tier competitors achieve compliance parity.
For New Entrants and Emerging Players: Build out white-space positions in mid-tier US regional banks shedding on-premises estates, where incumbent overlay pricing creates displacement openings. Target insurance carriers in Germany and France facing EU AI Act restructuring deadlines with explainability-native predictive analytics. Lead with managed service bundling that absorbs implementation risk and regulatory update management.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platforms with pre-built banking integrations over legacy on-premises specialists facing terminal decline. Long-term viability hinges on API ecosystem depth and multi-jurisdictional compliance coverage. Watch for inflection when tier 1 banks accelerate legacy estate retirement timelines beyond current hybrid overlay strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core Banking Integration | Embeds analytics directly into agent workflows at NICE Ltd and Genesys deployments. |
| Hybrid Cloud Certification Program | Enables EU data residency compliance for BfDI and CNIL supervisory access requirements. |
| Managed Service Bundling | Captures mid-tier banks seeking to convert capital expenditure into operational spending. |
| Real-Time Inference Optimization | Achieves sub-second latency for OCC-mandated live compliance flagging in retail banking. |
| Explainability-Native Model Development | Restructures predictive stacks for EU AI Act algorithmic transparency in insurance renewals. |
Research Approach
A spread of perspectives from contact center operations directors, regulatory compliance officers, cloud procurement leads, and core banking integration specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, RBI guideline releases, EU regulatory registers, and vendor earnings disclosures. Bottom-up sizing of deployment volumes triangulated against top-down banking IT spending benchmarks.
Demand-supply balance modeling segmented the market by technology layer, deployment architecture, institution tier, and jurisdictional regulatory cluster across the analysis window. CAGRs derived from slope-consistent growth trajectories anchored to observable procurement cycle lengths. Forecast inputs included cloud migration velocity at mid-tier banks and regulatory transcription mandate expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by hyperscaler-backed entrants would shift outcomes. Material shifts in sovereign AI requirements or cross-border data flow restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Currency Exchange Software Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
China Supply Chain Financing Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Broker Affiliate Programs Market
Financial Services
US Online Trading Platform Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Debt Collection Software and Service Market
Financial Services
United States Payroll Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Banknote Counters Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
Capital Restructuring Services Market
Financial Services
India Payroll Services Market
Financial Services
E-KYC Market