
 Italy Gift Card and Incentive Card Market | 2026-2036
Italy Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Gift Card and Incentive Card Market Foresight
Corporate clients are gaining share over retail consumers as the primary buyer archetype and is reorganizing procurement patterns across the Italy gift card and incentive card landscape. Edenred leverages its captive B2B network to anchor employee benefits distribution nationwide. PostePay competes through prepaid infrastructure integrated with Italy's postal banking system. Nexi Payments differentiates via POS-terminal ubiquity that captures in-store redemption flows.
Gift cards and incentive cards are prepaid stored-value instruments issued in physical or electronic form, typically encoded with magnetic stripes, EMV chips, or tokenized credentials redeemable at affiliated merchant networks; they function as non-cash payment surrogates for consumer gifting, employee recognition, and promotional loyalty mechanics. The digital card segment leads volume acceleration as open banking APIs enable real-time issuance and wallet integration, while reloadable instruments sustain higher per-account lifetime value through recurring corporate wellness budgets. Physical cards retain structural importance in retail outlet distribution where tactile gifting conventions persist, though margin pools increasingly migrate toward mobile app-delivered digital credentials.
Banca d'Italia supervises e-money licensing and capital reserve requirements for prepaid issuers, while the Italian Data Protection Authority enforces GDPR-mandated tokenization standards for digital cardholder data. PSD2 strong customer authentication rules shape product design by mandating biometric or two-factor verification for reloadable account access. Stakeholders must monitor forthcoming EU Digital Identity wallet interoperability requirements that could redefine competitive positioning across third-party platform distribution.
Market Dynamics
PSD2 strong customer authentication mandates are restructuring issuance protocols across Italy's prepaid card ecosystem, forcing issuers to retool legacy systems for biometric verification and real-time API connectivity.
Growth Catalysts
- Open Banking APIs:Real-time wallet integration enables instant digital card provisioning. Corporate HR departments leverage these interfaces for automated wellness program disbursements.
- GDPR Tokenization Standards:The Italian Data Protection Authority's encryption mandates create trust infrastructure that accelerates B2B adoption of digital credentials over physical instruments.
- Milan Financial Services Corridor:Concentrated fintech development in Lombardy generates specialized talent pools and vendor ecosystems for card program management.
Market Restraints
- EMV Chip Supply Concentration:Physical card manufacturing depends on semiconductor foundries concentrated in East Asia, exposing issuers to logistics volatility.
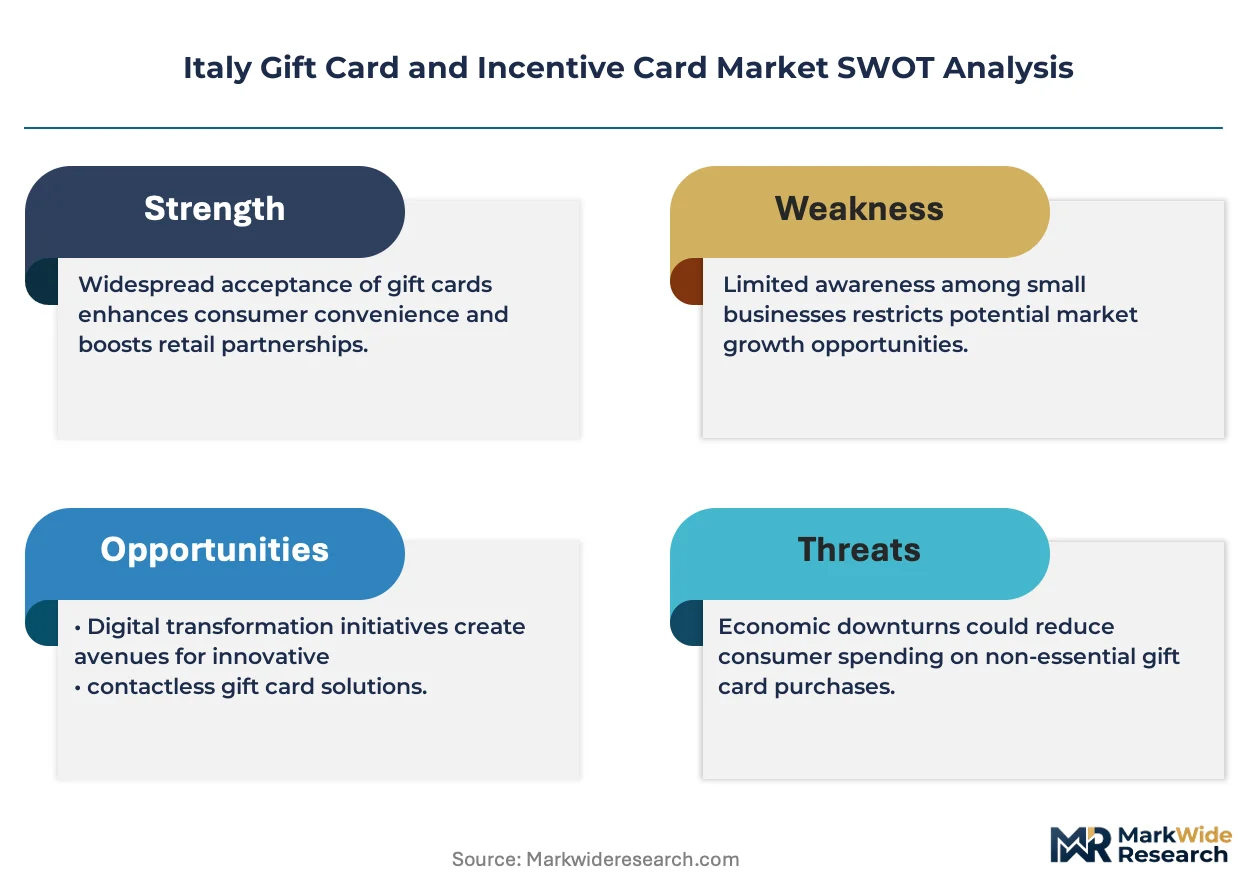
- PSD2 Compliance Costs:Biometric authentication infrastructure requires substantial capital expenditure that squeezes margin pools for mid-tier prepaid program managers.
- Interchange Fee Compression:EU-wide caps on merchant service charges limit revenue per transaction for reloadable incentive card products.
Strategic Opportunities
- Southern Italy SME Penetration:Corporate incentive card adoption remains underdeveloped in Campania and Sicily, creating whitespace for regional distribution partnerships.
- EU Digital Identity Wallet Convergence:Upcoming interoperability standards will enable prepaid credentials to function as government-recognized payment instruments.
- Mobile-First Wellness Platforms:Integration of gift card APIs with telehealth and fitness applications opens new redemption channels outside traditional retail networks.
Industry Challenges
- Legacy Core Banking Integration:Prepaid issuers face technical debt when connecting real-time card management systems to batch-oriented mainframe infrastructure at partner banks.
- SCA Friction in Low-Value Reloads:PSD2 authentication requirements create checkout abandonment for sub-threshold transactions that previously operated on streamlined rails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Gift Card and Incentive Card Market |
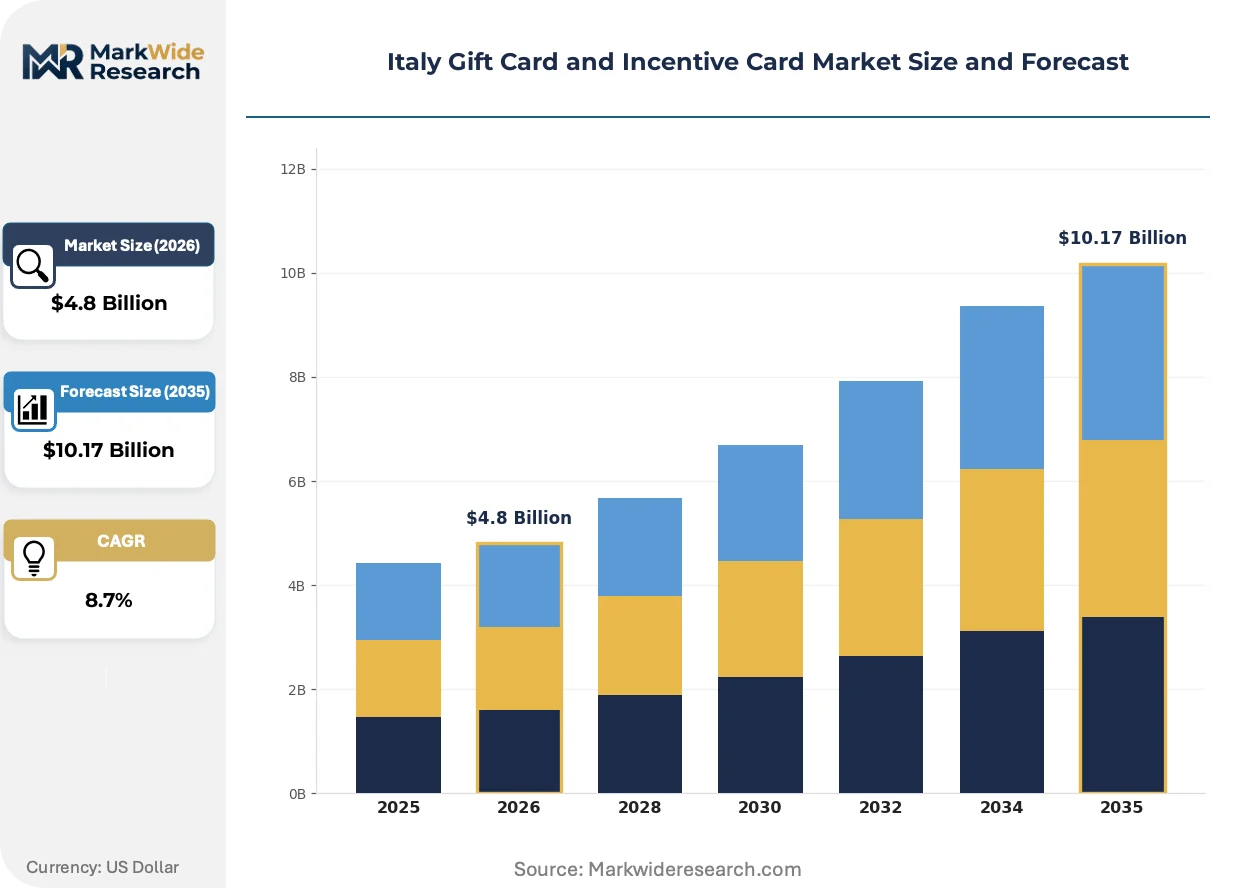
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Physical Card, Digital Card, Reloadable Card, Non-reloadable Card End User: Retail Consumers, Corporate Clients, Non-profits, Educational Institutions Distribution Channel: Online Stores, Retail Outlets, Third-party Platforms, Mobile Apps Usage Occasion: Gifting, Employee Rewards, Loyalty Programs, Promotional Campaigns |
| Companies Covered | Edenred, Esselunga, Epipoli Group, Carrefour Group, Conad, Nexi Payments, Amazon.com, Auchan Holding, PostePay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Gift Card and Incentive Card Market Shifts & Advancements
Tokenized credential delivery is compressing issuance timelines from days to seconds, while regulatory mandates around digital identity reshape competitive requirements for program infrastructure.
Tokenized mobile wallet credentials are supplanting magnetic-stripe physical cards as the default issuance format for corporate incentive programs. Large employers in Lombardy and Lazio now demand same-day digital provisioning for employee recognition disbursements. This shift compresses working capital cycles for program managers while eliminating plastic production and distribution overhead.
Italy's central bank enforces e-money licensing requirements that mandate segregated capital reserves and audit transparency for prepaid issuers. Banca d'Italia's supervision framework elevates compliance barriers that favor established financial institutions over technology entrants. Smaller fintech card providers respond by pursuing partnership models rather than direct licensing.
Procurement centralization among large Italian corporates is consolidating vendor relationships for employee benefits administration. Single-source contracts with integrated wellness platform providers are displacing fragmented multi-vendor arrangements. This concentration is most visible among multinational headquarters in Milan's Porta Nuova district, where procurement teams prioritize API interoperability over standalone card features.
Italy Gift Card and Incentive Card Market Segmentation
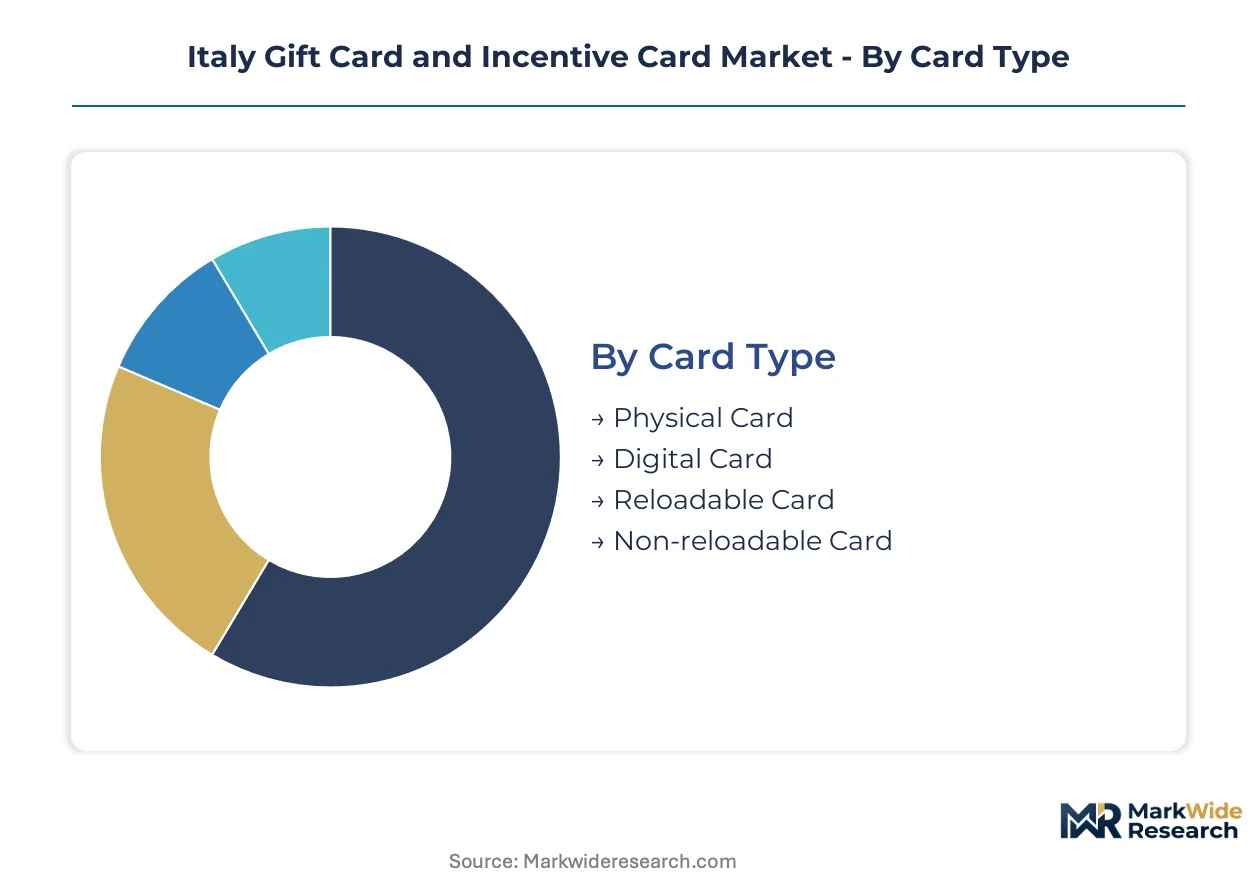
Segmentation reveals how substitution pressures from mobile wallets and real-time payment rails are fragmenting demand across traditional card formats. Issuers must align product architecture with specific buyer workflows rather than pursuing undifferentiated distribution.
Card Type:
Digital credentials face the strongest substitution threat from native banking apps, while physical and reloadable formats retain defensible positions through regulatory requirements and corporate procurement conventions.
- Physical Card:EMV-chip and magnetic-stripe instruments dominate retail gifting occasions where tactile presentation remains culturally significant. Demand concentrates in Rome's department store corridors and Milan's luxury retail clusters, constrained by semiconductor supply volatility from East Asian foundries.
- Digital Card:Tokenized credentials delivered via API enable instant issuance for corporate wellness disbursements. Lombardy-based HR departments drive adoption through open banking integration, though PSD2 authentication requirements introduce friction for low-value reloads.
- Reloadable Card:Sustains higher lifetime value through recurring corporate wellness budgets and employee benefit allocations.
- Non-reloadable Card:Single-load instruments serve promotional campaigns and seasonal gifting with simpler compliance overhead.
Physical cards anchor the volume base while digital credentials gain share at the steepest rate.
End User:
Corporate procurement budgets exceed retail spending per account, reshaping issuance economics toward B2B service models.
- Corporate Clients:Multinational headquarters in Milan's Porta Nuova district consolidate vendor relationships through single-source wellness platform contracts. Procurement teams prioritize API interoperability over standalone card features, displacing fragmented multi-vendor arrangements.
- Retail Consumers:Individual purchasers favor digital delivery for speed and wallet integration, though plastic persists for ceremonial gifting occasions.
- Non-profits:Donor recognition and volunteer incentive programs generate steady demand for modest-denomination instruments.
- Educational Institutions:Student meal allowances and campus payment systems drive reloadable adoption in university towns.
Corporate clients command the highest revenue per account while retail consumers provide the broadest addressable base.
Distribution Channel:
Channel economics diverge sharply between high-touch retail placement and zero-marginal-cost digital delivery.
- Mobile Apps:Wallet-integrated provisioning eliminates plastic production overhead and compresses working capital cycles for program managers. Rome and Milan employers now mandate same-day digital delivery for employee recognition disbursements.
- Online Stores:Direct-to-recipient email delivery serves remote gifting and last-minute purchase occasions with minimal fulfillment infrastructure.
- Retail Outlets:Physical placement in postal banking branches and convenience stores maintains access for unbanked populations and traditional gift-givers.
- Third-party Platforms:Aggregator marketplaces expand merchant redemption networks through API-based partnerships.
Mobile apps are climbing the fastest as issuance economics favor zero-marginal-cost delivery, while retail outlets defend residual demand from demographics slower to adopt digital wallets.
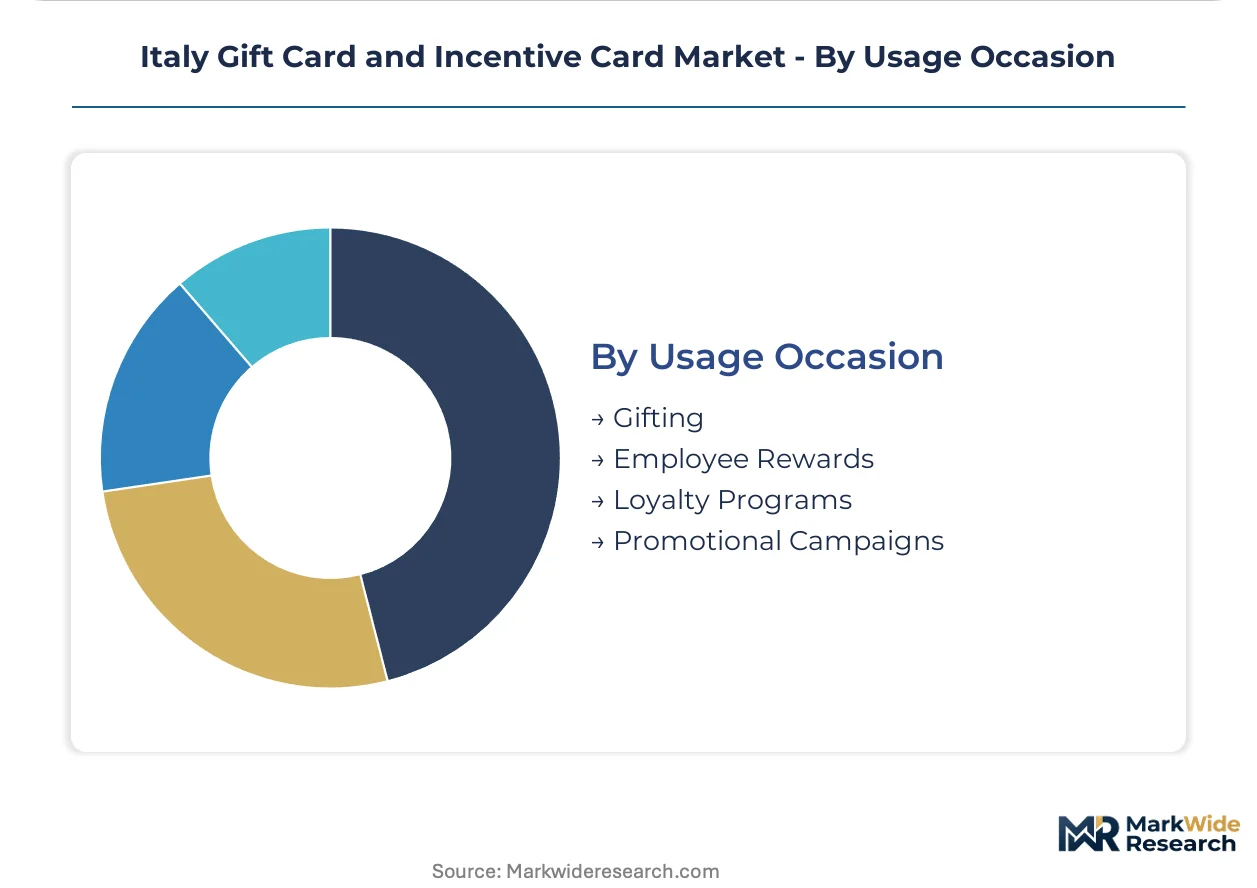
Usage Occasion:
Occasion-based positioning determines regulatory treatment and merchant acceptance terms.
- Employee Rewards:Performance and wellness program disbursements benefit from favorable tax treatment under Italian labor regulations. Centralized procurement in Lazio and Lombardy drives standardization around integrated platform providers.
- Gifting:Consumer-to-consumer transfers face stricter e-money licensing scrutiny from Banca d'Italia regarding fund safeguarding.
- Loyalty Programs:Points-based redemption systems require interoperability with existing merchant POS infrastructure.
- Promotional Campaigns:Time-limited marketing incentives prioritize rapid issuance and controlled expiration mechanics.
Employee rewards anchor B2B revenue stability while gifting occasions expand the consumer addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German gift card exports flow into Italian corporate procurement channels, while French fintech licensing frameworks influence Lombardy-based program managers. Cross-border API interoperability is accelerating under EU-wide open banking standards.
Lombardy
Milan's Porta Nuova district houses multinational headquarters consolidating wellness platform contracts through single-source procurement. Banca d'Italia's e-money licensing requirements enforce segregated capital reserves for prepaid issuers operating in the region. Fintech development clusters around Lombardy's financial services corridor generate specialized talent pools for card program management.
Lazio
Rome's public sector procurement hubs drive standardized incentive card adoption across government employee benefit programs. PSD2 strong customer authentication mandates reshape product design for reloadable instruments distributed through postal banking networks. Centralized HR departments in the capital prioritize API interoperability over standalone card features.
Veneto
Tourism-dependent retail economies in Venice and Verona sustain demand for physical gifting instruments during seasonal peaks. The Italian Data Protection Authority's GDPR tokenization standards accelerate merchant acceptance of digital credentials in hospitality sectors. Regional convenience store networks maintain plastic card distribution for unbanked populations.
Piedmont
Turin's automotive and industrial heritage supports corporate incentive programs tied to performance recognition systems. PostePay leverages prepaid infrastructure integrated with Italy's postal banking system to capture manufacturing sector disbursements. Industrial clusters generate steady demand for reloadable employee benefit allocations.
Campania
Naples and surrounding provinces present underdeveloped corporate incentive card penetration relative to northern regions. SME distribution partnerships remain fragmented across family-owned retail networks. Regional banks are exploring open banking API integration to bypass legacy core banking constraints in program infrastructure.
Italy Gift Card and Incentive Card Market Competitive Landscape
Player mix skews toward integrated B2B platform providers with captive corporate networks. Market structure concentrates around three strategic archetypes: employee benefits specialists leveraging prepaid infrastructure, retail conglomerates with proprietary merchant acceptance networks, and payment processors with POS-terminal ubiquity. Competitive moves center on API interoperability investments and regional distribution partnerships in underserved southern provinces.
Among Italy-based employee benefits platforms, Edenred anchors the B2B network tier through nationwide corporate client relationships. PostePay occupies a distinctive position integrating prepaid issuance with postal banking infrastructure. Nexi Payments exemplifies the processor archetype through merchant-facing terminal networks that capture in-store redemption flows.
| Leading Market Players |
|---|
| Edenred |
| Esselunga |
| Epipoli Group |
| Carrefour Group |
| Conad |
| Nexi Payments |
| Amazon.com |
| Auchan Holding |
| PostePay |
| Others |
Supply & Pricing Matrix
Sixty-day EMV chip lead times from East Asian foundries compress margin pools for physical card issuers while amplifying pricing power for digital credential providers with tokenized API infrastructure. This inventory tension concentrates cost pressure on plastic-dependent program managers and rewards agile fintechs bypassing semiconductor bottlenecks entirely.
Pricing Analysis
Next-generation tokenized digital credentials command premium positioning over legacy magnetic-stripe physical cards and first-generation EMV-chip instruments. Three-tier pricing structure across premium API-integrated platforms, standard web-portal delivery, and economy bulk-email issuance reflects buyer sophistication and integration depth. Cost compression in physical card tiers intensifies because semiconductor supply volatility forces expedited shipping premiums. Corporate procurement teams in Lombardy exhibit lowest price sensitivity due to wellness program budget fungibility, while Campania SMEs demonstrate acute responsiveness to per-unit issuance costs.
Supply Chain Analysis
Inventory cycles spanning 45-90 days for EMV components expose Italian issuers to Taiwan, South Korea, and China semiconductor concentration. Plastic card production draws from petrochemical feedstocks and specialized magnetic stripe substrates, with personalization equipment anchored in German and Italian manufacturing clusters. Single-source vulnerability around EMV chip procurement generates acute disruption risk from logistics chokepoints in East Asian port facilities. Distribution runs through postal banking branches for physical instruments and open banking APIs for digital credentials, creating bifurcated fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across corporate wellness platforms, postal banking networks, and fintech API providers creates multiple entry niches as procurement centralization displaces fragmented multi-vendor arrangements.
For Market Incumbents: Secure API interoperability certifications ahead of EU Digital Identity wallet convergence to preempt platform displacement by integrated wellness providers. Deepen captive B2B relationships through embedded issuance within HR management systems, defending against fintechs leveraging PSD2 infrastructure for direct corporate bypass. For New Entrants and Emerging Players: Anchor in Campania and Sicily SME corridors where corporate incentive card penetration lags northern benchmarks by substantial margins. Target regional bank partnerships as distribution conduits, exploiting legacy core banking constraints that impede incumbent agility in southern provinces. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement centralization among Milan multinationals will compress vendor counts from fragmented multi-source arrangements toward dominant integrated platforms. Monitor EU Digital Identity wallet interoperability announcements as inflection signal for credential-issuance infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | PSD2 compliance and open banking standards favor credentialed issuers in corporate procurement. |
| Regional Distribution Partnership | Campania and Sicily SME penetration remains underdeveloped relative to Lombardy benchmarks. |
| Digital Wallet Integration | EU Digital Identity convergence will redefine competitive positioning for tokenized credential providers. |
| Biometric Authentication Infrastructure | SCA mandates force capital expenditure that squeezes mid-tier prepaid program manager margins. |
| Embedded HR Platform Issuance | Procurement teams in Milan's Porta Nuova district prioritize integrated wellness platform providers. |
Research Methodology
Desk research of Banca d'Italia e-money licensing disclosures, EU PSD2 regulatory filings, and corporate wellness platform technical documentation preceded structured interviews with prepaid program managers, HR procurement leads at Lombardy multinationals, postal banking distribution executives, and fintech API integration specialists. Bottom-up triangulation across issuer transaction volumes and top-down validation through corporate benefits expenditure surveys anchored market sizing.
Variance decomposition across card type, end-user archetype, distribution channel, and usage occasion dimensions structured the analytical framework over the projection horizon. CAGRs derived from segmented growth rate modeling incorporating open banking API adoption curves, corporate wellness budget allocation trends, and regional procurement centralization patterns. Industry-specific inputs included PSD2 compliance cost trajectories and EMV chip supply elasticity assumptions.
Decision-makers should treat outputs as directional under sustained open banking infrastructure investment and stable EU regulatory harmonization; material deviation in SCA implementation timelines or semiconductor supply normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
LAMEA Financial Services Software Market
Financial Services
Capital Restructuring Services Market
Financial Services
Global Temporary Labor Market
Financial Services
ATM Management Service Market
Financial Services
North America B2B Legal Services Market
Financial Services
Financial Services Application Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Billing and Revenue Management Market
Financial Services
Latin America Factoring Services Market
Financial Services
Global Alternative Data Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Investment Trading Software Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Commodity Trade Finance Market
Financial Services
Global Executive Search (Headhunting) Market