
 India POS Terminals Market | 2026-2036
India POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
India POS Terminals Market Outlook
Market Context
The Reserve Bank of India's tokenization mandate and contactless payment guidelines is rebalancing the cost-of-entry calculus for new hardware vendors. Pine Labs Private Limited leverages its merchant network density across metropolitan clusters to sustain installation velocity. Mswipe Technologies Pvt. Ltd. anchors its position through deep distribution into semi-urban retail corridors. Ingenico Group SA competes on EMV certification breadth and compliance architecture.
Technical Definition and Segment Structure
India POS terminals are electronic payment processing devices comprising secure chip readers, encrypted communication modules, and touchscreen interfaces that authenticate card-based and mobile-wallet transactions at the point of sale. These systems integrate with merchant banking networks through GPRS, Wi-Fi, or Ethernet connectivity to enable real-time authorization and settlement. Mobile terminals and contactless terminals command disproportionate attention as deployment accelerates in street-vendor economies and quick-service restaurants where transaction speed determines merchant preference. Cloud-based deployment models are gaining structural traction because they reduce upfront capital expenditure and allow remote software updates across distributed merchant bases.
Regulatory Framework and Outlook
The Reserve Bank of India, the Bureau of Indian Standards, and the Payments Council of India collectively enforce hardware security standards, data localization protocols, and interoperability mandates that determine which terminal models gain market access. BIS certification requirements for electromagnetic compatibility and tamper-evident chassis design filter out uncertified imports and elevate domestic assembly incentives. Stakeholders must monitor how RBI's recurring updates to digital payment security guidelines reshape firmware upgrade obligations and merchant replacement cycles.
Market Dynamics
RBI's tokenization mandate and contactless transaction guidelines are compressing hardware replacement cycles across merchant categories, forcing acquirers to front-load terminal upgrades ahead of compliance deadlines.
Growth Catalysts
- UPI-PayNow linkage expansion:Cross-border retail payment corridors between India and Singapore are driving demand for multi-network terminals capable of processing both domestic and international wallet transactions.
- Street vendor digital onboarding:The PM SVANidhi scheme mandates QR-code and card acceptance for micro-merchants, creating a captive base for low-cost mobile POS deployment in informal economies.
- Contactless mandate velocity:RBI's directive for tap-and-pay capability on all new terminals is accelerating merchant willingness to replace legacy magnetic-stripe hardware.
Market Restraints
- Semiconductor import dependency:Secure element chip shortages from Taiwan and South Korea create 8-12 week lead time volatility for terminal manufacturers assembling in India.
- BIS certification bottlenecks:Electromagnetic compatibility testing queues at Bureau of Indian Standards laboratories extend product launch timelines by 4-6 months for new hardware entrants.
- Smartphone substitution threat:SoftPOS applications running on merchant-owned Android devices eliminate hardware acquisition costs for micro-merchants processing sub-50,000 monthly transaction values.
Strategic Opportunities
- Tier-III city penetration:Rajasthan, Madhya Pradesh, and Uttar Pradesh districts show sub-15% terminal density relative to merchant count, offering first-mover installation advantages.
- Soundbox integration convergence:Audio confirmation devices paired with POS terminals reduce transaction dispute rates and create bundled hardware-service revenue streams.
- PLI scheme localization:The Production Linked Incentive scheme for IT hardware subsidizes domestic assembly of payment terminals, reducing landed cost disadvantages against imports.
Industry Challenges
- Firmware certification latency:RBI's recurring security patch mandates require terminal vendors to recertify software builds, compressing development cycles and straining quality assurance teams.
- Merchant churn management:Acquirers face 18-24 month payback periods on subsidized terminal deployments, yet merchant switching rates exceed 25% annually in competitive urban clusters.
- Legacy system integration friction:ERP and inventory management platforms used by mid-market retailers demand proprietary API development for seamless POS reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India POS Terminals Market |
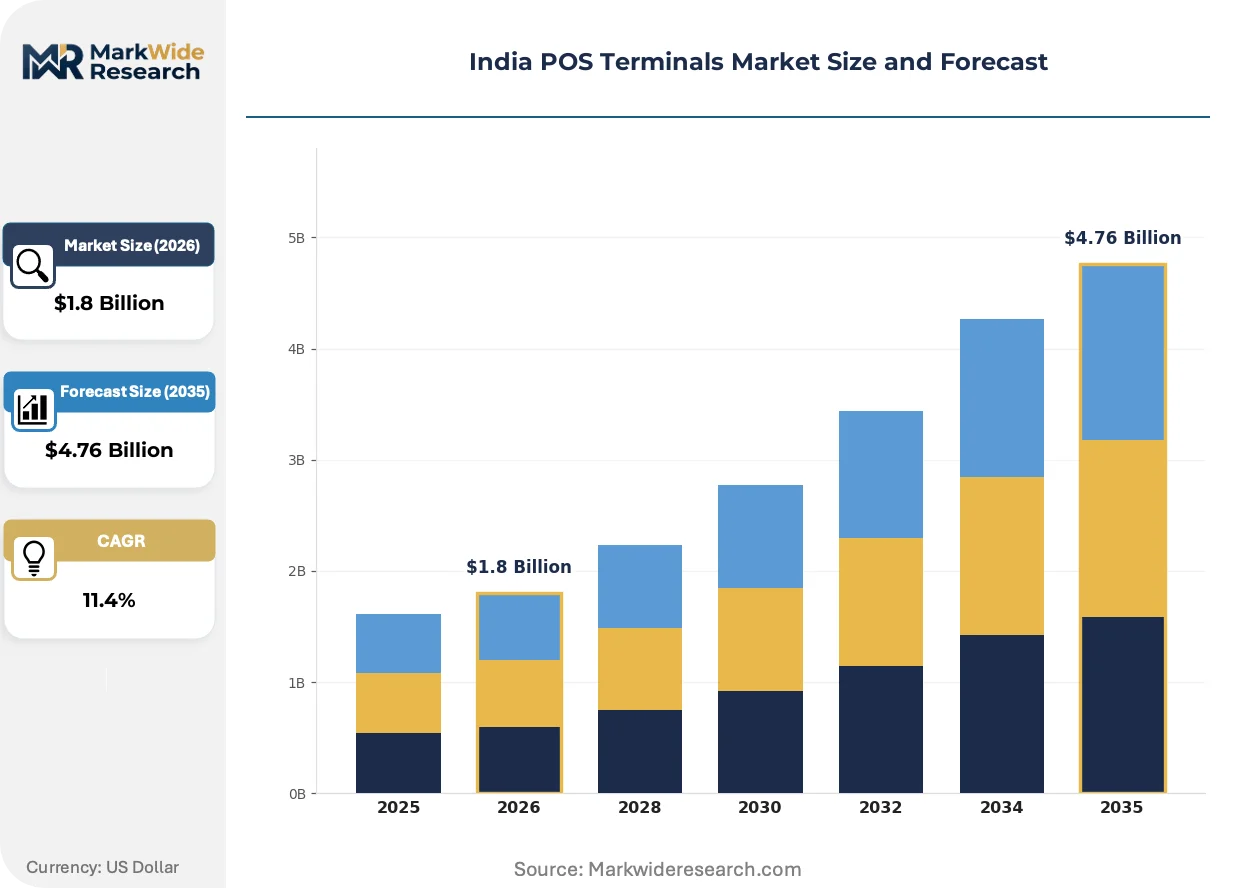
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Contactless Terminals, Integrated Terminals Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote End User Sector: Retail, Hospitality, Healthcare, Transportation Technology: EMV, NFC, Bluetooth, Magnetic Stripe |
| Companies Covered | Mswipe Technologies Pvt. Ltd., Ingenico Group SA, VeriFone Inc., Pine Labs Private Limited, PAX Technology Pvt. Ltd., Worldline, MobiSwipe Technologies Private Limited, NGX Technologies Pvt. Ltd., Razorpay Software Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India POS Terminals Market Strategic Shifts
Payment infrastructure is fragmenting across form factors and connectivity modes, with merchant preference increasingly dictated by transaction context rather than terminal specification alone.
Android-based open-platform terminals are decentralizing hardware procurement decisions away from bank-led distribution. Quick-service restaurants and fuel stations in Bengaluru and Hyderabad are adopting these devices at 3x the rate of proprietary systems. The shift enables merchants to run third-party applications for inventory, loyalty, and analytics on the same hardware, collapsing the traditional separation between payment and business management tools.
RBI's card-on-file tokenization guidelines are mandating end-to-end encryption architecture redesigns. Terminal manufacturers must now embed dedicated secure cryptoprocessors rather than software-based encryption, adding 12-15% to bill-of-materials costs. Food delivery aggregators and subscription commerce platforms represent the most affected segment, as their stored-credential transaction volumes face highest compliance exposure.
Merchant acquisition is fragmenting across non-bank fintech channels. Payment service providers are deploying field sales networks directly into mandi yards and wholesale clusters, bypassing traditional bank branch relationships. This channel shift is most pronounced in Gujarat's textile markets and Punjab's agricultural procurement centers, where merchant trust resides with trade associations rather than financial institutions.
India POS Terminals Market Segmentation
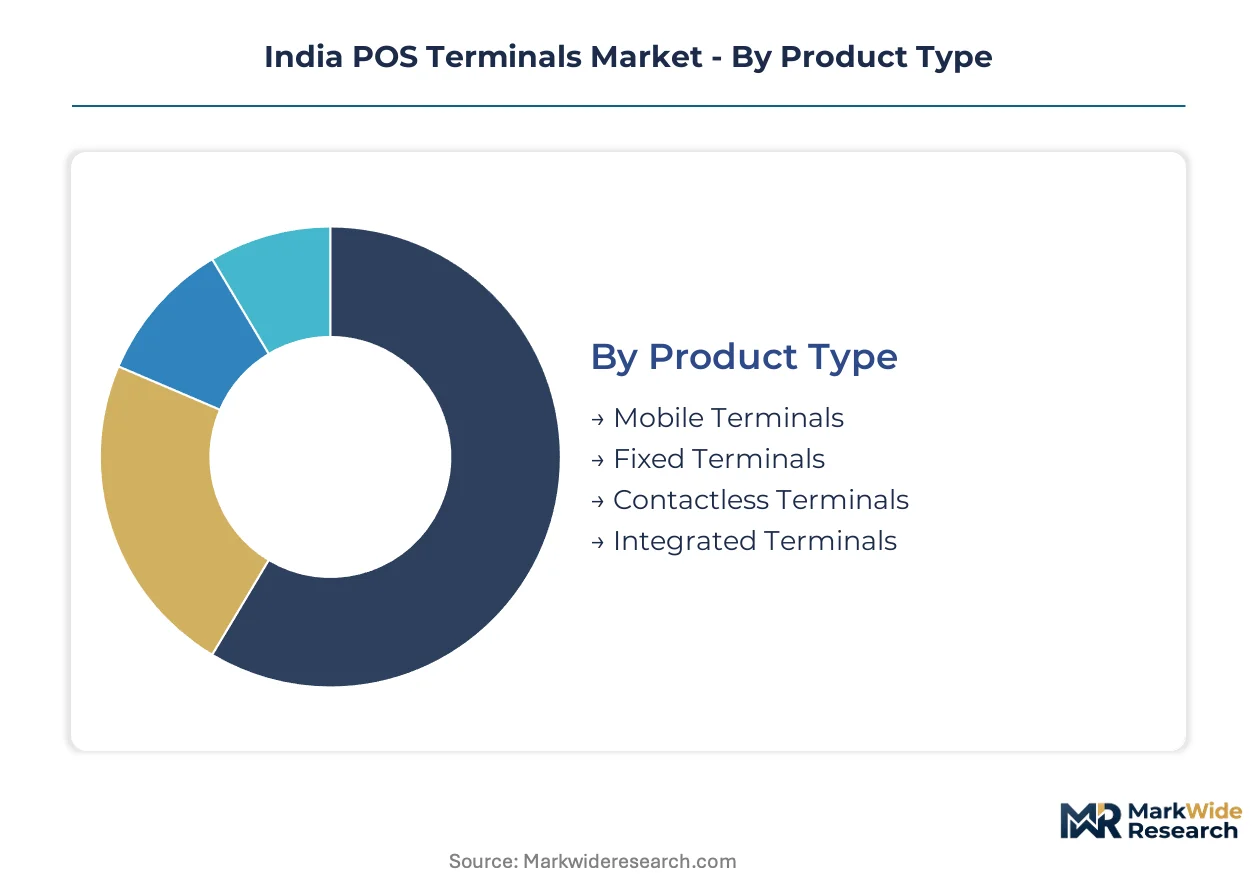
Segmentation in the India POS Terminals Market reveals how RBI mandates and merchant digital maturity are fragmenting procurement patterns across hardware specifications and service delivery models. Vendors must align terminal capabilities with specific compliance deadlines and connectivity infrastructure in target geographies.
Product Type:
Hardware specifications determine terminal mobility, transaction speed, and integration depth with merchant operations across street-vendor and enterprise contexts.
- Mobile Terminals:Battery-powered devices with GPRS/Wi-Fi connectivity enable transaction processing in delivery fleets and temporary market setups. PM SVANidhi scheme disbursements in Maharashtra and Gujarat mandis are accelerating deployment where fixed infrastructure is absent.
- Fixed Terminals:Countertop units with Ethernet tethering and receipt printers serve high-volume retail environments. Department stores in Bengaluru and Hyderabad clusters specify these for checkout throughput and ERP integration requirements.
- Contactless Terminals:NFC-enabled readers process tap-and-pay transactions under RBI's contactless mandate velocity. Quick-service restaurants prioritize these for sub-10-second transaction completion.
- Integrated Terminals:Units combining payment, inventory, and loyalty management collapse multiple vendor relationships into single hardware procurement. Mid-market retailers in Tier-II cities adopt these to reduce software integration friction.
Mature deployment sits with Fixed Terminals. Newer deployment is concentrated in Mobile Terminals.
Deployment Model:
Capital expenditure preferences and IT staff availability are pushing merchant selection toward operational expenditure models that externalize maintenance and security patch management.
- On-Premises:Local server installation with dedicated IT administration suits large-format retailers with legacy ERP dependencies. Multi-location chains in Mumbai and Delhi maintain these for transaction data sovereignty and custom reconciliation workflows.
- Cloud-Based:Terminal-as-a-service models shift firmware update and PCI-DSS compliance burdens to vendors. Micro-merchants in Rajasthan and Madhya Pradesh districts select these for zero upfront hardware acquisition and automatic RBI security guideline adherence.
- Hybrid:Split architecture keeps sensitive payment data on local hardware while routing analytics to cloud dashboards. Mid-tier hospitality operators in Goa and Kerala deploy these to balance transaction speed with business intelligence access.
- Remote:Fully vendor-managed terminals with field service coverage eliminate merchant IT involvement. Petroleum retail outlets along national highways specify these for 24/7 uptime guarantees and automatic hardware replacement.
On-Premises retains share among legacy retail chains. Cloud-Based is climbing the fastest as acquirers subsidize terminal placement to capture transaction fee revenue.
End User Sector:
Transaction context—frequency, value, customer flow—shapes terminal specification requirements more than hardware cost alone.
- Retail:Grocery, apparel, and electronics merchants require high-throughput terminals with inventory system handshake. Tier-III city general stores in Uttar Pradesh represent the largest untapped installation base.
- Hospitality:Restaurants and hotels need tip-adjustment capabilities and split-bill functionality. Coastal tourism circuits in Karnataka and Goa are seeing soundbox-integrated terminal bundling to reduce dispute rates.
- Healthcare:Clinics and pharmacies prioritize EMV certification and patient data segregation. Diagnostic chains in Gujarat specify terminals with standalone payment processing isolated from health record systems.
- Transportation:Fleet operators and toll plazas demand ruggedized units with offline transaction storage. State transport corporations in Tamil Nadu are piloting contactless terminals for conductor-less fare collection.
Retail commands the deepest installed base. Transportation is gaining share fastest as state digitization mandates expand.
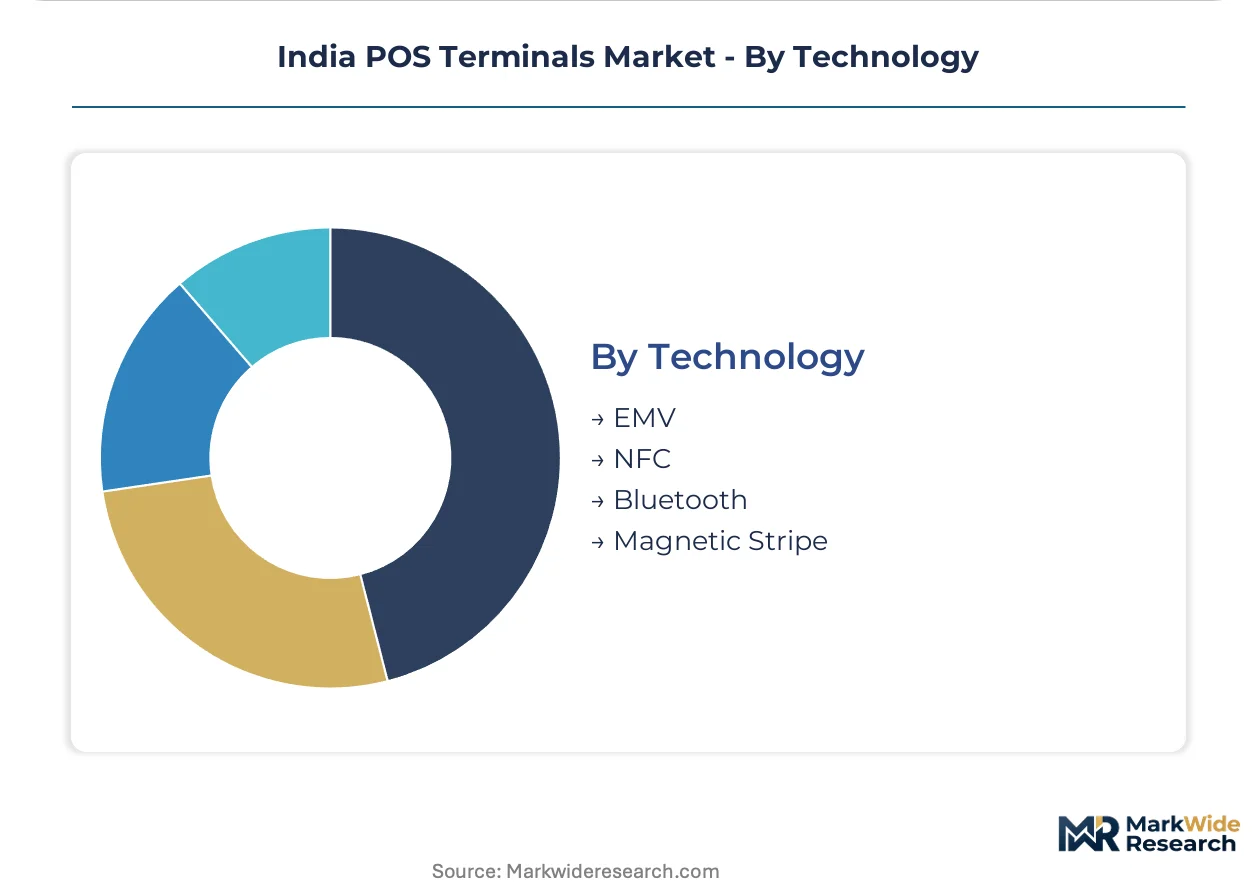
Technology:
Security architecture and transaction authentication methods are undergoing forced migration as RBI phases out legacy acceptance protocols.
- EMV:Chip-card authentication with dynamic cryptogram generation is mandatory for all new terminal certifications. Bank-led acquirers in metropolitan clusters have completed EMV migration; semi-urban deployments lag.
- NFC:Near-field communication enables tap-and-pay without card insertion. Quick-service restaurants and fuel stations in Hyderabad and Bengaluru are adopting at accelerated rates.
- Bluetooth:Low-energy pairing connects terminals to merchant smartphones for SoftPOS extension. Street vendors with PM SVANidhi eligibility use these for audio confirmation device pairing.
- Magnetic Stripe:Legacy swipe authentication faces RBI-mandated phase-out timelines. Replacement cycles are compressing as compliance deadlines approach for remaining installed units.
Magnetic Stripe represents residual replacement demand. NFC is expanding most quickly as contactless transaction thresholds rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant onboarding velocity concentrates in western and southern states where RBI's contactless mandates intersect with existing digital payment infrastructure. Semi-urban corridors in Maharashtra, Gujarat, and Karnataka absorb terminal deployment faster than northern counterparts due to denser banking correspondent networks and earlier EMV migration completion.
Maharashtra
Mumbai-Pune industrial belt drives enterprise-grade terminal procurement for retail chains and hospitality operators. RBI's tokenization guidelines force firmware upgrades across existing installed bases in Thane and Navi Mumbai commercial clusters. Tier-II cities Nagpur and Nashik show accelerated mobile POS adoption under PM SVANidhi scheme disbursements to street vendors in mandi yards.
Gujarat
Textile markets in Surat and Ahmedabad generate concentrated demand for integrated terminals combining payment processing with inventory reconciliation. BIS electromagnetic compatibility certification requirements filter hardware imports through domestic assembly incentives under PLI scheme provisions. Merchant acquisition bypasses traditional bank branches in favor of trade association-mediated fintech deployments across wholesale clusters.
Karnataka
Bengaluru's quick-service restaurant density prioritizes contactless terminals with sub-10-second transaction completion requirements. RBI's recurring security patch mandates compress development cycles for terminal vendors serving the city's food delivery aggregator ecosystem. Mysuru and Mangalore hospitality circuits adopt soundbox-integrated terminal bundling to reduce transaction dispute rates in tourism-dependent corridors.
Tamil Nadu
State transport corporation digitization pilots contactless terminals for conductor-less fare collection across Chennai metro and intercity bus networks. Semiconductor import dependency from Taiwan and South Korea creates lead time volatility for terminal manufacturers assembling in Sriperumbudur electronics corridor. Coimbatore's manufacturing SME base shows lagging EMV migration relative to southern counterparts.
Telangana
Hyderabad's fuel station and quick-service restaurant clusters adopt NFC-enabled terminals at rates exceeding national averages. Cloud-based deployment models gain traction among micro-merchants in Warangal and Nizamabad districts where zero upfront hardware acquisition outweighs data sovereignty concerns. RBI's contactless mandate velocity accelerates merchant willingness to replace legacy magnetic-stripe hardware in semi-urban procurement centers.
India POS Terminals Market Competitive Environment
Domestic acquirers anchor one tier; international hardware specialists hold certification and compliance architecture advantages. Market structure fragments across bank-led distribution networks, direct fintech field sales, and trade association-mediated channels. Three archetypes dominate: merchant network density players, EMV certification breadth specialists, and low-cost mobile terminal assemblers. Competitive moves concentrate on geographic expansion into Tier-III corridors and bundled hardware-service revenue streams through audio confirmation device integration.
Within the merchant network density tier, Pine Labs Private Limited and Mswipe Technologies Pvt. Ltd. exemplify divergent geographic strategies. Pine Labs leverages metropolitan cluster penetration to sustain installation velocity through existing banking relationships. Mswipe anchors position through distribution depth into semi-urban retail corridors where merchant trust resides with local trade associations rather than financial institutions. Ingenico Group SA occupies the international specialist position, competing on EMV certification breadth and compliance architecture that satisfies RBI's recurring security guideline updates.
| Leading Market Players |
|---|
| Mswipe Technologies Pvt. Ltd. |
| Ingenico Group SA |
| VeriFone Inc. |
| Pine Labs Private Limited |
| PAX Technology Pvt. Ltd. |
| Worldline |
| MobiSwipe Technologies Private Limited |
| NGX Technologies Pvt. Ltd. |
| Razorpay Software Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Embedded systems engineering talent concentration in Bengaluru and Hyderabad feeds labor-cost differentials that separate premium-tier integrated terminals from economy-grade mobile units. RBI certification complexity and secure element sourcing constraints widen these spreads as vendors pass compliance investments downstream.
Pricing Analysis
Volume-vs-margin splits favor transaction-fee capture over hardware margins, with acquirers subsidizing terminal placement to secure recurring payment processing revenue. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification depth, after-sales service bundling, and cloud-native architecture. Pricing pressure stems from SoftPOS applications eliminating hardware acquisition for micro-merchants. Street vendors under PM SVANidhi show highest price sensitivity; large-format retail chains prioritize integration depth over unit cost.
Supply Chain Analysis
Secure element chip supply rests on Taiwanese and South Korean semiconductor foundries, with domestic assembly concentrated in Sriperumbudur and Noida electronics corridors. Bill-of-materials draws from Chinese PCB manufacturers, Japanese display panel producers, and German precision component suppliers. Single-source vulnerability around EMV-certified secure cryptoprocessors creates procurement risk. Distribution runs through bank-led acquirer networks, direct fintech field sales, and trade association-mediated wholesale clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India POS Terminals Market sits in a forced hardware replacement cycle as NFC contactless architecture displaces legacy magnetic-stripe infrastructure under RBI mandate velocity.
For Market Incumbents: Lock in merchant switching costs through soundbox-integrated terminal bundling that raises replacement friction. Deepen firmware certification capabilities to compress RBI security patch turnaround times. Anchor cloud-based deployment models with automatic compliance updates to neutralize SoftPOS substitution threats from smartphone-based acceptance. For New Entrants and Emerging Players: Begin with Tier-III districts in Rajasthan, Madhya Pradesh, and Uttar Pradesh where terminal density lags merchant count by wide margins. Target mandi yards and agricultural procurement centers where trade association trust bypasses traditional bank channels. Deploy low-cost mobile terminals under PM SVANidhi scheme eligibility to establish field presence before scaling integrated offerings. For Investors and Strategic Acquirers: Re-rating potential sits with domestic assembly specialists given PLI scheme localization subsidies and BIS certification bottlenecks that filter import competition. Long-term viability favors vendors controlling both hardware certification depth and merchant acquisition channel density. Watch RBI tokenization guideline expansion into stored-credential commerce as inflection indicator for secure cryptoprocessor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Scale-Up | PLI scheme subsidies reduce landed cost disadvantages against Taiwanese and South Korean imports. |
| Cloud-Native Platform Migration | Terminal-as-a-service models externalize RBI firmware compliance burdens from micro-merchants. |
| Soundbox Hardware Bundling | Audio confirmation integration reduces transaction dispute rates in Karnataka and Goa hospitality corridors. |
| Tier-III Geographic Expansion | First-mover installation advantages persist in sub-15% terminal density districts of Uttar Pradesh. |
| EMV Certification Investment | Breadth of compliance architecture satisfies recurring RBI security guideline updates and accelerates merchant onboarding. |
Study Parameters
Independent corroboration across terminal manufacturer executives, bank-led acquirer procurement leads, and fintech field operations directors underwrites the qualitative findings. Secondary validation draws from RBI circulars on digital payment security, BIS electromagnetic compatibility certification records, PLI scheme disbursement disclosures, and customs import data for secure element chips. Bottom-up merchant installation estimates triangulate against top-down payment network transaction volume projections.
Comparable-period anchoring uses historical terminal deployment trajectories across EMV migration waves to inform projection mechanics across the analysis window. Segmentation dimensions span product mobility class, deployment architecture, end-user sector transaction context, and authentication technology type. CAGRs derive from installed base replacement cycle compression under regulatory mandate velocity and merchant digital onboarding program expansion.
Underlying measurement precision varies by segment; metropolitan cluster deployment data carries tighter precision than informal economy penetration estimates. Forecasts incorporate assumptions around semiconductor supply continuity and BIS laboratory certification throughput. RBI tokenization guideline scope expansion, secure element import lead time volatility, and SoftPOS adoption inflection warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mpos Terminals Market
Payments
Belgium POS Terminals Market
Payments
Global Gift Card Market
Payments
Germany Payment Gateway Market
Payments
Consumer Mobile Payment Market
Payments
France Payments Market
Payments
United Arab Emirates Payment Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Digital Money Transfer Market
Payments
Digital Payment in Healthcare Market
Payments
Croatia POS Terminals Market
Payments
Poland POS Terminal Market
Payments
Mexico Payments Market
Payments
Indonesia Payments Infrastructure Market
Payments
Europe POS Terminal Market
Payments
Freight Audit and Payment Service Market