
 South Korea Financial Services Software Market | 2026-2036
South Korea Financial Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Financial Services Software Market Insights
Market Context
South Korea is tilting its financial technology capacity toward cloud-native infrastructure and AI-embedded transaction platforms. Samsung SDS leverages its hyperscale cloud operations to dominate public-sector and chaebol-affiliated banking contracts. LG CNS anchors the competitive landscape through deep integration with major retail banks and insurance conglomerates. TmaxSoft competes aggressively on core banking alternatives that reduce foreign vendor dependency in the domestic market.
Technical Definition and Segment Structure
Financial services software encompasses specialized applications that automate transaction processing, risk calculation, regulatory reporting, and customer-facing banking operations through modular, API-connected architectures. Core banking systems manage ledger integrity and real-time settlement across deposit, loan, and treasury functions, while payment processing modules handle clearing, cross-border remittance, and digital wallet orchestration. Cloud-based deployment is displacing on-premises legacy stacks as Korean financial institutions prioritize elastic scalability and disaster recovery compliance. Payment processing captures expanding margin pools as real-time settlement volumes surge, whereas risk management segments deepen in sophistication under Basel III-aligned supervisory expectations.
Regulatory Framework and Outlook
The Financial Services Commission enforces open banking API standards and data portability rules that compel institutions to modernize interoperable software stacks. MFDS cybersecurity guidelines for financial infrastructure, combined with BIS-aligned operational risk frameworks, elevate compliance spending on audit-ready software modules. Stakeholders must monitor how Korea's central bank digital currency pilot reshapes payment processing requirements and core banking integration priorities.
Market Dynamics
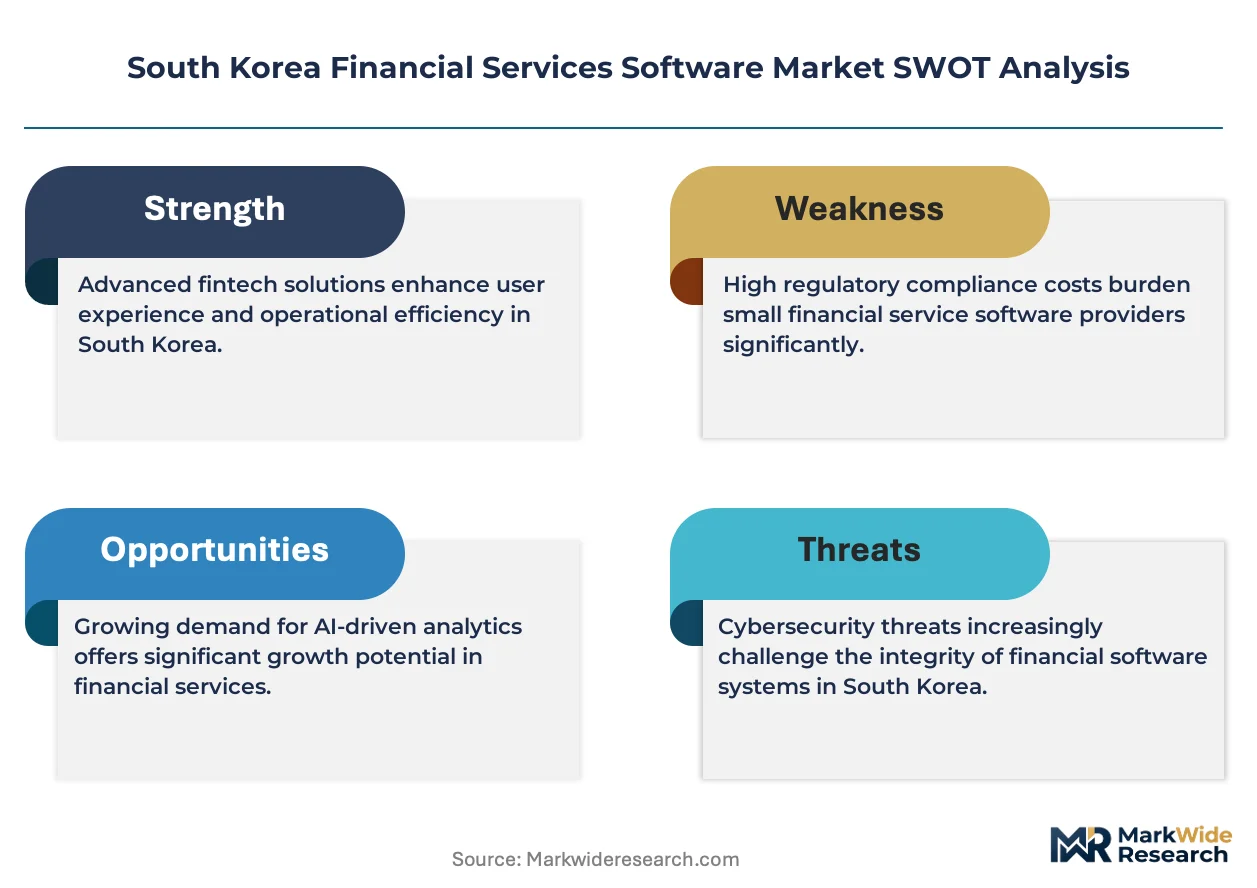
Cloud-native core banking migration is compressing vendor replacement cycles across South Korean financial institutions, forcing incumbent software providers to rearchitect legacy stacks around API-first interoperability demanded by Financial Services Commission mandates.
Growth Catalysts
- Open Banking API Mandates:The Financial Services Commission's standardized data-sharing protocols compel retail banks and fintechs to modernize interoperable software layers, accelerating procurement of modular core banking platforms.
- Real-Time Settlement Infrastructure:The Bank of Korea's retail payment system upgrades drive demand for payment processing modules capable of handling instant fund transfers and digital wallet orchestration.
- Seoul-Busan Cluster Concentration:Geographic clustering of financial headquarters in Yeouido and Busan's fintech hub creates dense procurement ecosystems where vendor proof-of-concepts convert rapidly to production contracts.
Market Restraints
- Legacy System Integration Costs:On-premises mainframe dependencies in major commercial banks impose prohibitive switching costs that delay full cloud migration timelines.
- Domestic Vendor Concentration:Heavy reliance on chaebol-affiliated software providers limits price competition and creates single-source vulnerability for specialized risk management modules.
- Cybersecurity Compliance Burden:MFDS financial infrastructure guidelines mandate continuous audit-ready documentation, elevating operational overhead for smaller regional banks.
Strategic Opportunities
- Central Bank Digital Currency Integration:The Bank of Korea's CBDC pilot program creates white space for payment processing vendors to develop ledger-agnostic settlement architectures.
- Busan Fintech Hub Expansion:Regulatory sandboxes in Korea's second-largest city attract foreign software entrants seeking localized deployment partnerships.
- AI-Embedded Risk Analytics:Convergence of machine learning algorithms with Basel III-aligned stress testing tools opens premium pricing tiers for predictive credit scoring modules.
Industry Challenges
- Cloud Architecture Talent Scarcity:Domestic universities produce insufficient engineers fluent in Kubernetes orchestration and distributed ledger systems to meet bank hiring targets.
- Multi-Vendor Integration Complexity:Hybrid deployments mixing foreign core banking engines with domestic payment modules create API versioning conflicts that delay production rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Financial Services Software Market |
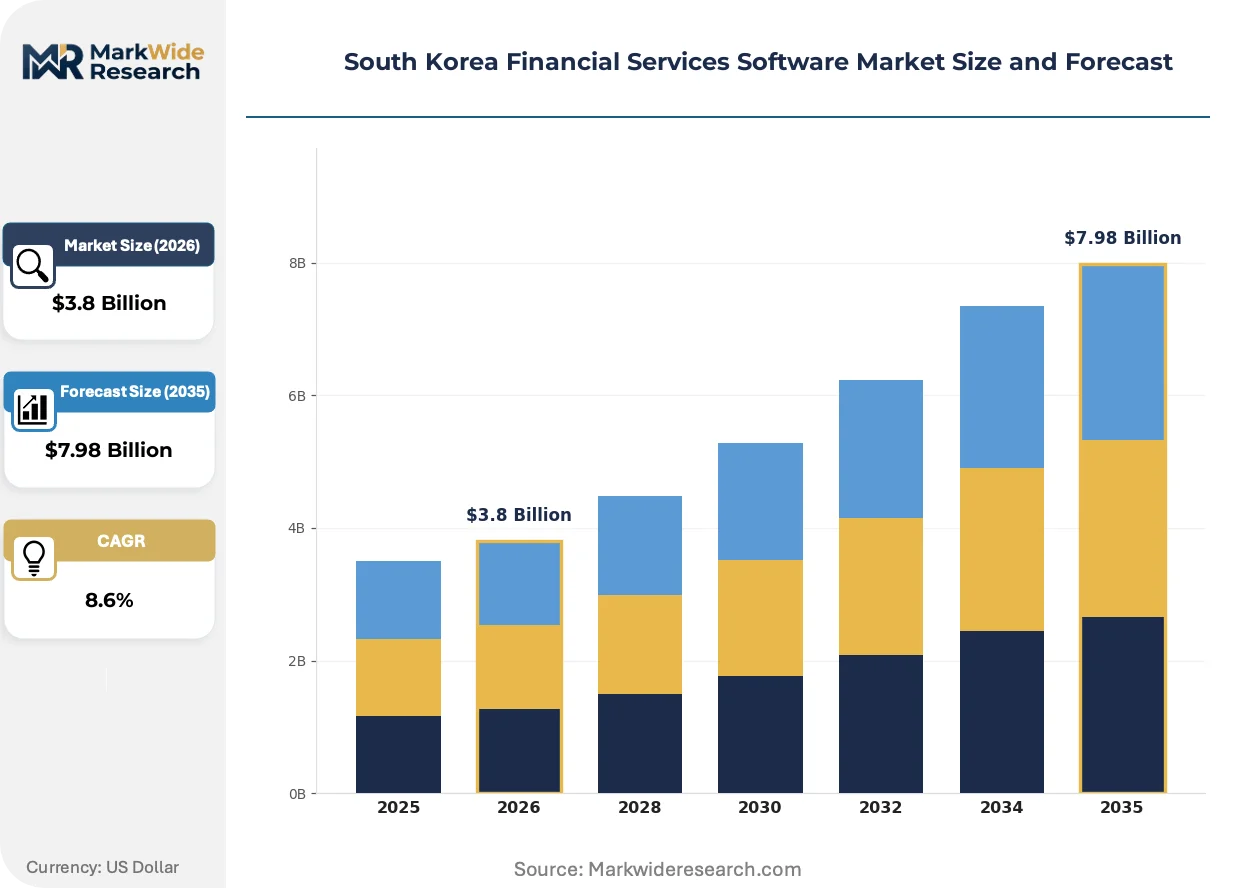
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Banking, Payment Processing, Risk Management, Wealth Management Service Type: Consulting, Integration, Support, Maintenance Client Type: Retail Banks, Investment Firms, Insurance Companies, Credit Unions Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Samsung SDS, LG CNS, TmaxSoft, NKIA, Finastra, Tata Consultancy Services, Oracle Financial Services Software, Infosys Finacle, FIS Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Financial Services Software Market Trends and Innovations
Software delivery models across Korean financial services are pivoting toward containerized microservices that decouple transaction processing from monolithic core systems, enabling incremental modernization without wholesale replacement.
Core banking infrastructure is migrating from on-premises IBM mainframe architectures to distributed cloud-native platforms. Mid-tier regional banks and internet-only banks are adopting these systems fastest, compressing implementation timelines from multi-year waterfall projects to iterative six-month sprints. This migration from legacy stacks is collapsing the traditional vendor lock-in periods that protected foreign incumbents for decades.
The Financial Services Commission's cloud-first policy framework now requires financial institutions to justify any new on-premises deployment, effectively mandating SaaS or private-cloud consumption for non-core functions. This regulatory pressure forces domestic software vendors to obtain ISO 27001 and SOC 2 certifications previously held only by global providers. Insurance and securities firms face the steepest compliance ramps as they lag retail banks in cloud maturity.
Subscription-based pricing for risk management and regulatory reporting modules is displacing perpetual license models that dominated Korean procurement for thirty years. Tier-two banks and credit unions now demand usage-based billing tied to transaction volumes rather than fixed annual fees. This shift is most visible in Seoul's Yeouido district where procurement teams renegotiate enterprise contracts to align software costs with fluctuating settlement volumes.
South Korea Financial Services Software Market Segmentation
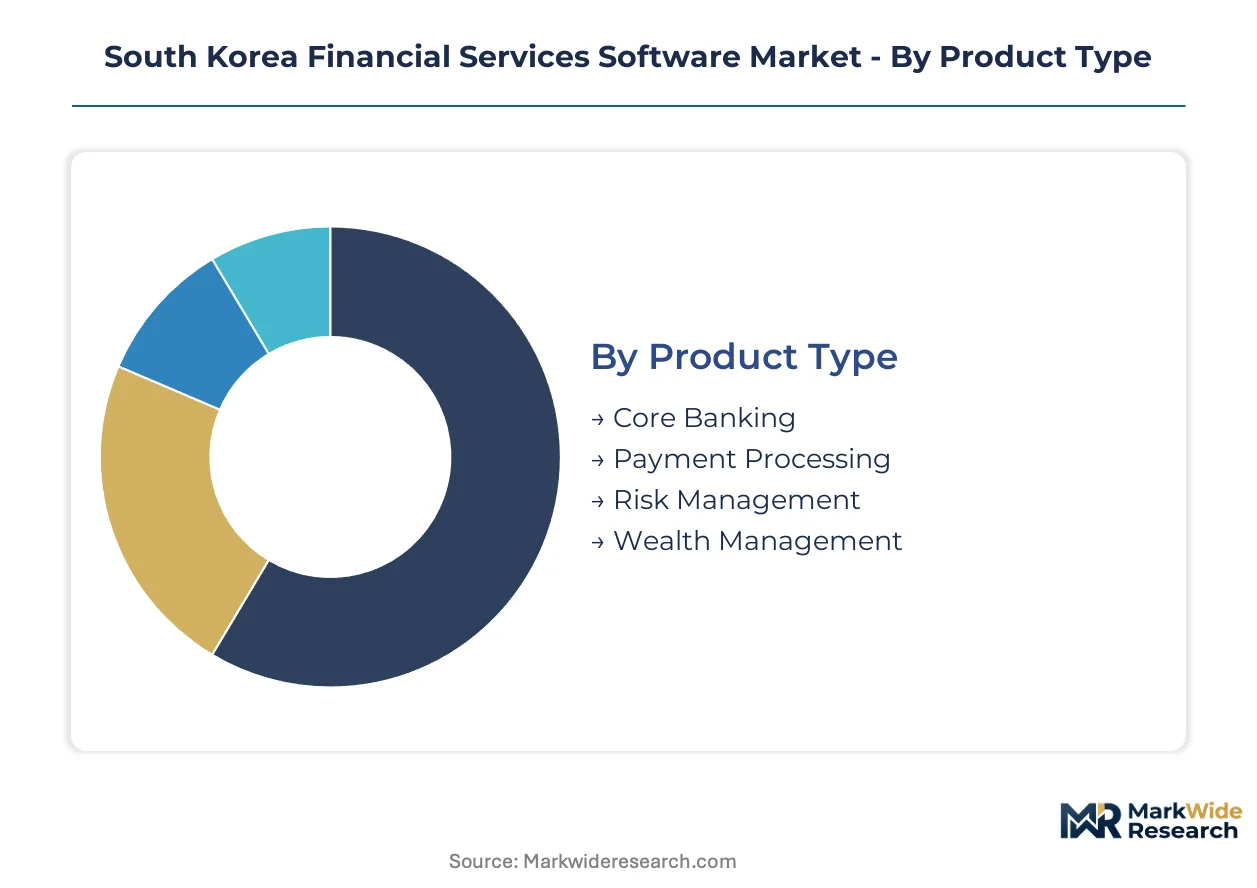
South Korean financial institutions select software modules based on regulatory compliance deadlines and cloud migration maturity. Procurement cycles vary dramatically across segments, with payment processing refreshing fastest while core banking systems endure decade-long replacement timelines.
Product Type:
Payment Processing turns over every 3-4 years as real-time settlement standards evolve, whereas Core Banking platforms persist 12-15 years between major upgrades.
- Core Banking:Ledger management systems handle deposit, loan, and treasury functions through real-time settlement engines. Major commercial banks in Seoul's Yeouido district prioritize these replacements to satisfy Financial Services Commission cloud-first mandates, though mainframe dependencies delay full migrations.
- Payment Processing:Clearing modules orchestrate instant fund transfers, cross-border remittance, and digital wallet integration. Busan's fintech cluster drives fastest adoption here as internet-only banks and foreign entrants compete on transaction speed.
- Risk Management:Basel III-aligned stress testing and credit scoring tools with continuous audit documentation capabilities. MFDS cybersecurity guidelines elevate procurement priority for regional banks lacking in-house compliance teams.
- Wealth Management:Portfolio analytics and robo-advisory platforms serving high-net-worth segments. Securities firms lag retail banks in deployment sophistication due to fragmented client data architectures.
Core Banking dominates installed base. Payment Processing is where expansion concentrates.
Service Type:
Integration services command premium pricing where hybrid deployments mix foreign engines with domestic modules, while Support contracts concentrate among smaller institutions lacking internal DevOps capacity.
- Consulting:Cloud migration strategy and regulatory gap analysis delivered by specialized boutiques. Tier-two banks in provincial cities rely heavily on external advisors to navigate Financial Services Commission open banking mandates.
- Integration:API middleware development connecting legacy mainframes to cloud-native platforms. This segment faces acute talent scarcity as Kubernetes orchestration skills outpace domestic university output.
- Support:24/7 technical assistance and incident response for production environments. Credit unions and regional banks purchase these services most intensively due to limited internal IT headcount.
- Maintenance:Patch management, security updates, and version control for deployed software stacks. Perpetual license holders in insurance sector generate steady recurring demand here.
Integration services capture highest margins. Support contracts represent the most predictable revenue stream.
Client Type:
Retail Banks drive largest absolute spending volumes, while Insurance Companies face steepest compliance ramps as they transition from paper-based processes.
- Retail Banks:Full-service institutions managing consumer deposits, lending, and payment networks. Kookmin, Shinhan, and Woori dominate procurement volumes as they modernize nationwide branch infrastructure.
- Investment Firms:Brokerage houses and asset managers requiring real-time trading platforms and regulatory reporting automation. These clients prioritize latency reduction over cost optimization in platform selection.
- Insurance Companies:Life and property-casualty carriers modernizing policy administration and claims processing. This segment trails banking in cloud maturity, creating white space for SaaS-based core system replacements.
- Credit Unions:Member-owned cooperative banks serving specific employer groups or communities. These institutions demand usage-based pricing models that align software costs with fluctuating transaction volumes.
Retail Banks dominate installed base. Insurance Companies represent the steepest expansion trajectory.
Deployment Model:
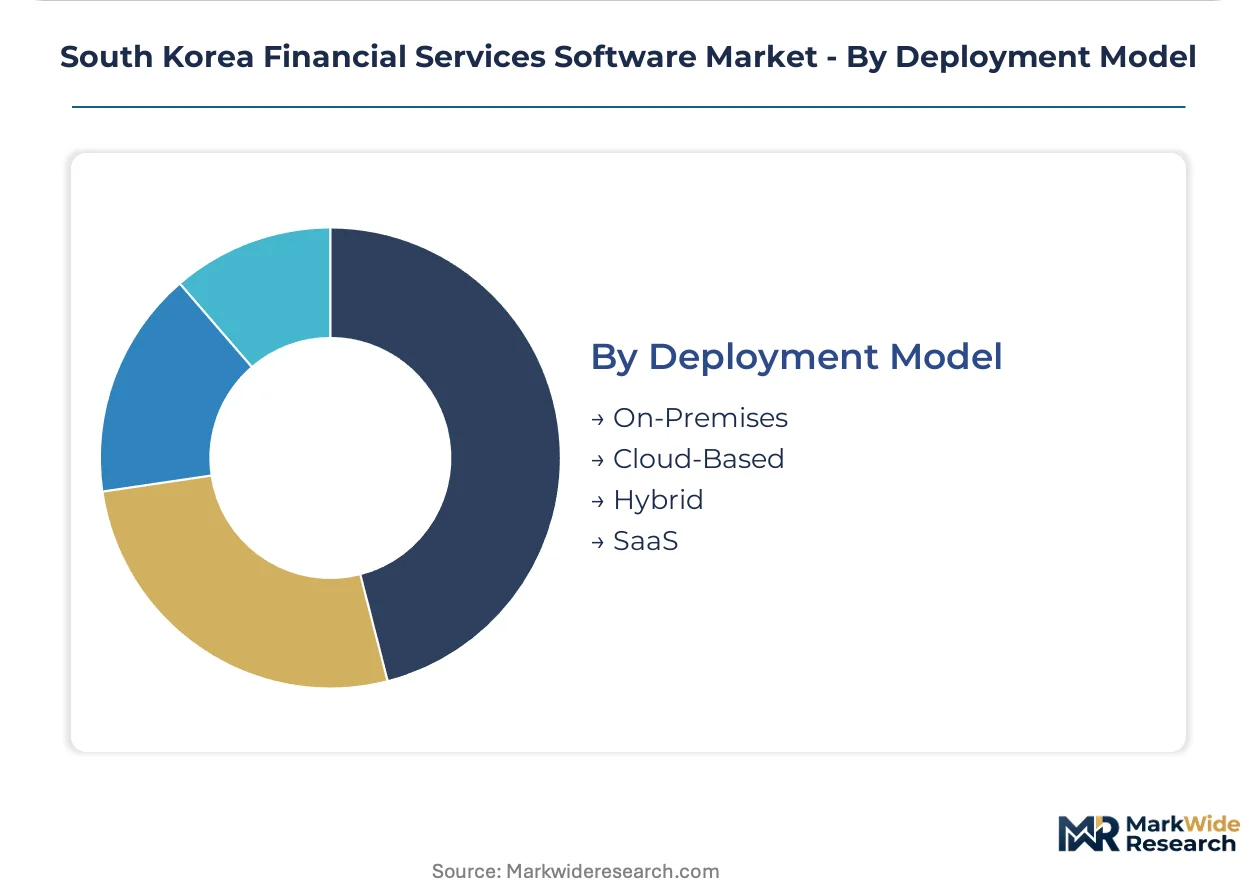
Cloud-Based deployments are climbing the fastest as Financial Services Commission policies effectively ban new on-premises installations for non-core functions.
- On-Premises:Legacy mainframe and private data center installations retained for core ledger functions. Major commercial banks maintain these environments for regulatory audit trails despite cloud migration pressure.
- Cloud-Based:Public or private cloud infrastructure with elastic scalability and automated disaster recovery. Internet-only banks like KakaoBank and Toss Bank built exclusively on these architectures, forcing incumbents to match their agility.
- Hybrid:Mixed environments segregating sensitive transaction data on-premises while routing customer-facing applications to cloud. This model prevails where banks lack confidence in single-vendor cloud security certifications.
- SaaS:Subscription-based consumption of standardized modules without customization. Regional banks and credit unions favor this approach to convert capital expenditure into predictable operating costs.
On-Premises retains largest legacy footprint. Cloud-Based deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Financial Services Commission anchors software procurement patterns across South Korea, with its open banking mandates and cloud-first policies creating distinct demand clusters in metropolitan financial centers.
Seoul Capital Area
Yeouido's concentrated headquarters of Kookmin, Shinhan, and Woori Bank drive core banking modernization spending. The Financial Services Commission's API standardization deadlines compress procurement cycles for modular ledger systems. Gangnam district hosts emerging fintech challengers demanding SaaS-native payment orchestration platforms.
Busan-Ulsan
Busan's regulatory sandbox attracts foreign software entrants seeking localized deployment partnerships. The Korea Internet and Security Agency operates cybersecurity certification facilities supporting regional bank compliance. Ulsan's industrial banking heritage creates specialized demand for trade finance automation modules.
Daegu-Gyeongbuk
Regional banking associations here lag capital-area peers in cloud migration maturity. The Financial Supervisory Service's branch supervision mandates elevate audit-ready documentation requirements. Daegu's emerging smart city initiatives pilot municipal-fintech integration use cases.
Daejeon-Sejong
Sejong's administrative city concentration houses government-affiliated financial institutions with unique procurement protocols. The Korea Financial Investment Association operates data centers requiring specialized risk management software. Daejeon's KAIST and ETRI research outputs feed local vendor AI development pipelines.
Gwangju-Honam
Agricultural cooperative banks in this southwestern region prioritize cost-optimized SaaS solutions over capital-intensive on-premises deployments. The Jeonnam regional government promotes fintech incubation through subsidized cloud infrastructure access. Gwangju's photonics industry spillover creates niche demand for optical-network-secured transaction processing.
South Korea Financial Services Software Market Competitive Landscape
Capability concentration sits with chaebol-affiliated systems integrators; scale advantage sits with global banking software specialists. Samsung SDS and LG CNS leverage hyperscale cloud operations and deep retail bank relationships respectively. TmaxSoft competes on core banking alternatives reducing foreign vendor dependency. Market consolidation proceeds through strategic partnerships between domestic integrators and foreign platform licensors, while vertical specialization deepens around AI-embedded risk analytics.
Within the domestic systems integrator tier, Samsung SDS, LG CNS, and TmaxSoft exemplify distinct competitive positioning. Samsung SDS occupies a position anchored in public-sector and chaebol-affiliated contracts. LG CNS represents deep integration archetypes serving major retail banking conglomerates. TmaxSoft sits within the alternative core banking segment targeting institutions seeking reduced dependency on foreign-engineered ledger systems. Global specialists including Finastra, Oracle Financial Services Software, and FIS Global license platform technology to domestic partners rather than direct deployment, reflecting regulatory constraints on foreign data handling in financial infrastructure.
| Leading Market Players |
|---|
| Samsung SDS |
| LG CNS |
| TmaxSoft |
| NKIA |
| Finastra |
| Tata Consultancy Services |
| Oracle Financial Services Software |
| Infosys Finacle |
| FIS Global |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure concentration in South Korea and the United States feeds directly into margin distribution across domestic software integrators, with chaebol-affiliated vendors capturing premium pricing tiers while foreign platform licensors accept compressed royalties.
Pricing Analysis
Seoul's Yeouido district commands 15-20% price premiums over Busan for equivalent core banking modules, reflecting procurement density and proof-of-concept conversion speed. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ISO 27001 certification status and customization depth for legacy mainframe integration. Pricing pressure stems from subscription-based SaaS models displacing perpetual licenses, particularly among regional banks seeking operating expense conversion. Credit unions and agricultural cooperatives exhibit highest price sensitivity, while major commercial banks prioritize latency reduction and regulatory audit readiness over cost optimization.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment and AI training chips constrain domestic Korean vendors' access to high-performance compute infrastructure for risk analytics development. Software supply chains draw from South Korea, the United States, and Ireland, with core banking engines licensed from foreign specialists while integration services remain captive to domestic chaebol affiliates. Dependencies include Kubernetes orchestration talent, API middleware frameworks, and cloud-native database architectures. Single-source vulnerability pervades specialized risk management modules where Samsung SDS and LG CNS dominate. Distribution runs through direct enterprise sales teams for Tier-1 banks, with channel partners serving provincial credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Korea's five major banking groups as procurement teams consolidate vendor rosters and demand usage-based pricing tied to real-time settlement volumes.
For Market Incumbents: Harden cloud-native certification portfolios against emerging fintech challengers by accelerating ISO 27001 and SOC 2 compliance timelines beyond regulatory minimums. Deepen vertical integration into AI-embedded risk analytics development to capture premium pricing tiers as Basel III stress testing requirements intensify. Defensive moves must address TmaxSoft's core banking alternatives and foreign platform vendors seeking direct market entry through Busan's regulatory sandbox. For New Entrants and Emerging Players: Mid-tier regional banks in Daegu-Gyeongbuk and Gwangju-Honam represent the most penetrable entry point, with agricultural cooperative banks demanding cost-optimized SaaS solutions and lacking internal DevOps capacity. Busan's fintech hub offers regulatory sandbox access for ledger-agnostic payment processing architectures aligned with the Bank of Korea's CBDC pilot. Go-to-market positioning should emphasize usage-based billing models that convert capital expenditure to predictable operating costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed integration boutiques possessing Kubernetes orchestration expertise and Financial Services Commission compliance track records. Long-term viability hinges on cloud-native talent acquisition and API-first platform architectures across a five-to-ten year window. Acquisition targets should demonstrate production deployments at internet-only banks like KakaoBank or Toss Bank. The signal to watch is central bank digital currency integration mandates reshaping payment processing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Banking Migration | Financial Services Commission mandates compress vendor replacement cycles and elevate API-first procurement priorities. |
| AI-Embedded Risk Analytics Development | Basel III-aligned stress testing tools open premium pricing tiers for predictive credit scoring modules. |
| CBDC Integration Partnership | Bank of Korea pilot program creates white space for ledger-agnostic settlement architectures. |
| Regional Bank SaaS Expansion | Usage-based billing models align software costs with fluctuating transaction volumes in provincial markets. |
| Cybersecurity Certification Investment | MFDS guidelines and ISO 27001 requirements create compliance barriers protecting certified incumbents. |
Research Methodology
A standing panel of chief technology officers at major retail banks, IT procurement officers in Seoul's Yeouido district, cloud platform engineers, and regulatory compliance specialists provided ongoing calibration across the research process. Primary interviews combined with secondary validation from Financial Services Commission policy filings, Bank of Korea payment system disclosures, MFDS cybersecurity guidelines, and hyperscaler capex reports. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level estimates.
Scenario-bracketing framed analytical projections across the modeling period, with segmentation dimensions including deployment model, organization size tier, vertical specialization, and regional adoption pattern. CAGRs derived from historical procurement cycle analysis and regulatory deadline impact assessment. Forecast inputs incorporated open banking API mandate compliance timelines and cloud-first policy enforcement trajectories specific to Korean financial infrastructure.
Practitioners should monitor central bank digital currency pilot expansion, foreign vendor direct entry attempts, and chaebol-affiliated vendor merger activity for early signals of structural shift. Forecasts reflect assumptions regarding regulatory enforcement consistency and talent pipeline development. Material shifts in Financial Services Commission cloud mandate scope or US-Korea technology transfer restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Germany Factoring Services Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Global Automated Algo Trading Market
Financial Services
India Legal Services Market
Financial Services
Account Aggregators Market
Financial Services
Islamic Finance Market
Financial Services
Direct Selling Market
Financial Services
South Korea Factoring Services Market
Financial Services
Silver Economy Market
Financial Services
Hyperinflation System Market
Financial Services
Online Investment Platform Market
Financial Services
Currency Exchange Software Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Financial Advisory Services Market
Financial Services
Source to Pay Market
Financial Services
E-KYC Market